
 Hematuria Treatment Market | 2026-2036
Hematuria Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hematuria Treatment Market Foresight
Modular diagnostic bundles is decoupling hematuria workups from traditional hospital-based referral chains. Pfizer Inc. leverages its oncology portfolio to anchor physician education programs on hematuria-linked malignancy screening. Novartis AG competes through specialized immuno-oncology assets that address underlying cancer etiologies driving gross hematuria presentations. Johnson & Johnson sustains channel dominance via its cystoscopy and endourology device ecosystem deployed across ambulatory surgery centers.
Hematuria treatment encompasses pharmacologic interventions, minimally invasive surgical techniques, and advanced diagnostic modalities targeting visible or non-visible blood in urine, typically quantified by urine dipstick sensitivity thresholds of 1-3 erythrocytes per high-power field. The primary commercial purpose centers on etiologic identification—ranging from urinary tract infection to urothelial carcinoma—while mitigating progression to irreversible renal or bladder damage. Medications occupy the largest revenue pool given chronic management requirements for benign prostatic hyperplasia and anticoagulation-related bleeding, though Diagnostic Tests generate superior per-procedure margins through molecular cytology and fluorescence in situ hybridization panel adoption. Hospitals remain the dominant end-user channel for complex hematuria protocols requiring cystoscopic biopsy, while Home Healthcare segments are gaining traction through telemedicine-integrated urine monitoring devices that reduce repeat clinic visits.
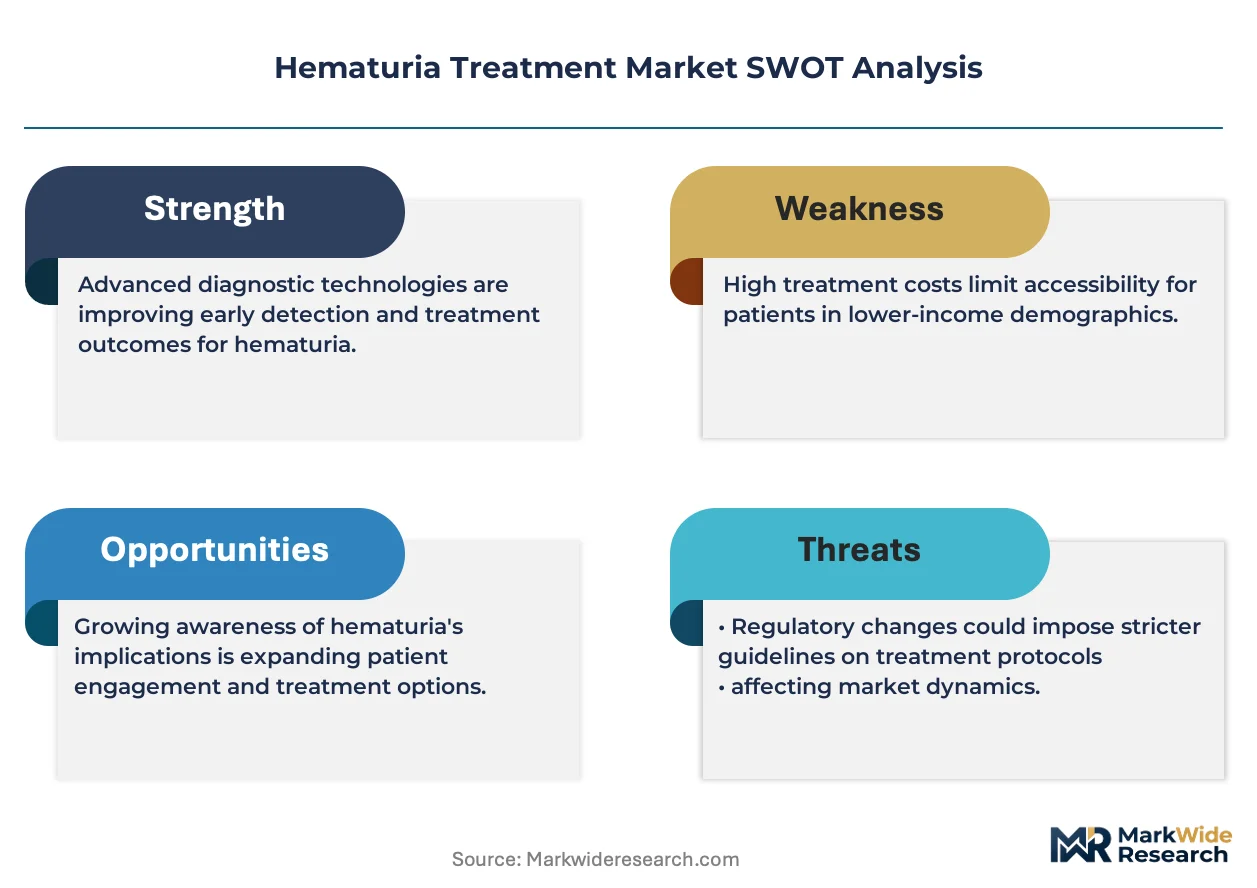
The FDA governs in vitro diagnostic platforms and cystoscopic devices through premarket notification and premarket approval pathways, while the Clinical Laboratory Improvement Amendments framework shapes laboratory-developed test accessibility for hematuria panels. ISO 13485 certification requirements and the EU Medical Device Regulation impose quality management burdens on manufacturers seeking transatlantic market presence. Stakeholders must monitor evolving reimbursement thresholds for ambulatory diagnostic bundles and position for value-based contracting as payors tighten authorization criteria for advanced urologic imaging.
Market Dynamics
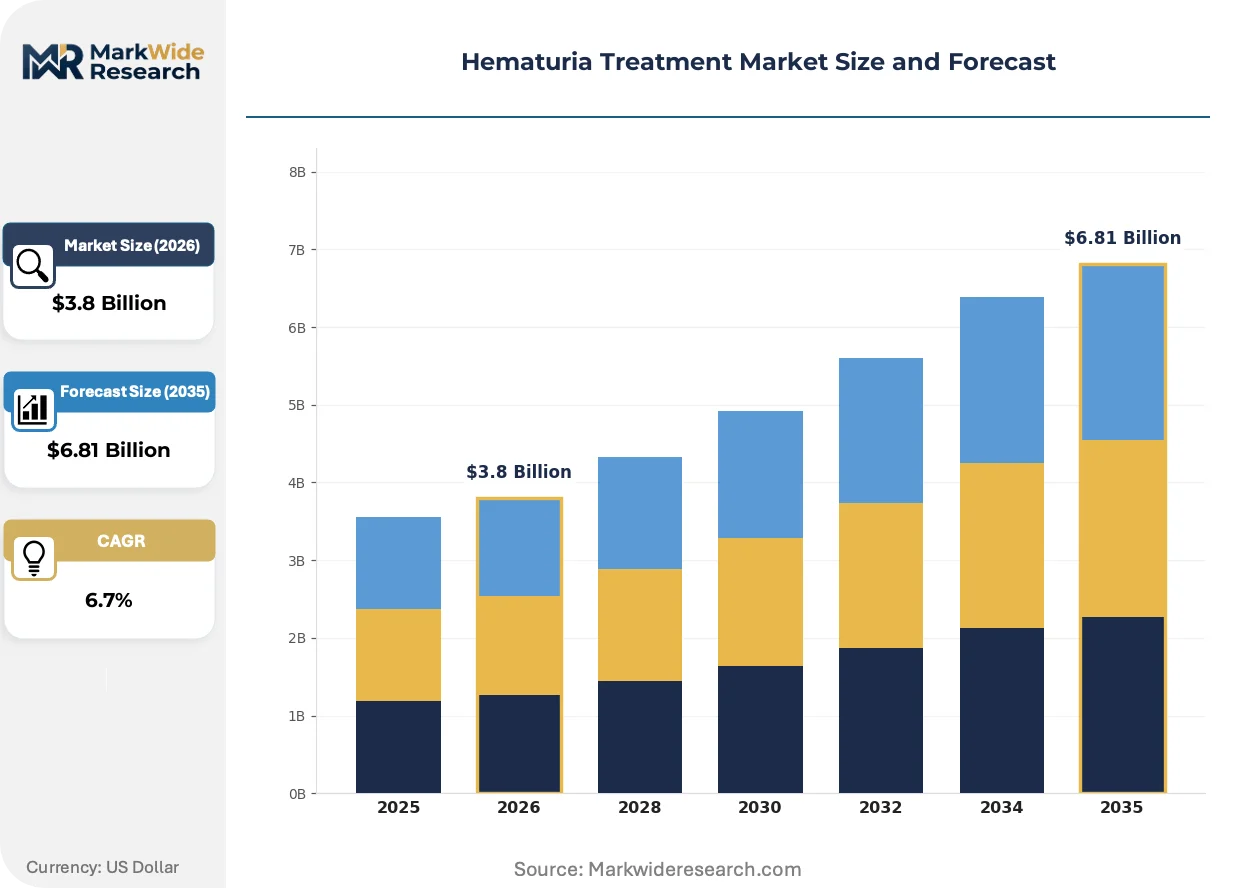
Ambulatory diagnostic bundles are fragmenting traditional hospital-centric hematuria workups as urology clinics build standalone molecular cytology capabilities and telemedicine-integrated monitoring reduces specialist referral dependency.
Growth Catalysts
- FDA Breakthrough Device Designation:Streamlined premarket pathways accelerate commercialization timelines for fluorescence in situ hybridization panels and AI-assisted cystoscopy systems.
- Ambulatory Surgery Centers:Medicare reimbursement parity for outpatient cystoscopic procedures shifts complex hematuria protocols away from inpatient settings.
- Integrated Delivery Networks:United States-based IDNs mandate early detection protocols for bladder malignancies, embedding hematuria screening into routine primary care workflows.
Market Restraints
- Reimbursement Compression:CMS prior authorization tightening for advanced urologic imaging creates payment friction for fluorescence-guided cystoscopy adoption.
- Laboratory Concentration:Molecular cytology testing capacity clusters in academic medical centers, limiting rural access to rapid hematuria panel turnaround.
- Anticoagulation Complexity:Direct oral anticoagulant use complicates gross hematuria etiology determination, delaying definitive urologic intervention.
Strategic Opportunities
- Home-Based Monitoring:Telemedicine-integrated urine dipstick devices with automated erythrocyte quantification open recurring revenue streams outside clinic walls.
- EU MDR Alignment:Harmonized quality management requirements under the Medical Device Regulation create transatlantic certification efficiencies for diagnostic platform manufacturers.
- Immuno-Oncology Convergence:PD-1/PD-L1 inhibitor expansion in non-muscle-invasive bladder cancer links hematuria resolution to therapy response monitoring.
Industry Challenges
- Pathologist Shortage:Specialized urologic pathology expertise scarcity delays molecular cytology interpretation and biopsy correlation.
- Legacy EHR Integration:Ambulatory diagnostic platforms face interoperability friction with hospital-centric electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hematuria Treatment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgical Procedures, Diagnostic Tests, Supportive Therapies End User: Hospitals, Clinics, Urgent Care Centers, Home Healthcare Application: Cancer Treatment, Kidney Disorders, Bladder Issues, Infection Management Delivery Mode: Oral, Intravenous, Topical, Inhalation |
| Companies Covered | Pfizer Inc., Novartis AG, Johnson & Johnson, Bristol Myers Squibb, AstraZeneca Plc, Janssen Pharmaceuticals Inc., Merck & Co., Inc., F. Hoffmann-La Roche Ltd., Vera Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hematuria Treatment Market Shifts & Advancements
Digital pathology and liquid biopsy platforms are compressing diagnostic timelines while regulatory sandboxes in major markets accelerate novel biomarker validation for hematuria-linked malignancy detection.
Multiplex molecular cytology panels integrating fluorescence in situ hybridization with next-generation sequencing biomarkers are unifying previously separate laboratory workflows. Academic medical centers in the United States are adopting these platforms within eighteen-month procurement cycles. The technology is unifying histopathology and genomic testing under single-specimen protocols, reducing patient visit burden and specialist handoff delays.
The EU Medical Device Regulation's enhanced clinical evidence requirements for Class III diagnostic devices are extending premarket timelines for novel cystoscopy systems. Manufacturers must now submit prospective performance data from European trial sites. German and French notified bodies are prioritizing review resources toward AI-assisted hematuria triage algorithms, creating competitive queue advantages for early filers.
Point-of-care urine analyzers with cloud-connected erythrocyte morphology classification are displacing centralized laboratory referrals for initial hematuria quantification. United States urology group practices are deploying these devices in satellite clinics to reduce specimen transport delays. Rural health systems in Texas and Florida report forty percent reduction in repeat patient visits through same-result consultation completion.
Hematuria Treatment Market Segmentation
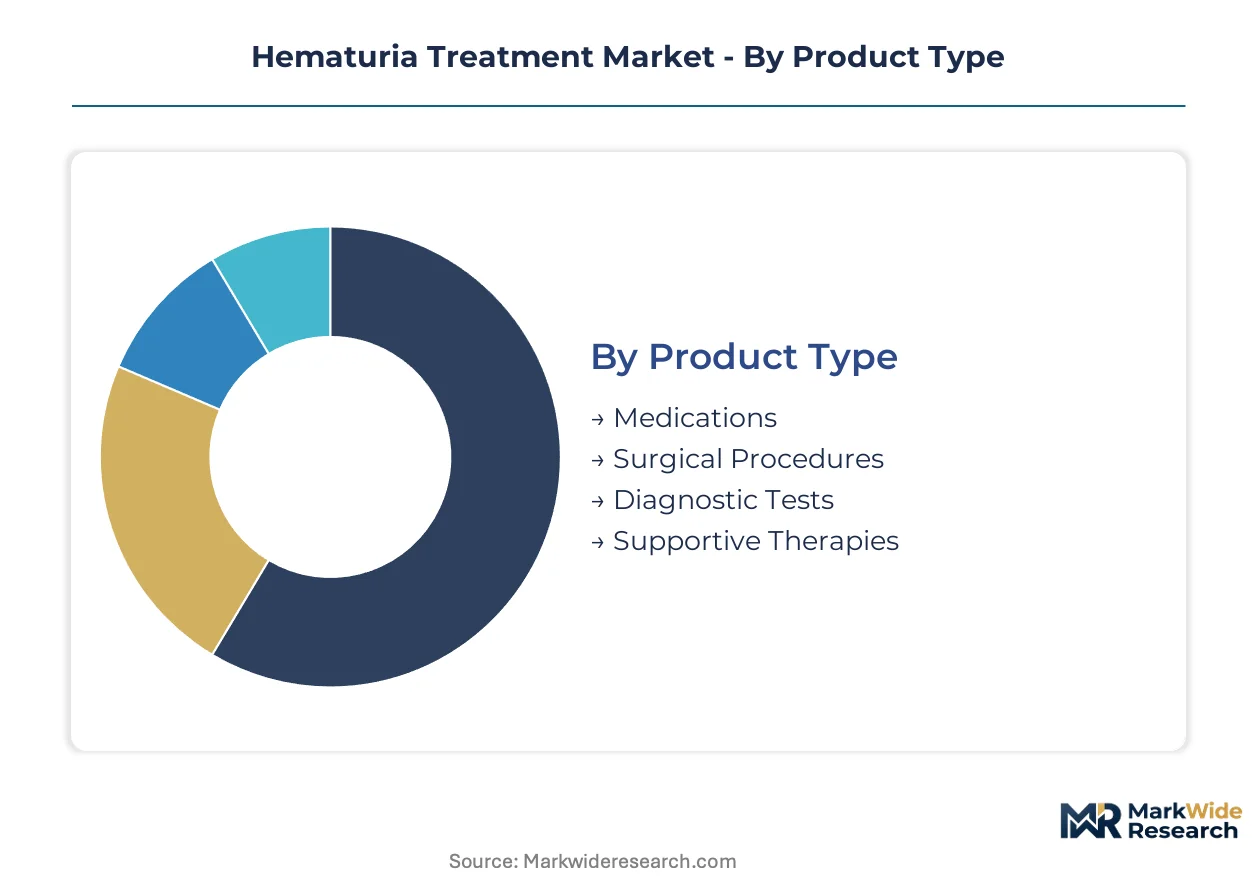
Hematuria treatment pathways fragment across four critical dimensions, each reshaping procurement patterns and clinical workflow design. Product type stratification reveals divergent margin profiles between chronic pharmaceutical management and high-value diagnostic interventions. End-user channel evolution is compressing traditional hospital dominance as ambulatory capabilities mature.
Product Type:
Replacement cycles vary sharply across this category, with diagnostic platforms refreshing every 3-5 years against decade-long horizons for surgical device ecosystems.
- Medications:Chronic oral therapies for benign prostatic hyperplasia and anticoagulation reversal dominate prescription volumes. United States integrated delivery networks prioritize formulary standardization for alpha-blockers and 5-alpha reductase inhibitors to reduce episode variability.
- Diagnostic Tests:Molecular cytology panels and fluorescence in situ hybridization assays command premium positioning through per-procedure margin superiority. Academic medical centers in the United States drive adoption of multiplex platforms unifying genomic and histopathologic analysis under single-specimen protocols.
- Surgical Procedures:Cystoscopic biopsy and transurethral resection protocols concentrate in hospital-based settings requiring anesthesia support.
- Supportive Therapies:Hydration management and pain control protocols supplement definitive interventions across all care settings.
Medications sit at the top of the volume ranking, with Diagnostic Tests climbing the fastest.
End User:
Channel cost tiers separate capital-intensive hospital infrastructure from lean ambulatory models reshaping access geography.
- Hospitals:Complex hematuria protocols requiring cystoscopic biopsy and anesthesia support anchor revenue concentration. United States facilities absorb prior authorization friction for fluorescence-guided imaging under CMS tightening.
- Clinics:Urology specialty practices deploy point-of-care urine analyzers with cloud-connected erythrocyte classification to compress diagnostic timelines. Texas and Florida rural health systems report substantial visit reduction through same-result consultation completion.
- Urgent Care Centers:Initial hematuria triage and referral coordination capture episodic presentations outside established patient relationships.
- Home Healthcare:Telemedicine-integrated urine monitoring devices with automated erythrocyte quantification extend surveillance beyond clinic walls.
Hospitals retain the highest absolute revenue share, though Home Healthcare is expanding most quickly.
Application:
Application-specific demand correlates directly with malignancy screening protocol intensity and chronic disease prevalence patterns.
- Cancer Treatment:Urothelial carcinoma workups drive highest-value diagnostic consumption through molecular cytology and fluorescence in situ hybridization panel adoption. United States IDN mandates embed hematuria screening into primary care workflows, accelerating referral volume.
- Bladder Issues:Interstitial cystitis and stone disease generate recurring procedural demand across ambulatory surgery centers. Medicare reimbursement parity for outpatient cystoscopic procedures shifts case volume away from inpatient settings.
- Kidney Disorders:Glomerular hematuria management concentrates in nephrology-nephrology integrated practices requiring specialized pathology interpretation.
- Infection Management:Urinary tract infection-related hematuria resolves primarily through antimicrobial therapy with limited diagnostic intensity.
Cancer Treatment commands the steepest expansion trajectory as early detection protocols proliferate.
Delivery Mode:
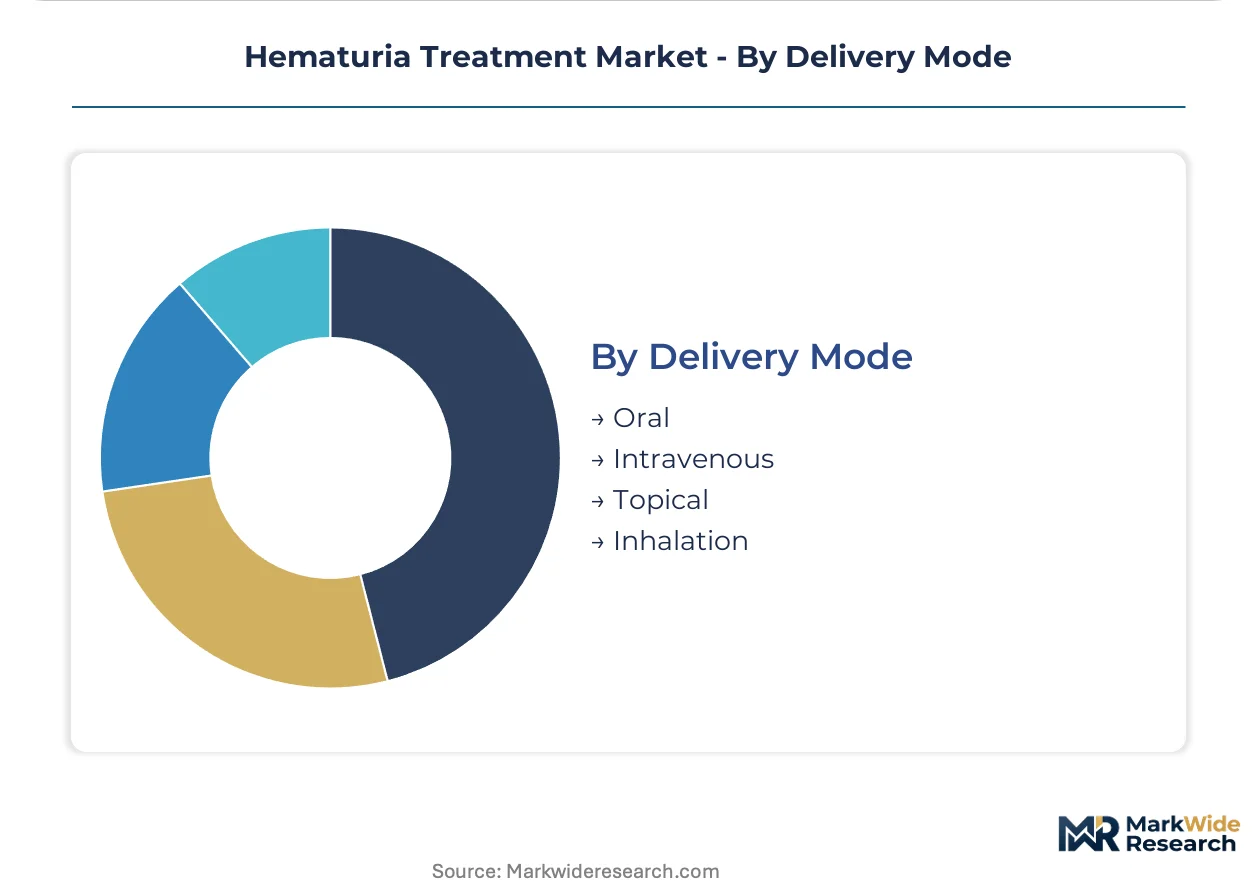
Route selection follows severity stratification and intervention invasiveness requirements across the care continuum.
- Oral:Alpha-blockers and anticoagulation reversal agents dominate chronic management with highest patient-administered volume. Formulary positioning in United States IDNs determines competitive access.
- Intravenous:Antibiotic administration and perioperative agents concentrate in hospital and ambulatory surgery center settings. Infusion infrastructure requirements limit channel flexibility.
- Topical:Intravesical therapies for non-muscle-invasive bladder cancer link hematuria resolution to PD-1/PD-L1 inhibitor response monitoring.
- Inhalation:Minimal role in hematuria-specific protocols, with occasional use for anesthesia delivery in surgical settings.
Oral delivery maintains volume leadership, while Intravenous routes gain share fastest through ambulatory surgery center expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hematuria diagnostics originated in academic medical centers across the United States and Germany during the 1980s fluorescence cytology revolution. These institutions established the clinical protocols and regulatory frameworks that now govern multinational market access.
United States
Integrated delivery networks in Texas and Florida drive point-of-care urine analyzer deployment to reduce rural patient visit burdens. The FDA's breakthrough device designation pathway accelerates commercialization timelines for AI-assisted cystoscopy systems. Houston and Miami health systems report substantial diagnostic compression through same-result consultation completion.
Germany
Notified bodies in Berlin and Munich prioritize review queues for AI-assisted hematuria triage algorithms under the EU Medical Device Regulation's enhanced clinical evidence requirements. Bavarian medical device clusters concentrate Class III diagnostic platform manufacturing. German urology practices adopt multiplex molecular cytology panels within compressed procurement cycles.
Japan
PMDA streamlined approval pathways for fluorescence in situ hybridization panels address aging-population bladder malignancy screening demand. Tokyo and Osaka academic medical centers anchor genomic-histopathology unified testing adoption. Japanese manufacturers leverage METI industrial policy support for diagnostic platform export certification.
United Kingdom
NHS England's early detection mandates for urothelial carcinoma embed hematuria screening into primary care workflows across London and the Southeast. The MHRA operates post-Brexit regulatory alignment with EU MDR quality management standards. Manchester and Birmingham urology networks build standalone molecular cytology capabilities outside hospital referral chains.
China
NMPA innovation pathways for in vitro diagnostic platforms accelerate domestic fluorescence cytology panel registration. Shanghai and Beijing medical device clusters concentrate cystoscopy system manufacturing for Asia-Pacific distribution. Chinese health systems deploy telemedicine-integrated urine monitoring to address specialist access gaps in provincial cities.
Hematuria Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across diagnostic test bundling and device ecosystem integration. The market structures around three tiers: pharmaceutical incumbents with oncology education programs, diversified device manufacturers with ambulatory surgery center channel dominance, and emerging biotech specialists with immuno-oncology assets. Consolidation pressure concentrates among diagnostic platform manufacturers seeking transatlantic certification efficiencies. Strategic partnerships between molecular cytology laboratories and telemedicine platforms represent the dominant competitive move alongside vertical integration into home-based monitoring devices.
Among pharmaceutical incumbents, Pfizer Inc. and Novartis AG exemplify contrasting archetypes—one leveraging broad oncology portfolio anchoring for physician education, the other competing through specialized immuno-oncology assets. Johnson & Johnson occupies a distinct position through cystoscopy and endourology device ecosystem deployment. These three represent the structural fault lines: pharmaceutical-led malignancy screening protocols versus device-led ambulatory procedure capture versus integrated diagnostic-therapeutic bundling.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Johnson & Johnson |
| Bristol Myers Squibb |
| AstraZeneca Plc |
| Janssen Pharmaceuticals Inc. |
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd. |
| Vera Therapeutics |
| Others |
Supply & Pricing Matrix
Fluorescent probe reagent costs flow from specialized chemical manufacturers through molecular cytology platform vendors into per-procedure pricing tiers at United States academic medical centers and German urology clinics. This input concentration upstream creates margin compression downstream as ambulatory diagnostic bundles force volume discounts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared fluorescence in situ hybridization panels from CE-marked alternatives and unvalidated laboratory-developed tests. Price differentiation hinges on regulatory certification tier and after-sales technical support intensity. Cost compression in the standard tier is intensifying because Medicare reimbursement parity for outpatient cystoscopy reduces hospital markup capture. Urgent care centers exhibit highest price sensitivity, while integrated delivery networks prioritize certification grade over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese optical component suppliers for cystoscopy system illumination modules. Manufacturing concentrates in Germany, the United States, and Japan for endoscopic device assembly. Raw material dependencies include rare-earth phosphors for fluorescence imaging, medical-grade stainless steel for biopsy forceps, and specialized polymers for disposable catheter channels. Tariff exposure on Chinese optical inputs threatens margin stability at Bavarian and Texan device assembly plants. Distribution runs through manufacturer-direct sales teams to hospital purchasing committees and group purchasing organization contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hematuria diagnostics represents a late-cycle quality story as United States integrated delivery networks mandate early detection protocols that privilege FDA breakthrough-designated platforms over commodity alternatives.
For Market Incumbents: To counter ambulatory surgery center channel fragmentation, Johnson & Johnson and Pfizer Inc. should deepen backward integration into fluorescence probe chemistry to capture reagent margin pools. Device ecosystem players must anchor hospital system partnerships through bundled cystoscopy-maintenance contracts that lock out molecular cytology disruptors.
For New Entrants and Emerging Players: Telemedicine platforms offer the most penetrable channel for home-based urine monitoring devices with automated erythrocyte quantification. White-space targets include rural Texas and Florida health systems seeking forty-percent visit reduction through same-result consultation completion. Go-to-market execution should prioritize cloud-connected point-of-care analyzer deployment via urology group practice management companies.
For Investors and Strategic Acquirers: Roll-up economics work for molecular cytology laboratory networks because EU MDR harmonization creates transatlantic certification efficiencies for consolidated diagnostic platforms. Long-term viability centers on capturing recurring revenue streams from multiplex panel adoption in non-muscle-invasive bladder cancer surveillance. The inflection signal to watch is CMS prior authorization relaxation for fluorescence-guided cystoscopy reimbursement.
| Strategic Initiative | Industry Significance |
|---|---|
| Breakthrough Device Designation Pathway | FDA streamlined review accelerates AI-assisted cystoscopy commercialization timelines for Houston health systems. |
| Hospital System Partnership | Integrated delivery network contracts embed hematuria screening into primary care workflows across Texas and Florida. |
| Software Companion Development | Telemedicine-integrated urine monitoring platforms extend surveillance beyond clinic walls for rural patient populations. |
| CE Marking Pathway | EU MDR alignment creates certification efficiencies for German and French diagnostic platform manufacturers. |
| Reimbursement Strategy | Medicare parity for outpatient cystoscopic procedures shifts case volume toward ambulatory surgery centers. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with urology practice administrators, hospital purchasing committee members, biomedical engineers, and GPO contracts managers alongside secondary validation. FDA 510(k) filings, EMA medical device registration databases, CMS Medicare reimbursement schedules, and hospital procurement contract repositories anchor quantitative triangulation. Bottom-up procedure volume estimates and top-down market sizing reconstructions were cross-checked for convergence.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. Segmentation dimensions modeled include product type, end-user channel, application severity, and delivery mode, with regional regulatory cluster as an additional cross-cutting variable. CAGRs were derived from fitted growth curves applied to base-year estimates, incorporating bladder malignancy incidence trajectories and ambulatory surgery center expansion rates as hematuria-specific inputs.
Revisions become necessary when CMS prior authorization criteria tighten, EU MDR notified body review queues lengthen, or fluorescence probe supply disruptions materialize. Forecasts reflect documented assumptions about reimbursement stability and regulatory pathway continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
North America Bladder Disorders Market
Urology
Varicocele Treatment Market
Urology
Pyelonephritis Treatment Market
Urology
Urology Ultrasound Market
Urology
US Urology Devices Market
Urology
North America Transrectal Ultrasound Market
Urology
Uropathy Treatment Market
Urology
Urology Lasers Market
Urology
Urinary Incontinence Treatment Drugs Market
Urology
Botulinum Toxin in Urology Market
Urology
Uraemia Treatment Market
Urology
Urethral Stricture Market
Urology
Ureter Cancer Treatment Market
Urology
Self-Intermittent Catheters Market
Urology
Urology Forceps Market
Urology
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market