
 Botulinum Toxin in Urology Market | 2026-2036
Botulinum Toxin in Urology Market Size, Share, and Industry Trends Forecast 2026-2036
Botulinum Toxin in Urology Market Analytics
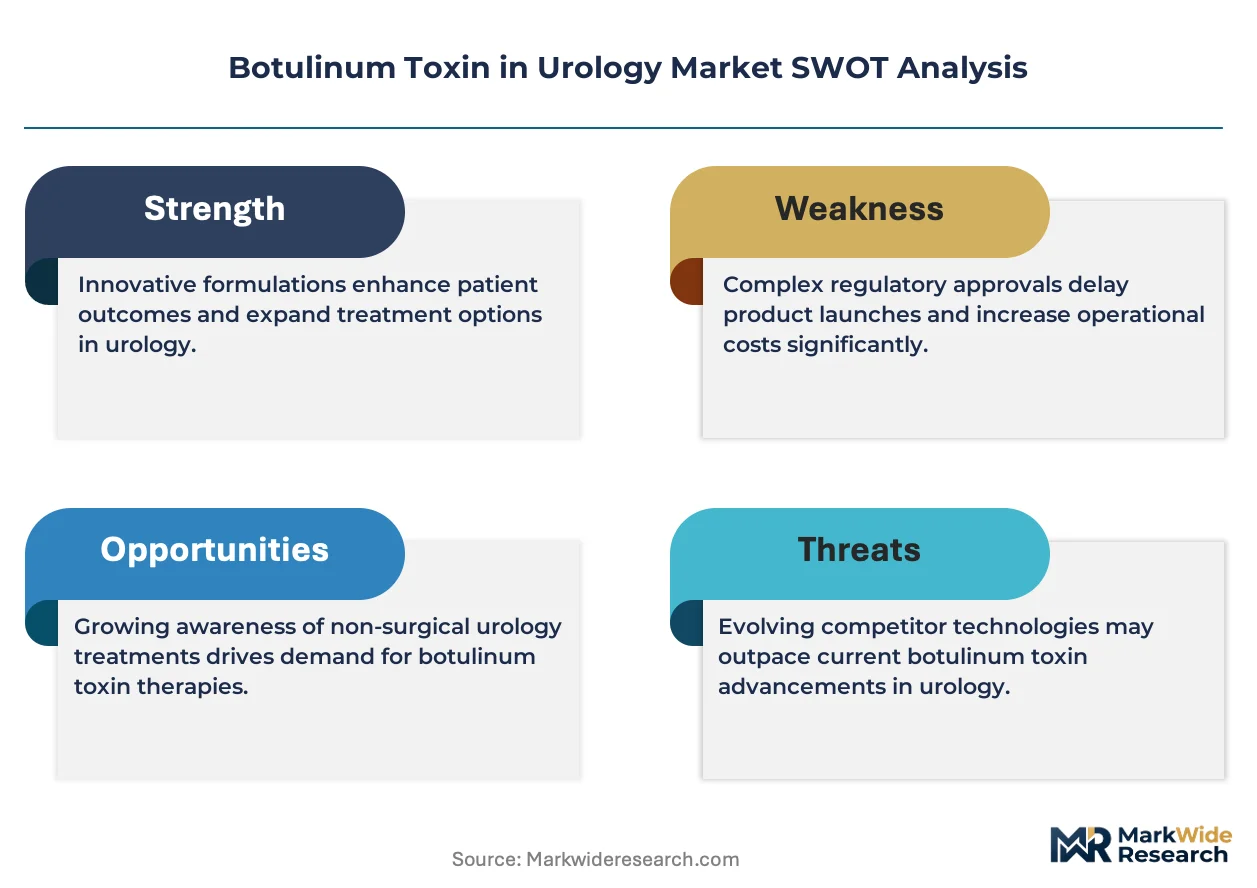
CE marking under the EU Medical Device Regulation is unwinding competitive access for botulinum toxin suppliers seeking European urology placement. AbbVie leverages its established neurology-to-urology prescriber relationships to sustain institutional loyalty. Ipsen Pharma anchors its position through specialized urology sales forces in Western Europe. Merz Pharma competes via differentiated toxin purity profiles that appeal to academic medical centers.
Botulinum toxin in urology denotes purified neurotoxin formulations administered via cystoscopic intradetrusor injection to inhibit acetylcholine release from presynaptic nerve terminals, thereby reducing detrusor muscle overactivity in conditions such as neurogenic bladder and overactive bladder refractory to antimuscarinic therapy. The application segment shows overactive bladder commanding the largest volume pool while neurogenic detrusor overactivity generates premium pricing due to complex reimbursement pathways. Among product types, Botox occupies the dominant share through first-mover urology indications, whereas Xeomin differentiates via absence of complexing proteins that may reduce immunogenicity risk in repeat-injection patients.
FDA oversight of biologic potency testing and EMA pharmacovigilance requirements for neurotoxin spread shape both product development costs and prescriber training mandates. The EU AI Act and GDPR frameworks increasingly govern digital patient-reported outcome tools used in post-market urology studies, adding compliance layers for device-drug combination tracking systems. Stakeholders must monitor evolving payer evidence requirements for sustained reimbursement across public and private channels.
Market Dynamics
Intravesical botulinum toxin administration is displacing chronic antimuscarinic pharmacotherapy as first-line intervention for refractory overactive bladder, compressing the addressable patient pool for oral agents while expanding cystoscopic procedure volumes across ambulatory surgery centers.
Growth Catalysts
- EMA MDR compliance deadlines:Accelerated CE marking renewals under the EU Medical Device Regulation are forcing suppliers to consolidate quality documentation, advantaging established toxin manufacturers with dedicated regulatory affairs infrastructure.
- Neurogenic bladder pathway expansion:Spinal cord injury and multiple sclerosis patient cohorts in Germany and Japan are accessing earlier intervention thresholds through revised national reimbursement catalogs.
- Ultrasound-guided injection protocols:Cystoscopic navigation assistance technologies are shortening procedure times and reducing post-injection urinary retention rates in high-volume urology clinics.
Market Restraints
- Clostridium botulinum fermentation capacity concentration:Bulk toxin production clusters in Swiss and Irish biomanufacturing facilities create geographic supply vulnerability to single-site contamination events.
- FDA potency testing variability:Mouse bioassay reference standard inconsistencies between lots extend release timelines and inflate working capital requirements for finished goods inventory.
- Sacral neuromodulation substitution:InterStim and comparable tibial nerve stimulation devices are capturing antimuscarinic-failure patients who might otherwise progress to intradetrusor toxin therapy.
Strategic Opportunities
- India urology infrastructure buildout:Greenfield specialty hospital chains in Mumbai and Bangalore are establishing dedicated neurourology units without legacy antimuscarinic prescribing patterns to displace.
- Pediatric neurogenic detrusor overactivity:EMA pediatric investigation plan commitments and FDA pediatric exclusivity incentives are opening regulatory pathways for age-indication expansion below 18 years.
- Digital patient-reported outcome integration:GDPR-compliant bladder diary applications linked to electronic health records are enabling real-world evidence generation for payer contract negotiations.
Industry Challenges
- Cystoscopic technique standardization gaps:Variable injection depth and mapping protocols across training institutions produce heterogeneous efficacy outcomes that complicate meta-analytic evidence synthesis.
- Antibody-mediated non-response management:Neutralizing antibody testing infrastructure remains fragmented, leaving clinicians without clear retreatment guidance for secondary non-responders.
- Cold chain integrity at ambulatory sites:Office-based procedure migration strains toxin vial storage compliance compared to hospital pharmacy-controlled environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botulinum Toxin in Urology Market |
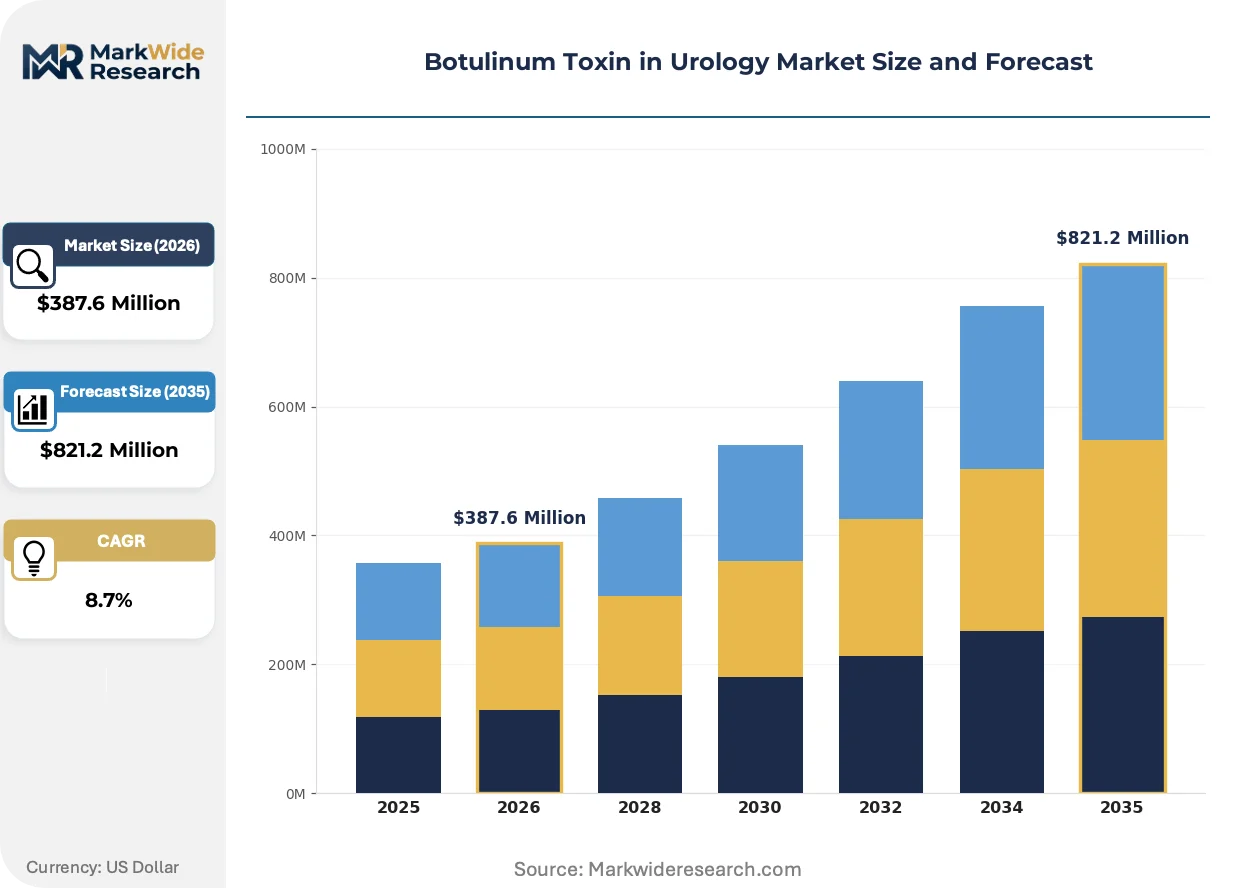
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Botox, Dysport, Xeomin, Jeuveau Application: Overactive Bladder, Chronic Prostatitis, Bladder Pain Syndrome, Neurogenic Detrusor Overactivity End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions Delivery Mode: Intradermal, Intramuscular, Subcutaneous, Local Anesthesia |
| Companies Covered | Medytox, Daewoong Pharmaceutical, AbbVie, Revance Therapeutics, Galderma, Ipsen Pharma, Hugel, Evolus, Merz Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botulinum Toxin in Urology Market Evolving Landscape
Recombinant toxin engineering and precision delivery instrumentation are converging to reshape therapeutic indices and expand addressable patient severity thresholds beyond current antimuscarinic-refractory definitions.
Needle-free intravesical instillation technologies utilizing permeation-enhanced formulations are displacing standard cystoscopic injection protocols in early-phase clinical development. Academic medical centers in the Netherlands and Sweden are piloting these catheter-based delivery systems for patients with anesthesia contraindications. The displacement of operative suite requirements toward outpatient catheterization clinics is compressing per-procedure facility fees and expanding rural access.
The EU AI Act risk classification framework for clinical decision support tools is mandating conformity assessment updates for urodynamic interpretation software integrated with toxin candidacy scoring. Manufacturers embedding machine learning into injection planning applications must now maintain technical documentation and human oversight protocols comparable to Class IIa medical devices. German notified bodies are experiencing backlog-induced delays that extend time-to-market for AI-augmented cystoscopy platforms by 8-14 months.
Hospital formulary committees are consolidating purchasing authority for biologic urology therapeutics into centralized pharmacy and therapeutics committees, displacing individual physician preference patterns. United States academic medical centers and integrated delivery networks are negotiating multi-year sole-source agreements that bundle toxin supply with cystoscopy service contracts. This concentration is most visible in the Northeast and Pacific Northwest, where health system mergers have created single-committee control over 60-80 cystoscopy suites.
Botulinum Toxin in Urology Market Segmentation
Botulinum toxin in urology segments along four functional dimensions: molecular formulation, clinical indication, care setting, and administration technique. Each axis carries distinct regulatory, reimbursement, and operational implications that shape supplier strategy and prescriber access patterns.
Product Type:
EMA pharmacovigilance requirements and FDA potency testing protocols create divergent compliance burdens across toxin formulations, advantaging manufacturers with dedicated regulatory infrastructure.
- Botox:The onabotulinumtoxinA formulation pioneered urology indications through cystoscopic intradetrusor injection protocols. Demand concentrates in United States academic medical centers where first-mover familiarity and established reimbursement codes sustain institutional loyalty despite premium positioning.
- Xeomin:IncobotulinumtoxinA distinguishes itself through absence of complexing proteins, potentially reducing immunogenicity risk in repeat-injection patients. German and Swiss neurourology clinics are adopting this formulation for spinal cord injury cohorts requiring sustained retreatment cycles.
- Dysport:AbobotulinumtoxinA offers unit-conversion dosing flexibility that appeals to high-volume ambulatory surgery centers managing mixed therapeutic portfolios.
- Jeuveau:PrabotulinumtoxinA enters urology through aesthetic-to-therapeutic prescriber migration, though urology-specific indication expansion remains pending in major markets.
Botox handles the majority of throughput; Xeomin is expanding most quickly on share among repeat-injection populations.
Application:
Reimbursement pathway complexity stratifies commercial attractiveness across urological conditions, with neurogenic indications commanding premium pricing despite smaller addressable volumes.
- Overactive Bladder:Antimuscarinic-refractory patients represent the largest procedural volume pool, with cystoscopic injection displacing chronic oral pharmacotherapy across United States ambulatory surgery centers and Japanese specialty clinics.
- Neurogenic Detrusor Overactivity:Spinal cord injury and multiple sclerosis populations generate premium pricing through complex prior authorization requirements. Germany's revised national reimbursement catalog and Japan's medical device reimbursement framework are expanding early intervention thresholds.
- Chronic Prostatitis:Pelvic floor injection protocols are gaining traction in academic urology departments exploring off-label applications.
- Bladder Pain Syndrome:Interstitial cystitis subpopulations represent emerging investigational use, with European urodynamics centers piloting trigone-sparing injection mapping.
Overactive Bladder dominates procedure volumes; Neurogenic Detrusor Overactivity delivers the steepest expansion trajectory through expanded reimbursement access.
End User:
Facility fee structures and cold chain capabilities are redistributing procedure volumes from inpatient settings toward outpatient environments with specialized urology infrastructure.
- Hospitals:Academic medical centers anchor complex neurogenic bladder cases requiring multidisciplinary coordination with rehabilitation medicine and neurourology services.
- Clinics:Dedicated urology practices in the United States Northeast and Pacific Northwest are consolidating cystoscopy capacity through health system mergers.
- Ambulatory Surgical Centers:Office-based procedure migration strains toxin vial storage compliance compared to hospital pharmacy-controlled environments, creating quality assurance gaps.
- Research Institutions:Netherlands and Sweden academic centers are piloting needle-free intravesical instillation technologies for anesthesia-contraindicated patients.
Hospitals retain the most complex cases; Ambulatory Surgical Centers are gaining share fastest through compressed per-procedure economics.
Delivery Mode:
Technique standardization gaps across training institutions produce heterogeneous efficacy outcomes that complicate meta-analytic evidence synthesis for payer negotiations.
- Intradermal:Periurethral injection protocols target sphincter dysfunction in select neurogenic bladder presentations.
- Intramuscular:Detrusor wall injection remains the standard of care for overactive bladder, with ultrasound-guided navigation shortening procedure times in high-volume German clinics.
- Subcutaneous:Limited urology applications persist in pelvic floor dysfunction investigations.
- Local Anesthesia:Office-based protocols are expanding patient access while reducing facility fee burdens compared to general anesthesia requirements.
Intramuscular delivery handles the majority of procedures; Local Anesthesia protocols are climbing the fastest as ambulatory migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and specialty urology clinics concentrate purchasing authority across four core markets. FDA, EMA, and PMDA frameworks shape reimbursement pathways and prescriber training mandates. Switzerland and Ireland anchor bulk toxin fermentation capacity.
United States
Ambulatory surgery centers in the Northeast and Pacific Northwest are consolidating cystoscopy capacity through health system mergers. FDA potency testing protocols and biologic licensing requirements govern product release timelines. Boston and Seattle academic medical centers anchor complex neurogenic bladder cases requiring multidisciplinary coordination.
Germany
Revised national reimbursement catalogs are expanding early intervention thresholds for spinal cord injury cohorts. EMA MDR compliance deadlines and CE marking renewals under the EU Medical Device Regulation force quality documentation consolidation. Munich and Heidelberg neurourology clinics are adopting incobotulinumtoxinA formulations for sustained retreatment cycles.
Japan
Specialty urology clinics in Tokyo and Osaka are driving procedural volume expansion for antimuscarinic-refractory patients. PMDA oversight of medical device reimbursement frameworks shapes market access timelines. The country's aging demographic is compressing intervention thresholds for overactive bladder management.
Switzerland
Swissmedic pharmacovigilance requirements for neurotoxin spread influence prescriber training mandates across European markets. Basel and Zurich anchor bulk Clostridium botulinum fermentation capacity for global toxin supply. The country's biomanufacturing infrastructure creates geographic concentration vulnerability to single-site contamination events.
India
Greenfield specialty hospital chains in Mumbai and Bangalore are establishing dedicated neurourology units without legacy prescribing patterns to displace. CDSCO oversight of biologic imports shapes market entry pathways for established toxin manufacturers. These clusters represent first-mover advantage for suppliers building institutional relationships ahead of reimbursement maturation.
Botulinum Toxin in Urology Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with established neurology-to-urology prescriber relationships. The market exhibits consolidated characteristics at the formulation level, with three toxin variants commanding procedural volume. Strategic archetypes include first-mover incumbents leveraging institutional familiarity, pure-play toxin specialists emphasizing purity differentiation, and Korean biopharma challengers expanding therapeutic indication portfolios. Dominant competitive moves center on M&A for regulatory infrastructure acquisition and strategic partnerships for cystoscopy service bundling.
Among diversified pharmaceutical conglomerates, AbbVie and Ipsen Pharma occupy positions anchored by established urology sales forces and prescriber loyalty programs. Merz Pharma exemplifies the purity-differentiation archetype through academic medical center targeting. Korean biopharma challengers Medytox and Hugel represent emerging competitive pressure through cost-efficient manufacturing scale and Asia-Pacific market expansion.
| Leading Market Players |
|---|
| Medytox |
| Daewoong Pharmaceutical |
| AbbVie |
| Revance Therapeutics |
| Galderma |
| Ipsen Pharma |
| Hugel |
| Evolus |
| Merz Pharma |
| Others |
Value Network & Pricing Analysis
Fermentation capacity utilization above 85% at Swiss and Irish bulk toxin facilities anchors supply-side pricing power for finished neurotoxin formulations. This concentration creates asymmetric cost pass-through dynamics where contract manufacturers absorb input volatility while brand suppliers maintain premium positioning through prescriber loyalty programs and formulary lock-in arrangements.
Pricing Analysis
Cost-plus contracts with quarterly API indexation dominate procurement between bulk toxin suppliers and finished goods manufacturers. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA biologic license tier and EMA MDR certification completeness. Pricing pressure stems from sacral neuromodulation device substitution in antimuscarinic-refractory cohorts. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers show lowest due to bundled service contracting.
Supply Chain Analysis
Swissmedic oversight of Basel-area Clostridium botulinum fermentation creates single-source vulnerability for global toxin supply. Bulk production draws from Swiss, Irish, and South Korean biomanufacturing clusters. Raw material dependencies include proprietary bacterial strains, specialized growth media, and GMP-grade filtration membranes. Regulatory restriction risk concentrates in EMA MDR transition deadlines. Distribution runs through cold-chain logistics partners serving hospital pharmacy and ambulatory surgery center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital patient-reported outcome platforms are reconfiguring this market toward ecosystem economics where toxin efficacy data interoperability determines formulary positioning. Stakeholders must architect data-sharing protocols that satisfy GDPR and FDA software-as-medical-device frameworks.
For Market Incumbents: Consolidate cystoscopy service bundling through multi-year sole-source agreements with merged health systems in the Northeast and Pacific Northwest. Deepen backward integration into fermentation capacity to neutralize Swiss-Irish supply concentration risk. Prioritize EMA MDR technical documentation renewal ahead of notified body backlog delays.
For New Entrants and Emerging Players: Lead with needle-free intravesical instillation technologies targeting anesthesia-contraindicated patients in Netherlands and Sweden academic centers. Penetrate India's greenfield neurourology units before reimbursement maturation cements incumbent relationships. Position through catheter-based delivery system partnerships rather than toxin formulation competition.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pure-play toxin specialists with dedicated urology sales forces and pediatric investigation plan commitments. Five-to-ten year viability favors manufacturers with EMA pediatric exclusivity incentives and FDA biologic potency testing infrastructure. Watch EMA notified body backlog resolution as inflection indicator for AI-augmented cystoscopy platform time-to-market.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Investigation Plan Commitment | EMA pediatric exclusivity incentives open regulatory pathways below 18 years. |
| AI-Augmented Cystoscopy Platform Development | EU AI Act Class IIa conformity assessment mandates technical documentation overhaul. |
| Needle-Free Instillation Technology Pilot | Netherlands and Sweden academic centers validate catheter-based delivery for contraindicated patients. |
| Health System Merger Service Bundling | Northeast and Pacific Northwest integrated delivery networks consolidate 60-80 cystoscopy suites. |
| GDPR-Compliant Outcome Data Integration | Bladder diary applications linked to electronic health records enable real-world evidence generation. |
Research Methodology
Desk research of FDA biologic license applications, EMA MDR technical documentation filings, and national reimbursement catalog revisions preceded structured interviews with neurourology clinicians, hospital pharmacy directors, ambulatory surgery center administrators, and regulatory affairs specialists at toxin manufacturers. Secondary validation drew from ClinicalTrials.gov entries, CMS Medicare procedure databases, and GPO contract disclosure records. Bottom-up procedure volume estimates triangulated against top-down market value reconstructions.
Variance decomposition across molecular formulation, clinical indication, care setting, and administration technique dimensions shaped the analytical framework over the projection horizon. CAGRs derived from logistic diffusion modeling of antimuscarinic-to-toxin substitution rates and reimbursement threshold expansion timelines. Industry-specific inputs included cystoscopic procedure migration rates toward ambulatory settings and EMA notified body capacity constraints.
Underlying assumptions cover sustained FDA potency testing protocol stability and EMA MDR transition completion, with deviation risk concentrated in single-site fermentation contamination events and sacral neuromodulation device efficacy improvements. Practitioners should keep alternative scenarios live as EU AI Act enforcement patterns and pediatric indication expansion timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Urinary Incontinence Therapeutics Market
Urology
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market
Urology
Prostate Cancer Treatment Market
Urology
Catheter-Associated Urinary Tract Infections Treatment Market
Urology
Primary Aldosteronism Market
Urology
Penile Cancer Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Prostatic Arterial Embolization (PAE) Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Urinary Catheters Market
Urology
Urinary Incontinence Treatment Drugs Market
Urology
Acute Pyelonephritis Treatment Market
Urology
Urology Devices Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
Middle East and Africa Bladder Disorders Market
Urology
Nocturia Market