
 Urology Robotic Surgery Market | 2026-2036
Urology Robotic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Urology Robotic Surgery Market Intelligence
North American surgical robot manufacturers is rebalancing production capacity toward modular platform architectures that support multiple urology procedures. Intuitive Surgical leverages its installed base of da Vinci systems to sustain recurring instrument revenue streams. Stryker competes through its Mako platform extensions into soft-tissue applications. Medtronic anchors its position via the Hugo RAS system, which navigates hospital procurement committees with open console designs.
Urology robotic surgery encompasses computer-assisted electromechanical platforms that translate surgeon hand movements into filtered, scaled instrument motions inside the patient body, typically operating at 7-10 millimeter incision widths with tremor reduction below 0.2 millimeters. These systems serve the primary commercial purpose of enabling minimally invasive prostatectomy, nephrectomy, and cystectomy with reduced blood loss and shorter recovery trajectories. Robotic systems capture the dominant share of capital expenditure within product type segmentation, while surgical instruments generate the recurring revenue margin pool through per-procedure disposable attachments. Among applications, prostatectomy leads in procedure volume as screening protocols expand eligible patient cohorts, whereas cystectomy represents the fastest-growing segment as enhanced visualization improves nerve-sparing outcomes in bladder cancer cases.
FDA 510(k) clearance pathways and EU MDR Class IIb certification requirements shape product development timelines and commercial launch sequencing for urology robotic platforms. The EPA and OSHA frameworks additionally govern sterilization protocols and operating room occupational exposure limits that influence system design specifications. Stakeholders must monitor how reimbursement parity between robotic and laparoscopic procedures evolves under CMS and national health authority schedules, as payment differentials will determine hospital capital commitment velocity regardless of technical performance gains.
Market Dynamics
Hospital procurement committees now prioritize modular robotic architectures that accommodate multiple urology procedures within single capital investments, compressing vendor selection cycles and favoring platforms with open console designs over proprietary closed systems.
Growth Catalysts
- CMS reimbursement parity:Medicare payment schedules now align robotic prostatectomy rates with laparoscopic equivalents, removing financial disincentives for hospital capital commitment.
- Japan's aging surgical workforce:Demographic contraction among practicing urologists accelerates adoption of tremor-filtering platforms to extend operative careers.
- Enhanced nerve-sparing visualization:4K fluorescence imaging integration improves bladder cancer outcomes, expanding cystectomy eligibility criteria.
Market Restraints
- Capital intensity:Single-platform acquisition costs exceed $2 million per unit, excluding annual service contracts and per-procedure instrument disposables.
- Supply concentration:Precision harmonic scalpel manufacturing concentrates in German and Japanese component suppliers, creating single-source vulnerability.
- EU MDR Class IIb timelines:Extended conformity assessment periods delay commercial launches by 18-24 months versus prior CE marking pathways.
Strategic Opportunities
- India's tier-2 hospital expansion:Government PLI scheme subsidies for medical device manufacturing reduce import duties on robotic platforms.
- Same-day discharge protocols:Ambulatory surgery centers represent untapped installation sites as enhanced recovery pathways shorten length-of-stay below 24 hours.
- AI-powered preoperative planning:Machine learning segmentation of MRI datasets converges with haptic feedback training modules to reduce learning curves.
Industry Challenges
- Surgeon credentialing bottlenecks:Proctoring requirements and case volume thresholds delay independent practice authorization by 6-12 months post-training.
- Interoperability gaps:Legacy hospital information systems require custom API development to integrate robotic logging data with electronic health records.
- Sterilization protocol complexity:Reusable instrument reprocessing demands dedicated CSSD infrastructure that many facilities lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urology Robotic Surgery Market |
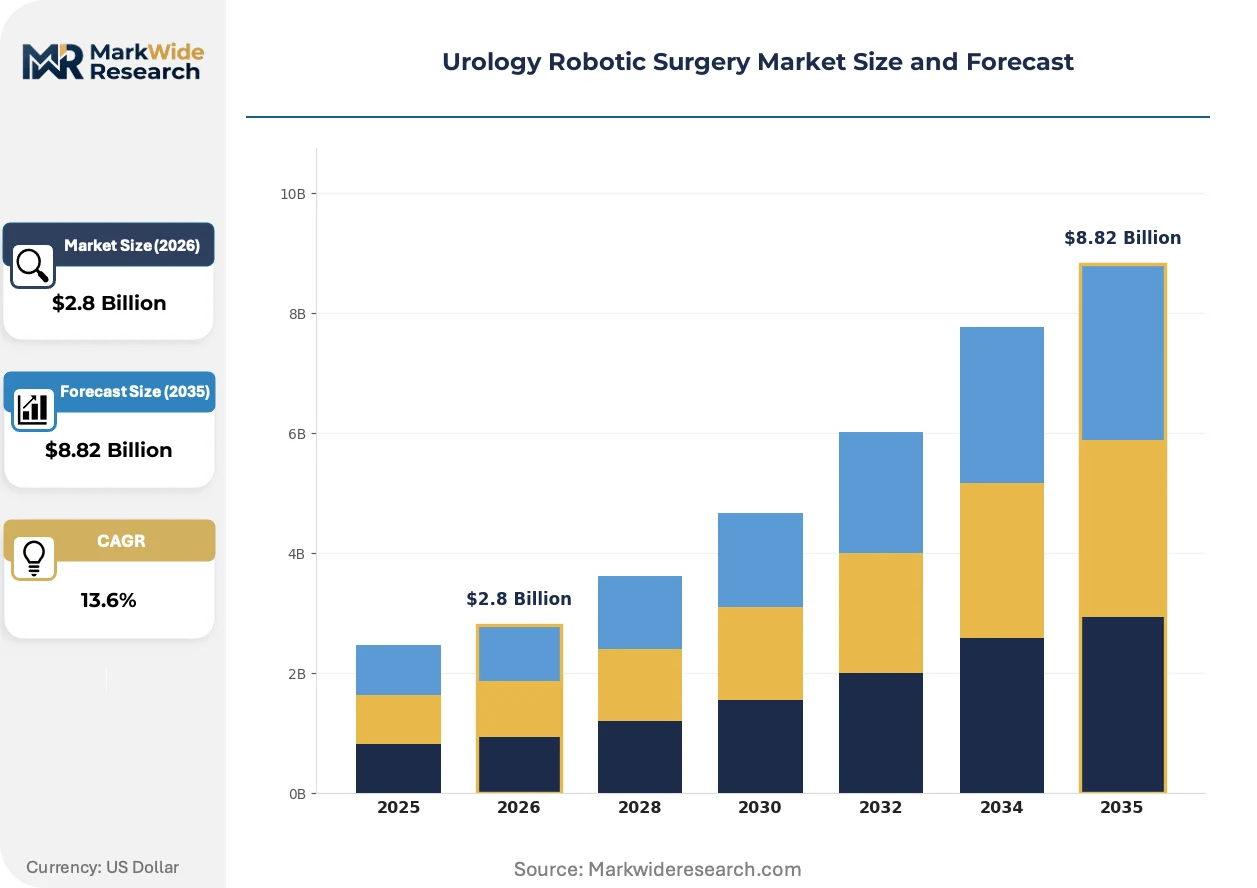
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Systems, Surgical Instruments, Accessories, Software Application: Prostatectomy, Nephrectomy, Cystectomy, Ureterectomy End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Research Institutions Technology: Computer-Assisted, Image-Guided, Minimally Invasive, Dual Console |
| Companies Covered | Intuitive Surgical, Stryker, Medtronic, THINK Surgical, Renishaw plc, Titan Medical, Asensus Surgical US, AVRA Medical Robotics, Surgical Science Sweden AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urology Robotic Surgery Market Strategic Shifts & Innovations
Digital surgery ecosystems are converging around real-time intraoperative analytics, with platform vendors embedding computer vision and machine learning directly into console interfaces to augment surgeon decision-making rather than merely replicate manual dexterity.
Autonomous suturing algorithms are automating anastomotic closure during radical prostatectomy, reducing operative time variability between high- and low-volume surgeons. Academic medical centers in Germany and the United States pilot these modules through FDA investigational device exemptions. The technology is automating skill transfer from experienced practitioners to training residents, compressing the traditional learning curve by standardizing critical technical steps.
EU MDR Article 10 post-market surveillance requirements now mandate systematic collection of real-world performance data across all implanted and reusable surgical instruments. Manufacturers must maintain electronic systems for trend analysis and incident reporting that interface with national competent authorities. Urology robotic platforms fall under intensified scrutiny given their Class IIb designation, with notified bodies demanding clinical follow-up protocols that extend 5-10 years post-procedure.
Hospital buying committees increasingly unbundle after-sales service contracts from initial capital purchases, negotiating multi-vendor maintenance agreements through third-party clinical engineering firms. This fragmentation shifts risk retention toward independent service organizations and away from original equipment manufacturers. The pattern is most pronounced in United States metropolitan hospital networks where consolidated procurement groups represent 15-20 affiliated facilities simultaneously.
Urology Robotic Surgery Market Segmentation
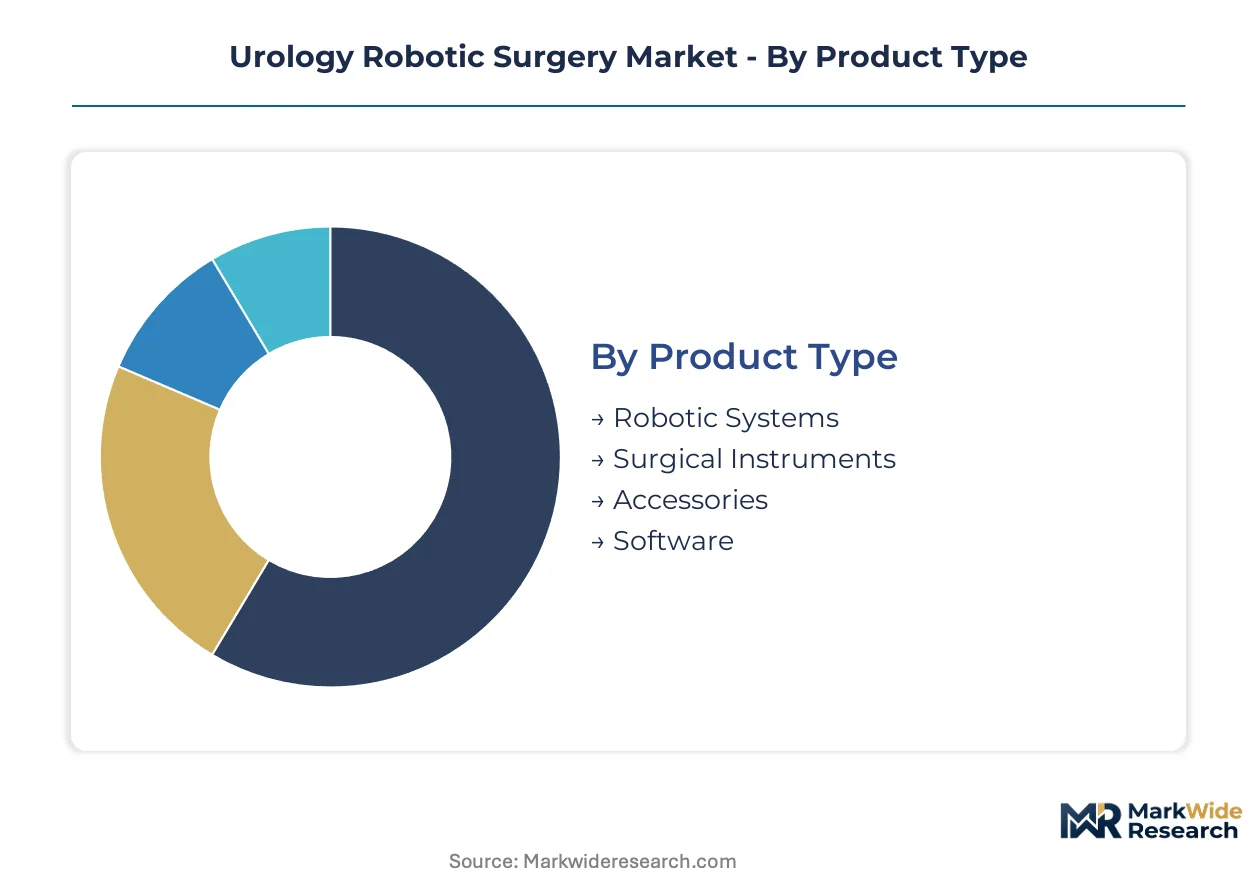
Segmentation reveals how capital intensity, procedure volume, and regulatory burden distribute across the urology robotic surgery value chain. Procurement committees evaluate segments through distinct lenses: capital equipment demands long depreciation cycles, while consumables generate recurring revenue streams tied to surgical throughput.
Product Type:
Robotic systems face FDA 510(k) and EU MDR Class IIb certification pathways with 18-24 month assessment timelines, whereas software modules navigate streamlined digital health premarket routes.
- Robotic Systems:Electromechanical platforms with articulated instrument arms, surgeon consoles, and vision carts translate hand motions into filtered micro-movements. Hospital networks in the United States and Germany concentrate procurement around modular architectures supporting multiple urology procedures within single capital commitments.
- Surgical Instruments:Per-procedure disposable attachments including graspers, needle drivers, and energy devices generate recurring margin pools. Japanese and German component suppliers dominate precision harmonic scalpel manufacturing, creating single-source vulnerability for OEMs.
- Accessories:Sterile drapes, trocars, and positioning aids complete the sterile field setup.
- Software:Preoperative planning modules, intraoperative analytics, and training simulations embed machine learning for skill transfer.
Robotic systems sit at the top of the volume ranking, with software climbing the fastest as AI-powered preoperative planning converges with haptic feedback training modules.
Application:
Procedure selection drives instrument consumption patterns and platform configuration requirements, with prostatectomy commanding dedicated single-purpose installations while cystectomy demands enhanced visualization capabilities.
- Prostatectomy:Radical removal of the prostate gland with nerve-sparing techniques dominates procedure volumes as expanded screening protocols enlarge eligible patient cohorts. Metropolitan hospital networks in the United States and Japan prioritize dedicated robotic suites for this indication.
- Cystectomy:Bladder removal with urinary diversion reconstruction represents the steepest expansion trajectory as 4K fluorescence imaging improves nerve-sparing outcomes and expands eligibility criteria for muscle-invasive cases.
- Nephrectomy:Partial or radical kidney removal leverages robotic precision for hilar dissection and vascular control.
- Ureterectomy:Ureteral resection and reconstruction addresses upper tract urothelial carcinoma with minimally invasive access.
Prostatectomy captures the largest share of installed base utilization, with cystectomy gaining share fastest through enhanced visualization adoption.
End User:
Facility type determines capital commitment scale, sterilization infrastructure requirements, and reimbursement capture mechanisms under divergent payment schedules.
- Hospitals:Academic medical centers and community hospitals house the dominant installed base with dedicated robotic surgery centers requiring CSSD infrastructure for reusable instrument reprocessing. Consolidated procurement groups across 15-20 affiliated facilities negotiate multi-vendor maintenance agreements through third-party clinical engineering firms.
- Ambulatory Surgery Centers:Freestanding facilities represent emerging installation sites as enhanced recovery pathways enable same-day discharge protocols for select prostatectomy cases.
- Specialty Clinics:Urology-focused outpatient settings concentrate diagnostic and minor procedural robotics.
- Research Institutions:Academic centers pilot autonomous suturing algorithms and computer vision modules through FDA investigational device exemptions.
Hospitals anchor capital deployment, with ambulatory surgery centers expanding most quickly as recovery protocols compress length-of-stay below 24 hours.
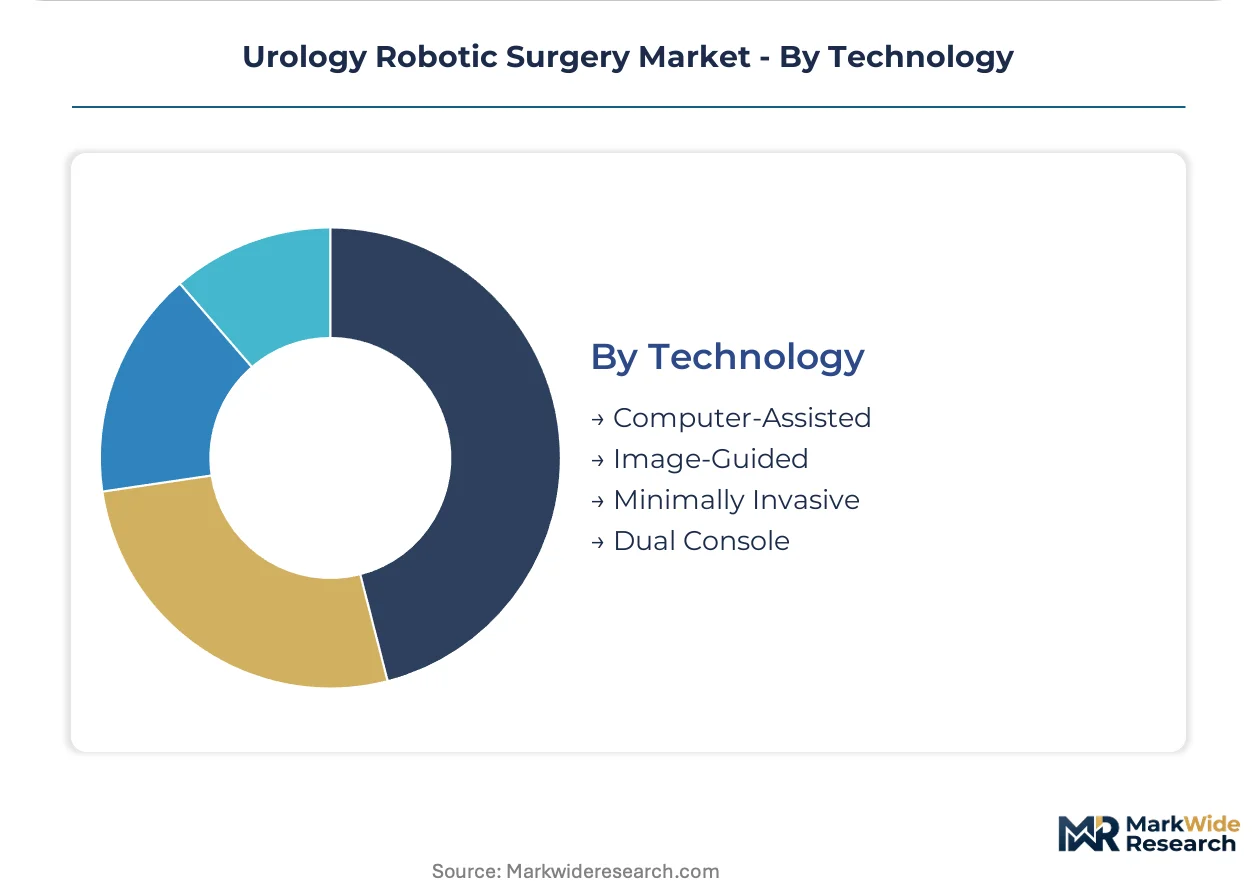
Technology:
Console architecture and guidance systems differentiate platforms through tremor filtration thresholds, visualization specifications, and training integration capabilities.
- Computer-Assisted:Master-slave teleoperation with motion scaling and tremor reduction below 0.2 millimeters constitutes the foundational platform category. Open console designs from Medtronic and modular architectures from Intuitive Surgical compete for hospital procurement committee preference.
- Image-Guided:Real-time overlay of preoperative MRI and CT datasets onto endoscopic views enables tumor margin identification.
- Minimally Invasive:7-10 millimeter incision widths with reduced blood loss and shorter recovery trajectories define the core value proposition.
- Dual Console:Two surgeon stations enable proctored training and collaborative procedures for complex reconstructions.
Computer-assisted platforms command the dominant technology share, with image-guided systems ascending fastest through AI-powered preoperative planning integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where urology robotic surgery platforms undergo final assembly, with EU MDR compliance costs pushing some manufacturers toward jurisdictions with streamlined premarket pathways while domestic production incentives in Asia-Pacific markets pull capacity eastward.
United States
Metropolitan hospital networks in Texas, California, and New York State are consolidating procurement across 15-20 affiliated facilities each, negotiating multi-vendor maintenance agreements through third-party clinical engineering firms. FDA 510(k) clearance pathways maintain their position as the benchmark for commercial launch sequencing, with average review cycles compressing for predicate-device submissions. The Greater Boston corridor anchors autonomous suturing algorithm development through academic medical center pilots under investigational device exemptions.
Germany
Baden-Württemberg and Bavaria host precision harmonic scalpel manufacturing clusters that supply componentry to global OEMs, creating single-source vulnerability for robotic instrument supply chains. EU MDR notified bodies in Berlin and Munich are extending conformity assessment timelines to 18-24 months for Class IIb surgical systems, delaying commercial launches versus prior CE marking pathways. The Rhine-Main region around Frankfurt concentrates hospital capital deployment for dedicated robotic surgery centers.
Japan
Demographic contraction among practicing urologists in the Kanto and Kansai regions is accelerating tremor-filtering platform adoption to extend operative careers beyond traditional retirement thresholds. METI production-linked incentives for medical device manufacturing are reducing import duties on robotic platforms for tier-2 hospital networks. Osaka and Nagoya academic medical centers are piloting 4K fluorescence imaging integration for nerve-sparing cystectomy outcomes.
India
Maharashtra and Karnataka are emerging as installation growth corridors as government PLI scheme subsidies for medical device manufacturing reduce landed costs for metropolitan hospital networks in Mumbai and Bangalore. CDSCO regulatory harmonization with FDA 510(k) pathways is compressing approval timelines for predicate robotic systems. The Delhi-NCR cluster is expanding dedicated robotic surgery centers within corporate hospital chains targeting medical tourism flows from Gulf states and Southeast Asia.
United Kingdom
The London-Southeast corridor dominates NHS capital procurement for robotic prostatectomy suites, with teaching hospitals in Manchester and Birmingham trailing in installation density. MHRA post-Brexit regulatory autonomy is diverging from EU MDR timelines for some digital surgery software modules, creating pathway arbitrage for AI-powered preoperative planning tools. Scotland and Wales remain underpenetrated relative to English hospital network concentration.
Urology Robotic Surgery Market Key Industry Players
United States producers anchor the premium-system tier; German and Japanese component specialists hold supply-side leverage over precision instrument manufacturing. The vendor base concentrates around three strategic archetypes: integrated platform OEMs with recurring instrument revenue streams, modular architecture challengers competing on procurement committee flexibility, and software-native entrants embedding AI directly into console interfaces. Capacity expansion through dedicated surgical suite construction and strategic partnerships with third-party clinical engineering firms represent the dominant competitive moves.
Among United States-based integrated platform manufacturers, Intuitive Surgical and Stryker occupy positions that exemplify divergent strategic postures toward open versus proprietary system architectures. Medtronic anchors the modular challenger tier with console designs that navigate hospital procurement committees through vendor-agnostic positioning. These three entities collectively represent the competitive fault lines around which pricing power, service contract bundling, and installed base retention will resolve over the forecast window.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Stryker |
| Medtronic |
| THINK Surgical |
| Renishaw plc |
| Titan Medical |
| Asensus Surgical US |
| AVRA Medical Robotics |
| Surgical Science Sweden AB |
| Others |
Cost & Logistics Intelligence
Consolidated procurement groups across United States metropolitan hospital networks command tiered pricing negotiations that unbundle after-sales service contracts from initial capital purchases. This buyer concentration shifts margin retention toward third-party clinical engineering firms and compresses OEM pricing power across robotic system and instrument categories.
Pricing Analysis
Direct-to-hospital contracting discounts dominate capital equipment transactions, with distributor margins compressed to single-digit percentages for robotic systems. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA clearance tier and after-sales bundling intensity. Pricing pressure stems from multi-vendor maintenance agreements that fragment service revenue pools. Ambulatory surgery centers exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize visualization specifications over unit economics.
Supply Chain Analysis
Precision manufacturing workforce availability in Baden-Württemberg and Bavaria anchors German component clusters, while Japanese suppliers in the Kansai region maintain harmonic scalpel production dominance. Robotic instrument supply draws from German precision engineering and Japanese miniaturization expertise, with trocar and drape manufacturing distributed across lower-cost Asian hubs. Single-source vulnerability concentrates in harmonic scalpel componentry. Distribution runs through OEM direct sales forces for capital equipment, with instrument disposables flowing through hospital GPO contracts and specialty surgical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in urology robotic surgery rests on instrument recurring revenue capture and software module attach rates as hardware pricing stabilizes. Cost compression in reusable instrument reprocessing creates additional margin pool for facilities investing in CSSD infrastructure.
For Market Incumbents: Cement installed base retention through proprietary instrument lock-in and console upgrade pathways. Defend against modular challengers by accelerating software companion development for preoperative planning. Prioritize backward integration into precision instrument manufacturing to reduce German and Japanese supplier dependency. Expand capacity in United States corridor markets to shorten proctoring logistics for surgeon credentialing programs.
For New Entrants and Emerging Players: Cloud-based training simulation platforms offer lowest-friction entry vectors for hospital systems seeking reduced learning curve solutions. Target ambulatory surgery center installations in United States metropolitan networks where same-day discharge protocols create capacity constraints unmet by incumbent scheduling. Pursue CE marking pathway arbitrage for AI-powered planning modules under MHRA post-Brexit regulatory autonomy.
For Investors and Strategic Acquirers: Hospital system strategic buyers are the most active acquirer in this space, consolidating procurement across 15-20 affiliated facilities to extract vendor concessions. Long-term viability favors platforms with open console architectures that accommodate multi-procedure utilization and third-party software integration. Monitor CMS reimbursement parity maintenance as primary inflection signal; material narrowing between robotic and laparoscopic payment rates would compress hospital capital commitment velocity regardless of clinical outcomes data.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIb timelines compress competitive launch windows for next-generation platforms. |
| Hospital System Partnership | Consolidated procurement groups across 15-20 facilities extract multi-vendor maintenance concessions. |
| Software Companion Development | AI-powered preoperative planning modules attach to console sales and generate recurring SaaS revenue. |
| Backward Integration | In-house precision instrument manufacturing reduces German and Japanese supplier concentration risk. |
| Reimbursement Strategy | CMS parity maintenance determines hospital capital commitment velocity for robotic suite construction. |
Research Approach
Multiple input streams — hospital procurement committee interviews, surgeon proctoring program assessments, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged urology department chairs, biomedical engineering directors, GPO contracts managers, and CSSD infrastructure planners across United States, German, and Japanese hospital networks. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement schedules, and hospital capital expenditure disclosures. Bottom-up installation base modeling and top-down healthcare capital spending allocation were cross-referenced for triangulation.
Data-stream reconciliation applied analytical frameworks across product type, application procedure, end-user facility category, and console technology architecture. CAGRs were derived from procedure volume elasticity to screening protocol expansion and installed base replacement cycles. Forecast inputs incorporated Japan's surgical workforce demographic contraction, India's PLI scheme subsidy phase-in, and autonomous suturing algorithm pilot progression through FDA investigational device exemptions.
The model assumes a particular technology adoption path; alternative pathways for autonomous suturing modules would alter the outlook for training program design and proctoring revenue models. Forecasts reflect assumptions regarding CMS reimbursement parity maintenance, EU MDR timeline normalization, and precision instrument supply chain stability. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Ureteral Catheters Market
Urology
Uropathy Treatment Market
Urology
Acute Pyelonephritis Treatment Market
Urology
Urinary Tract Infection (UTI) Market
Urology
Urology Devices Market
Urology
Obstructive Uropathy Treatment Market
Urology
Middle East and Africa Bladder Disorders Market
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market
Urology
Urethral Stricture Market
Urology
Complicated Urinary Tract Infections Treatment Market
Urology
Suprapubic Catheters Market
Urology
Ureterorenoscopes Market
Urology
India Urology Device Market
Urology
Europe Urology Devices Market
Urology
Urology Forceps Market
Urology
Prostatic Arterial Embolization (PAE) Market