
 Uropathy Treatment Market | 2026-2036
Uropathy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Uropathy Treatment Market Analytics
The EU Green Deal's pharmaceutical sustainability criteria is repositioning manufacturing standards across uropathy supply chains. Boston Scientific Corporation leverages its endourology device portfolio to sustain minimally invasive procedural growth in stone and benign prostatic hyperplasia management. Coloplast A/S anchors European continence care with specialized intermittent catheter systems. Medtronic competes through sacral neuromodulation technology leadership in refractory overactive bladder segments.
Uropathy treatment encompasses pharmacological and interventional therapies targeting disorders of urine production, storage, and evacuation, including small-molecule antimuscarinics, beta-3 adrenergic agonists, alpha-blockers, and neuromodulation devices typically administered via oral, intravesical, or implanted delivery routes to restore lower urinary tract function. The product type dimension shows antibiotics and antispasmodics occupying mature volume positions while herbal remedies gain traction in self-directed chronic management. The delivery mode segment reveals oral formulations dominating outpatient prescribing, with intravenous routes concentrated in acute pyelonephritis and complicated infection protocols. End-user structural patterns show hospitals capturing high-acuity procedural cases while homecare channels expand for long-term intermittent catheterization and neuromodulation maintenance.
The FDA's 505(b)(2) pathway and the EU MDR recertification timeline are reshaping product registration economics for device-drug combination therapies in urology. The EPA's pharmaceutical discharge standards and REACH chemical authorization requirements are forcing reformulation of catheter coatings and implantable device materials. Stakeholders must monitor evolving reimbursement divergence between sacral neuromodulation and emerging tibial nerve stimulation protocols across Medicare Advantage and commercial benefit designs.
Market Dynamics
The FDA's 505(b)(2) approval pathway is compressing development timelines for reformulated urological therapies while EU MDR recertification mandates force supply chain reconfiguration across implantable device portfolios.
Growth Catalysts
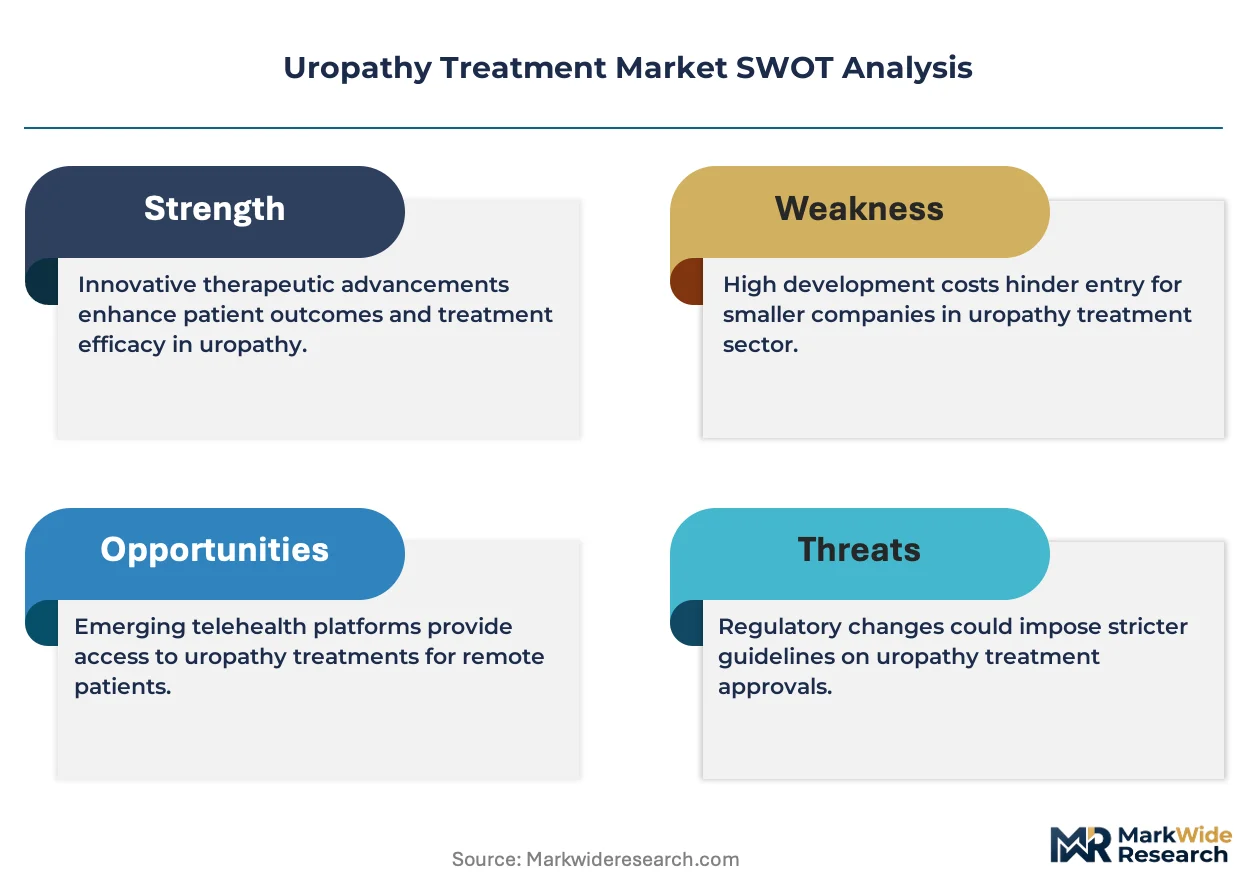
- Hospital outpatient expansion:Ambulatory surgical centers in the United States are absorbing high-volume stone management and benign prostatic hyperplasia procedures previously confined to inpatient settings.
- REACH chemical authorization:The European Chemicals Agency's phased restrictions on legacy catheter coatings are accelerating biocompatible material substitution in continence care manufacturing.
- Sacral neuromodulation:Implantable pulse generator technology is displacing chronic pharmaceutical management in refractory overactive bladder patient cohorts.
Market Restraints
- Silicone supply concentration:Catheter and implantable device manufacturers depend on a narrow base of Southeast Asian polymer suppliers, exposing production schedules to regional logistics disruptions.
- Reimbursement divergence:Medicare Advantage benefit designs create coverage gaps between sacral neuromodulation and percutaneous tibial nerve stimulation protocols.
- Antimicrobial resistance protocols:Hospital infection control committees are restricting empirical fluoroquinolone prescribing for uncomplicated urinary tract infections.
Strategic Opportunities
- Homecare channel expansion:Intermittent catheterization and neuromodulation device maintenance are migrating from clinical settings to patient-directed administration in Germany and France.
- Herbal remedy positioning:Self-directed chronic management segments in India present whitespace for standardized botanical formulations targeting interstitial cystitis symptom relief.
- Device-drug convergence:Intravesical delivery systems combining botulinum toxin with sustained-release matrices are opening procedural revenue streams in urology practices.
Industry Challenges
- EU MDR technical documentation:Legacy implantable device portfolios require extensive clinical evidence regeneration to maintain CE marking validity.
- Biocompatibility testing capacity:Contract laboratories face backlogs for ISO 10993 cytotoxicity and sensitization studies, delaying new coating introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uropathy Treatment Market |
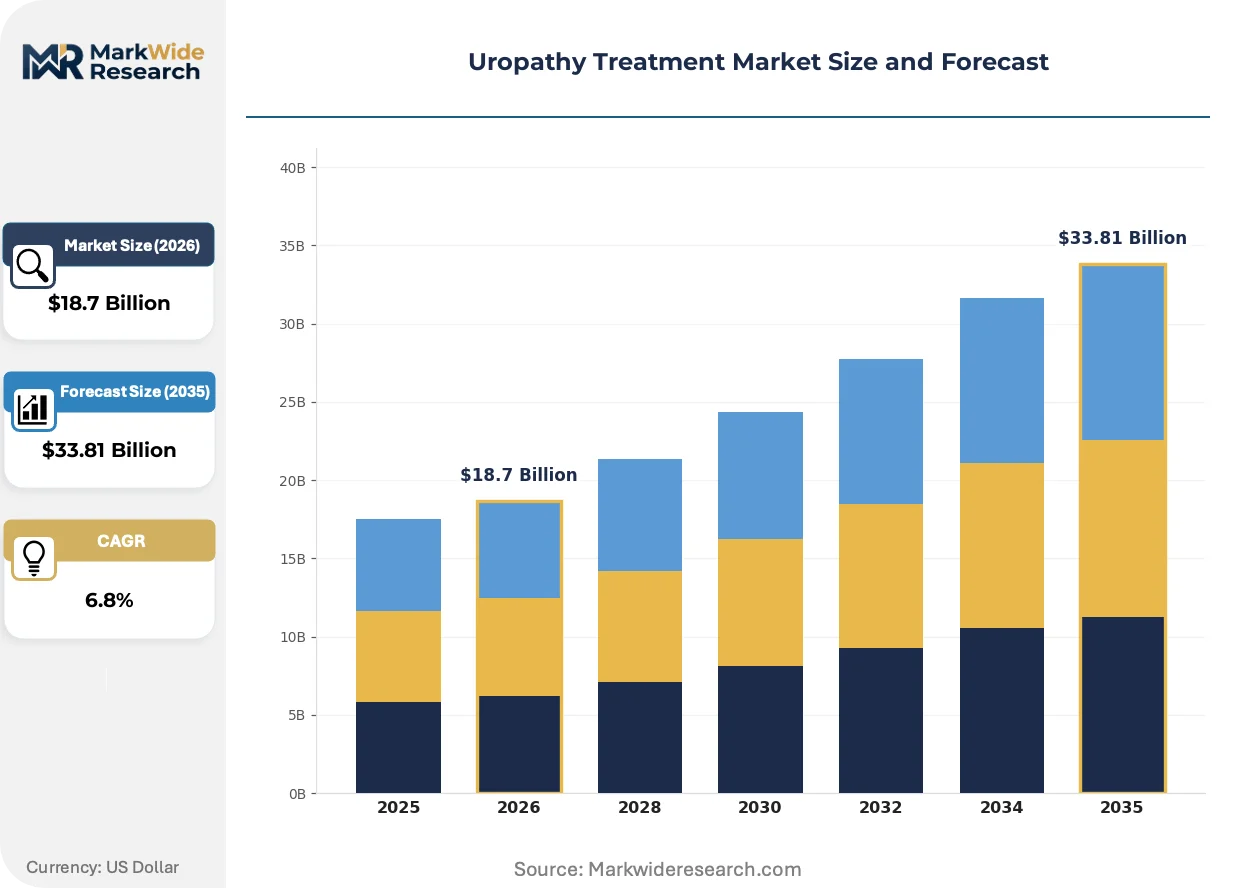
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antispasmodics, Analgesics, Herbal Remedies Delivery Mode: Intravenous, Oral, Topical, Subcutaneous End User: Clinics, Hospitals, Homecare, Rehabilitation Centers Treatment Stage: Acute, Chronic, Prophylactic, Palliative |
| Companies Covered | Boston Scientific Corporation, B. Braun Melsungen AG, Cook Medical, Coloplast A/S, Becton, Dickinson and Company, Astellas Pharma, Teleflex Incorporated, Medtronic, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uropathy Treatment Market Evolving Landscape
Digital health integration and minimally invasive procedural platforms are restructuring how uropathy therapies are delivered, monitored, and reimbursed across acute and chronic care continuums.
Beta-3 adrenergic agonists are overtaking antimuscarinic agents as first-line pharmacotherapy for overactive bladder in United States urology practices. Prescribers cite improved dry mouth and constipation tolerability profiles driving patient adherence. The shift is compressing antimuscarinic volume share and redirecting formulary negotiation leverage toward mirabegron-class molecules.
REACH authorization requirements for N-methyl-2-pyrrolidone and other legacy solvent systems are forcing catheter manufacturers toward aqueous-based coating processes. The industrial consequence is capital-intensive production line retooling across European manufacturing footprints. Device suppliers with integrated material science capabilities are internalizing coating development to maintain margin structures.
Patients with neurogenic bladder conditions are consolidating purchasing decisions through specialized durable medical equipment distributors rather than fragmented retail pharmacy channels. This channel concentration is elevating service bundling requirements—technical training, inventory management, insurance prior authorization support—as competitive differentiators. The pattern is most pronounced in Medicare-managed territories where prior authorization complexity deters direct-to-consumer models.
Uropathy Treatment Market Segmentation
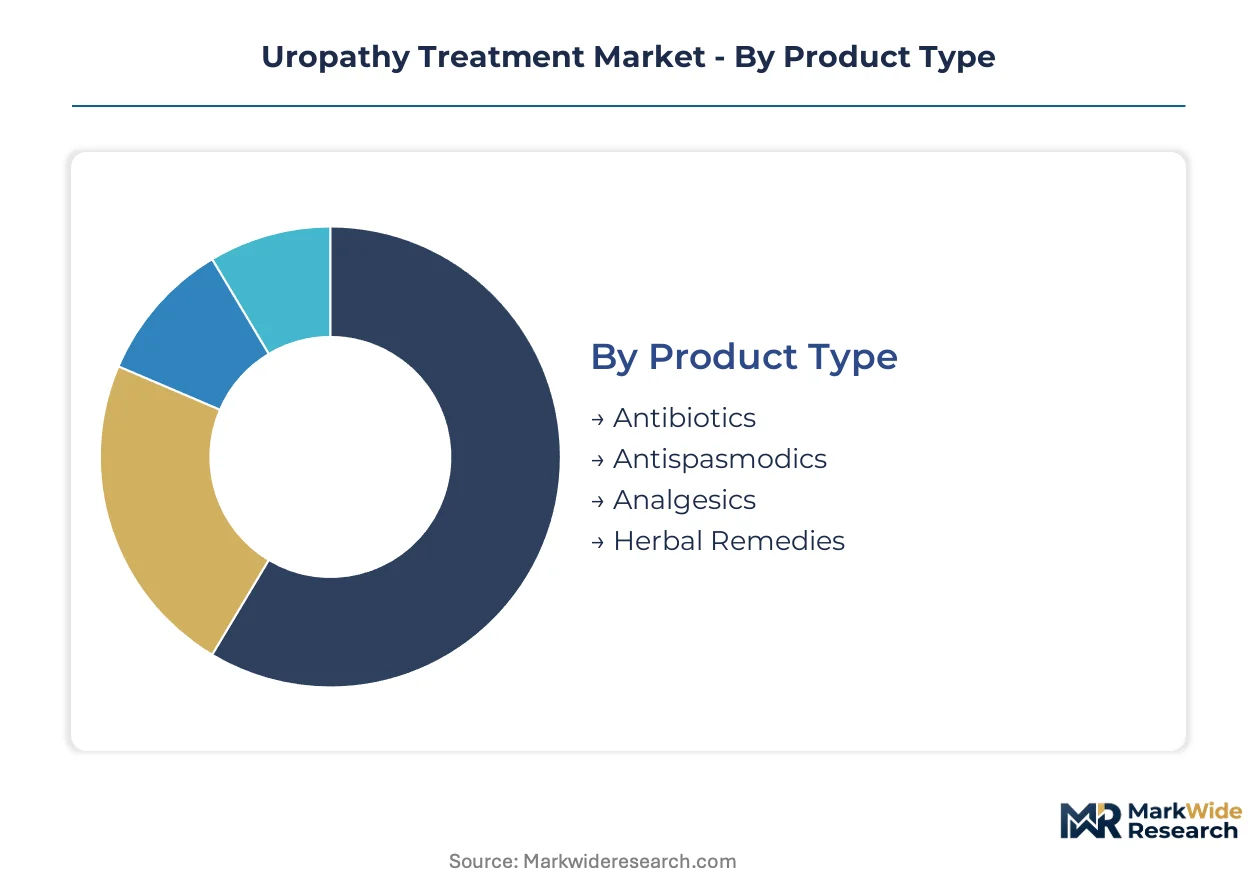
Uropathy treatment segmentation reveals distinct procurement patterns across pharmacological and interventional modalities. Buyer priorities shift from acute infection control toward chronic symptom management, reshaping volume distribution across delivery channels and care settings.
Product Type:
Prescriber tolerance profiles and resistance surveillance protocols determine formulary placement across therapeutic categories.
- Antibiotics:Fluoroquinolone and cephalosporin formulations dominate empirical therapy for uncomplicated urinary tract infections. Hospital formularies in the United States are narrowing coverage amid rising resistance surveillance mandates from the CDC.
- Antispasmodics:Antimuscarinic agents and beta-3 adrenergic agonists constitute first-line overactive bladder management. Mirabegron-class molecules are displacing tolterodine and oxybutynin in Medicare Advantage plans due to superior dry mouth and constipation profiles.
- Analgesics:Phenazopyridine and NSAID combinations address dysuria in acute cystitis protocols.
- Herbal Remedies:Standardized botanical formulations target interstitial cystitis symptom relief in self-directed patient segments.
Volume sits with antibiotics; growth tilts toward antispasmodics.
Delivery Mode:
Patient adherence economics and care setting migration reshape route selection across acute and chronic indications.
- Oral:Tablet and capsule formulations dominate outpatient prescribing for overactive bladder and benign prostatic hyperplasia. Retail pharmacy dispensing in Germany and France favors once-daily extended-release antimuscarinics.
- Intravenous:Ceftriaxone and piperacillin-tazobactam infusions concentrate in emergency department pyelonephritis protocols. Hospital outpatient departments in the United States absorb high-volume stone management cases previously confined to inpatient settings.
- Topical:Transdermal oxybutynin patches serve pediatric neurogenic bladder populations.
- Subcutaneous:Botulinum toxin delivery targets detrusor overactivity in spinal cord injury cohorts.
Oral routes capture the largest patient volumes; intravenous administration is expanding most quickly in ambulatory surgical centers.
End User:
Reimbursement complexity and procedural acuity determine channel concentration for device and pharmaceutical procurement.
- Hospitals:Academic medical centers manage complicated infections and surgical stone interventions. Sacral neuromodulation implantation and endourological procedures generate procedural revenue in high-acuity settings.
- Homecare:Intermittent catheterization and neuromodulation device maintenance are migrating from clinical settings to patient-directed administration. Specialized durable medical equipment distributors in Medicare-managed territories bundle technical training with inventory management.
- Clinics:Urology group practices administer intravesical botulinum toxin and percutaneous tibial nerve stimulation.
- Rehabilitation Centers:Neurogenic bladder programs coordinate catheterization schedules with physical therapy protocols.
Hospitals retain procedural margin concentration; homecare channels are gaining share fastest in continence care.
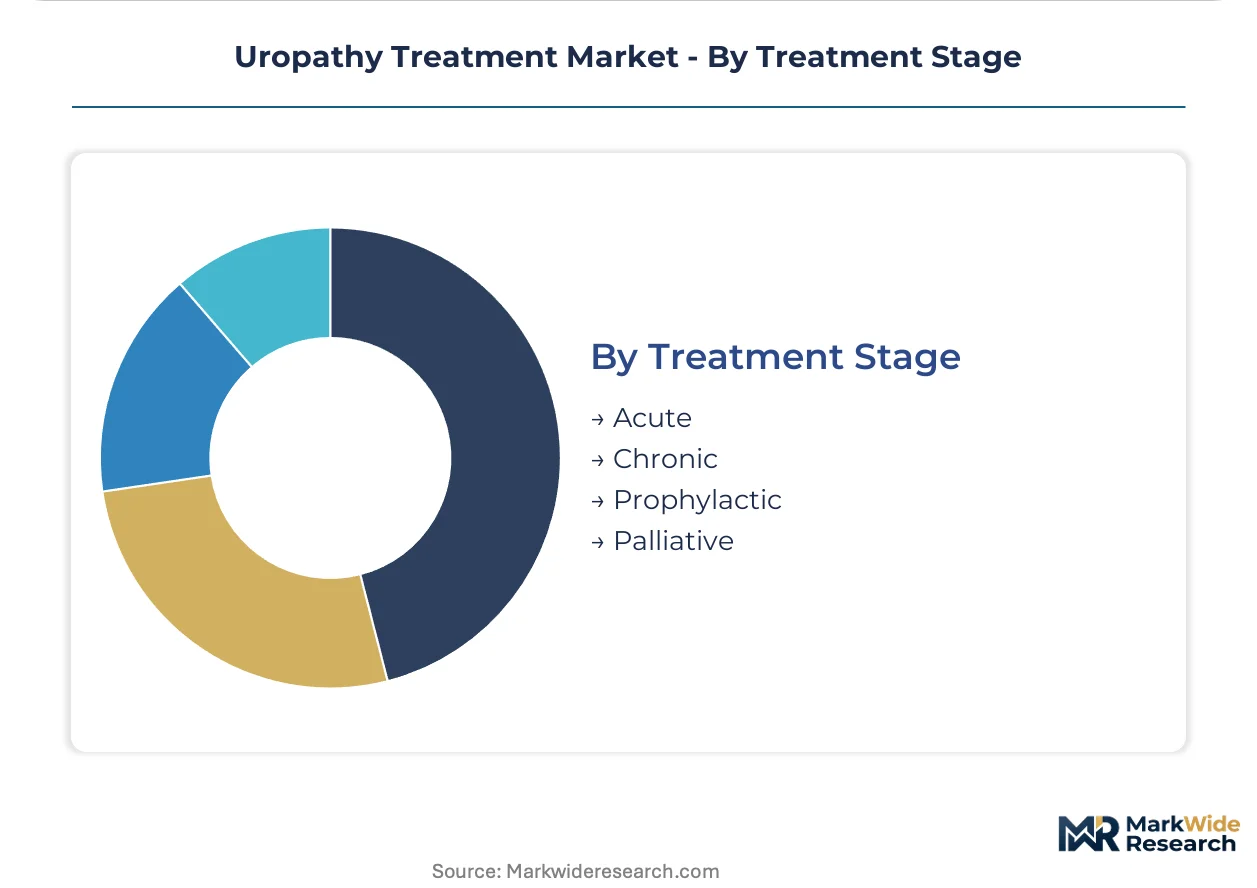
Treatment Stage:
Disease trajectory and symptom burden dictate therapy intensity and monitoring frequency across the care continuum.
- Acute:Empirical antibiotic therapy targets uncomplicated infection resolution. FDA antimicrobial resistance guidance is narrowing fluoroquinolone prescribing in emergency departments.
- Chronic:Long-term antimuscarinic or beta-3 agonist maintenance manages refractory overactive bladder. Patient adherence programs in commercial payer networks address persistence gaps beyond six months.
- Prophylactic:Low-dose antibiotic regimens and cranberry extract supplementation prevent recurrent infection in postmenopausal women.
- Palliative:Symptom-focused interventions address urinary obstruction in advanced malignancy.
Chronic stage management commands sustained pharmaceutical volume; acute intervention shows steepest expansion trajectory in ambulatory settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in the United States and Germany while pharmaceutical production spreads across Japan and India. Consumption patterns diverge between aging Western populations driving neuromodulation adoption and emerging Asian markets absorbing generic antibiotic volumes.
United States
Medicare Advantage expansion for overactive bladder therapies sustains pharmaceutical volume growth. The FDA's 505(b)(2) pathway accelerates reformulated urological therapy approvals. Minneapolis-based Medtronic anchors sacral neuromodulation device development while Boston Scientific Corporation drives endourology procedural innovation.
Germany
Hospital outpatient departments absorb high-volume stone management procedures previously confined to inpatient settings. REACH chemical authorization mandates force biocompatible catheter coating substitutions. Coloplast A/S maintains European continence care leadership through specialized intermittent catheter systems manufactured in the region.
Japan
Aging demographics drive beta-3 adrenergic agonist prescribing for overactive bladder management. The PMDA maintains rigorous clinical evidence standards for implantable device registrations. Tokyo-Osaka medical device clusters concentrate neuromodulation pulse generator assembly and urological endoscopy manufacturing.
India
Self-directed chronic management segments present whitespace for standardized botanical formulations targeting interstitial cystitis relief. CDSCO regulatory pathways streamline generic antibiotic registrations for uncomplicated urinary tract infections. Hyderabad and Ahmedabad pharmaceutical corridors expand cephalosporin and fluoroquinolone active pharmaceutical ingredient production.
United Kingdom
NHS England reimbursement protocols create coverage gaps between sacral neuromodulation and percutaneous tibial nerve stimulation. The MHRA post-Brexit regulatory framework diverges from EU MDR timelines for implantable device recertification. London-Oxford-Cambridge medical technology clusters concentrate digital health integration for remote uropathy monitoring platforms.
Uropathy Treatment Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with integrated device-drug portfolios. Large-cap players with neuromodulation and endourology capabilities capture procedural revenue concentration in hospital settings. Two strategic archetypes dominate: pharmaceutical specialists with urology-focused small-molecule pipelines and device manufacturers with minimally invasive platform ecosystems. Competitive moves center on M&A for coating technology capabilities and strategic partnerships for homecare channel distribution.
Among diversified medical technology conglomerates, Boston Scientific Corporation and Medtronic occupy positions exemplifying integrated neuromodulation and endourology platform strategies. Coloplast A/S represents the specialized continence care archetype with concentrated catheter system expertise. Astellas Pharma sits within the pharmaceutical specialist tier with beta-3 adrenergic agonist and antimuscarinic portfolios. These three anchors demonstrate how competitive positioning splits between procedural device ecosystems and chronic pharmaceutical maintenance therapies.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| B. Braun Melsungen AG |
| Cook Medical |
| Coloplast A/S |
| Becton, Dickinson and Company |
| Astellas Pharma |
| Teleflex Incorporated |
| Medtronic |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
Aqueous-based coating process transitions across European manufacturing footprints simultaneously compress production economics and concentrate supply relationships among catheter manufacturers with captive material science capabilities. REACH-mandated solvent substitutions force capital-intensive retooling that favors integrated producers over outsourced coating operations, reshaping margin structures and procurement leverage across the uropathy device landscape.
Pricing Analysis
Cost-down pressure on implantable neuromodulation devices accelerates as Medicare Advantage benefit designs narrow reimbursement differentials between sacral and tibial nerve stimulation protocols. Three-tier pricing structure across premium, standard, and economy levels separates advanced biocompatible coatings from legacy silicone formulations from uncoated commodity catheters. Price differentiation traces to ISO 10993 certification tiers and after-sales service bundling through durable medical equipment distributors. Hospital procurement committees demonstrate highest price sensitivity; academic medical centers with dedicated urology programs exhibit lowest.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian polymer suppliers for medical-grade silicone feedstocks essential to catheter and implantable device production. Manufacturing concentrates in Malaysia, Thailand, and Singapore for silicone raw materials, with Germany and the United States hosting downstream device assembly and coating operations. Component dependencies encompass platinum-cured silicone elastomers, implantable-grade titanium housings, and lithium-ion pulse generator cells. Tariff exposure on Chinese-sourced coating solvents elevates input cost volatility. Distribution runs through specialized durable medical equipment channels for homecare segments and direct hospital contracting for acute procedural volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The uropathy treatment market operates as a vertical-integration race where coating technology capabilities and homecare channel control represent decisive upstream and downstream levers. Players capturing both dimensions will consolidate margin pools currently fragmented across material suppliers, contract manufacturers, and regional distributors.
For Market Incumbents: Anchor sacral neuromodulation market position through backward integration into biocompatible coating development and captive silicone compounding capabilities. Defend against emerging tibial nerve stimulation substitutes by embedding pulse generator technology with hospital outpatient departments through exclusive equipment placement agreements. Prioritize CE marking investment under EU MDR recertification timelines to lock out non-compliant competitors.
For New Entrants and Emerging Players: Launch via specialized durable medical equipment distributor partnerships targeting Medicare-managed territories where prior authorization complexity deters direct-to-consumer models. Penetrate India's self-directed chronic management whitespace with standardized botanical formulations for interstitial cystitis symptom relief, leveraging CDSCO streamlined pathways. Exploit device-drug convergence opportunities in intravesical delivery systems combining botulinum toxin with sustained-release matrices.
For Investors and Strategic Acquirers: Exit pathways concentrate in coating technology specialists with ISO 10993 testing capabilities and established hospital system relationships. Long-term viability favors targets with integrated material science platforms capable of REACH-compliant aqueous process transitions. Watch FDA 505(b)(2) approval velocity for reformulated urological therapies as inflection indicator for pharmaceutical segment consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Biocompatible Coating Internalization | Captive aqueous process development insulates margins from REACH-mandated solvent substitution costs. |
| EU MDR Recertification Acceleration | Early CE marking completion under tightened clinical evidence requirements locks competitor access to European hospital procurement. |
| Homecare Channel Partnership Expansion | Durable medical equipment distributor alliances bundle technical training with inventory management for Medicare territories. |
| Botulinum Toxin Intravesical Delivery Development | Device-drug combination platforms open procedural revenue streams in urology group practices. |
| Beta-3 Agonist Formulary Positioning | Mirabegron-class molecule negotiations with Medicare Advantage plans displace antimuscarinic volume share. |
Research Methodology
Document review covered FDA 505(b)(2) approval filings, EU MDR technical documentation requirements, and hospital procurement database records, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at device manufacturers. Secondary sources encompassed CMS Medicare reimbursement schedules, ECHA REACH authorization timelines, and clinical evidence standards from ISO 10993 biocompatibility testing protocols. Bottom-up patient volume modeling and top-down pharmaceutical expenditure triangulation validated segment-level estimates.
Cross-referencing historical approval velocity against expert panel input on regulatory timeline compression shaped the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, delivery mode, end-user channel, and treatment stage intensity. CAGRs derived from patent expiration schedules, generic entry assumptions, and procedural volume migration patterns between inpatient and ambulatory settings. Forecast inputs incorporated neuromodulation device replacement cycles and antibiotic resistance surveillance protocol impacts on empirical prescribing.
The model assumes a particular technology adoption path; alternative pathways for tibial nerve stimulation displacement of sacral neuromodulation would alter the outlook for implantable device revenue concentration. Forecasts reflect assumptions regarding REACH implementation timelines and Medicare Advantage benefit design stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Urinary Retention Therapeutics Market
Urology
Transrectal Ultrasound Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
Europe Bladder Disorders Market
Urology
Acquired Cystic Kidney Disease Treatment Market
Urology
Urinary Incontinence Therapeutics Market
Urology
Urology Devices Market
Urology
Urethral Stricture Market
Urology
Ureter Cancer Treatment Market
Urology
Urology Disposables Market
Urology
Renal Cyst Treatment Market
Urology
Global Castrate Resistant Prostate Cancer Market
Urology
Nephrology and Urology Incontinence Devices Market
Urology
Cystoscope Market
Urology
Uraemia Treatment Market
Urology
Benign Prostatic Hyperplasia Market