
 Middle East and Africa Bladder Disorders Market | 2026-2036
Middle East and Africa Bladder Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Bladder Disorders Market Foresight
The Middle East and Africa bladder disorders landscape is pivoting between premium neuromodulator implants and commodity anticholinergic tablets. Astellas Pharma Inc leverages its established urology portfolio to dominate oral therapy channels across Gulf markets. Medtronic Plc anchors the high-value segment through its sacral nerve stimulation systems deployed in tertiary Saudi and UAE hospitals. Pfizer Inc competes on manufacturing scale, sustaining broad distribution of generic-accessible overactive bladder medications.
Middle East and Africa bladder disorders encompass pathological conditions affecting urinary storage and voiding function, treated through pharmaceutical agents targeting muscarinic or beta-adrenergic receptors and interventional therapies modulating nerve signaling. Anticholinergics retain the largest prescription volume but face margin compression from generic substitution, while beta-3 agonists capture premium positioning among patients intolerant to first-line therapy. Injectable botulinum toxin and intravesical delivery modes represent the fastest-expanding structural pockets, concentrated in South Africa's private reimbursement environment and Dubai's medical tourism corridors.
Saudi Arabia's SFDA and South Africa's SAHPRA enforce divergent approval timelines for implantable urological devices, fragmenting market access protocols across the region. The UAE's MOHAP and Egypt's EDA shape pharmaceutical import licensing and local manufacturing incentives that redirect supply chain investments. Stakeholders must monitor regulatory harmonization progress between Gulf standardization initiatives and sub-Saharan national formularies to anticipate reimbursement and registration advantages.
Market Dynamics
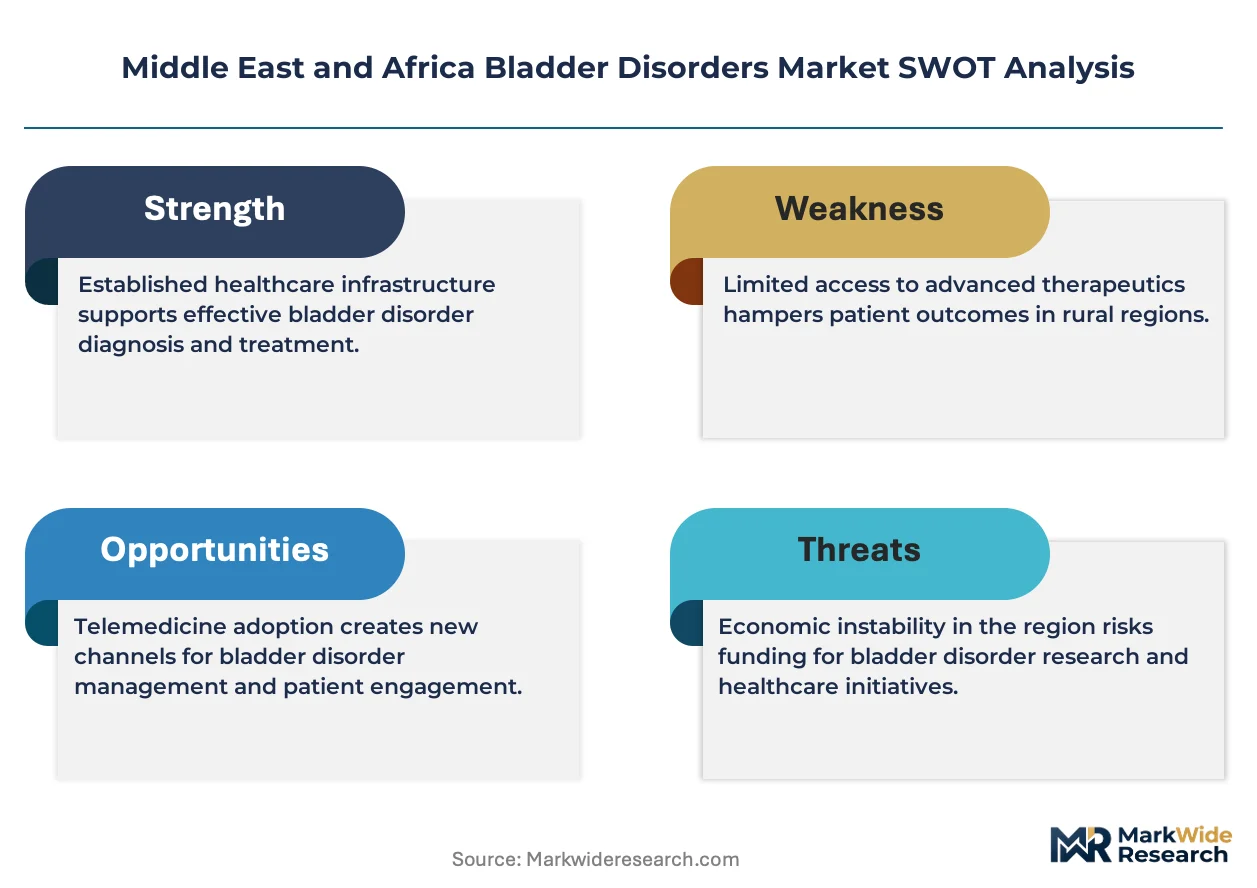
Hospital procurement of sacral neuromodulation systems is concentrating purchasing power across Gulf Cooperation Council tertiary care networks, compressing margins for implantable urological device suppliers while elevating technical service requirements.
Growth Catalysts
- SFDA pathway streamlining:Saudi Arabia's tightened yet clarified registration protocols for implantable urological products are accelerating commercialization timelines for neuromodulation systems in the kingdom's largest hospital networks.
- Medical tourism corridors:Dubai's healthcare free zones are attracting high-value bladder disorder interventions, creating demand clusters for botulinum toxin injections and advanced diagnostic urodynamics.
- Private hospital consolidation:South Africa's Netcare and Mediclinic networks are standardizing urology protocols across their facilities, generating volume commitments for premium beta-3 agonist therapies.
Market Restraints
- Generic anticholinergic saturation:Commodity tablet pricing in Egypt and Nigeria has collapsed below sustainable levels for originator manufacturers, eroding returns across North African pharmaceutical distribution.
- Implantable device supply concentration:Sacral nerve stimulation systems depend on single-source neurostimulator generators and lead assemblies, exposing Gulf hospital procurement to extended backorder risk.
- Reimbursement fragmentation:Divergent national formulary inclusion criteria across SAHPRA, EDA, and MOHAP jurisdictions force parallel regulatory investments without harmonized market access.
Strategic Opportunities
- Telemedicine-integrated urodynamics:Remote diagnostic platforms are penetrating Kenya and Nigeria's clinic networks, enabling bladder disorder screening without capital-intensive cystometry equipment deployment.
- Local manufacturing incentives:Egypt's EDA pharmaceutical import substitution policies offer tax advantages for regional production of oral overactive bladder medications serving Levant and North African markets.
- Intravesical delivery innovation:Novel catheter-based drug administration systems are capturing premium positioning in South Africa's private reimbursement environment for patients failing oral therapy.
Industry Challenges
- Implantable device servicing infrastructure:Sacral neuromodulator programming and troubleshooting requires trained clinical specialists scarce across sub-Saharan Africa's urology departments.
- Multinational trial recruitment:Bladder disorder clinical studies face patient enrollment bottlenecks in Gulf markets due to cultural sensitivities around urological condition disclosure.
- Legacy anticholinergic switching resistance:Physician prescribing habits in established Egyptian and Saudi clinic chains impede beta-3 agonist uptake despite superior tolerability profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Bladder Disorders Market |
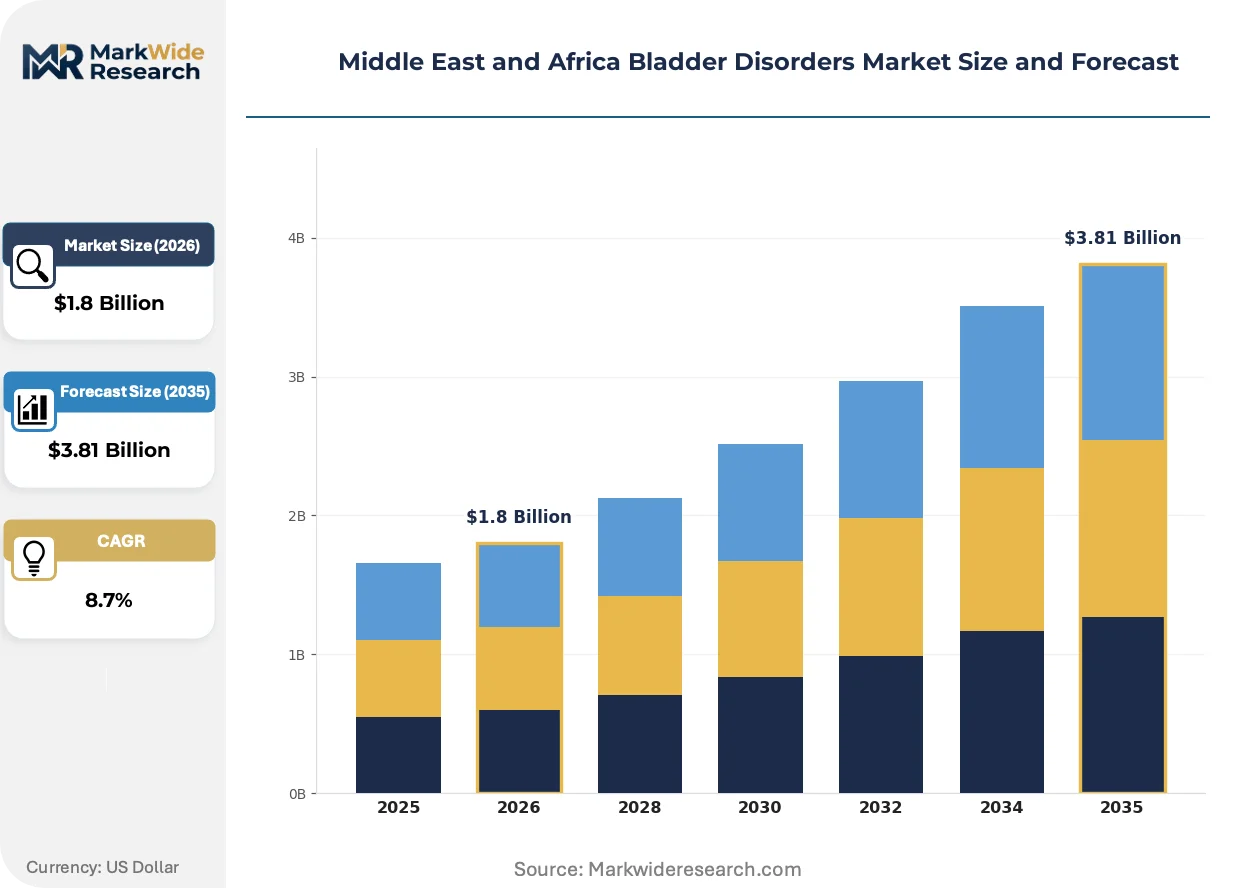
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticholinergics, Beta-3 Agonists, Neuromodulators, Botulinum Toxin Delivery Mode: Oral, Injectable, Transdermal, Intravesical End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Application: Overactive Bladder, Interstitial Cystitis, Bladder Cancer, Neurogenic Bladder |
| Companies Covered | Astellas Pharma Inc, AbbVie Inc, Pfizer Inc, Endo Pharmaceuticals Inc, Hisamitsu Pharmaceutical Co., Inc., Medtronic Plc, Teva Pharmaceutical Industries Ltd, Johnson & Johnson, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Bladder Disorders Market Shifts & Advancements
Digital health integration and minimally invasive intervention modalities are restructuring how bladder disorders are diagnosed, monitored, and treated across Middle East and Africa healthcare systems. Three developments merit particular attention.
Wireless home urodynamic monitoring systems are decentralizing diagnostic capacity from centralized hospital cystometry suites to outpatient and home settings. Private urology chains in the UAE and Saudi Arabia are deploying these platforms to reduce patient travel burden and accelerate treatment initiation. The technology is decentralizing geographic access to specialist bladder function assessment across dispersed Gulf populations.
SFDA's 2023 implantable device cybersecurity guidance is mandating encrypted telemetry and remote monitoring capabilities for all new neuromodulator registrations. Manufacturers must redesign legacy product architectures to satisfy these connectivity requirements before Saudi market entry. Sacral nerve stimulation systems face the steepest compliance burden given their long implantation lifecycles and software update dependencies.
Self-pay urology clinic chains in Egypt and Jordan are unbundling diagnostic packages from treatment protocols, allowing patients to stage expenditures across multiple visits. This payment flexibility is displacing traditional all-inclusive hospital billing models in cash-dominant healthcare markets. The behavioral shift is most pronounced among middle-income patients seeking botulinum toxin therapy without comprehensive insurance coverage.
Middle East and Africa Bladder Disorders Market Segmentation
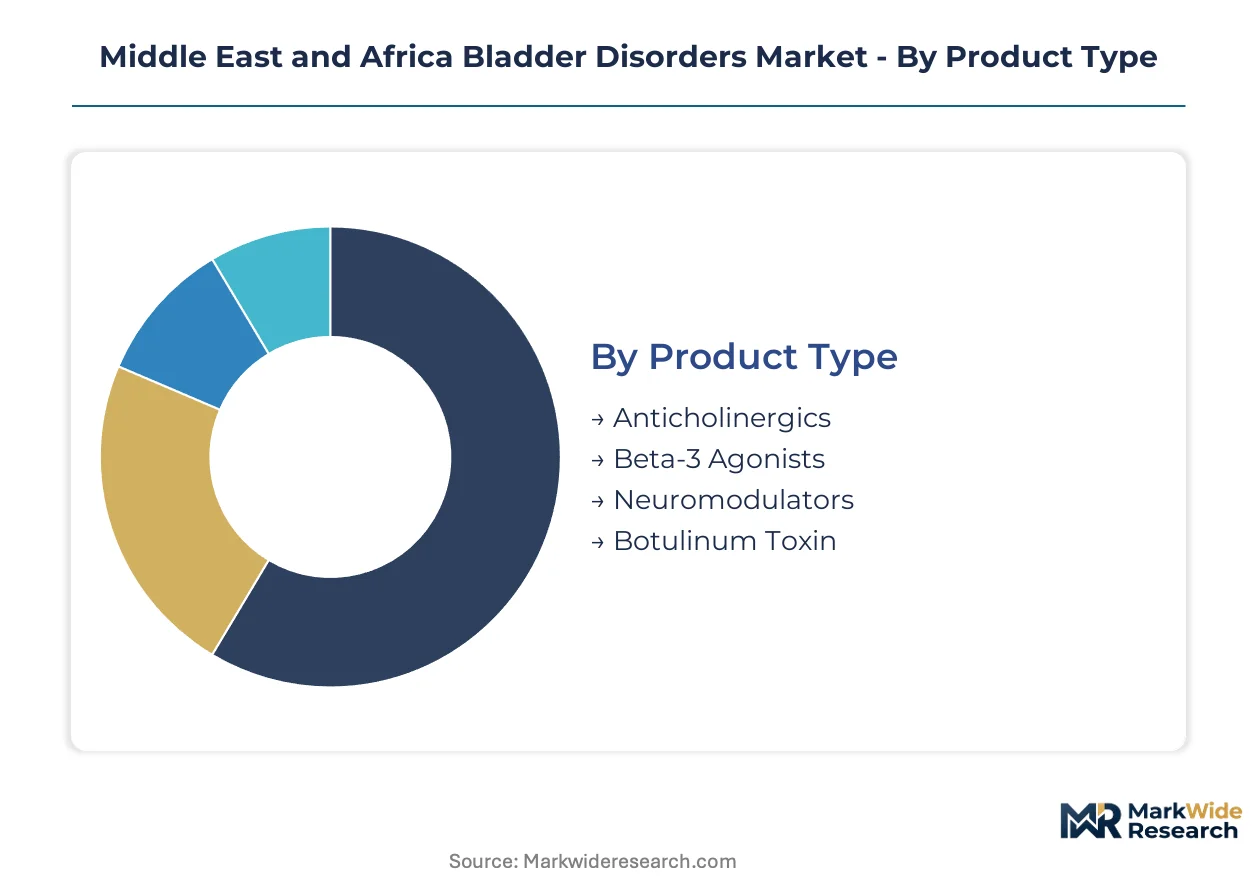
Bladder disorder therapeutics fragment across pharmacological mechanisms, delivery technologies, and care settings. Treatment selection depends on symptom severity, patient tolerance profiles, and reimbursement access across Gulf and sub-Saharan healthcare systems.
Product Type:
Customization intensity varies sharply across this category, from mass-manufactured tablets to patient-programmed implantable systems.
- Anticholinergics:First-line muscarinic receptor antagonists including oxybutynin and tolterodine dominate prescription volumes across Egypt and Nigeria's public health systems. Generic saturation in North African markets has collapsed pricing below sustainable levels for originator manufacturers.
- Beta-3 Agonists:Mirabegron and vibegron target adrenergic receptors with superior cardiovascular tolerability profiles. South Africa's Netcare and Mediclinic private networks are standardizing these therapies for patients failing anticholinergic therapy.
- Neuromodulators:Sacral nerve stimulation systems from Medtronic Plc anchor high-value segments in Saudi and UAE tertiary hospitals.
- Botulinum Toxin:Intradetrusor injections capture premium positioning in Dubai's medical tourism corridors and South African private reimbursement environments.
Leading the category by volume: Anticholinergics. Growing fastest: Neuromodulators.
Delivery Mode:
Route selection maps directly to care setting infrastructure and patient self-management capacity across the region.
- Oral:Tablet formulations enable widespread distribution through retail pharmacy channels in Egypt, Nigeria, and Kenya. Convenience drives adherence among working-age patients managing overactive bladder symptoms.
- Injectable:Botulinum toxin administration requires cystoscopic placement in hospital or ambulatory surgical settings. Demand concentrates in South Africa's private reimbursement environment and Dubai's healthcare free zones.
- Transdermal:Oxybutynin patches bypass first-pass hepatic metabolism for patients with anticholinergic intolerance. Limited availability through Gulf hospital formularies restricts penetration.
- Intravesical:Catheter-based drug delivery targets interstitial cystitis and refractory cases. Novel administration systems are capturing premium positioning in South African private networks.
Oral delivery commands the largest patient base. Intravesical modes are expanding most quickly.
End User:
Facility type determines technology access tier and reimbursement pathway across fragmented healthcare systems.
- Hospitals:Tertiary centers in Saudi Arabia, UAE, and South Africa deploy full diagnostic and interventional capabilities including urodynamics suites and neuromodulator implantation programs.
- Clinics:Egypt's expanding urology clinic chains and Jordan's self-pay facilities are unbundling diagnostic packages from treatment protocols. Payment flexibility attracts middle-income patients seeking staged expenditure.
- Rehabilitation Centers:Neurogenic bladder management for spinal cord injury patients concentrates in specialized facilities with catheterization programs.
- Home Care:Wireless home urodynamic monitoring systems are decentralizing diagnostic capacity from hospital cystometry suites to outpatient settings in UAE and Saudi Arabia.
Hospitals retain the highest procedure value. Home care shows the steepest expansion trajectory.
Application:
Disease severity and etiology dictate therapeutic intensity from behavioral modification to implantable devices.
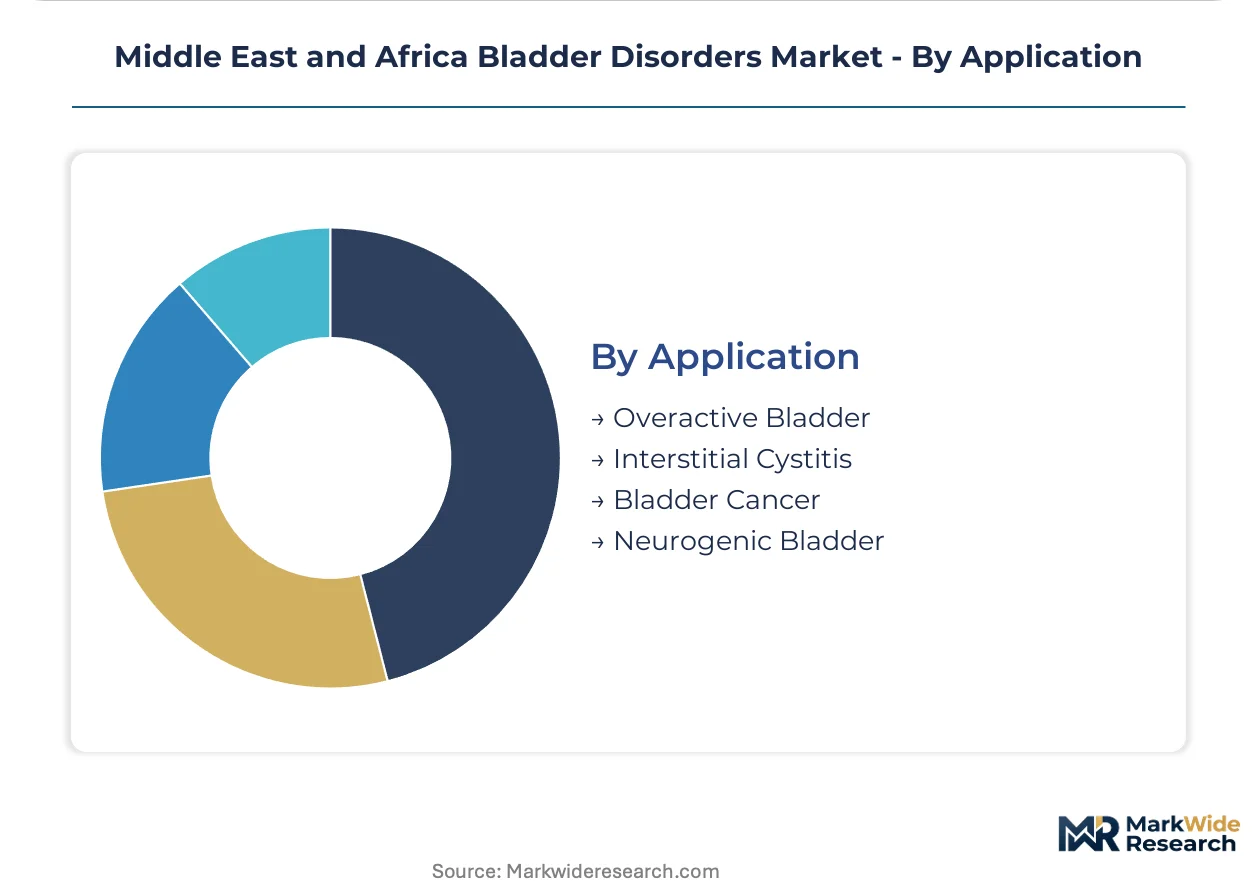
- Overactive Bladder:Idiopathic urgency-frequency syndrome represents the largest addressable population across all geographies. Treatment escalates from anticholinergics through beta-3 agonists to neuromodulation.
- Interstitial Cystitis:Painful bladder syndrome requires multimodal management including intravesical therapies. Diagnostic complexity limits recognition in resource-constrained settings.
- Bladder Cancer:Intravesical chemotherapy and immunotherapy installations overlap with functional bladder disorder infrastructure in hospital settings.
- Neurogenic Bladder:Spinal cord injury and multiple sclerosis-related voiding dysfunction demands specialized urodynamic evaluation and catheterization programs.
Overactive bladder generates the highest case volume. Neurogenic bladder applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's healthcare free zones anchor high-value bladder disorder interventions across the Middle East and Africa, drawing medical tourism demand for botulinum toxin injections and advanced urodynamics that reshape regional treatment distribution.
Saudi Arabia
King Faisal Specialist Hospital and Saudi German Hospital networks drive sacral neuromodulator implantation volumes for refractory overactive bladder patients. SFDA tightened cybersecurity requirements for implantable urological devices in 2023, mandating encrypted telemetry for new registrations. Riyadh and Jeddah tertiary centers concentrate Gulf Cooperation Council procurement negotiations, compressing supplier margins through consolidated purchasing power.
United Arab Emirates
Dubai Healthcare City and Abu Dhabi's Cleveland Clinic Abu Dhabi generate premium demand for intravesical therapies and wireless home urodynamic monitoring systems. MOHAP pharmaceutical import licensing frameworks incentivize regional distribution hub establishment. Private urology chains across Dubai's medical tourism corridors unbundle diagnostic packages from treatment protocols, enabling staged patient expenditure.
South Africa
Netcare and Mediclinic private hospital networks standardize beta-3 agonist protocols across their urology departments, generating volume commitments for premium oral therapies. SAHPRA maintains divergent approval timelines for implantable devices compared to Gulf regulators, fragmenting market access investments. Johannesburg and Cape Town private reimbursement environments concentrate botulinum toxin demand among insured populations.
Egypt
Expanding urology clinic chains in Cairo and Alexandria serve middle-income patients seeking anticholinergic therapy and staged diagnostic expenditure. EDA pharmaceutical import substitution policies offer tax advantages for local manufacturing of oral overactive bladder medications. Self-pay clinic models displace traditional hospital billing in cash-dominant healthcare markets.
Nigeria
Lagos and Abuja retail pharmacy channels distribute generic anticholinergic tablets to the region's largest addressable patient population for overactive bladder symptoms. The country's national pharmaceutical regulator enforces variable import licensing timelines that disrupt supply chain predictability. Urban clinic networks deploy telemedicine-integrated screening platforms to circumvent capital-intensive cystometry equipment gaps.
Middle East and Africa Bladder Disorders Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the therapeutic intensity spectrum, with implantable neuromodulation systems commanding technical service premiums while generic anticholinergic tablets face pricing collapse. The market structures around three strategic archetypes: multinational pharmaceutical conglomerates with established urology portfolios, specialized neuromodulation device manufacturers with hospital direct sales forces, and regional generic manufacturers exploiting import substitution incentives. Competitive moves concentrate on M&A for urology specialty assets and strategic partnerships with Gulf hospital procurement consortia.
Within the multinational pharmaceutical tier, Astellas Pharma Inc and Pfizer Inc anchor oral therapy distribution across divergent reimbursement environments. Medtronic Plc exemplifies the implantable device specialist archetype, occupying a position in tertiary hospital neuromodulation programs where technical service capabilities determine contract awards. These three companies represent the dominant competitive anchors spanning pharmaceutical and interventional therapeutic domains.
| Leading Market Players |
|---|
| Astellas Pharma Inc |
| AbbVie Inc |
| Pfizer Inc |
| Endo Pharmaceuticals Inc |
| Hisamitsu Pharmaceutical Co., Inc. |
| Medtronic Plc |
| Teva Pharmaceutical Industries Ltd |
| Johnson & Johnson |
| F. Hoffmann-La Roche Ltd |
| Others |
Supply & Pricing Matrix
Gulf Cooperation Council tertiary hospital networks concentrate procurement power for implantable urological devices, forcing value-based contracting that ties device pricing to patient outcome guarantees and technical service uptime commitments across Saudi and UAE health systems.
Pricing Analysis
Outcome-based pricing anchors the neuromodulator segment, where Medtronic Plc contracts with Saudi tertiary centers tie reimbursement to therapy response rates and device longevity metrics. Price differentiation separates premium beta-3 agonist therapies in South African private networks from commodity anticholinergic tablets in Egyptian retail channels. Cost compression in North African pharmaceutical distribution is intensifying because generic substitution has collapsed originator margins below sustainable levels. Public health systems in Egypt and Nigeria exhibit extreme price sensitivity, while Dubai's medical tourism corridors sustain premium positioning for botulinum toxin interventions.
Supply Chain Analysis
Single-source vulnerability sits with neurostimulator generator assemblies manufactured in the United States and Ireland, exposing Gulf hospital procurement to extended backorder risk when demand spikes exceed production capacity. The supply chain draws from specialized electrode lead production in Germany and Japan, with sterile packaging operations concentrated in Switzerland and the Netherlands. Tariff exposure on Class III implantable devices creates cost pass-through pressure for Saudi SFDA-registered products. Distribution runs through authorized dealer networks with biomedical engineering capabilities, bypassing standard pharmaceutical wholesale channels for device installation and programming support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA's 2023 cybersecurity mandate for implantable urological devices erects a compliance moat that favors incumbents with established encrypted telemetry architectures, raising capital barriers for entrants lacking legacy product redesign capabilities.
For Market Incumbents: To counter generic anticholinergic saturation in North African markets, Astellas Pharma Inc should deepen backward integration into regional API sourcing through Egyptian EDA manufacturing incentives, while Medtronic Plc must expand technical service headcount across Gulf hospital networks to defend neuromodulator contract renewals against pricing pressure from procurement consortia. For New Entrants and Emerging Players: Telemedicine-integrated urodynamics platforms offer the most penetrable entry vector into Kenya and Nigeria's clinic networks, bypassing capital-intensive cystometry equipment requirements. A direct-to-clinic software licensing model with revenue-sharing diagnostics enables market access without establishing physical distribution infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional generic manufacturers with Egyptian EDA tax-advantaged production capacity serving Levant and North African oral therapy demand. Watch for SFDA harmonization progress with Gulf standardization initiatives as the inflection signal for cross-border neuromodulator reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Cybersecurity Compliance Pathway | Encrypted telemetry redesign unlocks Saudi tertiary hospital procurement for neuromodulator systems. |
| Egypt EDA Local Manufacturing Incentive | Tax-advantaged regional production captures North African oral therapy substitution demand. |
| Telemedicine-Urodynamics Platform Launch | Remote diagnostic penetration addresses cystometry equipment scarcity in sub-Saharan clinics. |
| Gulf Hospital Procurement Consortium Partnership | Direct technical service agreements secure sacral neuromodulator volume commitments. |
| South African Private Reimbursement Strategy | Netcare and Mediclinic formulary inclusion drives beta-3 agonist premium positioning. |
Research Methodology
Multi-period observation of SFDA registration timelines, SAHPRA approval patterns, and Gulf hospital procurement contract awards anchored the trend analysis, supplemented by interviews with urology department heads, biomedical engineering directors, GPO contracts managers, and pharmaceutical regulatory affairs leads across Saudi Arabia, UAE, South Africa, and Egypt. Secondary validation drew from SFDA device registration databases, EDA pharmaceutical manufacturing incentive filings, hospital procurement disclosure records, and clinical trial registries. Bottom-up patient population modeling and top-down healthcare expenditure triangulation converged on segment sizing.
Segment-weighting across pharmacological mechanism, delivery technology, care setting, and regional regulatory cluster shaped the analytical framework across the projection horizon. CAGRs were derived from procedure volume trajectories and pricing elasticity assumptions specific to implantable device and pharmaceutical therapeutic categories. Forecast inputs incorporated neuromodulator implantation rates in Gulf tertiary centers and oral therapy substitution patterns in North African retail pharmacy channels.
Inputs from SFDA registration databases and South African private hospital procurement records were available through the study window; gaps in Egyptian EDA manufacturing volume disclosures and Nigerian national health expenditure data introduce uncertainty bands around North African market sizing. Forecasts reflect documented assumptions regarding regulatory harmonization progress and reimbursement expansion timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Urethral Stricture Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
Catheter-Associated Urinary Tract Infections Treatment Market
Urology
Cystectomy Market
Urology
Acquired Cystic Kidney Disease Treatment Market
Urology
Urinary Incontinence Market
Urology
Hematuria Treatment Market
Urology
Transrectal Ultrasound Market
Urology
Urinary Incontinence Treatment Drugs Market
Urology
Benign Prostatic Hyperplasia Market
Urology
Urinary Catheters Market
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market
Urology
Ureterorenoscopes Market
Urology
Global Prostate Health Market
Urology
Urology Laser Fibers Market
Urology
Global Prostate Cancer Market