
 LAMEA Transrectal Ultrasound Market | 2026-2036
LAMEA Transrectal Ultrasound Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Transrectal Ultrasound Market Insights
ANVISA's updated medical device vigilance framework is rebalancing procurement standards across Brazil, Argentina, and Mexico. GE Healthcare leverages its installed base of diagnostic imaging platforms to sustain service revenue streams across Latin American hospital networks. Siemens Healthineers anchors its position through localized technical training programs for urology specialists. Koninklijke Philips N.V. competes on integrated workflow solutions that connect transrectal ultrasound to pathology information systems.
Transrectal ultrasound employs high-frequency sound waves emitted from a rectally inserted probe to generate real-time images of the prostate gland, typically operating at 5–10 MHz for optimal tissue resolution. The modality serves primarily for prostate cancer detection, biopsy needle guidance, and seminal vesicle assessment in male infertility workups. Ultrasound Probes command the largest product category share due to replacement cycles and probe-specific sterilization protocols, while 4D Ultrasound technology captures the fastest expansion as urologists demand real-time three-dimensional visualization with temporal motion analysis for targeted biopsy procedures. Software Solutions increasingly concentrate margin pools through AI-assisted lesion segmentation and automated prostate volume calculation.
ANVISA governs device registration and post-market surveillance in Brazil, while South Africa's Health Products Regulatory Authority sets electromagnetic compatibility and clinical safety benchmarks for imported imaging systems. The South African Health Products Regulatory Authority mandates local adverse event reporting, which shapes distributor selection and technical service commitments for equipment suppliers. Stakeholders must monitor evolving reimbursement pathways for prostate cancer screening across national health systems and private insurance networks to anticipate capital equipment purchasing cycles.
Market Dynamics
ANVISA's tightened medical device vigilance framework is compressing procurement timelines across Brazilian hospital networks while accelerating local certification requirements for ultrasound manufacturers.
Growth Catalysts
- Biopsy guidance demand:Urology clinics across Latin America are expanding transrectal ultrasound deployment for prostate cancer screening protocols, particularly in Brazil's expanding private healthcare network.
- AI-assisted software:Automated prostate volume calculation and lesion segmentation tools are shortening diagnostic workflows in South African public oncology programs.
- Public hospital procurement:South Africa's national health procurement programs are prioritizing imaging equipment allocation for oncology screening in provincial hospital networks.
Market Restraints
- Probe replacement cycles:Ultrasound probe sterilization protocols and mechanical wear drive recurring capital expenditure that strains mid-tier clinic budgets.
- Electromagnetic compliance:South Africa's Health Products Regulatory Authority mandates costly local testing for imported imaging systems, extending distributor selection timelines.
- Technical training gaps:Shortage of certified urology specialists capable of interpreting 4D ultrasound volumes limits adoption velocity outside major metropolitan centers.
Strategic Opportunities
- Argentina's diagnostic gap:Underpenetrated urology imaging infrastructure in Buenos Aires provincial networks creates whitespace for equipment vendors with localized service capabilities.
- Workflow integration:Convergence of transrectal ultrasound systems with pathology information systems enables seamless biopsy-to-diagnosis data pipelines.
- Technical training programs:Siemens Healthineers' localized urology specialist certification model demonstrates scalable channel for manufacturer-led capability building.
Industry Challenges
- ANVISA registration timelines:Brazil's medical device registration process creates 18-24 month certification delays that compress product launch windows.
- Legacy system integration:Public hospital networks in Mexico require compatibility with existing PACS infrastructure, complicating equipment replacement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Transrectal Ultrasound Market |
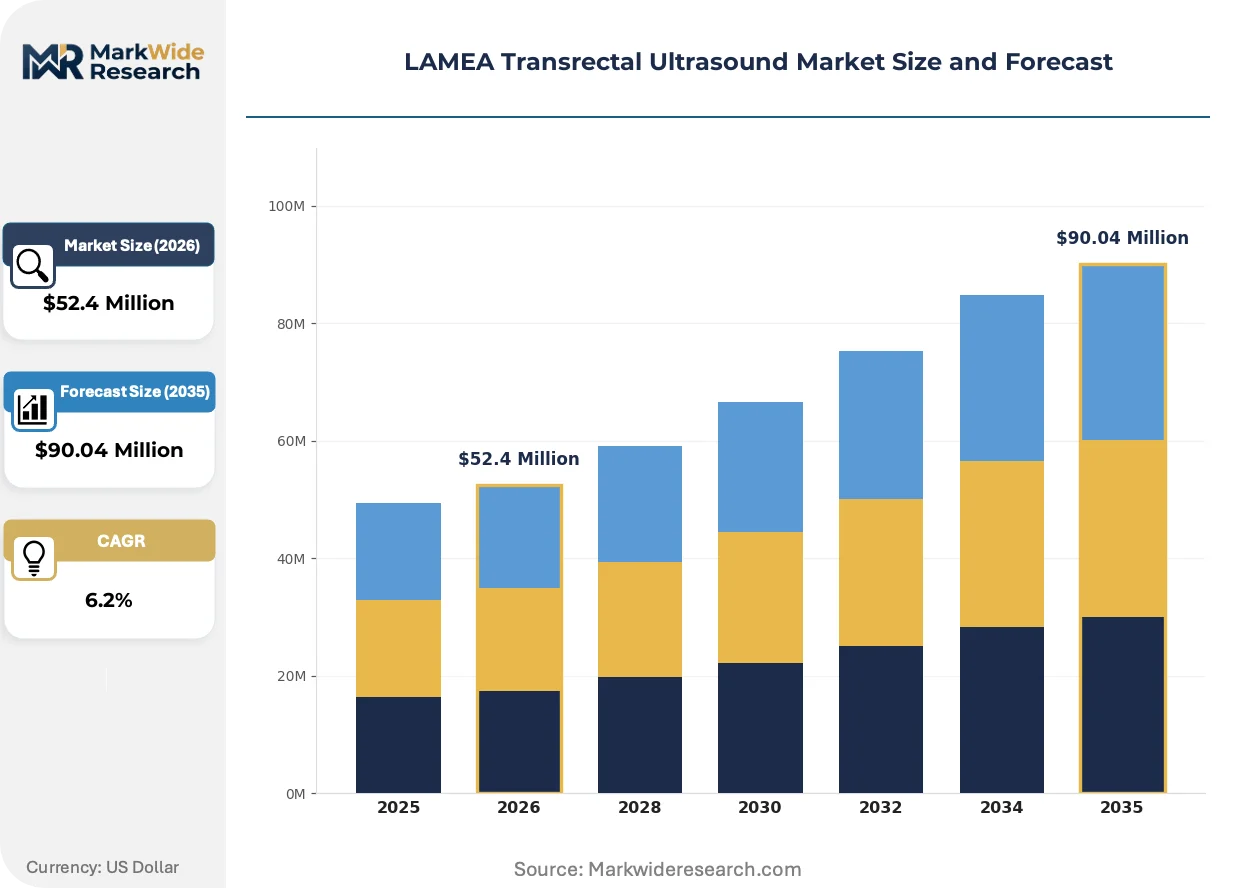
| Market Size in 2026 | $52.4 Million |
| Market Size in 2035 | $90.04 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Ultrasound Probes, Accessories, Software Solutions End User: Hospitals, Diagnostic Centers, Clinics, Research Institutions Application: Prostate Diagnosis, Biopsy Guidance, Infertility Assessment, Cancer Screening Technology: 3D Ultrasound, 4D Ultrasound, Doppler Ultrasound, Digital Imaging |
| Companies Covered | Siemens Healthineers AG, GE Healthcare, Koninklijke Philips N.V., FUJIFILM Corporation, KOELIS, Telemed Medical Systems, Exact Imaging, Mindray Medical International Limited, BK Medical Holding Company, Inc., Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Transrectal Ultrasound Market Trends and Innovations
Real-time three-dimensional visualization capabilities are compressing the gap between imaging and intervention across Latin American urology practices, while regulatory digitization reshapes equipment approval pathways.
4D ultrasound technology is expanding into targeted biopsy procedures across Brazilian and South African tertiary care centers. Urologists in São Paulo and Johannesburg academic hospitals are adopting temporal motion analysis for lesion tracking. The modality is expanding into standard-of-care protocols previously dominated by conventional 2D imaging, compressing training requirements for new specialists.
ANVISA's updated medical device vigilance framework mandates electronic adverse event reporting and post-market surveillance for all registered ultrasound systems. Brazilian distributors must maintain local technical service commitments to retain import licenses. Equipment suppliers are responding by embedding remote diagnostic capabilities into probe systems to satisfy real-time monitoring requirements.
After-sales service unbundling is fragmenting traditional equipment procurement models across Mexican private hospital networks. Buyers in Monterrey and Guadalajara are separating hardware acquisition from maintenance contracts, pressuring vendor margin structures. This pattern is most visible in mid-tier urology clinics seeking operational flexibility without long-term vendor lock-in.
LAMEA Transrectal Ultrasound Market Segmentation
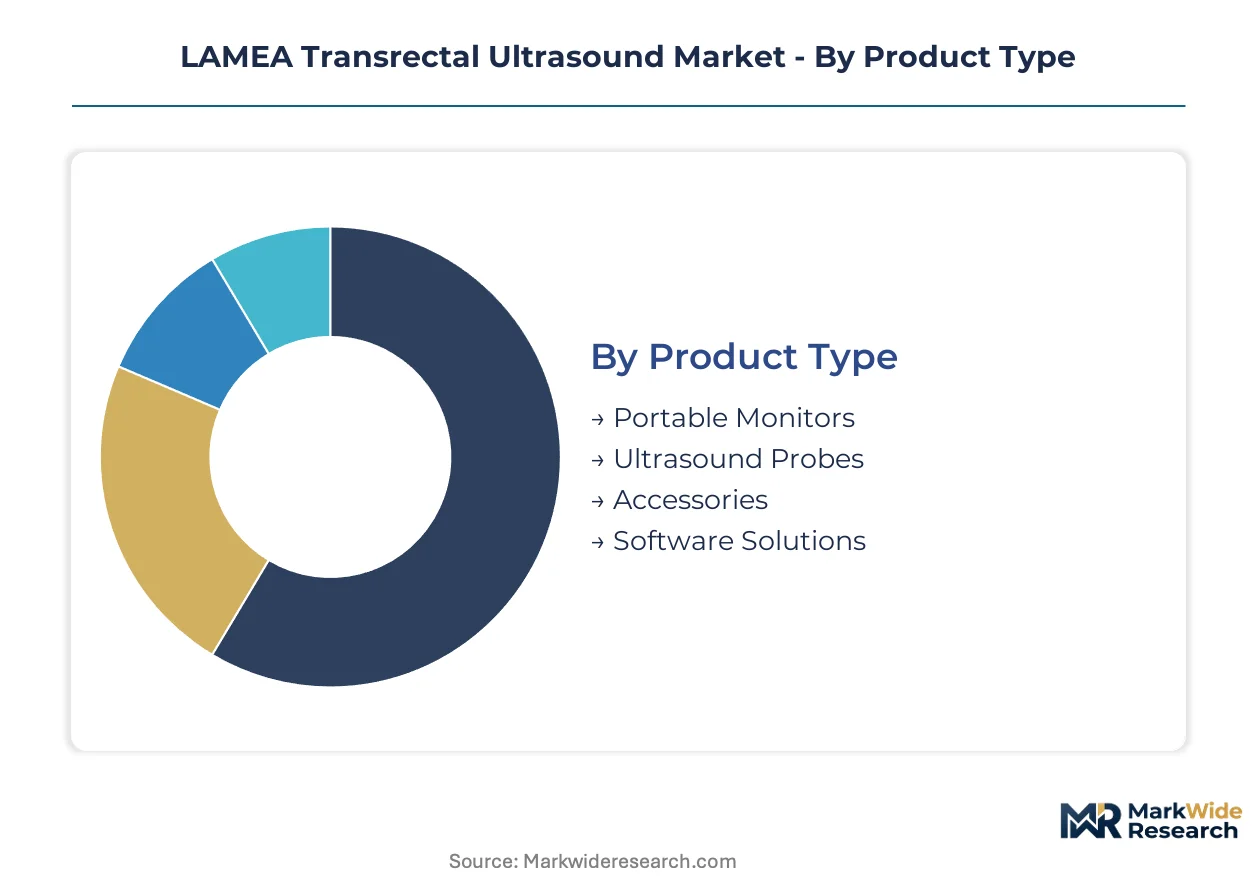
Product configuration and technology selection in transrectal ultrasound directly shape procurement economics across Brazilian and South African health systems. Segment boundaries determine where manufacturers concentrate service infrastructure and where distributors extract margin.
Product Type:
Supply concentration clusters around probe manufacturing and software development, with hardware assembly dispersing across regional contract manufacturers.
- Portable Monitors:Compact display units with integrated processing capabilities enable point-of-care deployment in mobile screening programs. Demand concentrates in South African provincial hospital networks where equipment portability supports rural oncology outreach.
- Ultrasound Probes:High-frequency transducers operating at 5–10 MHz with specialized rectal insertion geometry generate tissue-resolution images for prostate visualization. Brazilian urology clinics drive replacement demand through strict sterilization protocols and mechanical wear cycles that compress capital planning horizons.
- Accessories:Sterile probe covers, biopsy needle guides, and coupling gels complete procedural kits for single-use consumption models.
- Software Solutions:AI-assisted lesion segmentation and automated volume calculation tools capture expanding margin pools through recurring licensing structures.
Today's leader: Ultrasound Probes. Tomorrow's challenger: Software Solutions.
End User:
Procurement authority distributes across public tender systems, private hospital networks, and independent diagnostic chains with diverging technical specifications.
- Hospitals:Tertiary care centers with integrated urology departments require comprehensive imaging platforms with PACS connectivity and multi-specialty workflow integration. South Africa's public hospital procurement programs prioritize these systems for provincial oncology networks.
- Diagnostic Centers:Specialized imaging facilities concentrate prostate screening volume through dedicated urology service lines and rapid turnaround protocols.
- Clinics:Private urology practices in São Paulo and Buenos Aires deploy compact systems for biopsy guidance with emphasis on space efficiency and rapid patient throughput.
- Research Institutions:Academic medical centers in Johannesburg and Rio de Janeiro validate novel imaging biomarkers and train specialist cadres on advanced 4D visualization techniques.
Hospitals command current procurement volume. Diagnostic centers are climbing the fastest as outpatient screening protocols expand.
Application:
Clinical utility maps directly to reimbursement pathways and screening guideline adoption across national health systems.
- Prostate Diagnosis:Initial detection of prostatic hypertrophy and suspicious lesions through transrectal imaging establishes baseline clinical utility. Brazilian private health networks anchor demand through preventive screening packages.
- Biopsy Guidance:Real-time needle visualization for targeted tissue sampling reduces false-negative rates and supports active surveillance protocols. South African public oncology programs are expanding adoption to improve cancer detection yields.
- Infertility Assessment:Seminal vesicle and ejaculatory duct evaluation supports male factor infertility workups in specialized reproductive medicine centers.
- Cancer Screening:Population-level prostate cancer detection programs drive system utilization rates and equipment amortization schedules across regional hospital networks.
Biopsy guidance dominates current utilization. Cancer screening represents the steepest expansion trajectory as national programs mature.
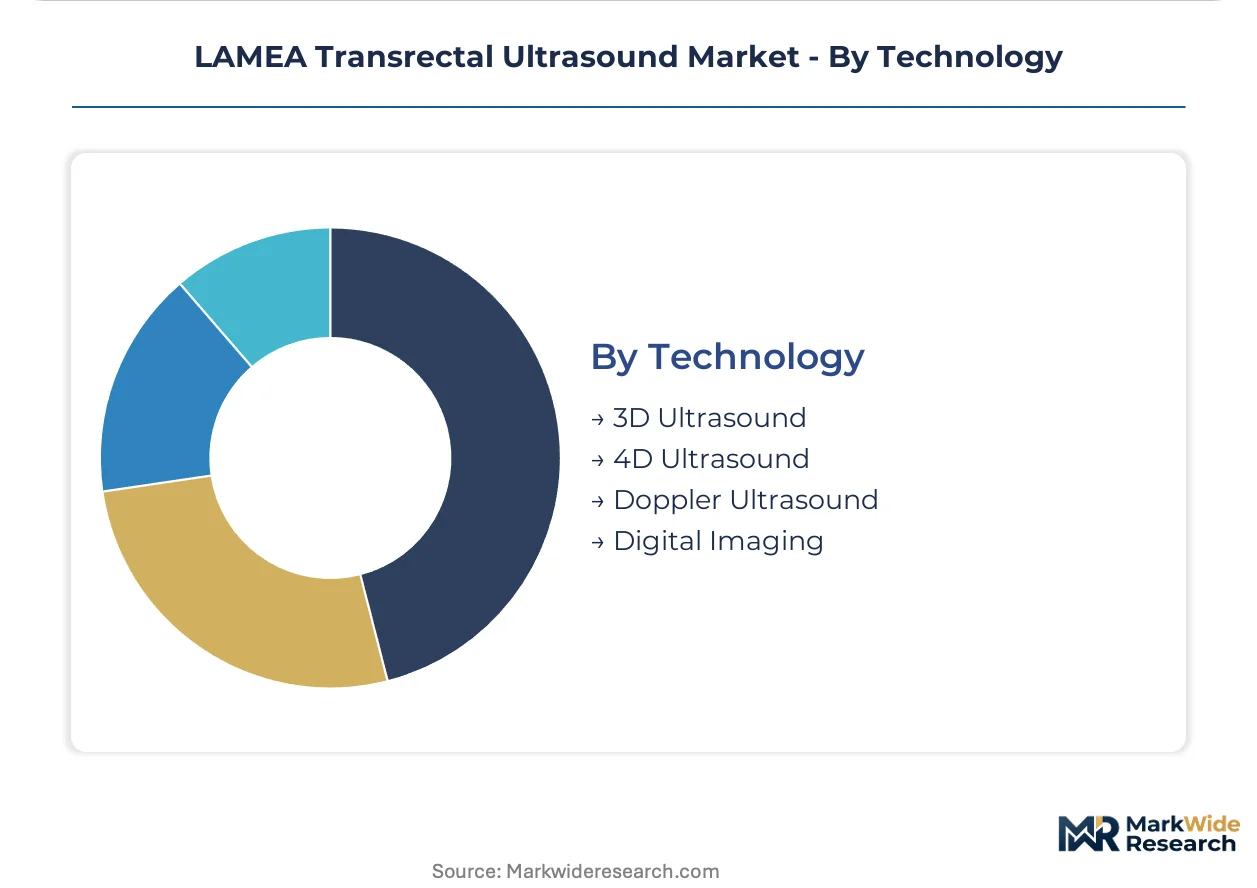
Technology:
Capability differentiation separates premium-tier equipment from standard imaging platforms through reconstruction algorithms and temporal resolution.
- 3D Ultrasound:Volumetric acquisition with multiplanar reconstruction enables offline analysis of prostatic anatomy. Mid-tier clinics in Mexico City and Santiago deploy these systems for cost-contained diagnostic workflows.
- 4D Ultrasound:Real-time three-dimensional visualization with temporal motion analysis supports targeted biopsy procedures and lesion tracking. São Paulo and Johannesburg academic hospitals are adopting this modality as standard-of-care for complex cases.
- Doppler Ultrasound:Vascular flow assessment distinguishes benign from malignant tissue through perfusion characterization.
- Digital Imaging:Raw data capture with post-processing flexibility enables AI-assisted analysis and remote diagnostic consultation.
4D Ultrasound leads technology migration. Digital Imaging is gaining share fastest through AI integration and workflow convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transrectal ultrasound technology first achieved clinical scale in European and North American urology centers during the 1980s, with Latin American and Middle Eastern adoption following through academic medical partnerships and equipment donation programs.
Brazil
Private healthcare networks in São Paulo and Rio de Janeiro are deploying 4D ultrasound systems for targeted prostate biopsy procedures. ANVISA's tightened medical device vigilance framework now mandates electronic adverse event reporting and local technical service commitments for all registered imaging equipment. The São Paulo metropolitan corridor concentrates procurement volume as tertiary care centers upgrade from conventional 2D platforms.
South Africa
Public hospital procurement programs are prioritizing imaging equipment allocation for provincial oncology screening networks in Gauteng and KwaZulu-Natal. The Health Products Regulatory Authority mandates electromagnetic compatibility testing and local adverse event reporting for imported systems, extending distributor selection timelines. Johannesburg academic medical centers are validating 4D visualization techniques for complex lesion tracking cases.
Mexico
Mid-tier urology clinics in Monterrey and Guadalajara are unbundling after-sales service from hardware acquisition to gain operational flexibility. The national health system requires compatibility with existing PACS infrastructure, complicating equipment replacement decisions in public hospital networks. Mexico City diagnostic chains are expanding dedicated prostate screening service lines with rapid turnaround protocols.
Argentina
Buenos Aires provincial networks present underpenetrated urology imaging infrastructure with whitespace for vendors offering localized service capabilities. The national pharmaceutical and medical device regulator maintains import licensing requirements that favor distributors with established technical support operations. Private urology practices in the capital region are deploying compact systems emphasizing space efficiency and patient throughput.
Saudi Arabia
The Saudi Food and Drug Authority governs medical device registration and post-market surveillance for ultrasound systems entering the Kingdom's healthcare modernization programs. Tertiary care centers in Riyadh and Jeddah are integrating transrectal ultrasound into population-level prostate cancer detection initiatives. Diagnostic networks in the Eastern Province are expanding dedicated urology service lines to support screening guideline adoption.
LAMEA Transrectal Ultrasound Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration and service bundling dimensions in the LAMEA transrectal ultrasound market. The competitive structure organizes around three archetypes: diversified imaging conglomerates with established service infrastructure, specialized urology equipment manufacturers with focused R&D pipelines, and emerging Asian manufacturers competing on hardware cost structures. Dominant competitive moves include workflow integration partnerships linking ultrasound platforms to pathology information systems, and localized technical training programs building specialist capability in target markets.
Among diversified imaging conglomerates, Siemens Healthineers AG and GE Healthcare exemplify the premium-tier archetype through their installed base leverage and service revenue streams across Latin American hospital networks. Koninklijke Philips N.V. occupies a position emphasizing integrated workflow solutions. These three companies represent the established competitive core against which specialized manufacturers and cost-focused entrants must differentiate.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE Healthcare |
| Koninklijke Philips N.V. |
| FUJIFILM Corporation |
| KOELIS |
| Telemed Medical Systems |
| Exact Imaging |
| Mindray Medical International Limited |
| BK Medical Holding Company, Inc. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between ANVISA-registered premium systems and non-certified economy imports splits procurement economics across Brazilian and South African health networks, concentrating margin capture with distributors holding local technical service licenses while compressing hardware margins for unbundled equipment sales.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors Brazilian procurement, with premium tiers commanding service-bundled contracts from São Paulo tertiary centers while economy tiers serve provincial clinics in Mexico and Argentina. Price differentiation rests on ANVISA registration status and 4D imaging capability, with certified systems carrying 40-60% service premiums. Cost compression in the economy tier intensifies as Asian manufacturers displace legacy 2D platforms. Public hospital procurement committees in South Africa exhibit highest price sensitivity; private diagnostic chains in Monterrey demonstrate lowest sensitivity due to rapid patient throughput economics.
Supply Chain Analysis
Freight costs from Asian manufacturing hubs to LAMEA distribution centers consume 8-12% of landed equipment value, with Brazilian port congestion adding inventory carrying penalties. Probe transducer assembly concentrates in China, Malaysia, and South Korea, while software development localizes in Israel and the United States. Piezoelectric crystal supply hinges on rare earth processing concentration in China. Single-source vulnerability in high-frequency transducer ceramics threatens replacement part availability. Distribution runs through authorized distributors with ANVISA technical service commitments rather than direct manufacturer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LAMEA transrectal ultrasound market represents a late-cycle quality story where urology clinics are upgrading from conventional 2D to 4D imaging platforms despite capital constraints, prioritizing biopsy guidance accuracy over equipment cost.
For Market Incumbents: Hedge against margin erosion in hardware sales by expanding software licensing revenue through AI-assisted lesion segmentation tools. Deepen backward integration into probe refurbishment capabilities to capture replacement cycle economics. Defend against emerging Asian cost competitors by embedding remote diagnostic capabilities that satisfy ANVISA real-time monitoring requirements. For New Entrants and Emerging Players: Distributors with established provincial hospital relationships in Buenos Aires and Johannesburg present the fastest path to revenue. Target underpenetrated urology imaging infrastructure in Argentina's provincial networks where localized service capabilities remain scarce. Enter through compact portable monitor configurations that bypass PACS integration complexity facing premium-tier competitors. For Investors and Strategic Acquirers: Consolidation pressure builds where software-enabled workflow integration separates premium vendors from commodity hardware suppliers. Five-to-ten year viability favors manufacturers with recurring revenue streams from AI-assisted diagnostic tools rather than pure equipment sales. Acquisition targets should demonstrate installed base leverage with ANVISA-registered service infrastructure. Monitor ANVISA registration timeline compression as inflection signal for competitive entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Pathway | Electronic adverse event reporting mandates reshape distributor technical service commitments across Brazil. |
| Hospital System Partnership | South Africa's provincial oncology networks prioritize imaging allocation through integrated procurement programs. |
| Software Companion Development | AI-assisted prostate volume calculation tools capture expanding margin pools through recurring licensing. |
| Workflow Integration | Pathology information system connectivity enables seamless biopsy-to-diagnosis data pipelines in São Paulo. |
| Technical Training Certification | Localized urology specialist programs build capability gaps limiting 4D adoption outside metropolitan centers. |
Research Methodology
Coverage spans Latin America, Middle East, and Africa with primary inputs from each regional cluster, combining structured interviews with urology specialists, hospital procurement managers, biomedical engineers, and distributor technical service heads with secondary validation from ANVISA registration databases, South African Health Products Regulatory Authority filings, hospital procurement tenders, and GPO contract disclosures. Bottom-up equipment shipment tracking triangulates against top-down health expenditure allocation models.
Granularity-level modeling disaggregates volume and value across product type, end user, application, and technology dimensions with country-level calibration for Brazil, South Africa, Mexico, Argentina, and Saudi Arabia. CAGRs derive from regression-adjusted trend extrapolation incorporating replacement cycle dynamics and screening guideline adoption curves. Forecast inputs include ANVISA registration pipeline data, provincial hospital budget allocation patterns, and 4D imaging adoption velocity in academic medical centers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to reimbursement pathway changes for prostate cancer screening and electromagnetic compliance testing cost shifts in South Africa. A model refresh is warranted upon material change in ANVISA medical device vigilance framework implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Varicocele Treatment Market
Urology
Urinary Bag Market
Urology
Ureteral Catheters Market
Urology
Global Prostate Cancer Market
Urology
Urology Laser Fibers Market
Urology
Global Bladder Cancer Market
Urology
Global Bladder Scanner Market
Urology
Acute Pyelonephritis Treatment Market
Urology
Global Hydronephrosis Market
Urology
Benign Prostatic Hyperplasia Market
Urology
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
Self-Intermittent Catheters Market
Urology
Cystectomy Market