
 Latin America Incontinence Pads Market | 2026-2036
Latin America Incontinence Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Incontinence Pads Market Intelligence
Nursing specialization in geriatric continence management is rotating toward community-based care models across Latin America, tightening institutional staffing and redirecting product demand toward home-use formats. Kimberly-Clark Corp leverages its regional manufacturing footprint to sustain price competitiveness in pharmacy and supermarket channels. Essity AB anchors its position through R&D intensity in skin-friendly absorbent materials. Ontex Group NV specializes in private-label partnerships that dominate retail store shelves across Mexico and Central America.
Latin America incontinence pads are absorbent hygiene products engineered with superabsorbent polymer cores, acquisition distribution layers, and breathable backsheet films designed to capture and isolate urinary output while maintaining skin integrity. Their primary commercial purpose centers on enabling mobility, dignity, and infection prevention among individuals with temporary or chronic bladder control impairment. Disposable pads command the dominant revenue share due to convenience preferences among institutional buyers, while reusable pads capture growing traction among environmentally conscious consumers in higher-income urban centers. Elderly care applications generate the deepest margin pools as post-acute and long-term facilities prioritize premium performance tiers, though home care delivery models are expanding fastest among individual users seeking discreet subscription replenishment.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia each enforce distinct medical device registration pathways that shape product labeling, clinical substantiation requirements, and market entry timelines for imported and locally manufactured pads. These frameworks elevate compliance costs for new entrants while rewarding established operators with validated quality systems and in-country technical documentation. Stakeholders must monitor evolving reimbursement discussions in Brazil's SUS system and private health plans, as coverage expansion for home-based continence supplies would fundamentally reshape volume distribution between institutional and retail channels.
Market Dynamics
ANVISA's 2024 medical device reclassification for absorbent hygiene products is forcing manufacturers to rebuild quality management systems and clinical documentation from the ground up, compressing margins for smaller Brazilian operators while advantaging multinationals with pre-existing ISO 13485 infrastructure.
Growth Catalysts
- Geriatric home care migration:Brazil's aging demographic is rotating care delivery from institutional facilities toward residential settings, expanding addressable volume for discreet, individually packaged pad formats.
- ANVISA compliance acceleration:The regulator's tightened technical documentation requirements are filtering out informal importers and consolidating shelf space for validated manufacturers with in-country testing capabilities.
- Superabsorbent polymer advances:Next-generation sodium polyacrylate formulations with improved retention under pressure are enabling thinner product profiles that reduce shipping cube and storage costs for distributors.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyethylene prices track Brent crude movements, exposing Brazilian converters to margin compression when naphtha spreads widen without corresponding finished goods pricing power.
- Southeast regional supply concentration:São Paulo state hosts over 70 percent of domestic absorbent hygiene manufacturing, creating hurricane and logistics disruption exposure for national distribution networks.
- Reimbursement fragmentation:Brazil's SUS system offers patchy coverage for home-use continence supplies, forcing elderly consumers to absorb full out-of-pocket costs and capping volume expansion in lower-income segments.
Strategic Opportunities
- Colombia's Pacific coast expansion:Cali and Medellín urban corridors show underpenetrated pharmacy distribution relative to demographic age profiles, offering first-mover shelf positioning for compliant entrants.
- Subscription direct-to-consumer channels:E-commerce replenishment models with discrete packaging are capturing higher lifetime value from mobile-enabled caregivers managing parental incontinence.
- COFEPRIS fast-track harmonization:Mexico's regulator is piloting synchronized review pathways with ANVISA, potentially compressing multi-country registration timelines for manufacturers with regional headquarters.
Industry Challenges
- Continence nurse certification gaps:Community-based care models require specialized wound and skin integrity training that outpaces current vocational program output across Brazil and Mexico.
- Legacy ERP integration friction:Family-owned distributors in Central America face multi-year SAP or Oracle transitions to meet traceability mandates under evolving medical device regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Incontinence Pads Market |
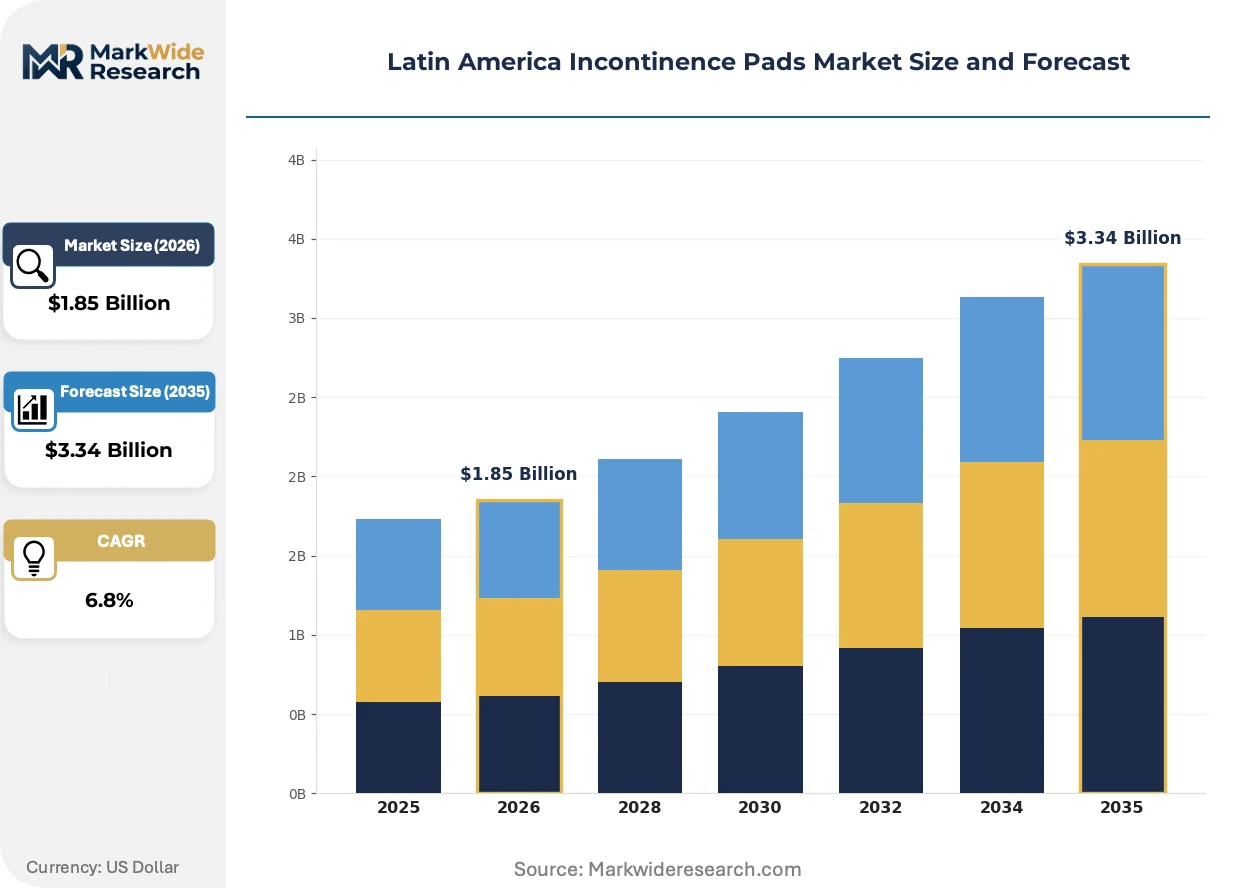
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Pads, Reusable Pads, Overnight Pads, Male Pads Distribution Channel: Retail Stores, Online Platforms, Pharmacies, Supermarkets End User: Hospitals, Nursing Homes, Home Care, Individual Users Application: Daytime Use, Nighttime Use, Postpartum Care, Elderly Care |
| Companies Covered | Kimberly-Clark Corp, Essity AB, Procter & Gamble Co, Ontex Group NV, Cardinal Health Inc, Paul Hartmann AG, Medline Industries, First Quality Enterprises, Drylock Technologies NV, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Incontinence Pads Market Strategic Shifts & Innovations
Material science convergence with digital health monitoring is redefining performance benchmarks across Latin American absorbent hygiene, while regulatory harmonization pressures and channel fragmentation are forcing simultaneous adaptation on multiple operational fronts.
Biodegradable superabsorbent polymers derived from modified starch matrices are decomposing the traditional petroleum-based supply chain for core materials. Premium-tier manufacturers in São Paulo and Monterrey are piloting these inputs for eco-labeled product lines targeting pharmacy chains with sustainability procurement criteria. The structural consequence is decomposing cost advantages for incumbent petrochemical-dependent producers as carbon accounting penetrates institutional tender requirements.
ANVISA's updated Resolução da Diretoria Colegiada framework for medical device classification is elevating clinical substantiation burdens for imported pads. Foreign manufacturers must now submit Brazilian-specific biocompatibility testing rather than relying on FDA or CE documentation alone. Mid-sized Central American private-label exporters face the steepest compliance timeline extensions, with some redirecting volume toward Mexican COFEPRIS registration as a regional beachhead.
Subscription-based replenishment platforms are capturing caregiver loyalty through predictive algorithms that anticipate consumption patterns. São Paulo's dense urban corridor hosts the most mature pilot programs, with pharmacy chains unbundling traditional wholesale relationships to own the customer data layer. Colombia's emerging middle-class elderly population represents the next geography where mobile-enabled ordering is displacing monthly supermarket stock-up behavior.
Latin America Incontinence Pads Market Segmentation
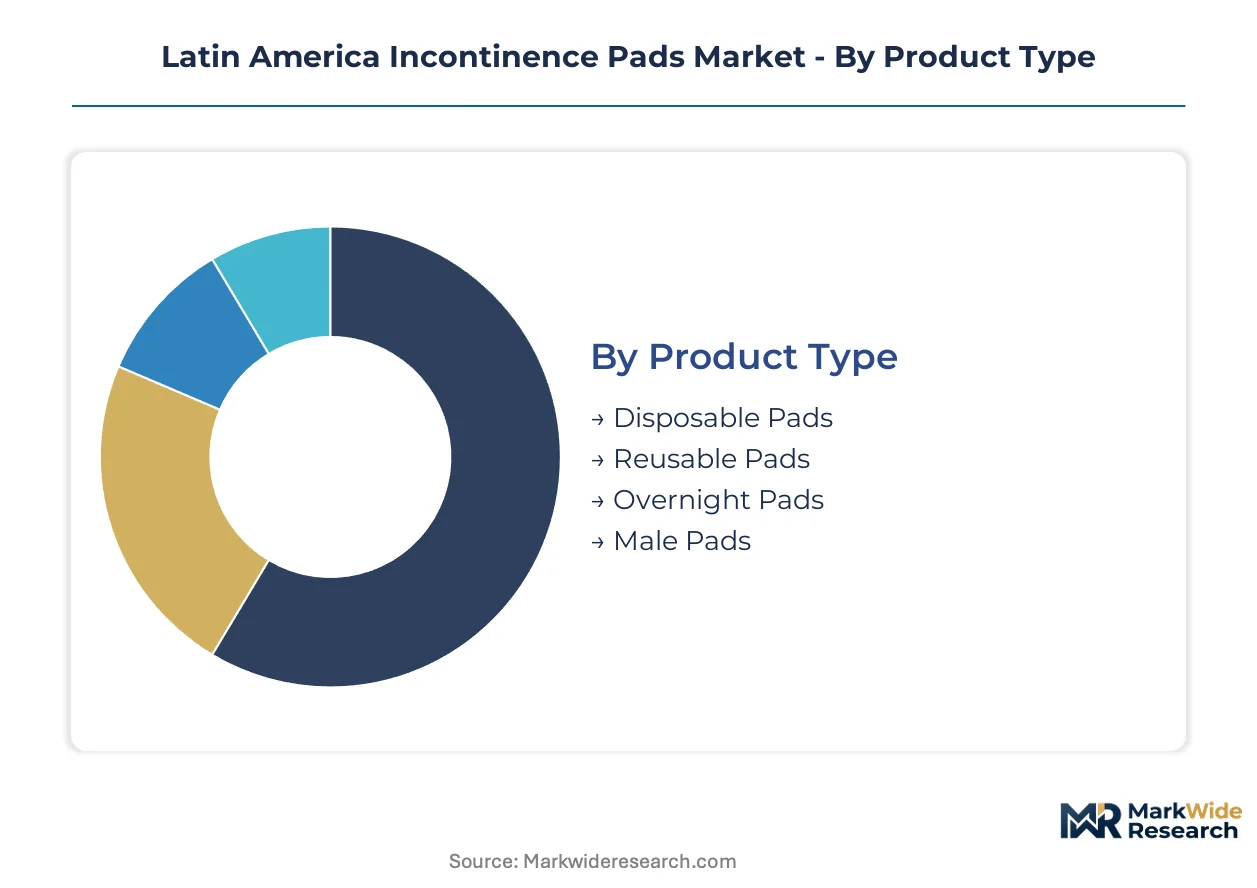
Product differentiation across Latin America's incontinence pads market tracks divergent care settings and purchasing behaviors. Manufacturers must align formulation, packaging, and channel strategy to each segment's clinical requirements and price sensitivity.
Product Type:
Disposable pads dominate Brazilian and Mexican domestic production, while reusable formats gain traction through Central American export channels targeting eco-conscious European buyers.
- Disposable Pads:Superabsorbent polymer cores with acquisition distribution layers deliver rapid fluid lock under pressure. São Paulo's institutional procurement concentrates demand for high-capacity formats in nursing homes and post-acute facilities, though ANVISA's tightened biocompatibility documentation is extending registration timelines for new entrants.
- Reusable Pads:Cotton-blend absorbent layers with waterproof polyurethane laminate backings support 200+ wash cycles. Colombian urban centers show emerging caregiver preference for home-laundered alternatives, driven by sustainability messaging and subscription service bundling.
- Overnight Pads:Extended-length designs with reinforced leakage barriers for supine positioning.
- Male Pads:Anatomically contoured shields with targeted front absorption zones.
Disposable pads command the established base. The steepest expansion runs through reusable pads.
Distribution Channel:
Channel economics split between high-touch pharmacy counseling for first-time users and automated replenishment for established caregivers, with cost-to-serve varying threefold across the matrix.
- Retail Stores:Shelf placement fees and promotional slotting contracts absorb 12-18% of wholesale value in Mexico's consolidated retail landscape. Ontex Group's private-label partnerships with Grupo Bimba and Chedraui dominate visibility in Monterrey and Guadalajara metropolitan zones.
- Online Platforms:Predictive algorithms and discrete packaging capture recurring revenue from mobile-enabled caregivers managing parental incontinence. São Paulo's pharmacy chains are unbundling wholesale relationships to own customer data layers directly.
- Pharmacies:Pharmacist consultation drives trial conversion among embarrassed first-time purchasers.
- Supermarkets:Monthly stock-up behavior persists among price-sensitive elderly consumers in Brazil's Northeast.
Retail stores anchor volume throughput. Online platforms are climbing the fastest.
End User:
End-user segmentation reflects Brazil's rotating care delivery models, with home care expanding at triple the rate of institutional bed growth.
- Home Care:Individually wrapped discreet formats with odor-neutralizing topsheets support dignity preservation in residential settings. Brazil's Southeast region generates the densest demand clusters, where São Paulo's urban corridor enables same-day delivery from pharmacy distribution centers.
- Nursing Homes:Bulk packaging and wetness indicators reduce per-change labor costs in post-acute facilities. Margin compression from SUS reimbursement caps is forcing procurement officers toward standard-tier products despite clinical preference for premium absorbency.
- Hospitals:Acute care discharge protocols drive short-duration pad utilization.
- Individual Users:Out-of-pocket purchasing dominates where public reimbursement gaps persist.
Nursing homes command the established base. Home care is gaining share fastest.
Application:
Application-driven formulation separates daytime mobility-optimized designs from nighttime capacity-focused architectures, with elderly care commanding premium pricing power.
- Elderly Care:Skin-friendly materials with pH-buffering topsheets prevent moisture-associated skin damage in aged populations with compromised epidermal barriers. Colombia's INVIMA registration requirements for geriatric-specific claims are elevating clinical substantiation costs above general-purpose alternatives.
- Nighttime Use:Higher total absorbency capacity with reinforced leg gathers manages extended wear intervals. Mexican nursing facilities report 40% lower nighttime change frequency with premium overnight formats, justifying per-unit price premiums despite budget pressure.
- Daytime Use:Thin profiles prioritize discretion under clothing for ambulatory users.
- Postpartum Care:Hospital discharge kits introduce product trial among younger demographics.
Daytime use commands the established base. Elderly care is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Southeast corridor consumes incontinence pads through institutional procurement channels, while Mexico's retail pharmacy networks dominate individual purchasing patterns across urban centers. Colombia's Pacific coast cities show underpenetrated distribution relative to demographic age profiles, creating divergent growth trajectories across the region.
Brazil
São Paulo's dense urban corridor anchors both nursing home procurement and direct-to-consumer subscription models for discreet home delivery. ANVISA's 2024 medical device reclassification forces manufacturers to rebuild quality management systems and clinical documentation from the ground up. The state's concentration of over 70 percent of domestic absorbent hygiene manufacturing creates logistics disruption exposure for national distribution networks.
Mexico
Monterrey and Guadalajara metropolitan zones drive pharmacy chain consolidation with private-label partnerships dominating retail shelf visibility. COFEPRIS is piloting synchronized review pathways with ANVISA, potentially compressing multi-country registration timelines for manufacturers with regional headquarters. The Bajío Region's manufacturing clusters support cost-competitive production for Central American export channels.
Colombia
Cali and Medellín urban corridors show underpenetrated pharmacy distribution relative to demographic age profiles, offering first-mover shelf positioning for compliant entrants. INVIMA enforces distinct medical device registration pathways that shape product labeling and clinical substantiation requirements for imported pads. Bogotá's institutional procurement officers prioritize premium performance tiers despite budget pressure from reimbursement fragmentation.
Argentina
Buenos Aires metropolitan demand concentrates among aging populations seeking dignified management solutions through retail pharmacy channels. The country's national pharmaceutical regulator maintains import registration requirements that extend market entry timelines for foreign manufacturers. Córdoba's industrial corridor hosts emerging local converters targeting price-sensitive segments with standard-tier formulations.
Chile
Santiago's urban elderly population drives subscription-based replenishment platforms capturing caregiver loyalty through predictive algorithms. The country's national medical device regulator enforces biocompatibility testing requirements that elevate compliance costs above general-purpose alternatives. Valparaíso's port infrastructure supports import-dependent supply chains for premium-tier products targeting higher-income households.
Latin America Incontinence Pads Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in Latin America's incontinence pads market. Multinational manufacturers with pre-existing ISO 13485 infrastructure capture disproportionate shelf space as ANVISA compliance filters out informal importers. Strategic archetypes divide between petrochemical-integrated volume players and skin-friendly material specialists. Competitive moves center on backward integration into superabsorbent polymer supply and pharmacy chain data partnerships.
Within the integrated multinational tier, Kimberly-Clark Corp and Essity AB exemplify archetypes of regional manufacturing footprint leverage and R&D intensity in absorbent materials respectively. Ontex Group NV occupies a position representing private-label partnership specialists that dominate retail store shelves across Mexico and Central America. These three anchors sit within distinct competitive vectors—cost competitiveness, material innovation, and retail channel control—that define the market's strategic geometry.
| Leading Market Players |
|---|
| Kimberly-Clark Corp |
| Essity AB |
| Procter & Gamble Co |
| Ontex Group NV |
| Cardinal Health Inc |
| Paul Hartmann AG |
| Medline Industries |
| First Quality Enterprises |
| Drylock Technologies NV |
| Others |
Cost & Logistics Intelligence
São Paulo's concentration of over 70 percent of domestic absorbent hygiene manufacturing creates scale economies that compress unit costs for validated producers while elevating entry barriers for smaller operators lacking ISO 13485 infrastructure. This geographic clustering simultaneously anchors price floors through logistics efficiency and exposes national distribution networks to single-point disruption risks.
Pricing Analysis
Long-term offtake agreements between São Paulo converters and petrochemical suppliers dominate raw material procurement, insulating tier-one manufacturers from spot market volatility in polypropylene and polyethylene. Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-validated clinical-grade products from private-label alternatives and informal imports. Cost compression in standard-tier segments is intensifying because nursing home procurement officers face SUS reimbursement caps. Home care subscribers show lowest price sensitivity due to dignity-driven preference for discreet, individually wrapped formats.
Supply Chain Analysis
Brazil and Mexico anchor superabsorbent polymer conversion and finished pad assembly for Latin American consumption, with Colombian distributors increasingly sourcing through Medellín logistics hubs. Core inputs draw from Saudi Arabian and Asian petrochemical suppliers for sodium polyacrylate resin, while breathable backsheet films rest on German and Japanese specialty polymer producers. Single-source vulnerability concentrates in São Paulo state's manufacturing corridor, where hurricane and logistics disruption exposure threatens national fulfillment. Distribution runs through pharmacy chain consolidation in Monterrey and Guadalajara, supermarket monthly stock-up behavior in Brazil's Northeast, and emerging subscription platforms in Santiago and São Paulo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across Latin America's incontinence pads market as home care delivery models outpace institutional bed growth, creating niches for specialized service layers that incumbents under-serve.
For Market Incumbents: Secure backward integration into biodegradable superabsorbent polymer supply chains before carbon accounting penetrates institutional tender requirements. Anchor pharmacy chain data partnerships in São Paulo and Monterrey to capture recurring-revenue conversion from mobile-enabled caregivers, defending against subscription platform disintermediation. For New Entrants and Emerging Players: Caregiver education and skin-integrity consultation services represent underexploited white space where incumbents focus on product volume over clinical support. Target Colombia's Pacific coast cities through INVIMA-compliant direct-to-consumer launches, leveraging first-mover shelf positioning in Cali and Medellín pharmacy networks before consolidated retail captures share. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-platform operators with predictive replenishment algorithms and discrete packaging capabilities. Five-to-ten year viability favors acquisition targets with validated ANVISA quality systems and established private-label relationships across Central American retail. Monitor ANVISA-COFEPRIS harmonization pilot outcomes as inflection signal for multi-country registration timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biodegradable SAP Supply | Captures carbon-accounting premium as Brazilian institutional tenders adopt sustainability criteria. |
| Pharmacy Chain Data Partnership | Owns customer consumption patterns in São Paulo's dense urban corridor ahead of wholesale unbundling. |
| INVIMA Fast-Track Registration | Accelerates shelf positioning in Colombia's underpenetrated Pacific coast cities before competitor consolidation. |
| Subscription Platform Launch | Converts mobile-enabled caregivers to recurring revenue with predictive algorithms and discreet packaging. |
| COFEPRIS-ANVISA Harmonization Alignment | Compresses multi-country registration timelines for manufacturers with regional headquarters in Monterrey. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across nursing home procurement officers, pharmacy chain category managers, biomedical engineers specializing in absorbent materials, and ANVISA regulatory affairs specialists. Secondary validation drew from ANVISA medical device registration databases, COFEPRIS approval filings, INVIMA import records, and São Paulo state industrial production statistics. Bottom-up volume modeling triangulated against top-down macroeconomic projections across the analysis window.
Across the analysis window, forecasts segmented by product type, distribution channel, end-user setting, and application severity integrated demographic aging trajectories, reimbursement policy scenarios, and superabsorbent polymer technology diffusion curves. CAGRs derived from regression analysis of historical volume trends against projected care-delivery model shifts. Industry-specific inputs included ANVISA compliance timeline data and pharmacy channel consolidation rates in Mexico's metropolitan zones.
Forecasts assume regulatory continuity in ANVISA, COFEPRIS, and INVIMA medical device frameworks; material policy shifts in reimbursement coverage or biocompatibility testing requirements would require re-modeling. Specific risks include petrochemical input cost volatility, logistics disruption in São Paulo's manufacturing corridor, and SUS coverage expansion altering channel volume distribution. Recalibration cycles align with material shifts in regulatory harmonization progress and home care delivery model penetration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Histology and Cytology Consumables Supplies Market
Medical Supplies
Japan Hospital Supplies Market
Medical Supplies
Tattoo Needles Market
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
Super Absorbent Dressings Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Western Europe Sterile Gloves Market
Medical Supplies
Micro Vials Market
Medical Supplies
Spain Hospital Supplies Market
Medical Supplies
Disposable Sanitary Pad Market
Medical Supplies
Medical Gas Market
Medical Supplies
Global Needles Market
Medical Supplies
IV Infusion Gravity Bags Market
Medical Supplies
Dehydrated Culture Media Market
Medical Supplies
Trach Care Trays Market
Medical Supplies
Europe Syringe Market