
 Antimicrobial Hospital Curtains Market | 2026-2036
Antimicrobial Hospital Curtains Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Hospital Curtains Market Analysis
AAMI PB70 liquid barrier classification is bifurcating supplier eligibility between certified medical textile manufacturers and general drapery converters. Endurocide Limited leverages integrated biocide impregnation chemistry to sustain recurring hospital contracts across the United Kingdom. Elers Medical anchors its position through dedicated NHS supply chain accreditation, while Hangzhou Xiang Jun competes on manufacturing scale for vinyl-coated curtain volumes destined for Asia-Pacific procurement offices.
Antimicrobial hospital curtains are engineered textile barriers incorporating biocidal agents—typically silver-ion, quaternary ammonium, or triclosan formulations bonded to polyester or vinyl substrates—to suppress pathogen colonization on privacy surfaces in clinical environments. These products must maintain ASTM E2149 quantitative antimicrobial efficacy while delivering flame resistance per NFPA 701 and dimensional stability through commercial laundering or disposal protocols. Ceiling-mounted configurations dominate installed base across existing hospital infrastructure, while portable and folding formats represent the fastest-expanding segment as ambulatory surgical centers prioritize rapid room reconfiguration. Polyester substrates lead material selection for breathability and print compatibility, though vinyl commands margin concentration in isolation settings requiring fluid-impermeable barriers.
FDA 510(k) clearance pathways for antimicrobial device claims intersect with EPA FIFRA registration requirements for biocidal-treated articles, creating dual compliance overhead that filters smaller textile converters from hospital vendor lists. The EU Medical Device Regulation's expanded scope for products claiming infection prevention properties is redirecting European manufacturer documentation investments toward notified body engagement. Stakeholders must monitor evolving CMS hospital-acquired condition penalty schedules and Joint Commission environment-of-care standards to anticipate procurement specification shifts before contract renewal cycles.
Market Dynamics
The EPA's emerging pathogen claims framework is compressing supplier eligibility by demanding quantitative efficacy documentation that general drapery converters cannot produce, bifurcating the market between certified medical textile manufacturers and commodity producers.
Growth Catalysts
- ICU Expansion:Intensive care units across US hospital networks are expanding procurement of disposable antimicrobial privacy barriers to meet Joint Commission environment-of-care standards.
- German Mandates:Nosocomial infection protocols in German tertiary care facilities mandate frequent curtain replacement cycles, institutionalizing recurring demand.
- Silver-Ion Chemistry:Advanced silver-ion bonding to polyester substrates delivers ASTM E2149 efficacy without compromising flame resistance per NFPA 701.
Market Restraints
- Dual Compliance Overhead:FDA 510(k) clearance intersecting with EPA FIFRA registration filters smaller textile converters from hospital vendor lists.
- Raw Material Concentration:Quaternary ammonium compound supply concentrates among specialty chemical producers in China, exposing buyers to input volatility.
- Technical Limitation:Triclosan formulations face efficacy degradation through repeated commercial laundering cycles.
Strategic Opportunities
- EU MDR Expansion:The EU Medical Device Regulation's broadened scope for infection prevention claims redirects manufacturer documentation investments toward notified body engagement.
- Ambulatory Surgical Centers:Portable and folding curtain formats capture demand from ASCs prioritizing rapid room reconfiguration over fixed infrastructure.
- CMS Penalty Schedules:Evolving hospital-acquired condition penalty structures create specification-shifting leverage for vendors ahead of contract renewal cycles.
Industry Challenges
- Certification Timeline Compression:ASTM E2149 quantitative testing combined with NFPA 701 flame resistance validation extends product development cycles beyond typical hospital procurement windows.
- Legacy Infrastructure Integration:Ceiling-mounted track systems in existing hospital buildings constrain format innovation and complicate portable product adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Hospital Curtains Market |
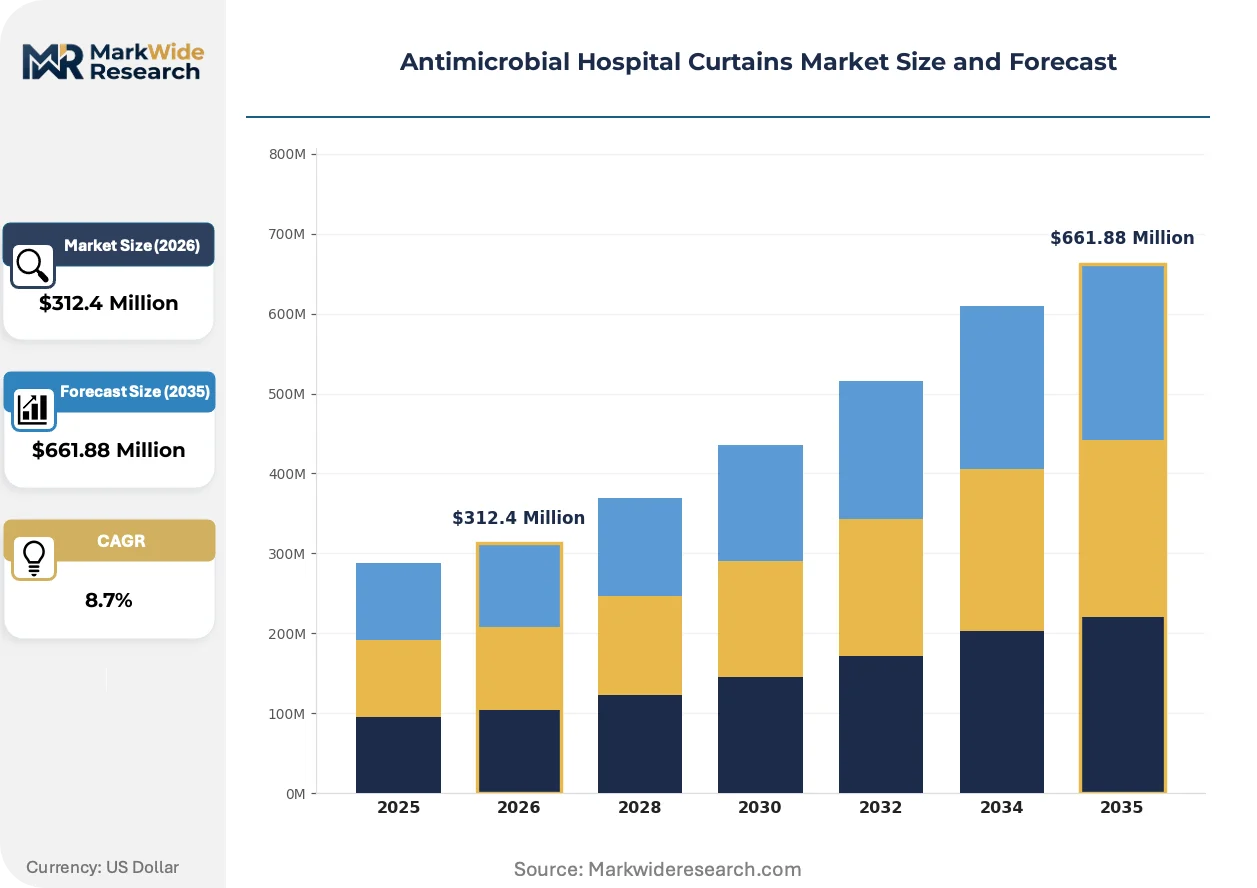
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceiling-Mounted, Wall-Mounted, Portable, Folding Material: Polyester, Vinyl, Cotton, Blended Fabrics Application: Patient Rooms, Surgical Theaters, Isolation Areas, Waiting Areas End User: Hospitals, Clinics, Rehabilitation Centers, Long-Term Care Facilities |
| Companies Covered | Endurocide Limited, Hospital Curtain Solutions, Elers Medical, National Surgical Corporation, Anglo Middle East, Hangzhou Xiang Jun, RD Plast, EcoMed Technologies, Tracks2Curtains, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Hospital Curtains Market Emerging Trajectories
Biocide impregnation chemistry is actively reshaping competitive positioning by enabling manufacturers to sustain recurring hospital contracts through efficacy durability claims rather than commodity pricing.
Photocatalytic titanium dioxide coatings is supplanting traditional silver-ion formulations in isolation settings requiring continuous pathogen suppression without chemical depletion. German tertiary care facilities are piloting these surfaces in hematology wards where immunocompromised patients demand non-stop antimicrobial activity. The technology is compressing replacement cycle economics by extending functional lifespan beyond standard disposable protocols.
REACH restrictions on persistent biocidal substances are forcing European manufacturers to reformulate quaternary ammonium bonding agents ahead of 2026 authorization deadlines. The industrial consequence is a documentation burden shift toward ECHA substance evaluation dossiers that smaller converters cannot sustain. Medical textile specialists with dedicated regulatory affairs functions are capturing market share from generalist suppliers unable to absorb compliance costs.
Hospital purchasing departments are consolidating vendor lists around AAMI PB70 liquid barrier certification as a gatekeeping criterion for infection control committees. Group purchasing organizations are disintermediating independent drapery converters by mandating direct manufacturer relationships with notified body accreditation. This concentration is most visible in NHS supply chain frameworks where Elers Medical's dedicated accreditation anchors procurement preference over unverified competitors.
Antimicrobial Hospital Curtains Market Segmentation
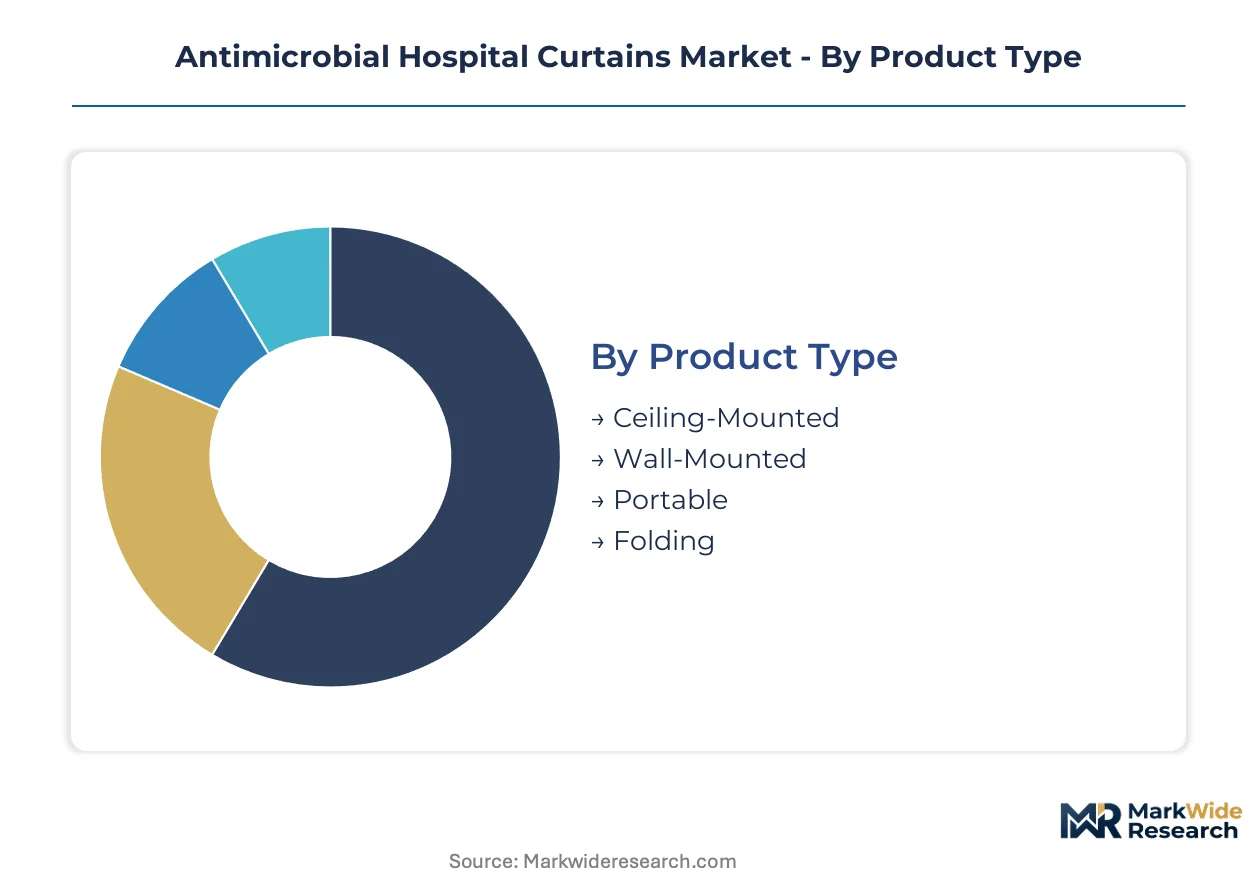
Antimicrobial hospital curtains segment across installation formats, substrate chemistry, clinical setting, and facility type. Procurement specifications diverge sharply between acute care networks requiring ASTM E2149 validation and ambulatory settings prioritizing rapid deployment economics.
Product Type:
Domestic production dominates ceiling-mounted and wall-mounted systems, while portable and folding formats draw heavily from Asian manufacturing clusters serving export markets.
- Ceiling-Mounted:Track-suspended polyester or vinyl panels engineered for ASTM E2149 efficacy retention through repeated laundering cycles. Demand concentrates in US tertiary care facilities where Joint Commission environment-of-care standards mandate fixed infrastructure with documented pathogen suppression. NFPA 701 flame resistance certification filters smaller suppliers from hospital vendor lists.
- Portable:Freestanding frames with snap-on antimicrobial panels enable rapid room reconfiguration without ceiling track installation. Ambulatory surgical centers across Germany and the United Kingdom are expanding procurement as facility flexibility outweighs infrastructure permanence in rental or converted clinical spaces.
- Wall-Mounted:Fixed bracket systems for permanent privacy barriers in patient rooms and corridors. NHS supply chain frameworks in the United Kingdom favor these configurations for renovation projects where ceiling structural loads are constrained.
- Folding:Accordion-pleated panels on mobile frames for temporary isolation or overflow capacity. Asian export manufacturers compete aggressively on unit economics for developing market hospital expansions.
Ceiling-mounted configurations hold the largest share; momentum sits with portable formats.
Material:
Cost tier stratification separates premium biocide-impregnated substrates from commodity vinyl alternatives, with margin concentration tracking infection risk severity in target clinical settings.
- Polyester:Woven synthetic substrates with silver-ion or quaternary ammonium bonding deliver breathability and print compatibility for branded hospital environments. US intensive care units specify these materials for patient room privacy where flame resistance and antimicrobial durability must coexist.
- Vinyl:Fluid-impermeable coated fabrics commanding premium pricing in isolation settings requiring complete pathogen containment. German hematology wards are piloting photocatalytic titanium dioxide variants to extend functional lifespan beyond standard replacement cycles.
- Cotton:Natural fiber substrates with limited commercial presence due to moisture retention and laundering degradation of antimicrobial treatments. Niche demand persists in psychiatric and pediatric settings where textile hand-feel influences patient experience metrics.
- Blended Fabrics:Polyester-cotton combinations attempting to balance durability with aesthetic softness. European manufacturers are reformulating these substrates ahead of REACH authorization deadlines for persistent biocidal substances.
Vinyl commands the highest unit margins; polyester substrates are expanding most quickly across general ward applications.
Application:
Volume concentration tracks bed density and infection protocol stringency, with specification tiers separating life-critical surgical environments from lower-acuity waiting areas.
- Surgical Theaters:Ceiling-mounted vinyl barriers with AAMI PB70 liquid barrier certification for sterile field protection. US hospital networks mandate these specifications for operating room renovation projects tied to CMS hospital-acquired condition penalty avoidance.
- Patient Rooms:Polyester privacy curtains for multi-bed and single-occupancy configurations. German nosocomial infection protocols mandate frequent replacement cycles, institutionalizing recurring demand for disposable or short-lifecycle products.
- Isolation Areas:Fluid-impermeable barriers with continuous antimicrobial activity for immunocompromised patient protection. Photocatalytic coatings are displacing silver-ion formulations in these settings where chemical depletion cannot be tolerated.
- Waiting Areas:Lower-specification polyester curtains with basic quaternary ammonium treatments. Cost pressure from facility management contractors limits adoption of premium biocide chemistries in these lower-risk zones.
Patient rooms generate the highest absolute volume; isolation areas show the steepest expansion trajectory as immunocompromised patient populations grow.
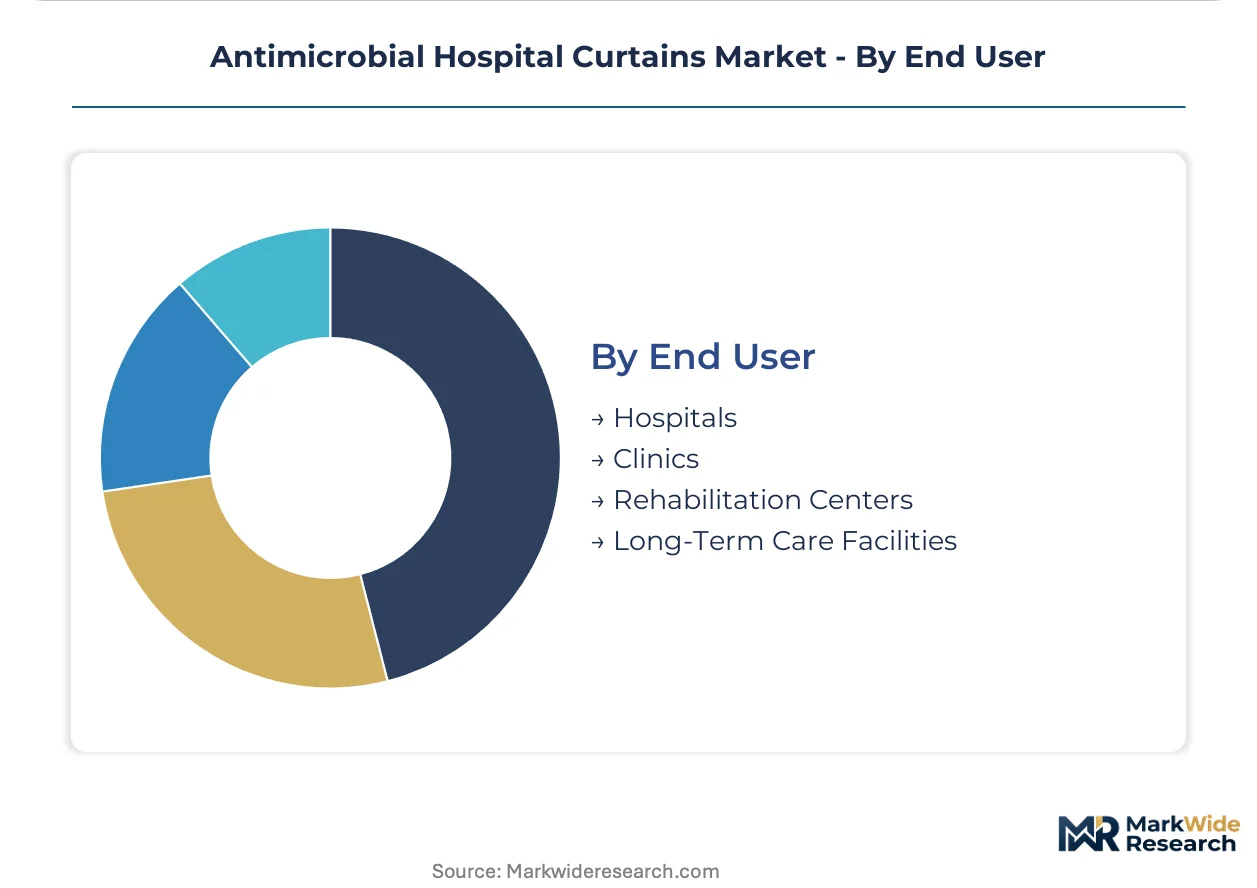
End User:
Customer type determines procurement channel and specification rigor, with hospital systems demanding direct manufacturer relationships that exclude general drapery converters.
- Hospitals:Acute care networks with dedicated infection control committees setting ASTM E2149 and NFPA 701 as gatekeeping criteria. Group purchasing organizations are consolidating vendor lists around notified body accreditation, disintermediating smaller suppliers.
- Clinics:Outpatient and specialty facilities with lower bed density but rising antimicrobial surface requirements. Portable curtain formats are gaining share fastest in this segment as lease flexibility outweighs infrastructure investment.
- Long-Term Care Facilities:Nursing homes and skilled nursing facilities with extended patient stays elevating surface contamination risk. Regulatory scrutiny of healthcare-associated infections in these settings is tightening procurement specifications.
- Rehabilitation Centers:Post-acute facilities with intermediate infection control requirements. Budget constraints relative to hospital networks limit adoption of premium biocide-impregnated substrates.
Hospitals anchor procurement volume; clinics are climbing the fastest as ambulatory care expansion outpaces inpatient bed growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States, Germany, and the United Kingdom drive specification-setting for antimicrobial textile barriers, with tertiary care networks in these markets mandating ASTM E2149 efficacy validation as a baseline vendor qualification.
United States
Intensive care units across major hospital networks are expanding disposable privacy barrier procurement to meet Joint Commission environment-of-care standards. The EPA's emerging pathogen claims framework is compressing supplier eligibility by demanding quantitative efficacy documentation. Boston and Minneapolis medical device clusters host specialized textile converters serving GPO-integrated supply chains.
Germany
Nosocomial infection protocols in tertiary care facilities mandate frequent curtain replacement cycles, institutionalizing recurring demand for short-lifecycle products. The EU Medical Device Regulation's expanded scope for infection prevention claims is redirecting manufacturer documentation investments toward notified body engagement. North Rhine-Westphalia's industrial textile belt concentrates production of AAMI PB70-certified barriers.
United Kingdom
NHS supply chain frameworks favor dedicated accreditation for renovation projects where ceiling structural loads constrain configuration options. REACH restrictions on persistent biocidal substances are forcing reformulation of quaternary ammonium bonding agents ahead of authorization deadlines. Yorkshire-based medical textile specialists are capturing procurement preference through regulatory affairs capabilities.
China
Quaternary ammonium compound supply concentrates among specialty chemical producers, exposing downstream buyers to input volatility. GB standards for medical textiles are converging with international efficacy benchmarks. Hangzhou and Shaoxing manufacturing clusters dominate vinyl-coated curtain volumes destined for Asia-Pacific procurement offices.
Japan
Metropolitan Tokyo hospital systems are piloting photocatalytic titanium dioxide coatings in hematology wards where immunocompromised patients demand continuous pathogen suppression. PMDA consultation pathways for antimicrobial device claims intersect with industrial chemical registration requirements. Osaka-based textile converters are developing hybrid substrate formulations for premium isolation settings.
Antimicrobial Hospital Curtains Market Vendor Landscape
Player mix skews toward mid-scale medical textile specialists with dedicated regulatory affairs functions rather than commodity drapery converters. The market exhibits tiered concentration around AAMI PB70 certification holders, with notified body accreditation serving as the primary gating mechanism for hospital vendor list inclusion. Two strategic archetypes dominate: integrated biocide chemistry developers and NHS-accredited supply chain anchors. Competitive moves center on ECHA dossier preparation for REACH compliance and capacity expansion in polyester substrate finishing.
Within the certification-driven tier, Endurocide Limited and Elers Medical occupy positions anchored to recurring hospital contract structures. Hangzhou Xiang Jun represents the scale-driven manufacturing archetype competing on vinyl-coated volume economics. These three exemplify the bifurcation between efficacy-durability claimants and unit-cost optimizers that the EPA and EU MDR frameworks are actively reinforcing.
| Leading Market Players |
|---|
| Endurocide Limited |
| Hospital Curtain Solutions |
| Elers Medical |
| National Surgical Corporation |
| Anglo Middle East |
| Hangzhou Xiang Jun |
| RD Plast |
| EcoMed Technologies |
| Tracks2Curtains |
| Others |
Supply Flow & Price Mechanics
AAMI PB70 liquid barrier certification gates both supply qualification and price differentiation simultaneously, filtering general drapery converters from hospital vendor lists while concentrating margin capture among notified body-accredited manufacturers. This regulatory threshold bifurcates procurement economics between premium-certified tiers and commodity alternatives.
Pricing Analysis
Cost-plus contracts with silver-ion compound indexation dominate hospital GPO agreements, locking in raw material pass-through mechanisms. Three-tier pricing structure across premium, standard, and economy levels separates AAMI PB70-certified vinyl barriers from ASTM E2149 polyester grades and unverified commodity alternatives. Pricing pressure stems from REACH-driven quaternary ammonium reformulation costs in European supply chains. Ambulatory surgical centers exhibit highest price sensitivity, while German tertiary care facilities prioritize efficacy durability over unit economics.
Supply Chain Analysis
Quaternary ammonium compound production concentrates in China's Zhejiang and Jiangsu provinces, creating single-source vulnerability for downstream textile finishers. Polyester substrate weaving draws from Hangzhou and Shaoxing manufacturing clusters, while silver-ion chemistry relies on South Korean and Japanese specialty chemical producers. Tariff exposure on Chinese biocide imports threatens margin stability for European converters. Distribution runs through hospital group purchasing organizations that disintermediate independent drapery suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of dedicated regulatory affairs capabilities constrains supplier expansion, as ECHA dossier preparation and FDA 510(k) clearance demand specialized personnel that commodity textile converters cannot recruit.
For Market Incumbents: Secure recurring NHS and US hospital network contracts through ECHA substance evaluation dossier completion ahead of authorization deadlines. Anchor backward integration into silver-ion chemistry to defend margin position against raw material volatility. Prioritize photocatalytic titanium dioxide R&D to displace formulation-dependent competitors in isolation ward specifications. For New Entrants and Emerging Players: Anchor in portable and folding curtain formats for ambulatory surgical centers where ceiling infrastructure constraints eliminate incumbent track-system advantages. Target German clinic networks underserved by rigid hospital GPO structures. Lead with rapid deployment value propositions rather than efficacy certification parity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed medical textile specialists holding notified body accreditation but lacking EU MDR transition capital. Five-to-ten year viability hinges on REACH compliance cost absorption rather than volume scale. Monitor EPA emerging pathogen claim enforcement intensity as inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ECHA Dossier Completion | REACH authorization secures European market access against reformulation-driven competitor exit. |
| Photocatalytic Coating Scale-Up | Titanium dioxide manufacturing captures German hematology ward replacement cycle extension demand. |
| Backward Integration into Biocide Chemistry | In-house silver-ion production insulates margin from Zhejiang compound price volatility. |
| Portable Format Capacity Addition | Freestanding frame manufacturing serves ASC flexibility requirements outside fixed infrastructure. |
| NHS Supply Chain Accreditation | Dedicated framework inclusion disintermediates unverified competitors in UK renovation procurement. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA registration databases, ECHA authorization dossiers, and hospital GPO contract disclosures. Interviews with infection control committee chairs, biomedical textile procurement managers, regulatory affairs directors at notified bodies, and GPO contracts specialists informed demand-side specification evolution. Secondary validation drew from FDA 510(k) clearances, NHS supply chain framework awards, and customs trade data for quaternary ammonium compound flows. Bottom-up facility-level procurement estimates triangulate against top-down market sizing from manufacturer capacity disclosures.
Segmentation dimensions modeled span installation format, substrate chemistry, clinical application severity, and end-user facility type across the analysis window. CAGRs derive from facility expansion pipelines, replacement cycle frequency mandates, and biocide chemistry transition timelines. Forecast inputs incorporate Joint Commission environment-of-care standard revision schedules and CMS hospital-acquired condition penalty structure evolution.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory enforcement intensity; material deviation in EPA or ECHA timeline adherence would warrant model refresh. Practitioners should keep alternative scenarios live as REACH authorization deadlines and emerging pathogen claim frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Biological and Chemical Indicators Market
Infection Control
Antimicrobial Catheters Market
Infection Control
Denture Disinfectants Market
Infection Control
Intra Abdominal Infection Market
Infection Control
Multi-Surface Disinfection Booster Systems with Low QAC Load Market
Infection Control
Ultraviolet Germicidal Irradiation Market
Infection Control
Hand Sanitizer Spray Market
Infection Control
Infection Control Supplies Market
Infection Control
UV Disinfection Equipment Market
Infection Control
Surgical Site Infections Market
Infection Control
Global Wall Mounted Ozone Disinfection Machine Market
Infection Control
Hygiene Stations Market
Infection Control
New Zealand Healthcare Surface Disinfectant Wipes Market
Infection Control
Ultraviolet Disinfection Equipment Market
Infection Control
Preventable Vaccines Market
Infection Control
North America Hand Sanitizer Market