
 Complicated Urinary Tract Infections Treatment Market | 2026-2036
Complicated Urinary Tract Infections Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Complicated Urinary Tract Infections Treatment Market Outlook
India is narrowing the manufacturing cost gap in generic intravenous antibiotics while building active pharmaceutical ingredient capacity for cephalosporin and carbapenem classes. Pfizer Inc. leverages its hospital infectious disease franchise to sustain formulary access across tertiary care networks. Merck & Co., Inc. anchors its position through backward integration into fermentation-based antibiotic production. Shionogi & Co., Ltd. differentiates via its Japan-centric focus on resistant Gram-negative uropathogen coverage.
Complicated urinary tract infections treatment encompasses antimicrobial therapies administered to patients with structural or functional urinary abnormalities, immunocompromise, or resistant pathogens, typically requiring intravenous ceftriaxone, piperacillin-tazobactam, or carbapenems with minimum inhibitory concentration-guided dosing. The primary purpose is eradication of uropathogens while preventing progression to pyelonephritis, bacteremia, or sepsis in high-risk patient populations. Antibiotics occupy the dominant revenue share within product type segmentation, though antiseptics gain traction as adjunctive bladder irrigation therapies in catheter-associated cases. Injectable delivery mode leads in value terms due to hospital inpatient concentration, while oral formulations represent the fastest transition category as step-down protocols expand. Hospitals capture the largest end user segment, but homecare infusion services emerge as a structurally important margin pool for long antibiotic courses.
FDA antimicrobial resistance frameworks and EMA's updated infectious disease guidelines shape clinical development pathways, trial endpoints, and post-market surveillance obligations for novel agents targeting multidrug-resistant Enterobacteriaceae. The country's national pharmaceutical regulator in India, CDSCO, enforces bioequivalence standards that determine generic substitution eligibility for complicated UTI indications. WHO stewardship protocols influence hospital formulary restrictions and duration-of-therapy protocols across OECD markets. Stakeholders must monitor resistance surveillance data from CDC and ECDC to anticipate shifts in empiric therapy guidelines and corresponding product demand.
Market Dynamics
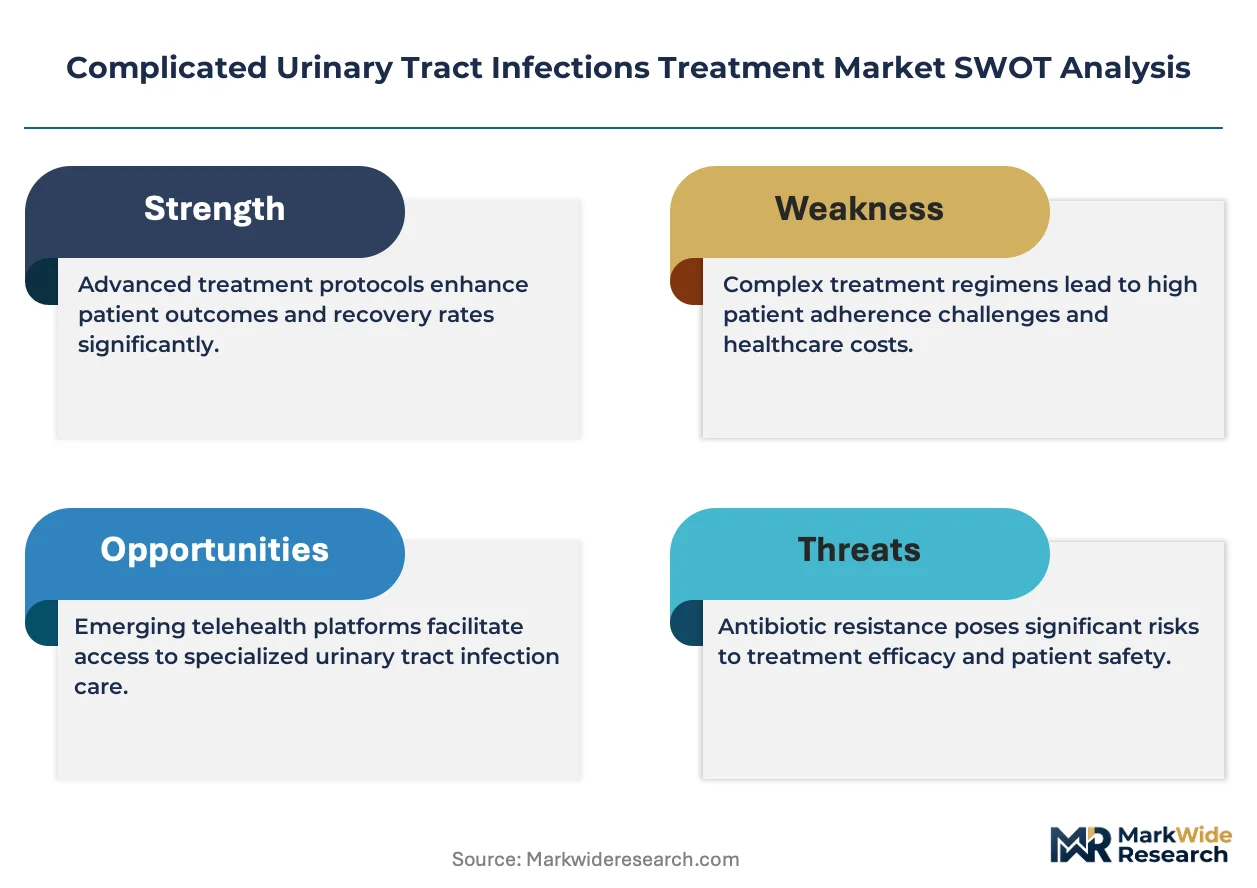
Hospital formulary restrictions and antimicrobial stewardship protocols are compressing empiric prescribing latitude, forcing manufacturers to demonstrate resistance-relevant efficacy through FDA and EMA pathway redesigns rather than traditional superiority trials.
Growth Catalysts
- Resistance surveillance integration:CDC and ECDC real-time pathogen tracking enables targeted therapy protocols that prioritize agents with documented activity against local multidrug-resistant Enterobacteriaceae.
- Carbapenem-sparing protocols:Hospital infectious disease departments in the United States and Germany are expanding piperacillin-tazobactam and novel beta-lactamase inhibitor combinations to preserve last-reserve antibiotics.
- Home infusion infrastructure:Specialty pharmacy networks now support extended intravenous antibiotic courses, reducing inpatient length-of-stay and expanding addressable patient populations.
Market Restraints
- Fermentation capacity concentration:Active pharmaceutical ingredient production for cephalosporin and carbapenem classes clusters in China and India, creating single-source vulnerability for Western finished-dose manufacturers.
- Clinical trial cost inflation:FDA's updated complicated UTI guidance demands larger non-inferiority margins and microbiological intent-to-treat endpoints, extending enrollment timelines.
- Oral step-down substitution:Fluoroquinolone and trimethoprim-sulfamethoxazole generics capture post-stabilization patients who would otherwise continue branded intravenous therapy.
Strategic Opportunities
- Japan's resistant Gram-negative niche:PMDA's streamlined review for agents targeting carbapenem-resistant pathogens creates first-mover positioning for novel beta-lactam combinations.
- Bladder irrigation antiseptics:Catheter-associated complicated UTI protocols are integrating chlorhexidine and povidone-iodine instillations as adjunctive therapy alongside systemic antibiotics.
- Pharmacokinetic-guided dosing software:Integration of minimum inhibitory concentration data with Bayesian modeling tools enables precision dosing that differentiates premium intravenous agents.
Industry Challenges
- Microbiology laboratory staffing:Specialized personnel for susceptibility testing and resistance mechanism identification are scarce in community hospital settings, delaying appropriate therapy selection.
- Legacy electronic health record integration:Antimicrobial stewardship decision support modules require costly customization to interface with entrenched hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Complicated Urinary Tract Infections Treatment Market |
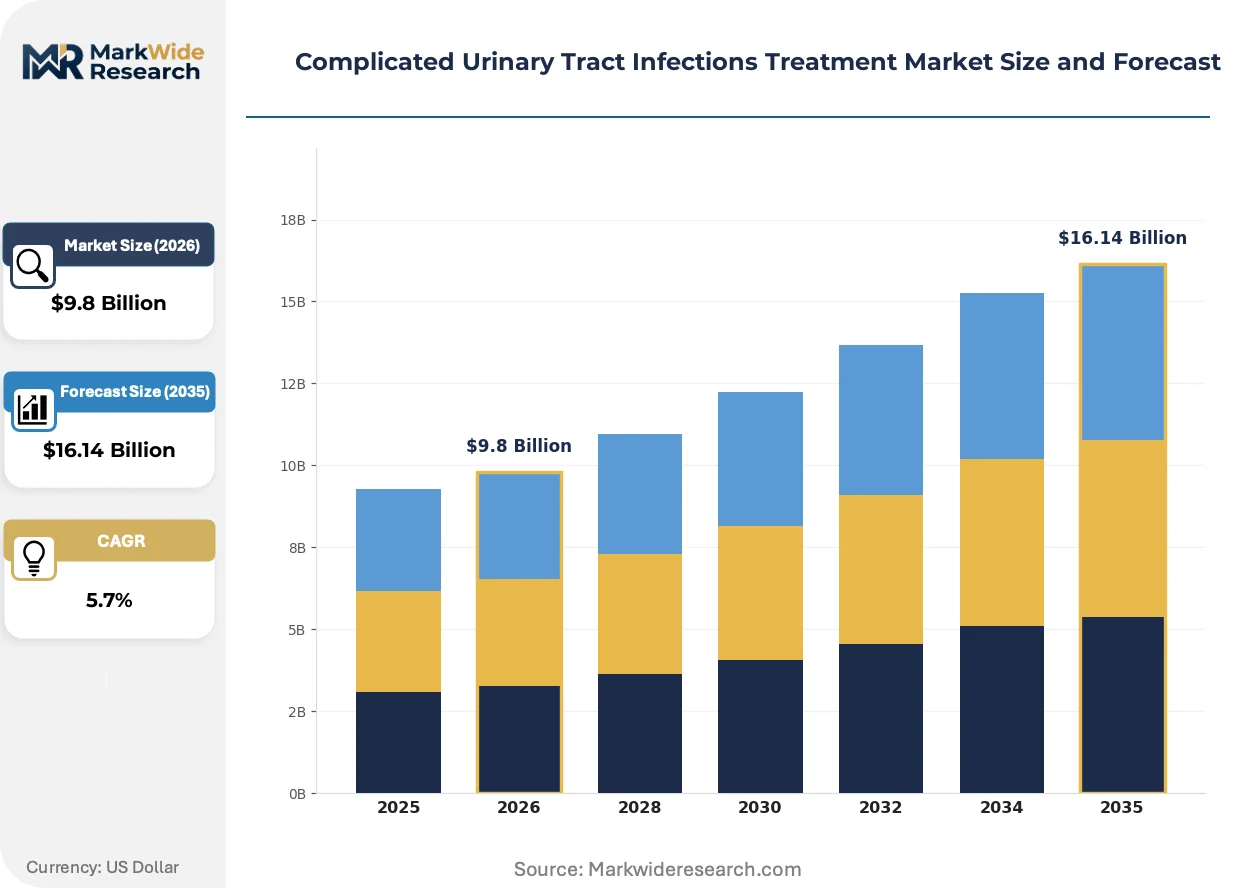
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antiseptics, Probiotics, Antifungals Delivery Mode: Oral, Injectable, Topical, Intravenous End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Care Setting: Inpatient, Outpatient, Urgent Care, Primary Care |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Shionogi & Co., Ltd., Cipla Ltd., Wockhardt Ltd., AbbVie Inc., AstraZeneca, GlaxoSmithKline, Venatorx Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Complicated Urinary Tract Infections Treatment Market Strategic Shifts
Antimicrobial development is pivoting toward pathogen-specific indications and resistance-informed trial designs, while care delivery models compress the boundary between inpatient and outpatient intravenous administration.
Plazomicin and other next-generation aminoglycosides engineered for activity against carbapenem-resistant Enterobacteriaceae are collapsing traditional hierarchies between reserve and first-line agents in tertiary care networks. Hospital infectious disease departments in the United States are adopting these agents earlier in treatment algorithms when susceptibility profiles permit. This compression is shortening the commercial runway for legacy broad-spectrum antibiotics that previously dominated empiric protocols.
EMA's updated infectious disease guidelines now mandate resistance surveillance sub-studies and post-authorization safety commitments for all novel antibiotics seeking complicated UTI indications. Manufacturers must establish European pharmacovigilance infrastructure and commit to annual resistance reporting as a condition of marketing authorization. German and French hospital procurement coalitions are incorporating these stewardship obligations into tender evaluations, favoring suppliers with demonstrated post-market surveillance capabilities.
Step-down therapy protocols are accelerating transitions from intravenous to oral formulations once clinical stabilization occurs, compressing revenue capture windows for hospital-administered agents. Specialty pharmacy providers and home infusion services are capturing margin from extended antibiotic courses that previously remained inpatient. This channel shift is most pronounced in the United States, where bundled payment models incentivize earlier discharge and outpatient parenteral antimicrobial therapy expansion.
Complicated Urinary Tract Infections Treatment Market Segmentation
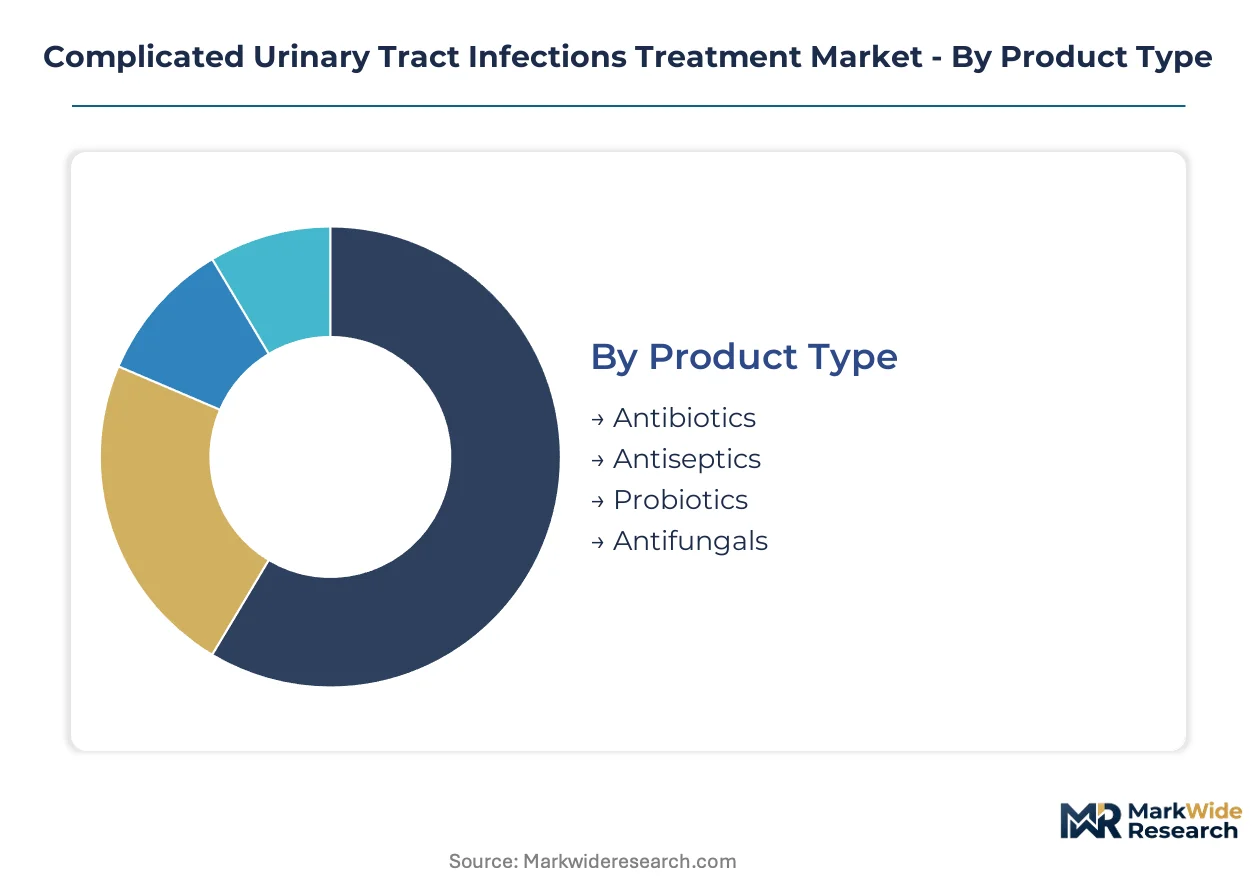
Segmentation in complicated urinary tract infections treatment reveals distinct margin profiles tied to care setting economics and administration complexity. Hospital procurement teams weight formulary decisions differently across delivery modes, while homecare expansion creates channel-specific pricing dynamics.
Product Type:
Cycle times vary sharply across therapeutic classes, with intravenous antibiotics turning over in days while probiotic adjuvants require weeks of patient adherence to demonstrate value.
- Antibiotics:Beta-lactams, carbapenems, and aminoglycosides constitute the clinical backbone for multidrug-resistant Enterobacteriaceae coverage. Demand concentrates in tertiary care networks across the United States, Germany, and Japan where carbapenem-sparing protocols prioritize piperacillin-tazobactam and novel beta-lactamase inhibitor combinations.
- Antiseptics:Chlorhexidine and povidone-iodine formulations serve as adjunctive bladder irrigation therapies in catheter-associated cases. German and French hospital procurement coalitions favor suppliers with demonstrated post-market surveillance capabilities when evaluating antiseptic tenders.
- Probiotics:Lactobacillus-based formulations target microbiome restoration following antibiotic courses.
- Antifungals:Fluconazole and echinocandins address candiduria in immunocompromised patients with complicated UTIs.
Antibiotics anchor the volume base while antiseptics gain share at the steepest rate.
Delivery Mode:
Cost tier stratification separates premium intravenous hospital administration from commoditized oral generics, with reimbursement differentials driving channel allocation decisions.
- Injectable:Intramuscular cephalosporins bridge inpatient and outpatient settings for patients unable to tolerate oral transition. Specialty pharmacy networks in the United States capture margin from extended injectable courses that reduce inpatient length-of-stay.
- Intravenous:Continuous infusion pumps and intermittent bolus dosing dominate hospital inpatient revenue capture. FDA antimicrobial resistance frameworks mandate microbiological intent-to-treat endpoints that extend development timelines for novel intravenous agents.
- Oral:Fluoroquinolone and trimethoprim-sulfamethoxazole generics capture post-stabilization patients in step-down protocols.
- Topical:Limited application in uncomplicated cases with minimal penetration in complicated UTI protocols.
Intravenous administration commands the highest revenue per patient-day while oral formulations expand most quickly through step-down protocol adoption.
End User:
Customer type segmentation aligns purchasing authority with clinical decision-making, separating centralized hospital formulary control from decentralized homecare prescribing.
- Hospitals:Tertiary care networks in the United States and Germany drive empiric protocol design and resistance surveillance integration. Antimicrobial stewardship committees restrict broad-spectrum agent prescribing to documented susceptible isolates.
- Homecare:Infusion services and specialty pharmacies manage extended antibiotic courses for stable patients discharged from inpatient settings. United States bundled payment models incentivize earlier discharge and outpatient parenteral antimicrobial therapy expansion.
- Clinics:Urology and infectious disease outpatient practices handle initial diagnosis and stabilization decisions.
- Long-term Care Facilities:Catheter-associated infection management drives antiseptic adjunctive use alongside systemic therapy.
Hospitals anchor the volume base while homecare gains share at the steepest rate.
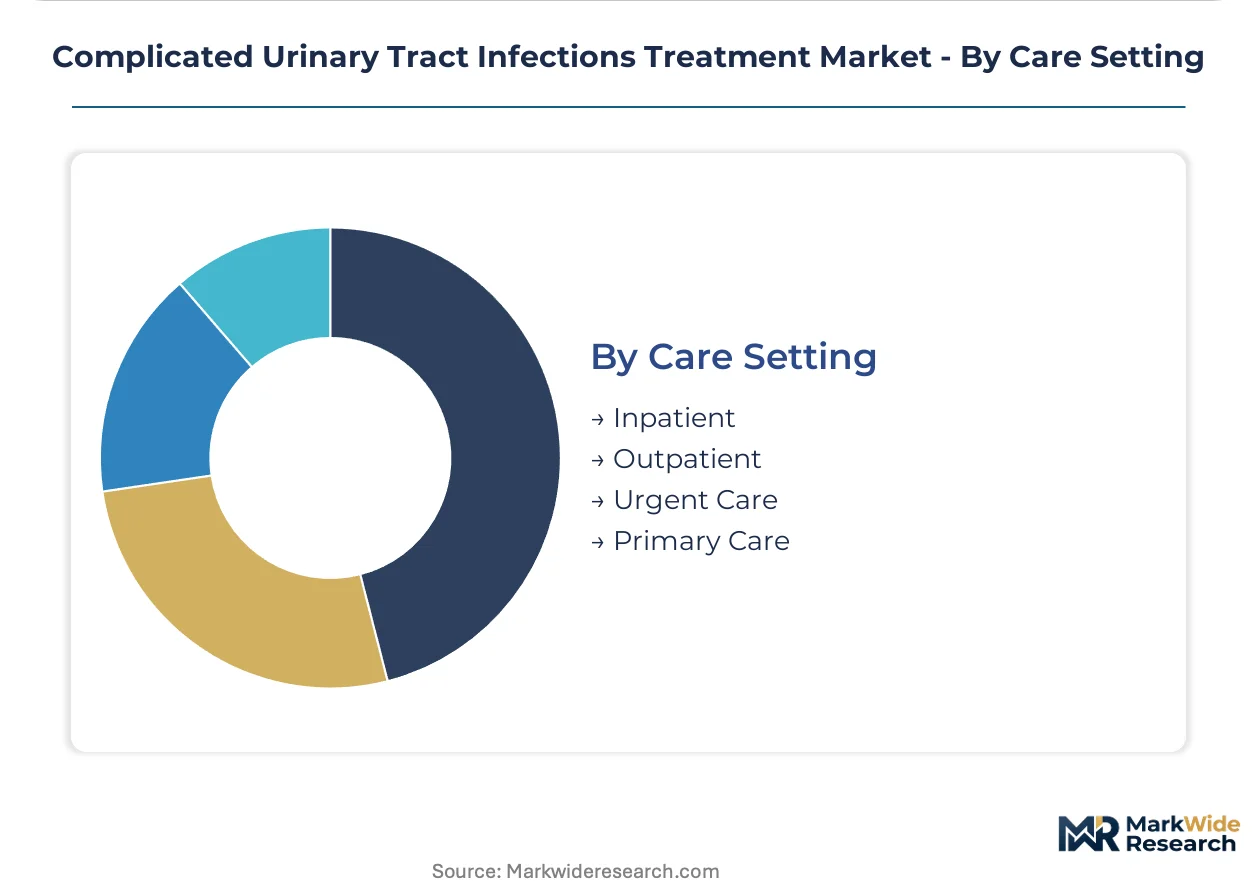
Care Setting:
Application urgency determines reimbursement tier and therapy intensity, with inpatient admission criteria tightening under antimicrobial stewardship protocols.
- Inpatient:Structural urinary abnormalities, immunocompromise, or hemodynamic instability mandate intravenous antibiotic initiation. EMA's updated infectious disease guidelines require resistance surveillance sub-studies as conditions of marketing authorization for inpatient-targeted agents.
- Urgent Care:Same-day stabilization and intravenous antibiotic initiation for patients meeting sepsis criteria. Japanese tertiary networks leverage PMDA's streamlined review for carbapenem-resistant pathogen coverage to prioritize novel agents.
- Outpatient:Oral antibiotic prescribing for clinically stable patients with reliable follow-up.
- Primary Care:Initial diagnosis and referral coordination for complicated case identification.
Inpatient care anchors the volume base while urgent care gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: the United States prioritizes carbapenem-sparing protocols in tertiary networks, while Japan and Germany concentrate on resistant Gram-negative coverage, and India scales generic intravenous manufacturing.
United States
Hospital formulary restrictions and antimicrobial stewardship committees drive empiric prescribing toward piperacillin-tazobactam combinations. FDA's updated complicated UTI guidance mandates microbiological intent-to-treat endpoints that extend development timelines. Tertiary care networks in Boston and Houston anchor resistance surveillance integration and novel beta-lactam adoption.
Germany
Hospital procurement coalitions prioritize suppliers with demonstrated post-market surveillance capabilities in tender evaluations. EMA's updated infectious disease guidelines require resistance surveillance sub-studies as conditions of marketing authorization. The Rhine-Ruhr metropolitan region concentrates formulary decision-making for carbapenem-sparing protocols across university hospitals.
Japan
PMDA's streamlined review pathway for agents targeting carbapenem-resistant pathogens creates first-mover positioning opportunities. METI coordinates national resistance surveillance infrastructure that informs hospital empiric therapy guidelines. The Kanto region around Tokyo anchors tertiary network adoption of novel beta-lactamase inhibitor combinations.
India
CDSCO enforces bioequivalence standards that determine generic substitution eligibility for complicated UTI indications. The country's national pharmaceutical regulator accelerates active pharmaceutical ingredient capacity building for cephalosporin and carbapenem classes. Gujarat and Maharashtra industrial clusters narrow manufacturing cost gaps in generic intravenous antibiotics while serving Western finished-dose manufacturers.
Complicated Urinary Tract Infections Treatment Market Competitive Environment
Capability concentration sits with fermentation-based antibiotic producers; scale advantage sits with hospital infectious disease franchise holders. The market structures around three tiers: backward-integrated API manufacturers, hospital formulary incumbents with stewardship relationships, and regional generic specialists with cost-optimized production. Dominant competitive moves include strategic partnerships for resistance surveillance data access and geographic expansion into Japanese and German procurement coalitions.
Within the hospital franchise tier, Pfizer Inc. and Merck & Co., Inc. occupy positions anchored by tertiary care network relationships and fermentation-based production integration. Shionogi & Co., Ltd. exemplifies the geography-focused specialist archetype, concentrating on Japan-centric resistant Gram-negative uropathogen coverage. Among emerging challengers, Venatorx Pharmaceuticals represents the novel mechanism pathway, while Cipla Ltd. and Wockhardt Ltd. sit within the cost-optimized generic manufacturing tier serving volume markets.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Shionogi & Co., Ltd. |
| Cipla Ltd. |
| Wockhardt Ltd. |
| AbbVie Inc. |
| AstraZeneca |
| GlaxoSmithKline |
| Venatorx Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency for fermentation-based cephalosporin and carbapenem active pharmaceutical ingredients determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic concentration of finished-dose manufacturing capacity. Western hospital networks face asymmetric negotiating leverage against API suppliers concentrated in China and India, compressing margins at the generic intravenous tier while preserving premium positioning for novel beta-lactamase inhibitor combinations.
Pricing Analysis
United States hospital procurement coalitions command 40-60% discounts off list prices for generic piperacillin-tazobactam through competitive tendering, while Japanese tertiary networks accept premium positioning for carbapenem-resistant pathogen coverage under PMDA's streamlined review pathway. Price differentiation rests on FDA antimicrobial resistance framework compliance and demonstrated post-market surveillance capabilities rather than clinical efficacy alone. Cost compression in the generic intravenous tier is intensifying because Indian manufacturers are narrowing production cost gaps through backward integration into fermentation capacity. Homecare infusion services exhibit the highest price sensitivity due to bundled payment model constraints, whereas academic medical centers prioritize resistance-relevant efficacy over acquisition cost.
Supply Chain Analysis
Fermentation feedstock for cephalosporin and carbapenem antibiotic classes draws from agricultural glucose and soybean meal suppliers concentrated in the United States, Brazil, and Argentina. Active pharmaceutical ingredient production clusters in China and India, with Gujarat and Maharashtra industrial hubs serving Western finished-dose manufacturers. Single-source vulnerability for carbapenem intermediates creates exposure to export license restrictions and environmental compliance shutdowns. Distribution runs through hospital procurement coalitions in Germany, specialty pharmacy networks in the United States, and regional distributors serving Japanese tertiary care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FDA and EMA antimicrobial resistance frameworks create sticky formulary relationships that resist displacement by cost-optimized alternatives.
For Market Incumbents: Pre-empt generic substitution threats by deepening backward integration into fermentation-based API production and securing exclusive resistance surveillance data partnerships with CDC and ECDC networks. Anchor hospital infectious disease franchise positions through stewardship committee relationships that prioritize post-market surveillance capabilities in formulary evaluations.
For New Entrants and Emerging Players: Japan's underpenetrated homecare infusion channel offers first-mover positioning for outpatient parenteral antimicrobial therapy expansion under PMDA's streamlined review pathway. Target bladder irrigation antiseptics as the most penetrable adjunctive therapy segment, leveraging chlorhexidine and povidone-iodine formulation gaps in catheter-associated complicated UTI protocols. Pursue pharmacokinetic-guided dosing software partnerships as the primary go-to-market angle to differentiate premium intravenous agents.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated API manufacturers with hospital formulary incumbency. Long-term viability hinges on fermentation capacity ownership and resistance surveillance infrastructure commitments. Monitor CDC and ECDC real-time pathogen tracking data releases as the critical inflection indicator for empiric therapy guideline shifts and corresponding product demand repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive API supply secures margin control against Chinese and Indian supplier concentration. |
| Resistance Surveillance Data Partnership | CDC and ECDC network access enables targeted therapy protocol integration and formulary anchoring. |
| Homecare Infusion Channel Expansion | Specialty pharmacy relationships capture margin from extended intravenous antibiotic courses. |
| Pharmacokinetic-Guided Dosing Software Development | Bayesian modeling integration differentiates premium agents through precision dosing capabilities. |
| PMDA Streamlined Review Pathway Pursuit | Japan's carbapenem-resistant pathogen indication creates first-mover positioning in resistant Gram-negative coverage. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across infectious disease specialists, hospital formulary directors, antimicrobial stewardship committee chairs, and specialty pharmacy procurement managers. Secondary validation drew from FDA antimicrobial resistance framework documents, EMA updated infectious disease guidelines, ClinicalTrials.gov enrollment records, and hospital procurement database extracts. Bottom-up patient-volume modeling and top-down pharmaceutical expenditure triangulation anchored market size calibration.
Calibration against historical resistance surveillance data from CDC and ECDC informed projection assumptions across the analysis window. Segmentation dimensions modeled include product type, delivery mode, end user, care setting, and regional regulatory cluster. CAGRs were derived from epidemiological trend extrapolation and formulary restriction scenario analysis. Forecast inputs incorporated carbapenem-sparing protocol adoption curves and homecare infusion infrastructure expansion rates.
Macroeconomic conditions sit as an overlay; deviation in hospital reimbursement rates and pharmaceutical tariff regimes would shift the trajectory. Forecasts reflect documented assumptions regarding resistance surveillance integration timelines and stewardship committee influence expansion. Material shifts in FDA or EMA antimicrobial resistance framework requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Urinary Incontinence Treatment Drugs Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Uraemia Treatment Market
Urology
Ureter Cancer Treatment Market
Urology
Self-Intermittent Catheters Market
Urology
Catheter-Associated Urinary Tract Infections Treatment Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Disposable Ureteroscope Market
Urology
Transrectal Ultrasound Market
Urology
Cystoscope Market
Urology
Global Nephrology and Urology Devices Market
Urology
Voiding Cystourethrogram Market
Urology
Chronic Pyelonephritis Treatment Market
Urology
Acquired Cystic Kidney Disease Treatment Market
Urology
Suprapubic Catheters Market
Urology
Nocturia Market