
 Urology Disposables Market | 2026-2036
Urology Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Urology Disposables Market Analytics
Market Context
German catheter manufacturers is pivoting toward automated silicone extrusion lines to serve rising European hospital demand. Coloplast A/S leverages its integrated manufacturing in Denmark to sustain premium positioning across hydrophilic catheter lines. Boston Scientific Corporation anchors its urology disposable portfolio through specialized stent and drainage kit production for ambulatory settings. Cook Medical differentiates via physician training programs that bind end-users to its procedural tray configurations.
Technical Definition and Segment Structure
Urology disposables encompass single-use devices including catheters, drains, kits, and trays manufactured from latex, silicone, PVC, or polypropylene through extrusion, molding, and gamma-sterilization processes, designed to maintain sterile fields during urinary drainage, stone management, or endoscopic procedures. Catheters command the largest product-type position due to indwelling and intermittent use volumes across acute and chronic patient populations, while telehealth-enabled home care delivery is expanding fastest as remote patient monitoring platforms integrate with self-catheterization protocols. Silicone material grades capture premium margin pools where biocompatibility requirements exclude PVC alternatives in long-term indwelling applications.
Regulatory Framework and Outlook
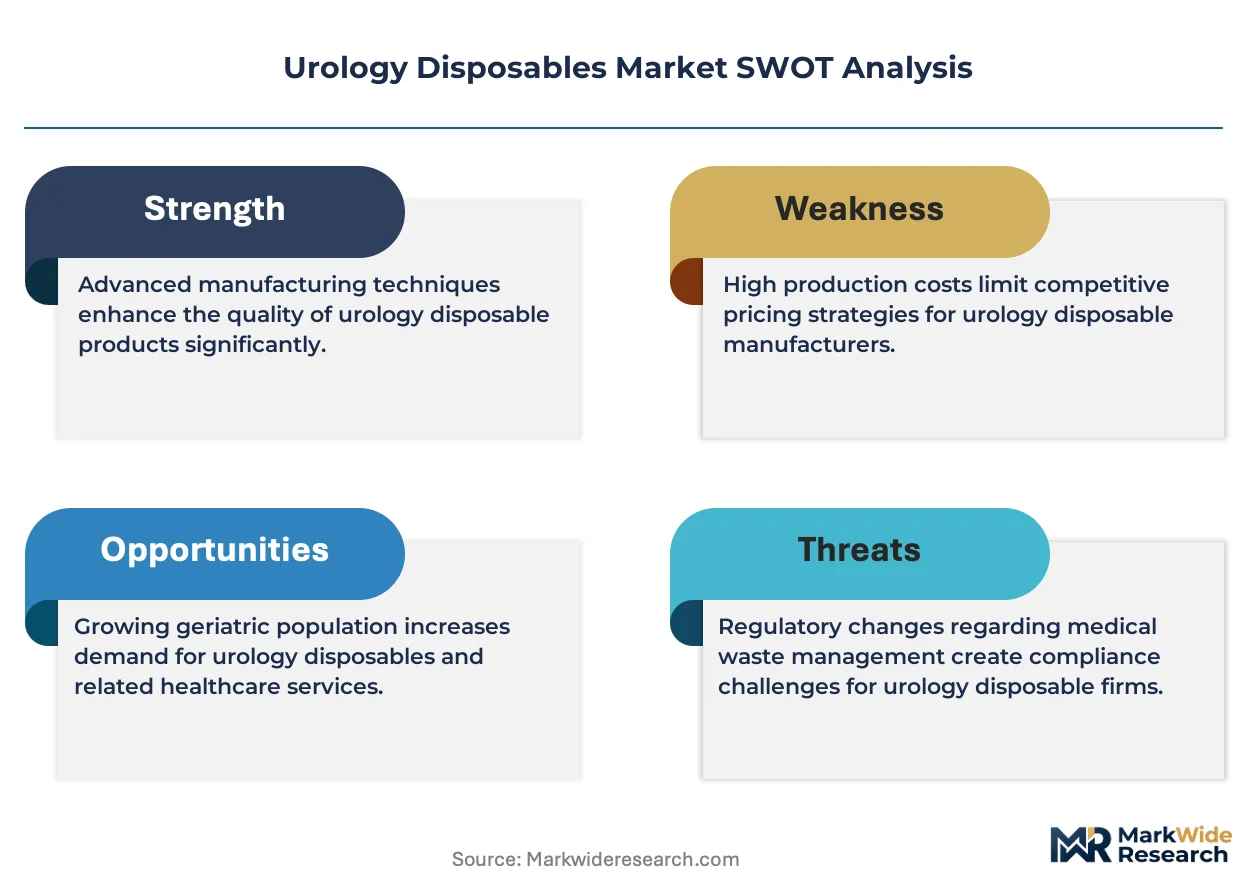
The FDA enforces Class II device controls and 510(k) clearance pathways for urology disposables, while the EU Medical Device Regulation mandates notified body certification and post-market surveillance that elevates compliance costs for tray and kit assemblers. ISO 13485 quality management systems and USP Class VI biocompatibility testing form baseline market-access requirements that filter out non-specialized contract manufacturers. Stakeholders must monitor evolving EPA and REACH restrictions on phthalate plasticizers in PVC formulations, as material substitution decisions will reshape supplier qualification timelines and production economics across the value chain.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around pre-sterilized procedural trays as infection control protocols tighten and liability exposure from reprocessed devices escalates. This buyer-side consolidation is compressing supplier margins while elevating compliance documentation requirements across the value chain.
Growth Catalysts
- FDA 510(k) pathway clarification:The agency's updated guidance on single-use device equivalency is accelerating hospital conversions from reprocessed catheters to verified sterile disposables in ambulatory surgery centers.
- Silicone extrusion automation:German manufacturers deploying robotic extrusion lines are reducing per-unit production costs for hydrophilic catheter coatings, expanding addressable patient populations.
- Ambulatory surgery center expansion:United States same-day urological procedure volume is concentrating demand for compact, procedure-specific disposable kits designed for rapid turnover.
Market Restraints
- Medical-grade silicone supply concentration:Three specialty chemical producers in Germany and Japan control upstream silicone monomer supply, creating input cost volatility during semiconductor industry demand spikes.
- EU MDR certification timelines:Notified body backlogs for Class IIa urology device recertification are extending market access delays to 18-24 months for tray and kit assemblers.
- Phthalate substitution complexity:REACH restrictions on DEHP plasticizers in PVC formulations force material validation cycles that disrupt established supply relationships.
Strategic Opportunities
- Home care telehealth integration:Remote patient monitoring platforms pairing with self-catheterization protocols are opening recurring revenue streams outside acute care settings.
- India domestic manufacturing incentives:PLI scheme subsidies for medical device production are attracting contract manufacturers to serve South Asian hospital procurement.
- Biodegradable polymer development:Convergence of polylactic acid processing with gamma-sterilization protocols is enabling eco-positioned catheter lines for sustainability-mandated European tenders.
Industry Challenges
- Gamma sterilization capacity bottlenecks:Cobalt-60 source replenishment delays and facility licensing backlogs are extending finished goods quarantine periods.
- ISO 13485 auditor scarcity:Qualified quality management system auditors are concentrated in Western Europe, slowing certification for Asian contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urology Disposables Market |
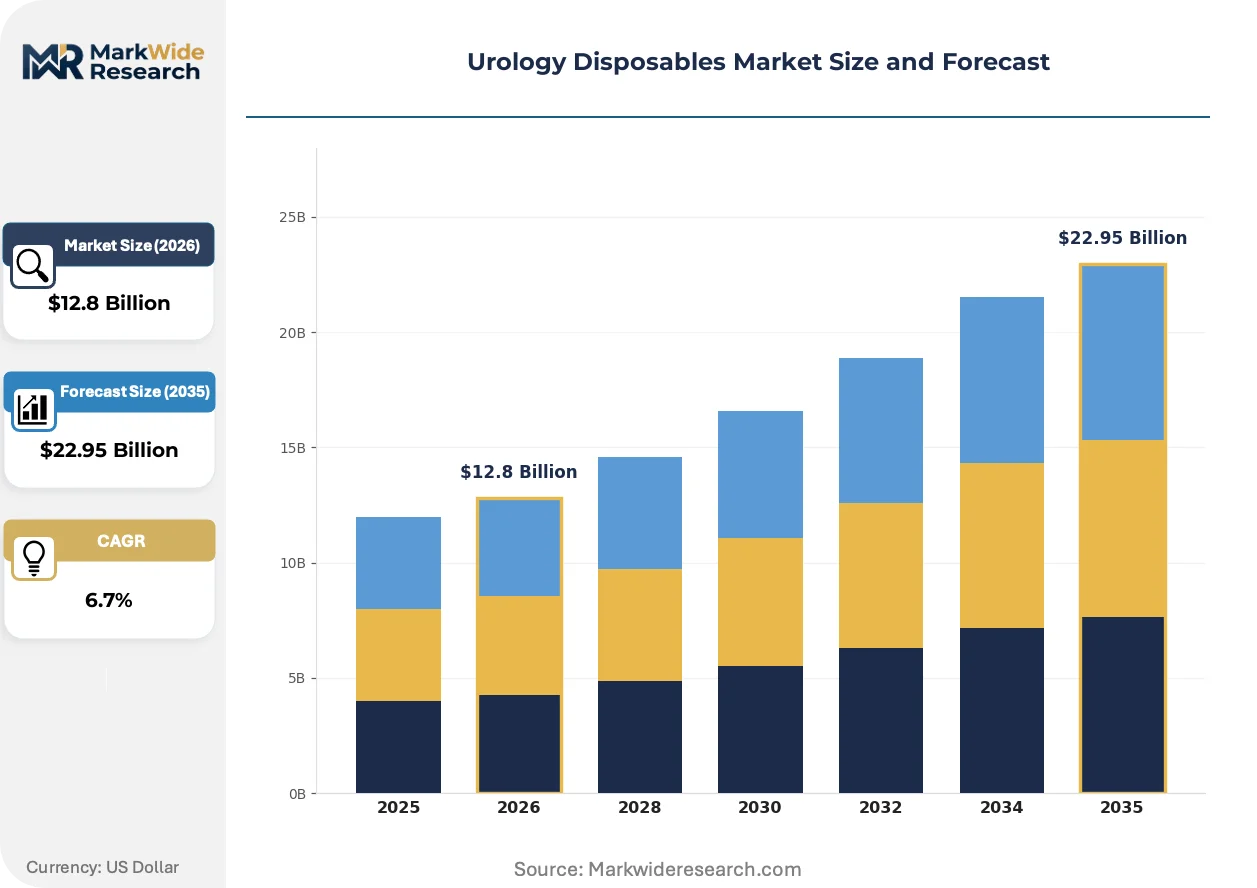
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Drains, Kits, Trays Delivery Mode: Inpatient, Outpatient, Home Care, Telehealth End User: Hospitals, Clinics, Nursing Homes, Athletic Facilities Material: Latex, Silicone, PVC, Polypropylene |
| Companies Covered | Coloplast A/S, Boston Scientific Corporation, Olympus Corporation, B. Braun Melsungen AG, Stryker Corporation, Cook Medical, Rocamed, GPC Medical Ltd, Narang Medical Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urology Disposables Market Evolving Landscape
Digital connectivity and material science advances are converging to transform urology disposables from passive commodity items into data-generating care components. Manufacturers are racing to embed sensing capabilities and sustainable materials before regulatory windows close.
Smart catheter systems incorporating pressure sensors and Bluetooth transmission modules are rewriting clinical workflow expectations. Academic medical centers in the United States are piloting these devices for post-operative monitoring, capturing real-time bladder pressure data that previously required invasive nursing assessment. The technology is compressing hospital length-of-stay metrics while creating new liability frameworks around data accuracy.
EU Medical Device Regulation post-market surveillance requirements are forcing manufacturers to maintain clinical follow-up databases for hydrophilic-coated devices. Danish and German producers are investing in patient registry infrastructure to satisfy notified body demands for long-term biocompatibility evidence. This regulatory burden is filtering out smaller tray assemblers lacking epidemiological tracking capabilities.
Hospital buying cooperatives are consolidating purchasing decisions for urology disposables under centralized materials management departments. United States health systems exceeding 50 facilities are negotiating multi-year sole-source agreements that displace traditional distributor relationships. This concentration is visible most acutely in the Southeast, where regional hospital networks are standardizing catheter specifications across affiliate campuses.
Urology Disposables Market Segmentation
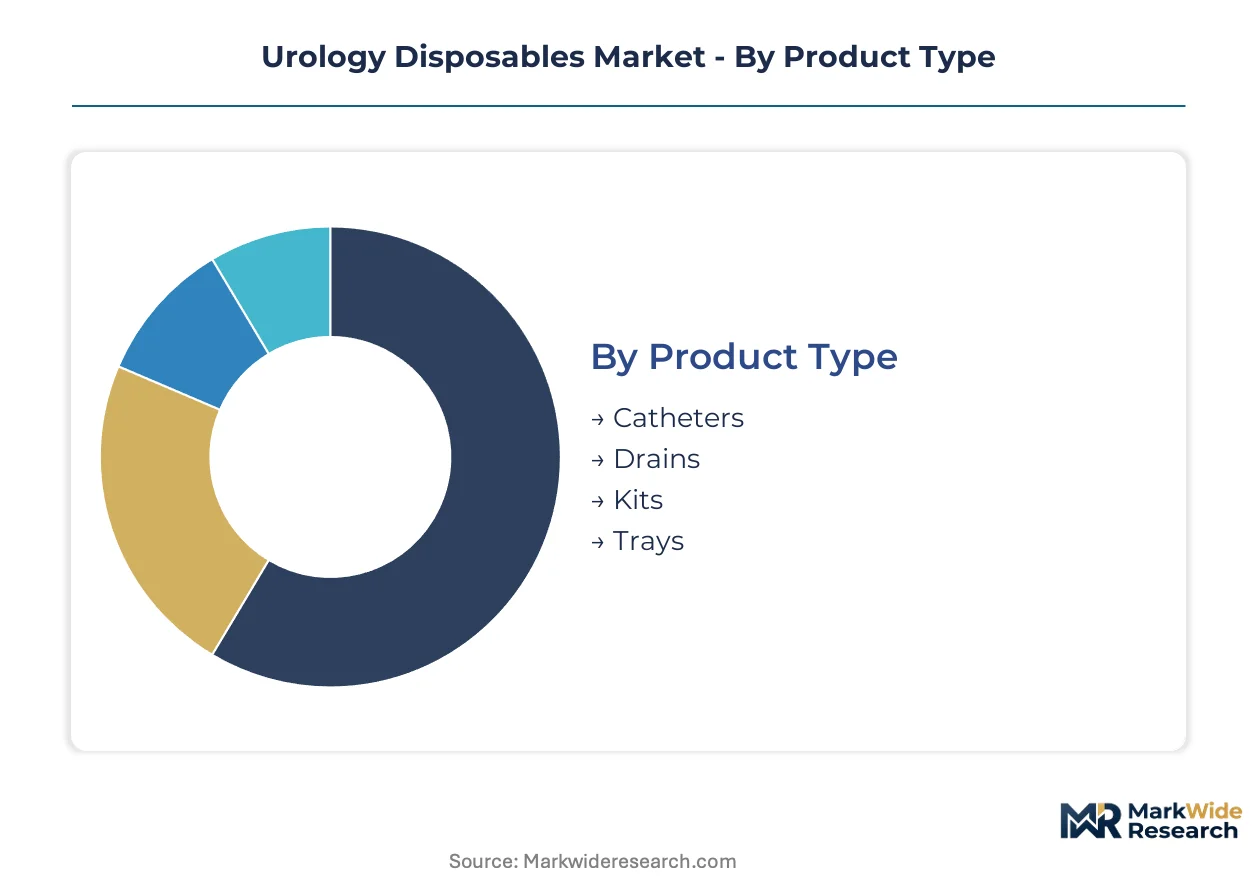
Urology disposables fragment across four distinct category axes that reshape procurement priorities and margin structures. Product type and material selection drive clinical performance specifications, while delivery mode and end-user concentration determine channel economics and regulatory exposure.
Product Type:
Hospital procurement departments evaluate product types through infection risk profiles and procedure throughput requirements rather than unit cost alone.
- Catheters:Manufactured via extrusion of latex, silicone, or PVC with hydrophilic surface coatings for lubricity. Demand concentrates in United States ambulatory surgery centers where same-day discharge protocols require reliable sterile supply chains and rapid turnover capacity.
- Drains:Constructed with radiopaque striping and graduated volume markings for post-surgical fluid management. Nephrostomy and surgical drain procurement is tightening in German university hospitals as EUDAMED traceability mandates elevate documentation burdens on reusable alternatives.
- Kits:Pre-configured sterile collections bundling catheters, drapes, and prep materials for specific procedures.
- Trays:Comprehensive procedural setups incorporating multiple device classes with standardized instrument layouts.
Volume sits with catheters; growth tilts toward procedure-specific kits.
Delivery Mode:
Reimbursement coding and care site certification requirements create sharp demand boundaries between acute and non-acute delivery channels.
- Inpatient:Acute care utilization governed by hospital-acquired infection protocols and nursing workflow standardization. United States health systems exceeding 50 facilities are consolidating catheter specifications across affiliate campuses under centralized materials management.
- Outpatient:Ambulatory surgery center consumption shaped by rapid turnover requirements and limited storage footprint. FDA 510(k) pathway clarification on single-use device equivalency is accelerating conversions from reprocessed catheters in these settings.
- Home Care:Patient-directed utilization supported by insurance authorization and caregiver training infrastructure.
- Telehealth:Remote monitoring integration enabling self-catheterization with clinical oversight through connected platforms.
Inpatient channels capture current volume dominance; telehealth-enabled home delivery is climbing the fastest as remote patient monitoring platforms mature.
End User:
Facility type determines sterility assurance requirements, inventory carrying costs, and liability exposure from device failure.
- Hospitals:High-throughput purchasers with dedicated sterile processing departments and infection control committees. Southeast United States regional hospital networks are standardizing disposable specifications across multi-campus systems under sole-source agreements.
- Clinics:Lower-volume settings with limited storage and constrained capital for inventory diversification.
- Nursing Homes:Long-term care facilities managing chronic catheterization with emphasis on staff training and complication reduction.
- Athletic Facilities:Specialized settings requiring rapid-response urinary management for trauma and hydration monitoring.
Procurement scale concentrates in hospitals; margin expansion is shifting toward nursing homes as bundled payment models extend post-acute accountability.
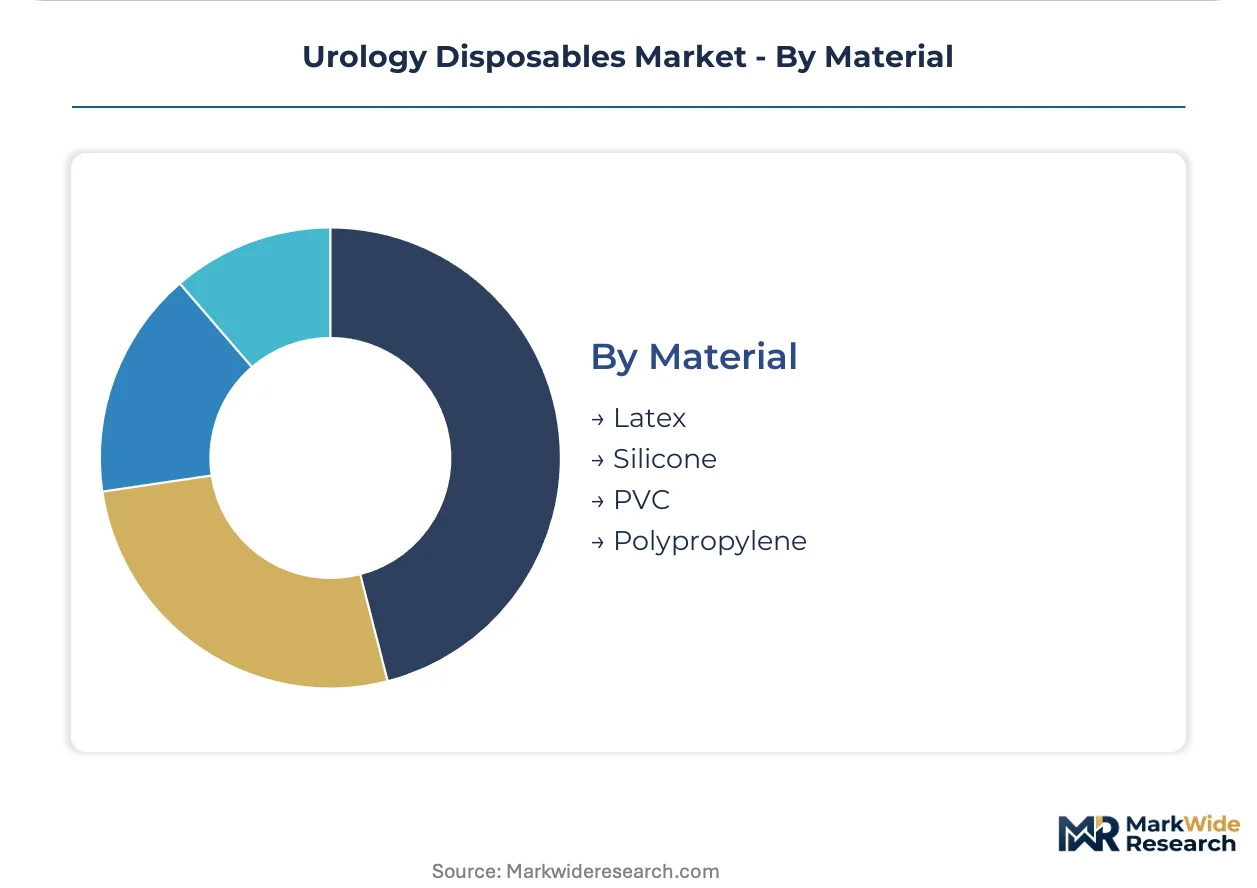
Material:
Biocompatibility duration and regulatory restrictions on plasticizers segment material selection into distinct price-performance tiers.
- Silicone:Platinum-cured elastomer grades meeting USP Class VI standards for long-term indwelling applications. REACH restrictions on phthalate plasticizers are displacing PVC in European tenders for extended-use devices, elevating silicone share in Danish and German hospital procurement.
- Latex:Natural rubber formulations with cost advantages offset by allergen sensitivity concerns in sensitized patient populations.
- PVC:Plasticized formulations facing substitution pressure from DEHP regulatory limits in pediatric and long-term applications.
- Polypropylene:Rigid thermoplastic for drainage components and connector housings requiring dimensional stability.
PVC retains volume leadership through cost position; silicone is gaining share fastest as REACH compliance timelines compress and biocompatibility requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty silicone monomer production concentrates in Germany and Japan, anchoring supply security for catheter manufacturers serving European and Asian hospital procurement networks.
United States
Ambulatory surgery centers in Florida and Texas are scaling same-day urological procedures, concentrating demand for compact disposable kits. FDA 510(k) pathway clarification on single-use device equivalency is accelerating hospital conversions from reprocessed catheters. Southeast regional hospital networks are standardizing catheter specifications across multi-campus systems under sole-source agreements negotiated in Atlanta and Charlotte.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are tightening nephrostomy drain procurement as EUDAMED traceability mandates elevate documentation burdens. REACH restrictions on DEHP plasticizers in PVC formulations are displacing conventional materials in extended-use device tenders. Automated silicone extrusion lines in Freiburg and Munich are reducing per-unit production costs for hydrophilic catheter coatings.
Denmark
Integrated manufacturing clusters near Copenhagen sustain premium positioning across hydrophilic catheter lines serving Nordic and North European hospital systems. EU Medical Device Regulation post-market surveillance requirements are forcing investment in patient registry infrastructure for long-term biocompatibility evidence. Danish producers are qualifying biodegradable polymer formulations to capture sustainability-mandated tenders.
Japan
Specialty chemical producers in the Kanto region control upstream silicone monomer supply, creating input cost volatility during semiconductor industry demand spikes. PMDA device registration timelines are extending market access for foreign kit assemblers. Tokyo academic medical centers are piloting smart catheter systems with pressure sensors for post-operative monitoring.
India
Domestic manufacturing incentives under the PLI scheme are attracting contract manufacturers to serve South Asian hospital procurement in Maharashtra and Gujarat. CDSCO medical device regulations are harmonizing with international standards for tray and kit assemblers. Delhi-NCR and Bangalore clusters are developing gamma-sterilization capacity to reduce finished goods quarantine periods.
Urology Disposables Market Competitive Landscape
Global majors compete with regional champions across material science and sterile manufacturing capabilities, producing a tiered structure where integrated silicone processors hold cost advantages over kit assemblers dependent on external supply. The vendor base separates into three strategic archetypes: vertically integrated elastomer specialists, procedure-focused disposable kit assemblers, and telehealth-enabled home care platform operators. Dominant competitive moves include backward integration into silicone compounding and strategic partnerships with ambulatory surgery center networks.
Within the integrated manufacturing tier, Coloplast A/S and Boston Scientific Corporation exemplify divergent geographic anchoring strategies, with the former representing European premium positioning and the latter occupying a position calibrated to United States ambulatory settings. Cook Medical sits within the specialist fabricator archetype, its physician training programs binding end-users to procedural tray configurations. Among scale-driven operators, Stryker Corporation and B. Braun Melsungen AG represent diversified medical technology conglomerates where urology disposables constitute a segment within broader surgical portfolios.
| Leading Market Players |
|---|
| Coloplast A/S |
| Boston Scientific Corporation |
| Olympus Corporation |
| B. Braun Melsungen AG |
| Stryker Corporation |
| Cook Medical |
| Rocamed |
| GPC Medical Ltd |
| Narang Medical Limited |
| Others |
Value Network & Pricing Analysis
Medical-grade silicone spot indices in Germany and Japan cascade through catheter manufacturing tiers, compressing margins for assemblers lacking backward integration into monomer supply while amplifying pricing power for integrated producers serving European hospital procurement networks.
Pricing Analysis
Warranty and technical service bundling separates premium catheter lines from unbundled commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks biocompatibility certification grade and sterilization validation depth. Pricing pressure stems from hospital buying cooperative consolidation in the United States Southeast, where multi-campus sole-source agreements displace distributor markups. Ambulatory surgery centers exhibit highest price sensitivity due to rapid turnover requirements and limited storage capital; integrated silicone processors face lowest sensitivity given captive cost positions.
Supply Chain Analysis
Freight cost volatility from Asia-Europe lanes disrupts just-in-time tray assembly schedules for European kit manufacturers. Upstream concentration rests on Germany and Japan for specialty silicone monomers, China for PVC resin and gamma-sterilization equipment, and Denmark for hydrophilic coating chemistry. Single-source vulnerability concentrates in cobalt-60 isotope supply for terminal sterilization. Distribution runs through health system materials management departments consolidating vendor relationships under multi-year agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliance-capable manufacturers as EU MDR recertification timelines filter out smaller tray assemblers lacking epidemiological tracking infrastructure.
For Market Incumbents: Anticipate notified body backlogs extending competitive moats for early-certified producers. Secure gamma-sterilization capacity through long-term cobalt-60 sourcing agreements before facility licensing delays worsen. Invest in patient registry infrastructure to satisfy post-market surveillance demands for hydrophilic-coated devices, displacing smaller competitors unable to bear epidemiological tracking costs.
For New Entrants and Emerging Players: Begin with biodegradable polymer catheter lines targeting sustainability-mandated European tenders where incumbents face material substitution lag. Penetrate India's domestic manufacturing incentives under PLI scheme subsidies before contract manufacturer saturation. Deploy direct hospital contracting models bypassing traditional distributor relationships in South Asian metropolitan clusters.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap silicone extrusion specialists in Germany with underutilized automated lines and existing ISO 13485 certification. Long-term viability hinges on upstream integration depth and regulatory dossier completeness rather than brand equity alone. Monitor EUDAMED traceability mandate enforcement as inflection indicator for compliance-cost driven consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Compounding | Captive monomer supply insulates German catheter producers from semiconductor industry demand spikes. |
| Hospital System Partnership | Southeast United States multi-campus sole-source agreements displace traditional distributor relationships. |
| CE Marking Pathway Acceleration | Early EU MDR recertification creates 18-24 month competitive moats against backlog-constrained rivals. |
| Software Companion Development | Bluetooth-enabled pressure sensors in smart catheters capture real-time data for post-operative monitoring. |
| Reimbursement Strategy | Telehealth-integrated self-catheterization protocols unlock recurring revenue outside acute care settings. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR notified body certification records, and hospital procurement databases, complemented by interviews with catheter manufacturing executives, hospital materials management directors, GPO contracts managers, and biomedical engineers specializing in infection control. Secondary sources included EUDAMED traceability filings, REACH restriction updates, and customs data for medical-grade silicone trade flows. Bottom-up production capacity modeling triangulated against top-down hospital expenditure tracking.
Segment-level demand projections across product type, material grade, delivery mode, and end-user facility category fed into analytical framework spanning the projection horizon. CAGRs derived from volume-outpatient procedure correlations, silicone price elasticity coefficients, and regulatory timeline scenario weights. Industry-specific inputs incorporated ambulatory surgery center expansion rates and gamma-sterilization facility licensing backlogs.
Underlying measurement precision varies by segment; catheter volume estimates carry tighter precision than emerging telehealth-enabled home care categories. Forecasts reflect assumptions around regulatory enforcement intensity and hospital consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Global Hydronephrosis Market
Urology
Continence Care Market
Urology
Botulinum Toxin in Urology Market
Urology
Urinary Catheters Market
Urology
North America Transrectal Ultrasound Market
Urology
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market
Urology
Ureterorenoscopes Market
Urology
India Urology Device Market
Urology
Urinary Tract Infection (UTI) Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Self-Intermittent Catheters Market
Urology
Nephrology and Urology Incontinence Devices Market
Urology
Urethral Stricture Market
Urology
Urology Lasers Market
Urology
Urology Robotic Surgery Market
Urology
Global Bladder Cancer Market