
 North America Bladder Disorders Market | 2026-2036
North America Bladder Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bladder Disorders Market Analytics
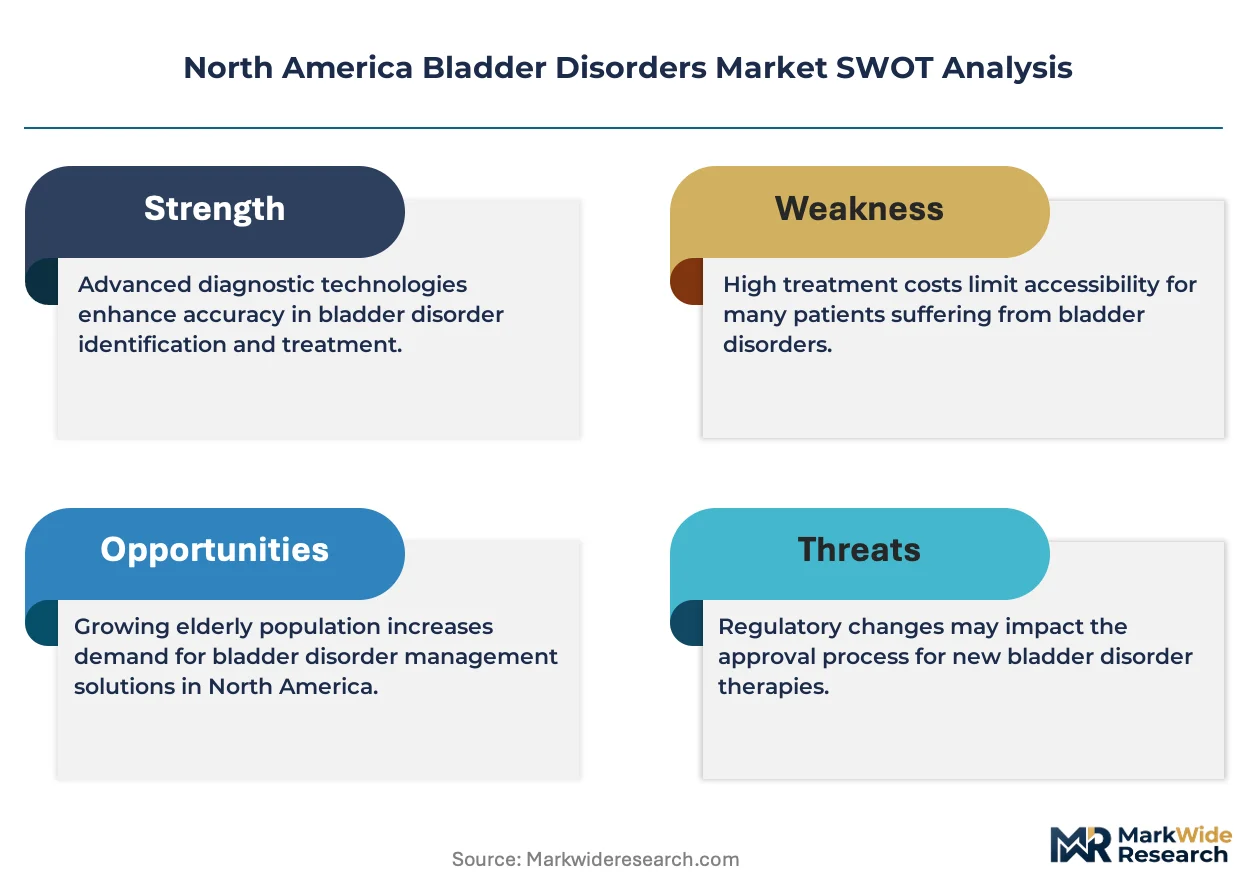
Buyer concentration among integrated delivery networks is pivoting procurement toward long-term supply agreements with device manufacturers. Pfizer Inc leverages its established urology portfolio to sustain formulary positioning across major hospital systems. Astellas Pharma Inc anchors its presence through specialty distribution channels serving high-volume outpatient clinics. Medtronic Plc dominates the neuromodulation segment with sacral nerve stimulation systems that compete directly against pharmaceutical management protocols.
Bladder disorders encompass a spectrum of dysfunctional conditions affecting urinary storage and voiding, including overactive bladder, interstitial cystitis, and neurogenic bladder, typically diagnosed through urodynamic testing, cystoscopy, and patient-reported outcome instruments measuring frequency, urgency, and incontinence episodes. The condition's primary commercial purpose centers on restoring continence, preventing upper tract deterioration, and improving quality-of-life metrics that determine reimbursement thresholds across public and private payers. Medications retain the largest revenue pool despite patent cliffs, while surgical devices represent the fastest-expanding margin category as minimally invasive neuromodulation displaces chronic pharmaceutical regimens. Home Care as an end-user channel is capturing disproportionate growth as catheter and remote monitoring technologies enable shift from institutional to domiciliary management.
The FDA governs premarket approval for implantable neuromodulation devices through its neurological devices panel, while CMS reimbursement determinations directly shape provider adoption thresholds for novel interventions. Health Canada and the Canadian Agency for Drugs and Technologies in Health establish parallel evidentiary standards that manufacturers must satisfy for cross-border market access. Stakeholders must monitor evolving FDA guidance on breakthrough device designation criteria and CMS national coverage determinations for digital therapeutics as these frameworks will determine which modalities secure sustainable reimbursement pathways.
Market Dynamics
Integrated delivery networks across the United States are consolidating procurement authority, forcing device manufacturers to restructure commercial relationships around multi-year supply agreements rather than transactional sales.
Growth Catalysts
- Medicare Advantage expansion:CMS reimbursement policies for sacral nerve stimulation procedures are expanding eligible patient pools across the Northeast and Midwest, accelerating provider adoption of implantable neuromodulation systems.
- Digital therapeutics pathways:FDA breakthrough device designation criteria are compressing premarket review timelines for bladder monitoring applications, enabling faster commercialization of remote patient management platforms.
- Home care infrastructure:Catheter technology advances and telehealth reimbursement codes are shifting post-surgical monitoring from hospitals to domiciliary settings, creating new device deployment channels.
Market Restraints
- Silicone supply concentration:Implantable device manufacturers depend on concentrated specialty polymer suppliers in Germany and Japan, exposing production schedules to raw material allocation disruptions.
- Neuromodulation reimbursement variability:State-level Medicaid prior authorization requirements create patchwork coverage gaps that delay patient access to sacral nerve stimulation procedures in the Southeastern United States.
- Antimuscarinic substitution pressure:Generic pharmaceutical alternatives to branded overactive bladder medications are compressing pricing power for conservative management protocols, limiting device therapy conversion economics.
Strategic Opportunities
- Canadian market underpenetration:Health Canada's parallel review pathways with FDA clearances create accelerated entry potential for neuromodulation systems already approved in the United States.
- Pediatric neurogenic bladder applications:Sacral nerve stimulation protocols are expanding beyond adult overactive bladder into congenital spinal cord defect populations, opening specialty referral center partnerships.
- Remote monitoring integration:Bluetooth-enabled uroflowmetry devices are converging with existing cardiac and diabetes remote patient monitoring infrastructure, leveraging established reimbursement codes.
Industry Challenges
- Implantable device servicing expertise:Sacral nerve stimulation reprogramming and battery replacement procedures require specialized urological surgical training that academic medical centers struggle to scale across community hospital networks.
- Legacy EHR integration complexity:Digital therapeutic platforms for bladder diary management face interoperability friction with Cerner and Epic systems that dominate large integrated delivery network installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bladder Disorders Market |
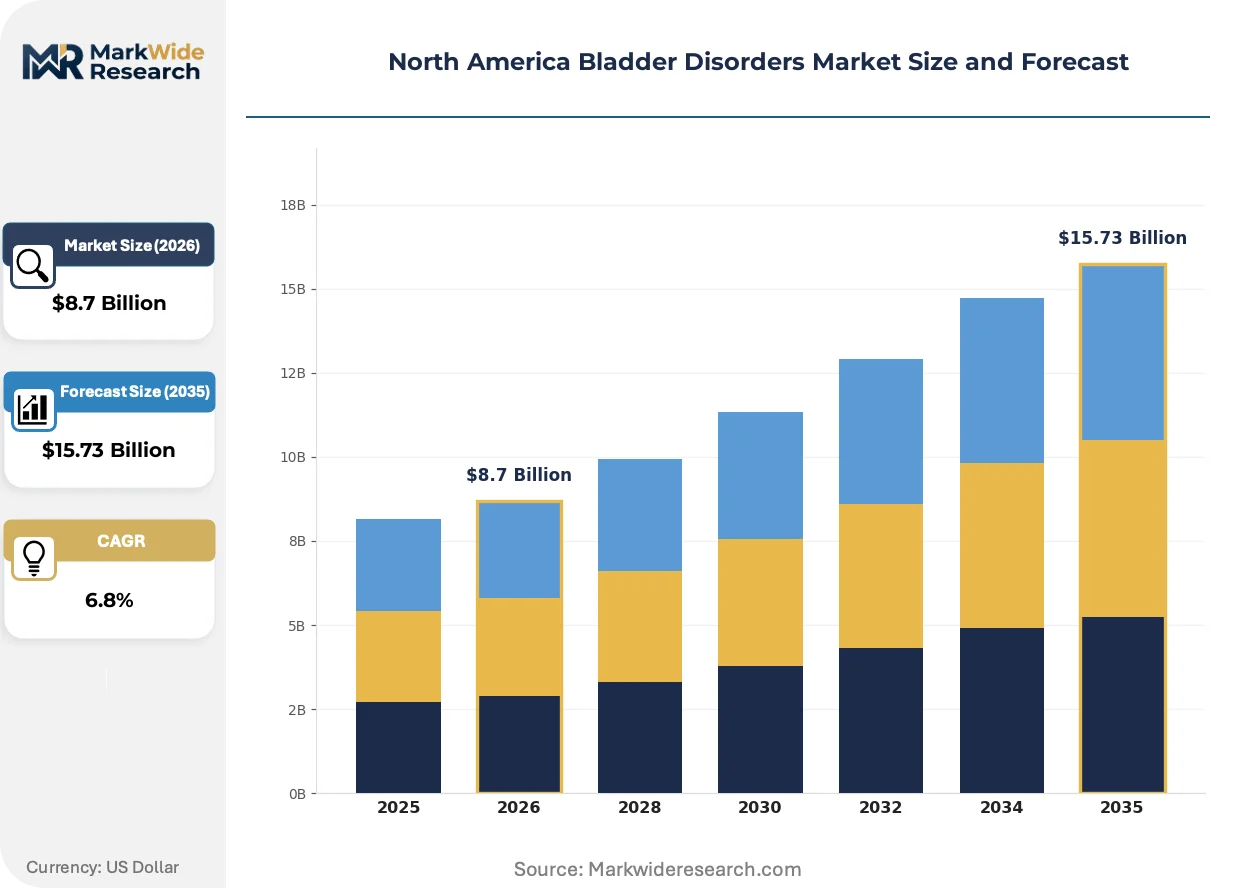
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Catheters, Surgical Devices, Diagnostics End User: Hospitals, Clinics, Home Care, Long-Term Care Treatment Method: Medication, Surgery, Physical Therapy, Behavioral Therapy Age Group: Pediatric, Adult, Geriatric, Others |
| Companies Covered | Pfizer Inc, Astellas Pharma Inc, AbbVie Inc, Teva Pharmaceutical Industries Ltd, Medtronic Plc, Johnson & Johnson, Endo International, Hisamitsu Pharmaceutical Co., Inc., Axonics Modulation Technologies, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bladder Disorders Market Evolving Landscape
Neuromodulation hardware and digital diagnostic platforms are converging to create closed-loop therapeutic systems that challenge traditional pharmaceutical-first treatment hierarchies in urological practice.
Closed-loop sacral nerve stimulation systems are integrating real-time detrusor pressure sensing with automated amplitude adjustment, enabling personalized therapy delivery without manual physician reprogramming. Academic medical centers in Boston and Cleveland are piloting these systems for refractory overactive bladder populations. The technology is integrating pharmaceutical management and device therapy into unified care pathways that compress total cost-of-ownership calculations for payers.
FDA's evolving guidance on breakthrough device designation for neurological indications is compressing premarket approval timelines for novel implantable platforms. The agency's neurological devices panel has streamlined evidentiary requirements for predicate device comparisons in the sacral nerve stimulation category. Manufacturers targeting the Medicare Advantage segment are restructuring clinical trial protocols to satisfy both FDA clearance and CMS national coverage determination evidentiary standards simultaneously.
Hospital procurement departments are consolidating urological device purchasing through single-source agreements that bundle catheters, neuromodulation systems, and disposable accessories. Large integrated delivery networks in Texas and California are displacing traditional distributor relationships with direct manufacturer contracts that include inventory management and consignment arrangements. This concentration is most visible in Medicare Advantage–dominated markets where total cost-per-procedure metrics determine formulary positioning.
North America Bladder Disorders Market Segmentation
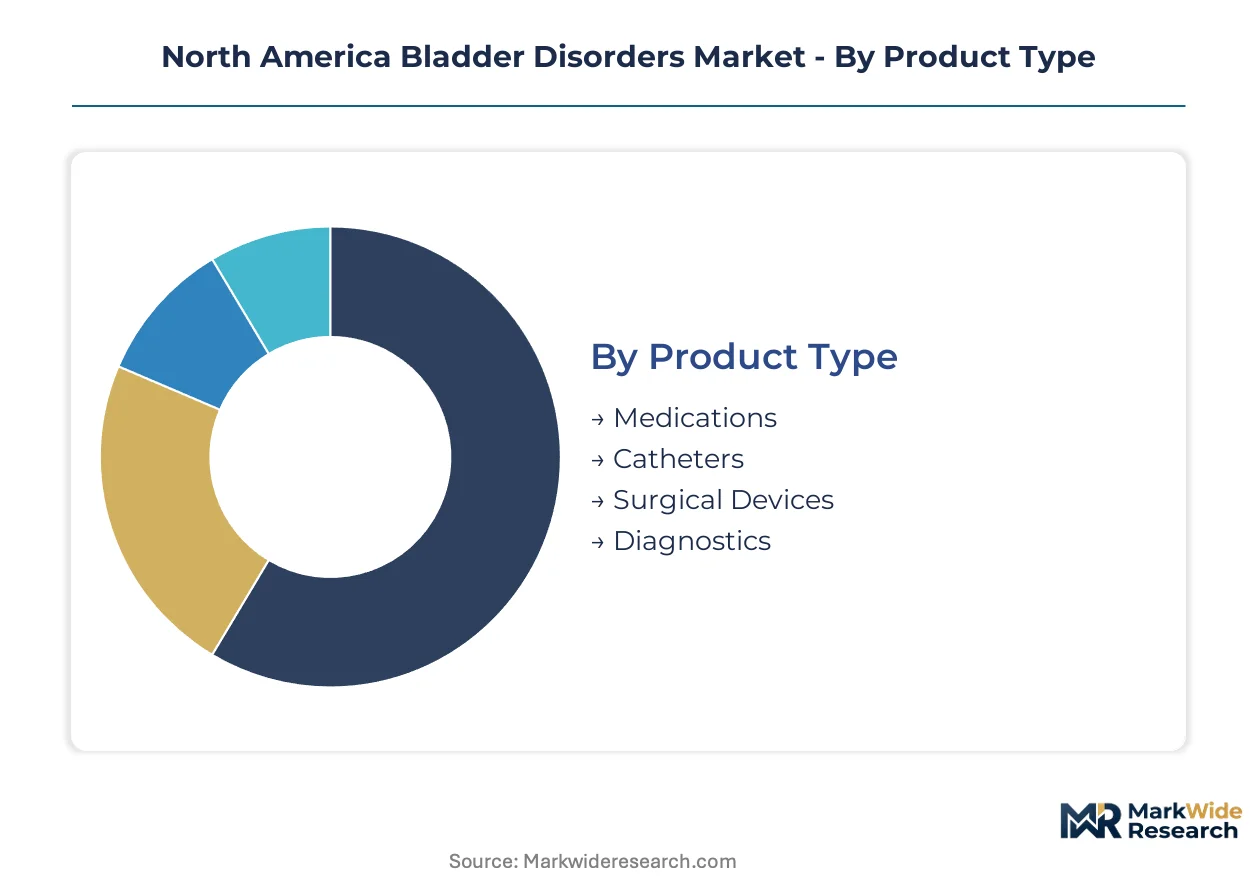
Segmentation in the North America bladder disorders market reveals distinct procurement patterns across product categories and care settings. Integrated delivery networks prioritize segments that compress total cost-of-care while specialty distributors focus on high-margin niches that require clinical training support.
Product Type:
Medications dominate absolute volume while surgical devices command premium pricing and fastest margin expansion.
- Medications:Antimuscarinics and beta-3 agonists constitute the foundational pharmaceutical layer for overactive bladder management. Demand concentrates in Medicare Advantage formularies across the Northeast and Midwest, where prior authorization requirements favor established brands with proven adherence data.
- Surgical Devices:Implantable neuromodulation systems and minimally invasive slings displace chronic pharmaceutical regimens in refractory cases. Academic medical centers in Boston and Cleveland drive adoption of closed-loop sacral nerve stimulation platforms that integrate real-time detrusor sensing.
- Catheters:Intermittent and indwelling catheter systems enable the shift from institutional to domiciliary management that Home Care channels are capturing.
- Diagnostics:Urodynamic testing equipment and cystoscopy platforms anchor initial disease characterization in hospital outpatient departments.
Mature deployment sits with Medications. Newer deployment is concentrated in Surgical Devices.
End User:
Procurement authority is migrating toward settings that demonstrate measurable outcomes per episode of care.
- Hospitals:Large academic medical centers and integrated delivery networks consolidate purchasing power through multi-year supply agreements. Texas and California systems are displacing traditional distributors with direct manufacturer contracts that bundle devices and disposable accessories.
- Home Care:Bluetooth-enabled uroflowmetry and remote monitoring platforms are climbing the fastest as telehealth reimbursement codes mature. Domiciliary catheter management reduces readmission penalties that Medicare Advantage plans track closely.
- Clinics:High-volume urology and gynecology outpatient practices anchor specialty pharmaceutical distribution through Astellas and Pfizer field forces.
- Long-Term Care:Skilled nursing facilities manage neurogenic bladder populations with protocolized catheterization schedules that emphasize infection prevention.
Procurement maturity centers on Hospitals. Capability expansion is accelerating fastest in Home Care.
Treatment Method:
Reimbursement pathways determine which modalities achieve sustainable adoption across payer categories.
- Medication:Conservative first-line protocols retain the largest patient volume despite generic substitution pressure on antimuscarinic pricing.
- Surgery:Sacral nerve stimulation and sling procedures gain share where CMS national coverage determinations and Medicare Advantage medical policy align on evidentiary standards.
- Physical Therapy:Pelvic floor rehabilitation programs expand through dedicated continence clinics that credential specialized therapists.
- Behavioral Therapy:Digital bladder diary applications and biofeedback platforms face EHR interoperability friction with dominant Cerner and Epic installations.
Established reimbursement sits with Medication. Emerging validation is concentrated in Surgery.
Age Group:
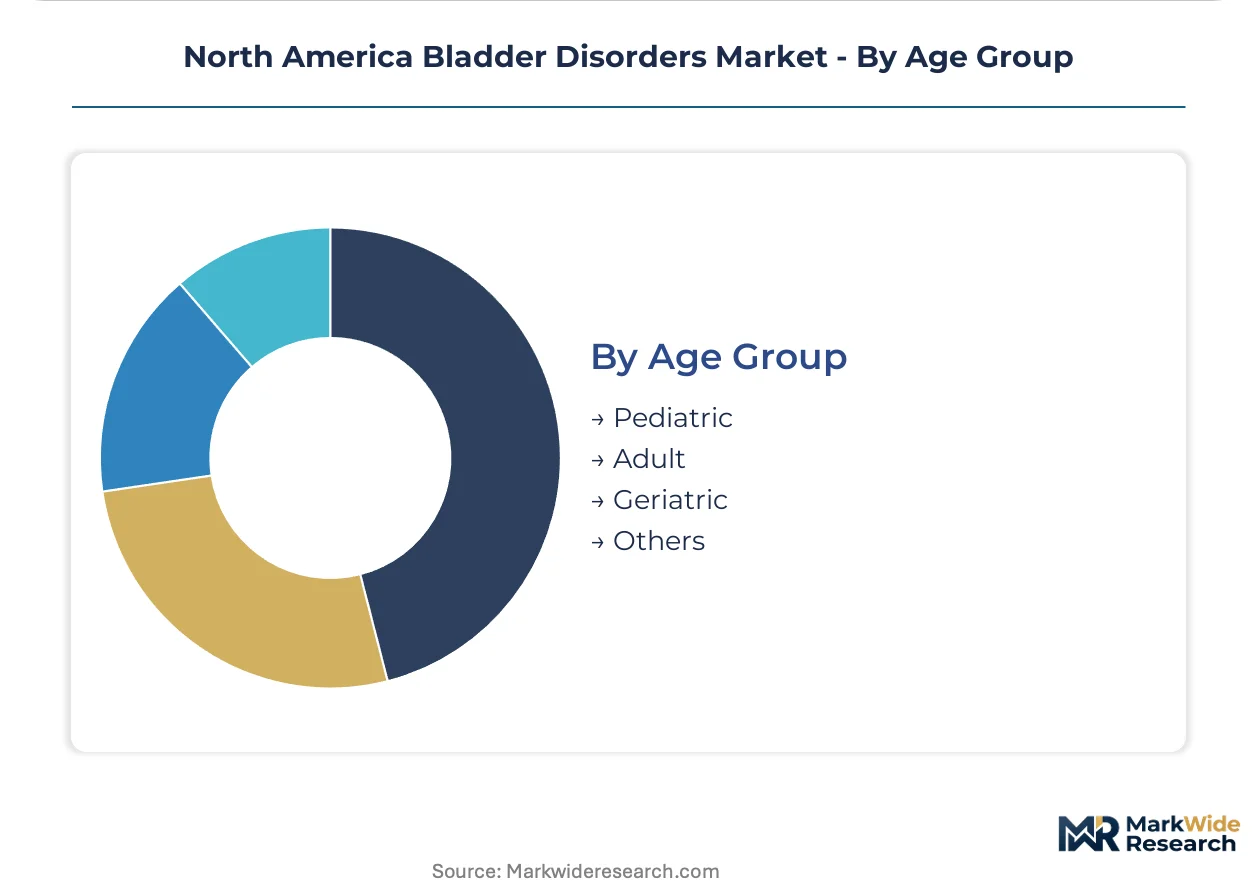
Disease prevalence and treatment tolerance create distinct commercial requirements across demographic bands.
- Geriatric:Polypharmacy concerns and fall risk drive demand for device-based alternatives to antimuscarinic cognitive side effects in Medicare populations.
- Adult:Working-age patients with overactive bladder prioritize discrete, minimally disruptive interventions that preserve employment productivity.
- Pediatric:Congenital spinal cord defects and neurogenic bladder conditions open specialty referral partnerships for sacral nerve stimulation protocols beyond adult indications.
- Others:Transitional age populations with complex comorbidities require coordinated urology-neurology care pathways.
Clinical evidence maturity sits with Geriatric. Protocol expansion is advancing fastest in Pediatric.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in the North America Bladder Disorders Market centers on Medicare Advantage penetration and academic medical center procurement networks. The United States dominates absolute volume, while Canada offers parallel regulatory pathways for device manufacturers seeking cross-border expansion. Mexico represents an emerging access point for catheter manufacturing and distribution logistics.
United States
Medicare Advantage plans in the Northeast and Midwest drive sacral nerve stimulation procedure volumes through aligned medical policy frameworks. FDA breakthrough device designation criteria compress premarket timelines for neuromodulation systems targeting refractory overactive bladder. Boston and Cleveland academic medical centers pilot closed-loop stimulation platforms that integrate real-time detrusor pressure sensing with automated therapy adjustment.
Canada
Health Canada parallel review pathways with FDA clearances enable accelerated market entry for implantable neuromodulation devices already approved south of the border. The Canadian Agency for Drugs and Technologies in Health establishes evidentiary standards that manufacturers must satisfy for provincial formulary inclusion. Ontario and Quebec health systems concentrate procurement authority through centralized hospital networks that favor long-term supply agreements over transactional purchasing.
Mexico
Private hospital chains in Mexico City and Monterrey anchor demand for urological surgical devices serving affluent patient segments with cross-border treatment preferences. COFEPRIS regulatory frameworks for medical devices are converging toward international harmonization standards that facilitate importation of FDA-cleared platforms. Northern border states function as distribution hubs for catheter and disposable accessory flows into southwestern United States markets.
North America Bladder Disorders Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital therapeutic and remote monitoring adjacencies that challenge pharmaceutical-first protocols. The vendor base stratifies across multinational pharmaceutical conglomerates with urology portfolios, dedicated neuromodulation device specialists, and catheter manufacturers serving institutional and domiciliary channels. Strategic archetypes include formulary defenders leveraging field force relationships, technology licensors seeking breakthrough device designations, and supply chain integrators bundling disposables with capital equipment. Competitive moves center on multi-year integrated delivery network contracting and portfolio diversification into home care monitoring platforms.
Among the named participants, Pfizer Inc and Astellas Pharma Inc anchor the pharmaceutical tier with established urology field forces, while Medtronic Plc exemplifies the device-specialist archetype in implantable neuromodulation. These three entities represent distinct competitive positions: formulary-based pharmaceutical management, specialty distribution channel control, and surgical device therapy displacement of chronic medication regimens.
| Leading Market Players |
|---|
| Pfizer Inc |
| Astellas Pharma Inc |
| AbbVie Inc |
| Teva Pharmaceutical Industries Ltd |
| Medtronic Plc |
| Johnson & Johnson |
| Endo International |
| Hisamitsu Pharmaceutical Co., Inc. |
| Axonics Modulation Technologies, Inc |
| Others |
Value Network & Pricing Analysis
Specialized urological surgical training concentration in the Northeast and Midwest creates labor-cost differentials that widen pricing-tier spreads between academic medical centers and community hospital networks. Medicare Advantage reimbursement compression in the Southeast further accentuates these regional price gradients for sacral nerve stimulation procedures.
Pricing Analysis
Volume concentrates in generic antimuscarinic medications while margins accrue to implantable neuromodulation systems. Three-tier pricing structure across premium closed-loop stimulation platforms, standard sacral nerve generators, and economy catheter systems differentiates by clinical sophistication and after-sales reprogramming service bundling. Pricing pressure stems from Medicaid prior authorization variability that delays device therapy conversion in the Southeastern United States. Community hospital networks exhibit highest price sensitivity due to capital equipment budget constraints, while integrated delivery networks leverage volume scale for preferential contracting.
Supply Chain Analysis
Silicone polymer supply rests on specialty chemical producers in Germany and Japan, exposing implantable device manufacturers to raw material allocation disruptions. Production of implantable pulse generators and lead assemblies concentrates in the United States, Ireland, and Costa Rica. Single-source vulnerability characterizes the neuromodulation battery cell tier, where lithium-thionyl chloride chemistry depends on concentrated Asian suppliers. Distribution runs through integrated delivery network consignment arrangements that displace traditional medical-surgical distributors in Texas and California procurement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where control over catheter manufacturing and remote monitoring software development determines margin capture. Players are pursuing downstream integration into home care service delivery to lock in recurring revenue streams.
For Market Incumbents: To counter generic pharmaceutical substitution pressure on antimuscarinic portfolios, Pfizer and Astellas should deepen backward integration into active pharmaceutical ingredient sourcing for beta-3 agonist molecules. Device specialists like Medtronic must secure captive supply agreements for lithium-thionyl chloride battery cells to mitigate single-source exposure. Hospital system partnership density in Medicare Advantage corridors represents the priority defensive lever.
For New Entrants and Emerging Players: Underserved pediatric neurogenic bladder populations in congenital spinal cord defect referral centers offer white-space penetration with lower competitive intensity than adult overactive bladder markets. Canadian provincial health systems present accelerated entry potential through Health Canada parallel review pathways for FDA-cleared platforms. Digital therapeutic developers should pursue Bluetooth-enabled uroflowmetry integration with existing cardiac remote patient monitoring infrastructure to leverage established reimbursement codes.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated catheter manufacturers given home care channel expansion and Medicare readmission penalty avoidance economics. Long-term viability over the next decade favors assets with software companion development capabilities that enable outcome-based contracting with integrated delivery networks. FDA breakthrough device designation velocity for neuromodulation platforms warrants ongoing watch as an inflection indicator for premium valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year supply agreements with Texas and California integrated delivery networks displace distributor intermediaries. |
| Software Companion Development | Bladder diary applications that achieve Epic and Cerner interoperability unlock Medicare Advantage remote monitoring reimbursement. |
| FDA Breakthrough Designation Pathway | Compressed premarket timelines for closed-loop sacral nerve stimulation accelerate commercialization against pharmaceutical protocols. |
| Backward Integration into Battery Supply | In-house lithium-thionyl chloride sourcing mitigates Asian supplier concentration risk for implantable pulse generators. |
| Reimbursement Strategy | CMS national coverage determination alignment with Medicare Advantage medical policy expands eligible patient pools for device therapy. |
Research Methodology
FDA 510(k) filings, CMS national coverage determinations, and hospital procurement databases formed the secondary backbone, supplemented by Medicare Advantage formulary data and Health Canada device licensing records. Primary interviews with urology department chairs, integrated delivery network procurement directors, biomedical engineers, and GPO contracts managers validated demand-side assumptions. Bottom-up procedure volume estimates triangulated against top-down pharmaceutical dispensing data across the analysis window.
Historical trendline analysis of sacral nerve stimulation implant volumes, antimuscarinic prescription trends, and catheter unit shipments informed baseline trajectory development. Segmentation modeling incorporated product type, end-user channel, treatment method, and age group dimensions alongside regional regulatory cluster variations. CAGRs were derived from fitted growth curves adjusted for Medicare Advantage penetration rates and FDA breakthrough designation velocity. Forecast inputs included Medicaid prior authorization policy shifts and telehealth reimbursement code expansion timelines.
Revisions become necessary when FDA guidance on breakthrough device criteria shifts, CMS national coverage determinations exclude novel neuromodulation indications, or silicone supply disruptions from German and Japanese producers materialize. Forecasts reflect assumptions about Medicare Advantage medical policy alignment and hospital procurement consolidation trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Global Prostate Health Market
Urology
Uropathy Treatment Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
North America Transrectal Ultrasound Market
Urology
Suprapubic Catheters Market
Urology
Self-Intermittent Catheters Market
Urology
Voiding Cystourethrogram Market
Urology
Penile Cancer Market
Urology
Varicocele Treatment Market
Urology
Global Lithotripsy Market
Urology
Urinary Catheters Market
Urology
Prostate Cancer Treatment Market
Urology
Male Urinary Incontinence Market
Urology
Urinary Incontinence Therapeutics Market
Urology
Complicated Urinary Tract Infections Treatment Market
Urology
Urology Laser Fibers Market