
 Global Catheters Market | 2026-2036
Global Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Catheters Market Analysis
Home care is hardening as the fastest-expanding end-use channel for catheter manufacturers. Boston Scientific Corporation leverages its interventional cardiology portfolio to anchor premium positioning in cardiovascular catheters. Medtronic sustains broad manufacturing scale across neurovascular and cardiac rhythm management lines. Johnson & Johnson competes through its Ethicon surgical access devices and infection control technologies.
A catheter is a hollow, flexible tube inserted into body cavities, vessels, or ducts to drain fluids, administer therapeutics, or enable diagnostic access; most clinical variants employ medical-grade silicone, latex, or thermoplastic polyurethane with lumen diameters calibrated to flow-rate requirements and dwell-time tolerances. Indwelling catheters dominate hospital procurement volumes due to extended dwell protocols in intensive care, while specialty catheters command superior margins through procedure-specific designs in electrophysiology and neurointervention. Silicone material formulations are displacing latex in chronic applications because of superior biocompatibility profiles and reduced protein allergen risks.
The FDA enforces Class II and Class III device controls through 510(k) and PMA pathways that govern sterility validation and material fatigue testing for extended-use catheters. The EU MDR and ISO 13485 quality management standards are reshaping market access by mandating clinical evidence portfolios and post-market surveillance systems for all sterile invasive devices. Stakeholders must monitor reimbursement code consolidation in major markets and align product development with antimicrobial surface technologies that address catheter-associated infection protocols.
Market Dynamics
The EU MDR is compressing market access timelines by mandating clinical evidence portfolios for all sterile invasive devices, forcing manufacturers to restructure quality management systems and post-market surveillance infrastructure ahead of 2026 compliance deadlines.
Growth Catalysts
- Home care migration:Patients in the United States, Germany, and Japan are shifting from institutional settings toward self-managed catheterization, expanding addressable volume for disposable and intermittent catheter lines.
- EU MDR sterility mandates:The framework's tightened biocompatibility requirements for long-dwelling devices is filtering out non-compliant suppliers and consolidating procurement toward certified manufacturers.
- Silicone material transition:Medical-grade silicone formulations are displacing latex in chronic applications due to superior biocompatibility profiles and reduced protein allergen risks.
Market Restraints
- Medical-grade polymer cost volatility:Thermoplastic polyurethane and silicone feedstock prices fluctuate with petrochemical input cycles, compressing margin stability for high-volume manufacturers.
- Single-source sterilization concentration:Gamma and ethylene oxide sterilization capacity concentrates in the United States and Germany, creating geographic supply risk for European and Asian device makers.
- Reimbursement code consolidation:CMS and national health technology assessment bodies in Japan and Germany are bundling catheter reimbursement into procedure codes, limiting price realization for standalone device sales.
Strategic Opportunities
- India outpatient expansion:The country's central pharmaceutical regulator is streamlining CDSCO medical device licensing, opening private hospital and diagnostic center channels for cardiovascular and urological catheter suppliers.
- Antimicrobial surface convergence:Silver-ion and antibiotic-impregnated polymer technologies are converging with hydrophilic coating processes to address catheter-associated urinary tract infection protocols in intensive care settings.
- Direct-to-patient distribution:E-commerce and specialty pharmacy channels are bypassing traditional hospital procurement in Germany and Japan for intermittent catheter users managing neurogenic bladder conditions.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity and sensitization studies face bottlenecks at contract research organizations, extending product development timelines for novel material formulations.
- Legacy ERP integration:Manufacturers are reconfiguring supply chain and quality management software to capture EU MDR-required post-market surveillance data and unique device identification traceability.
- Ethylene oxide sterilization transition:EPA emissions restrictions and facility closures in the United States are forcing rapid validation of alternative terminal sterilization methods without compromising sterility assurance levels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Catheters Market |
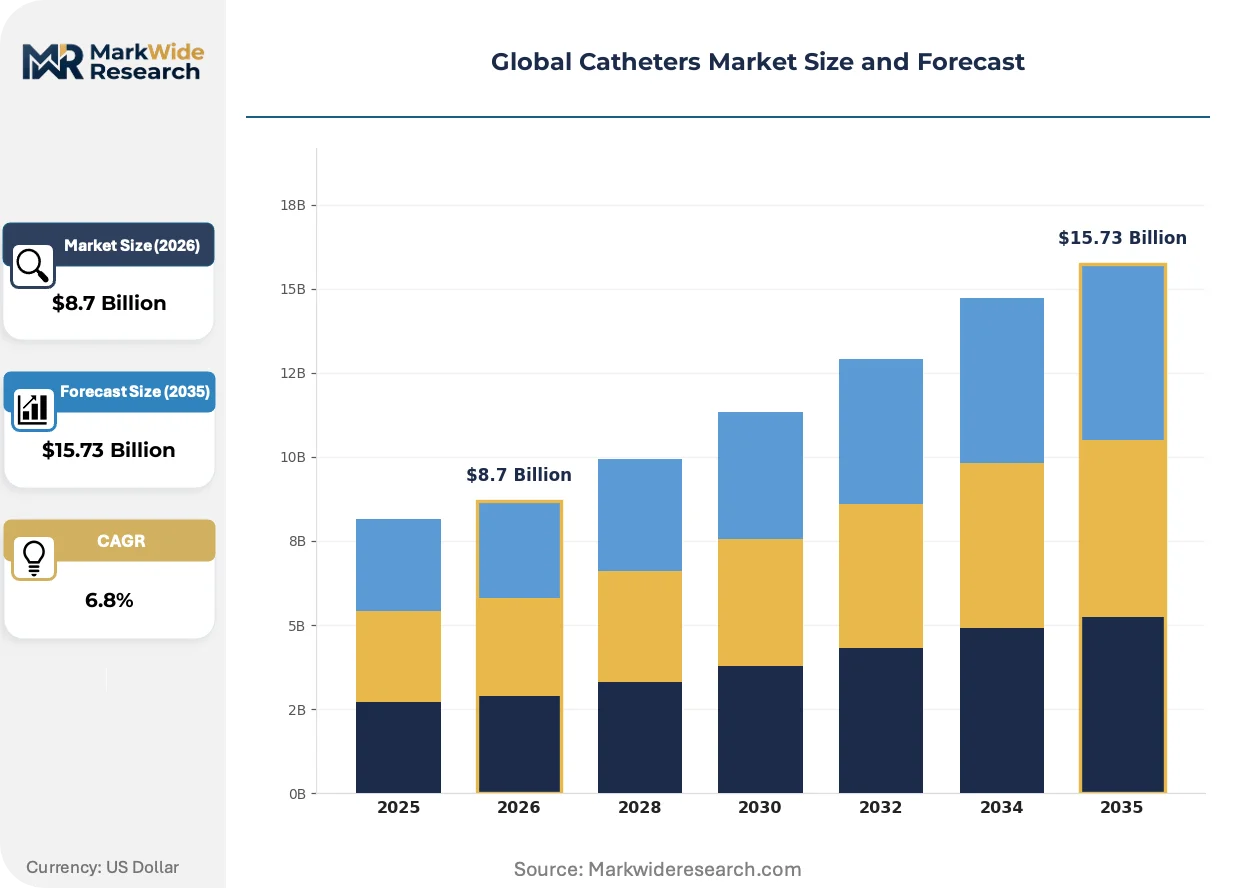
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intermittent Catheters, Indwelling Catheters, Condom Catheters, Specialty Catheters End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers Material: Latex, Silicone, PVC, Teflon Application: Urinary Incontinence, Hemodialysis, Cardiovascular Procedures, Surgical Procedures |
| Companies Covered | Boston Scientific Corporation, Medtronic, Johnson & Johnson, Becton Dickinson and Company, Abbott Laboratories, Teleflex Incorporated, Stryker Corporation, Terumo Corporation, Hollister Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Catheters Market Emerging Trajectories
Digital integration and material science advances are restructuring how catheter performance is validated, reimbursed, and delivered across acute and ambulatory settings.
Robotic-assisted catheter navigation systems is automating precision placement in electrophysiology and neurointerventional procedures, with academic medical centers in Germany and Japan piloting integration into standard ablation workflows. Hospital capital committees are approving these platforms at measured pace due to reimbursement uncertainty and training overhead. The technology is automating physician workflow standardization while compressing procedure time variability and fluoroscopy exposure.
REACH substance restrictions and EU MDR Article 10 technical documentation requirements are forcing reformulation of plasticizers and stabilizers in PVC-based devices, with notified bodies demanding extended migration testing for phthalate alternatives. Compounders in the Netherlands and Switzerland are scaling medical-grade TPU and copolyester elastomer capacity to serve catheter extrusion houses. Cardiovascular and neonatal segments face the steepest compliance cost escalation due to longest dwell-time exposure profiles.
Hospital buying groups in the United States are consolidating catheter procurement across IDN networks, displacing individual facility contracting with multi-year sole-source agreements tied to utilization guarantees and vendor-managed inventory. GPOs are extracting price concessions in exchange for volume commitments and data sharing on consumption patterns. This concentration is most visible in cardiovascular and peripheral intervention catheters where Boston Scientific and Medtronic compete for exclusive supply contracts.
Global Catheters Market Segmentation
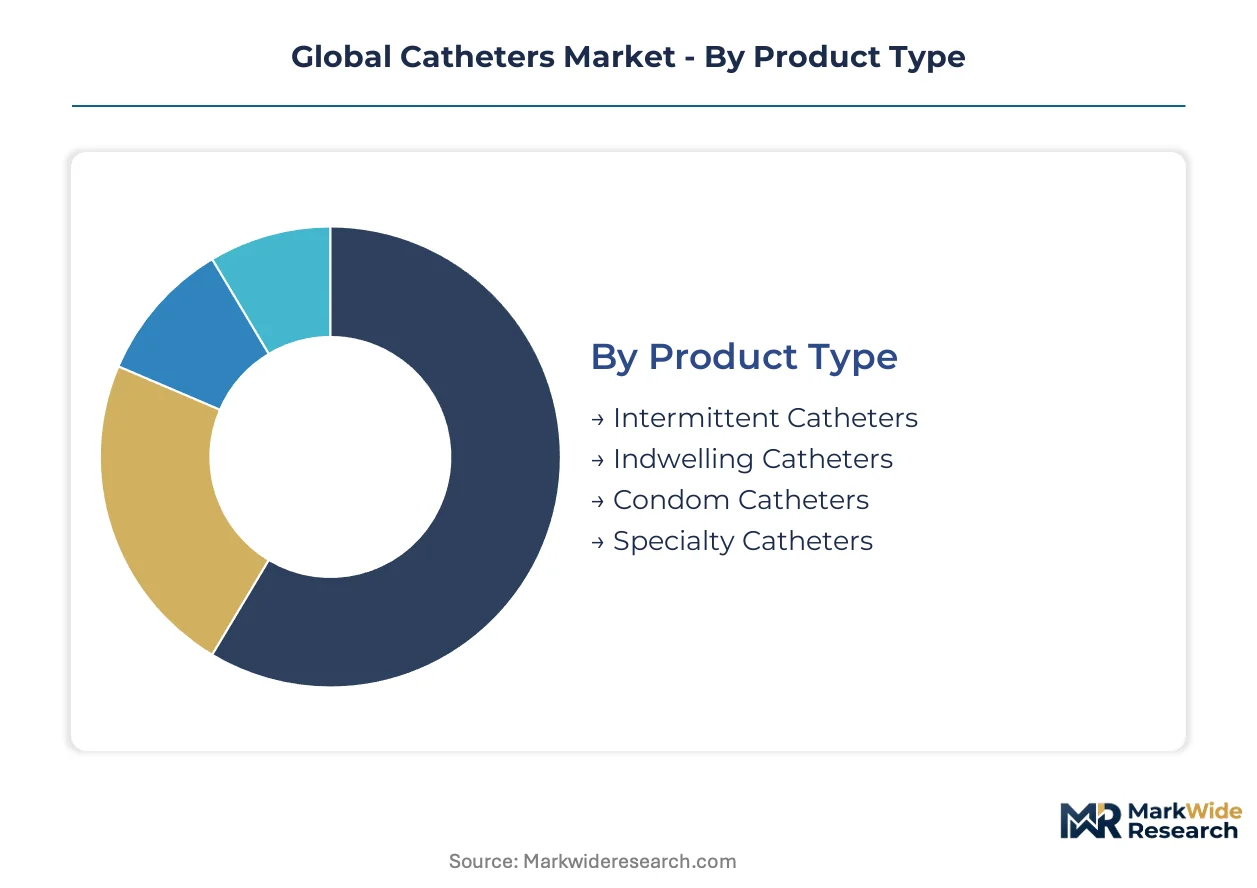
Catheter procurement decisions split across clinical workflow requirements, reimbursement pathways, and patient self-management capabilities. Manufacturers align product portfolios against these decision hierarchies to capture volume in institutional settings and margin in specialized applications.
Product Type:
Hospital procurement teams weight dwell-time protocols and infection risk profiles when selecting catheter formats for formulary inclusion.
- Intermittent Catheters:Single-use sterile devices designed for clean intermittent catheterization protocols; demand concentrates in home care channels across Germany and Japan as reimbursement codes expand for neurogenic bladder self-management.
- Indwelling Catheters:Foley-type devices with inflatable retention balloons for extended urinary drainage; ICU and long-term acute care facilities in the United States drive procurement volume through bundled payment structures.
- Condom Catheters:External sheath devices for male patients with functional urethras; urology clinics favor these for reduced catheter-associated urinary tract infection risk compared to invasive alternatives.
- Specialty Catheters:Procedure-specific designs including electrophysiology mapping and neurointerventional access devices; cardiac catheterization labs command premium pricing for advanced navigation capabilities.
Indwelling catheters lead on scale; specialty catheters lead on momentum.
End User:
Channel economics diverge sharply between capital-intensive hospital systems and distributed home care supply chains.
- Hospitals:Integrated delivery networks consolidate catheter procurement through group purchasing organizations, extracting volume discounts in exchange for sole-source contracts and utilization data sharing.
- Clinics:Outpatient urology and dialysis centers stock standardized catheter inventories aligned with procedure-specific reimbursement codes.
- Home Care:Patients managing spinal cord injury or multiple sclerosis source intermittent catheters through specialty pharmacies and direct-to-patient e-commerce platforms in Germany and Japan.
- Ambulatory Surgical Centers:Same-day procedure facilities prioritize compact packaging and rapid turnover compatibility for cardiovascular and peripheral intervention cases.
Hospitals dominate absolute volume; home care channels are expanding most quickly.
Material:
Biocompatibility mandates and allergen liability reshape compound selection across chronic and acute applications.
- Latex:Natural rubber formulations with high elasticity and tensile strength; protein allergen risks and EU REACH restrictions are compressing adoption to cost-sensitive emerging markets.
- Silicone:Medical-grade platinum-cured formulations with superior tissue tolerance and reduced encrustation; long-term indwelling applications in the United States and Japan are converting rapidly to this substrate.
- PVC:Plasticized polyvinyl chloride remains prevalent in high-volume disposable lines; phthalate plasticizer migration concerns under EU MDR Article 10 are forcing reformulation investments.
- Teflon:Polytetrafluoroethylene coatings reduce friction in vascular access and guidewire applications; interventional cardiology suites specify these for lesion crossing performance.
Silicone commands the steepest expansion trajectory; PVC retains the largest installed base.
Application:
Procedure reimbursement codes and clinical outcome metrics determine addressable market size for each indication.
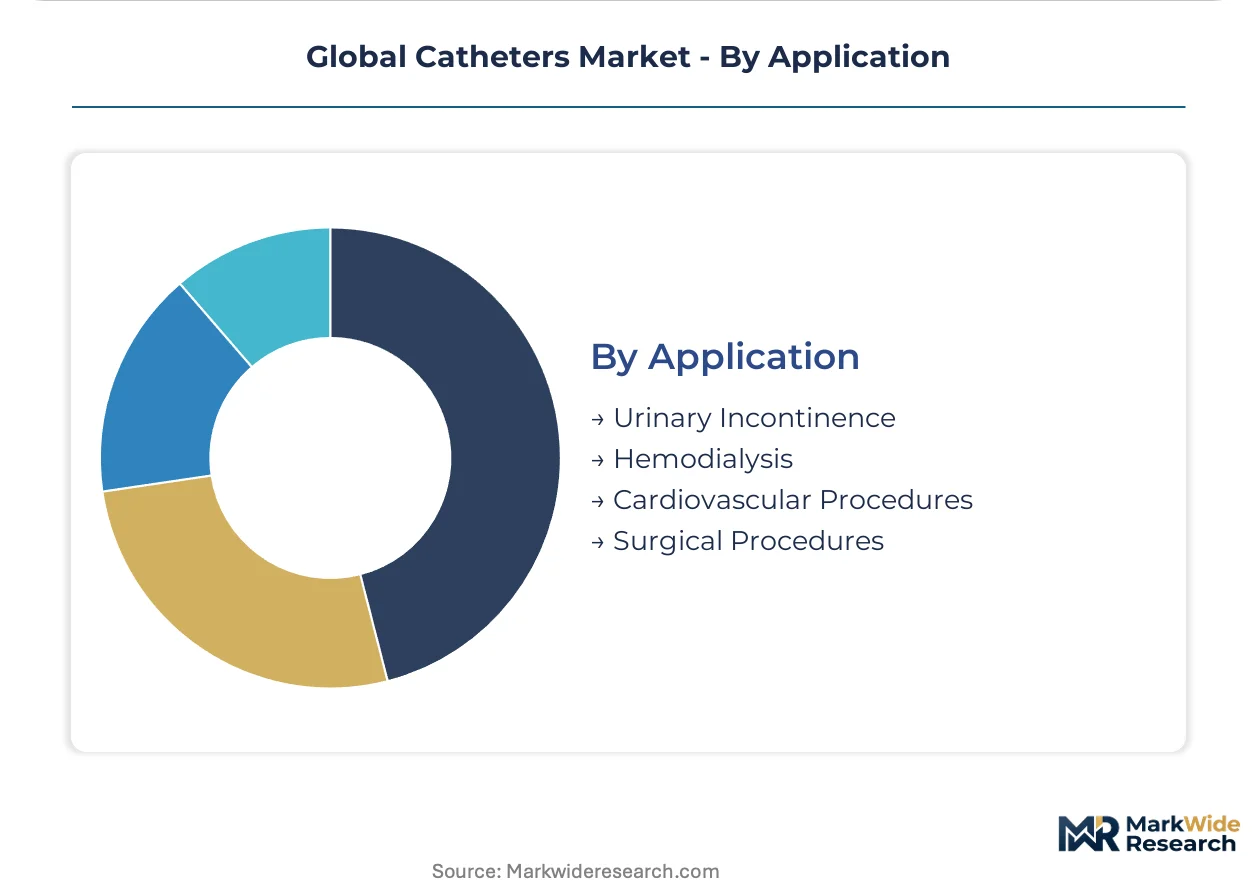
- Urinary Incontinence:Neurogenic and stress incontinence management drives intermittent catheter consumption; aging demographics in Japan and Germany expand the eligible patient population.
- Hemodialysis:Central venous catheters for vascular access in renal replacement therapy; dialysis clinic chains in the United States standardize on specific lumen configurations for flow-rate optimization.
- Cardiovascular Procedures:Diagnostic and interventional catheters for coronary and peripheral artery disease; electrophysiology ablation cases are gaining share fastest as atrial fibrillation prevalence rises.
- Surgical Procedures:Drainage and access catheters deployed across general surgery, thoracic, and orthopedic subspecialties; ambulatory surgical center migration is shifting volume toward shorter-dwell designs.
Cardiovascular applications lead on revenue intensity; urinary incontinence leads on patient volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting catheter manufacturing toward jurisdictions with streamlined compliance pathways and established sterilization infrastructure. Production migration tracks the cost-of-compliance gap between legacy markets and emerging regulatory hubs.
United States
Aging demographics and bundled payment structures for chronic conditions sustain hospital procurement volumes. FDA Class II and Class III device controls through 510(k) and PMA pathways govern sterility validation. Gamma sterilization capacity concentrates in Illinois and California, serving domestic and export demand.
Germany
Home care reimbursement expansion for neurogenic bladder management accelerates intermittent catheter adoption. EU MDR Article 10 technical documentation requirements and REACH substance restrictions force PVC reformulation investments. Medical technology clusters in Baden-Württemberg and North Rhine-Westphalia host TPU compounding and extrusion operations.
Japan
PMDA accelerated approval pathways for novel antimicrobial surface technologies attract specialty catheter development. METI industrial policy supports domestic manufacturing resilience for critical medical devices. Tokyo-Osaka corridor facilities specialize in platinum-cured silicone formulations for long-dwelling applications.
India
CDSCO medical device licensing streamlining opens private hospital and diagnostic center channels. Central government production-linked incentive schemes for medical devices attract contract manufacturing investment. Gujarat and Karnataka industrial zones develop sterilization and packaging capabilities for export markets.
Switzerland
Swissmedic quality system requirements and ISO 13485 certification density attract premium catheter R&D operations. Bilateral mutual recognition agreements with EU and US regulators enable streamlined market access. Basel and Zurich clusters concentrate in hydrophilic coating and drug-eluting catheter technologies.
Global Catheters Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers restructure around antimicrobial surface convergence and home care channel expansion. The vendor base stratifies across three tiers: diversified medtech conglomerates with full catheter portfolios, mid-scale specialists focused on single application areas, and regional contract manufacturers serving private-label demand. Strategic archetypes include scale-driven procurement consolidators, technology-led premium positioning specialists, and cost-optimized emerging market suppliers. M&A activity and capacity expansion in sterilization infrastructure represent the dominant competitive moves.
Among diversified medtech conglomerates, Boston Scientific Corporation, Medtronic, and Johnson & Johnson exemplify scale-driven positioning across cardiovascular and surgical access segments. These entities occupy positions anchored by interventional cardiology and cardiac rhythm management portfolios that extend into catheter-based delivery systems. Their manufacturing footprints span multiple regulatory jurisdictions to mitigate EU MDR and FDA compliance concentration risk.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Johnson & Johnson |
| Becton Dickinson and Company |
| Abbott Laboratories |
| Teleflex Incorporated |
| Stryker Corporation |
| Terumo Corporation |
| Hollister Incorporated |
| Others |
Supply Flow & Price Mechanics
Captive sterilization infrastructure in Illinois and California anchors supply positioning and pricing power for catheter manufacturers serving FDA-regulated markets. This geographic concentration of gamma and ethylene oxide capacity forces Asian and European device makers to absorb logistics premiums or invest in redundant sterilization partnerships, compressing margin flexibility at the procurement tier.
Pricing Analysis
Distributor margin layers in the United States and Germany absorb 15-25 points before hospital GPO contracting, while direct-to-patient e-commerce in Japan and Germany bypasses traditional markup structures entirely. Three-tier pricing structure across premium antimicrobial-coated, standard silicone, and economy PVC levels separates reimbursement-eligible hospital formulary tiers from cash-pay home care channels. Cost compression in standard indwelling lines is intensifying because GPOs extract volume guarantees in exchange for sole-source contracts. Dialysis clinic chains and ambulatory surgical centers exhibit highest price sensitivity; electrophysiology labs show lowest sensitivity due to procedure-specific performance requirements.
Supply Chain Analysis
Reverse-logistics flows for catheter products remain minimal given single-use sterility requirements, though Japan and Germany pilot limited recycling programs for packaging waste from home care channels. Medical-grade silicone feedstock concentrates in the United States, Japan, and Germany, with platinum-cured formulations tethered to Tokyo-Osaka and Baden-Württemberg compounding clusters. Thermoplastic polyurethane and plasticized PVC depend on petrochemical input cycles, exposing margin stability to commodity volatility. Single-source sterilization concentration in Illinois and California creates geographic supply risk for European and Asian device makers. Distribution runs through hospital GPOs in the United States, specialty pharmacy networks in Germany, and direct-to-patient platforms in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Catheters Market functions as a regulatory compounder where EU MDR sterility mandates and FDA Class III controls continuously filter supplier bases and consolidate procurement toward certified manufacturers.
For Market Incumbents: Deepen backward integration into platinum-cured silicone compounding to secure feedstock against petrochemical volatility and REACH reformulation requirements. Expand captive sterilization capacity in Germany or Switzerland to reduce geographic concentration risk. Defend GPO contract positions by embedding vendor-managed inventory systems that lock out challenger brands through utilization data integration. For New Entrants and Emerging Players: CDSCO licensing streamlining in India opens a window for cardiovascular and urological catheter suppliers to capture private hospital procurement before incumbent GPO contracts solidify. Target diagnostic center channels in Gujarat and Karnataka where sterilization infrastructure investments are attracting contract manufacturing demand. Pursue antimicrobial surface technology partnerships with academic medical centers in Germany to generate clinical evidence portfolios required for EU MDR compliance. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale specialty catheter developers because EU MDR compliance costs are forcing non-certified suppliers toward exit or acquisition. Platform consolidation across electrophysiology and neurointerventional segments offers 5-10 year viability given procedure volume expansion and premium pricing persistence. Monitor EPA ethylene oxide facility closure announcements as inflection indicators for sterilization capacity scarcity and alternative method validation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body certification unlocks procurement access across German and Swiss hospital networks. |
| Antimicrobial Surface Technology Partnership | Silver-ion coating validation addresses CMS catheter-associated infection protocols in intensive care. |
| Direct-to-Patient Distribution Buildout | E-commerce channels in Germany and Japan bypass GPO price compression for intermittent catheter users. |
| Sterilization Infrastructure Expansion | Gamma facility investment in India reduces supply risk from EPA ethylene oxide restrictions. |
| Platinum-Cured Silicone Backward Integration | In-house compounding secures margin against REACH phthalate alternative migration testing costs. |
Methodological Framework
Multiple input streams — hospital procurement database analysis, GPO contract review, and regulatory filing examination — were reconciled against primary interviews with catheter manufacturing executives, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, EU MDR notified body certification records, CMS reimbursement code databases, and customs trade data for medical-grade polymer imports. Bottom-up demand modeling across intermittent, indwelling, and specialty catheter formats was triangulated with top-down market sizing from manufacturer revenue disclosures.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through multi-dimensional segmentation modeling. Product type, material substrate, end-user channel, and application indication served as core segmentation dimensions, with antimicrobial surface technology adoption tracked as a cross-cutting innovation layer. CAGRs were derived from procedure volume trends, reimbursement code expansion patterns, and patient demographic projections without reliance on single-source estimates. Sterilization capacity utilization rates and polymer feedstock price indices informed cost-side assumptions.
Revisions become necessary when EPA ethylene oxide facility closures accelerate, EU MDR notified body backlogs extend compliance timelines, or CMS reimbursement bundling shifts unexpectedly toward procedure-based rather than device-based payment. Practitioners should monitor sterilization capacity announcements, notified body certification queue lengths, and GPO contract renewal cycles for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Cardiovascular Ultrasound System Market
Cardiovascular Devices
Mitral Valve Disease Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Cardiac Cryoablation Device Market
Cardiovascular Devices
Global Vascular Plugs Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Surgical and Interventional Cardiology Devices Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Global Percutaneous Coronary Intervention (PCI) Devices Market
Cardiovascular Devices
Transcatheter Heart Valve Replacement (THVR) Market
Cardiovascular Devices
North America Vascular Stents Market
Cardiovascular Devices
North America Vascular Graft Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market