
 Global Bladder Cancer Market | 2026-2036
Global Bladder Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bladder Cancer Market Foresight
Project finance for late-stage clinical trials is reconfiguring which developers can sustain multi-year oncology programs. Bristol Myers Squibb Company leverages its scale in immuno-oncology to anchor commercial infrastructure across major markets. Merck & Co. Inc. sustains leadership in PD-1 checkpoint inhibition through extensive investigator-sponsored trial networks. AstraZeneca PLC competes aggressively in antibody-drug conjugate development for muscle-invasive disease.
Bladder cancer encompasses malignant neoplasms arising from urothelial cells lining the urinary bladder, with histological grading based on cellular atypia and depth of invasion into the lamina propria or muscularis propria. The condition demands precise staging via cystoscopy, cross-sectional imaging, and molecular profiling to determine therapeutic strategy. Immunotherapy dominates current revenue pools as checkpoint inhibitors reshape first-line metastatic treatment paradigms. Diagnostic Kits represent the fastest-expanding segment as liquid biopsy platforms and urine-based biomarker assays displace repeat cystoscopic surveillance. Chemotherapy retains substantial volume in neoadjuvant settings but faces margin compression from biosimilar substitution.
The FDA's accelerated approval framework and Breakthrough Therapy designation compress development timelines for novel bladder cancer agents, while the EMA's conditional marketing authorization creates parallel European access pathways. The EU MDR elevates clinical evidence requirements for diagnostic kits and companion devices, reshaping regulatory investment thresholds for market entrants. Stakeholders must monitor evolving reimbursement decisions for combination regimens across the United States, Germany, and Japan, where health technology assessment bodies increasingly demand comparative effectiveness data against existing standards of care.
Market Dynamics
Checkpoint inhibitor reimbursement protocols are concentrating demand among outpatient oncology networks, compressing site-of-care economics and reshaping prescriber allegiance across major markets.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's Breakthrough Therapy designation compresses Phase II-to-launch timelines for novel immuno-oncology agents. Developers gain earlier revenue recognition and faster patient access.
- Liquid Biopsy Platforms:Urine-based NGS assays and methylation biomarker panels are displacing repeat cystoscopic surveillance. Urology practices in the United States and Germany are prioritizing non-invasive monitoring protocols.
- Medicare Reimbursement:Outpatient administration codes for PD-1 inhibitors favor community oncology centers over hospital-based infusion units. This policy shift concentrates patient volume in lower-cost settings.
Market Restraints
- Biosimilar Substitution:Generic carboplatin and gemcitabine formulations are compressing neoadjuvant chemotherapy margins. Originators face pricing pressure across European tender markets.
- Clinical Evidence Thresholds:The EU MDR elevates post-market surveillance requirements for companion diagnostic kits. Smaller IVD developers face capital constraints for PMCF studies.
- Site-of-Care Concentration:Infusion capacity constraints in Japan and Australia limit patient throughput for checkpoint inhibitor expansion. Rural access gaps persist despite policy intent.
Strategic Opportunities
- Antibody-Drug Conjugate Development:Nectin-4 and TROP2-targeted payloads represent unaddressed segments in muscle-invasive disease. First-movers in Japan and the United States capture investigator-sponsored trial networks.
- Digital Pathology Integration:AI-enabled histological grading tools align with EMA qualification pathways for novel biomarker categories. European reference laboratories are piloting automated PD-L1 scoring.
- Combination Regimen Reimbursement:Parallel FDA and PMDA reviews for chemo-immunotherapy protocols create synchronized market entry. Developers with cross-regulatory experience capture HTA advantages.
Industry Challenges
- Biomarker Assay Harmonization:Discordant PD-L1 scoring between 22C3 and SP142 antibodies complicates clinical trial enrollment. Pathology labs require dual-platform validation.
- Cold Chain Logistics:Temperature-sensitive ADC payloads demand specialized distribution infrastructure. Emerging market access remains constrained by last-mile refrigeration gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bladder Cancer Market |
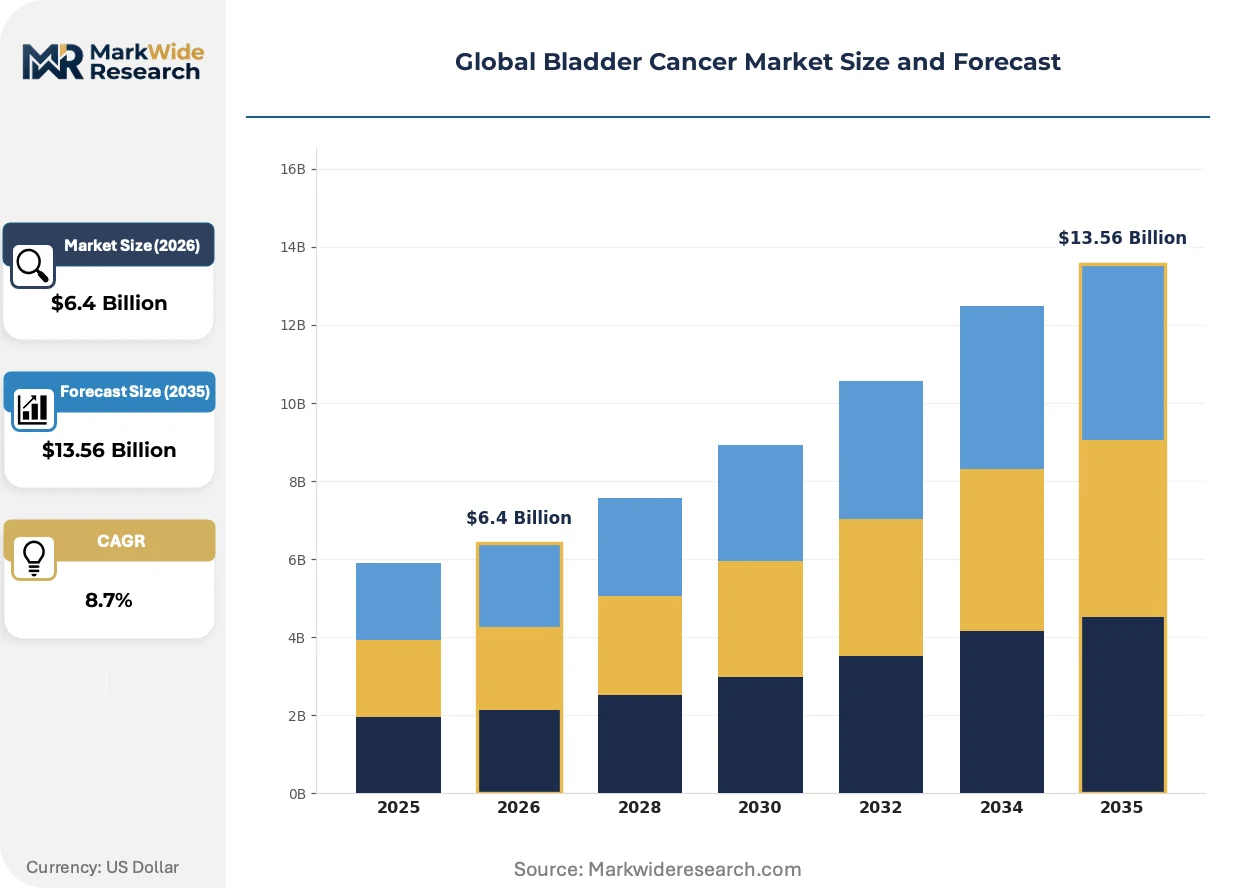
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunotherapy, Chemotherapy, Targeted Therapy, Photodynamic Therapy, Diagnostic Kits Application: Superficial Bladder Cancer, Muscle-Invasive Bladder Cancer, Metastatic Bladder Cancer, Recurrent Bladder Cancer End User: Oncology Centers, Academic Research Institutions, Specialized Clinics, Diagnostic Laboratories Therapy Area: Non-Muscle Invasive, Muscle Invasive, Advanced Stage, Carcinoma in Situ |
| Companies Covered | Bristol Myers Squibb Company, Merck & Co. Inc., AstraZeneca PLC, Johnson & Johnson, F. Hoffmann-La Roche Ltd., Pfizer Inc., Astellas Pharma Inc., Eli Lilly and Company, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bladder Cancer Market Shifts & Advancements
Diagnostic virtualization and regulatory pathway convergence are compressing development timelines while fragmenting traditional site-of-care economics across bladder cancer management.
Computational pathology platforms are virtualizing traditional histological review workflows. Academic medical centers in Germany and the Netherlands are deploying cloud-based whole-slide analysis for multicenter trial adjudication. This virtualization is compressing central lab turnaround times and enabling real-time quality control across distributed investigator networks.
The EU MDR's companion diagnostic classification rules are elevating clinical evidence requirements for urine-based assays. IVD manufacturers must now submit prospective validation data for biomarker claims previously accepted on retrospective cohorts. European notified bodies are prioritizing submissions from developers with established QMS infrastructure, creating regulatory capacity bottlenecks for mid-tier entrants.
Patient-driven surveillance scheduling is displacing rigid cystoscopic protocols in United States urology practices. Direct-to-consumer genetic testing awareness has elevated demand for personalized monitoring intervals. This behavioral shift concentrates volume in high-throughput ambulatory surgery centers equipped for same-day biopsy and molecular profiling.
Global Bladder Cancer Market Segmentation
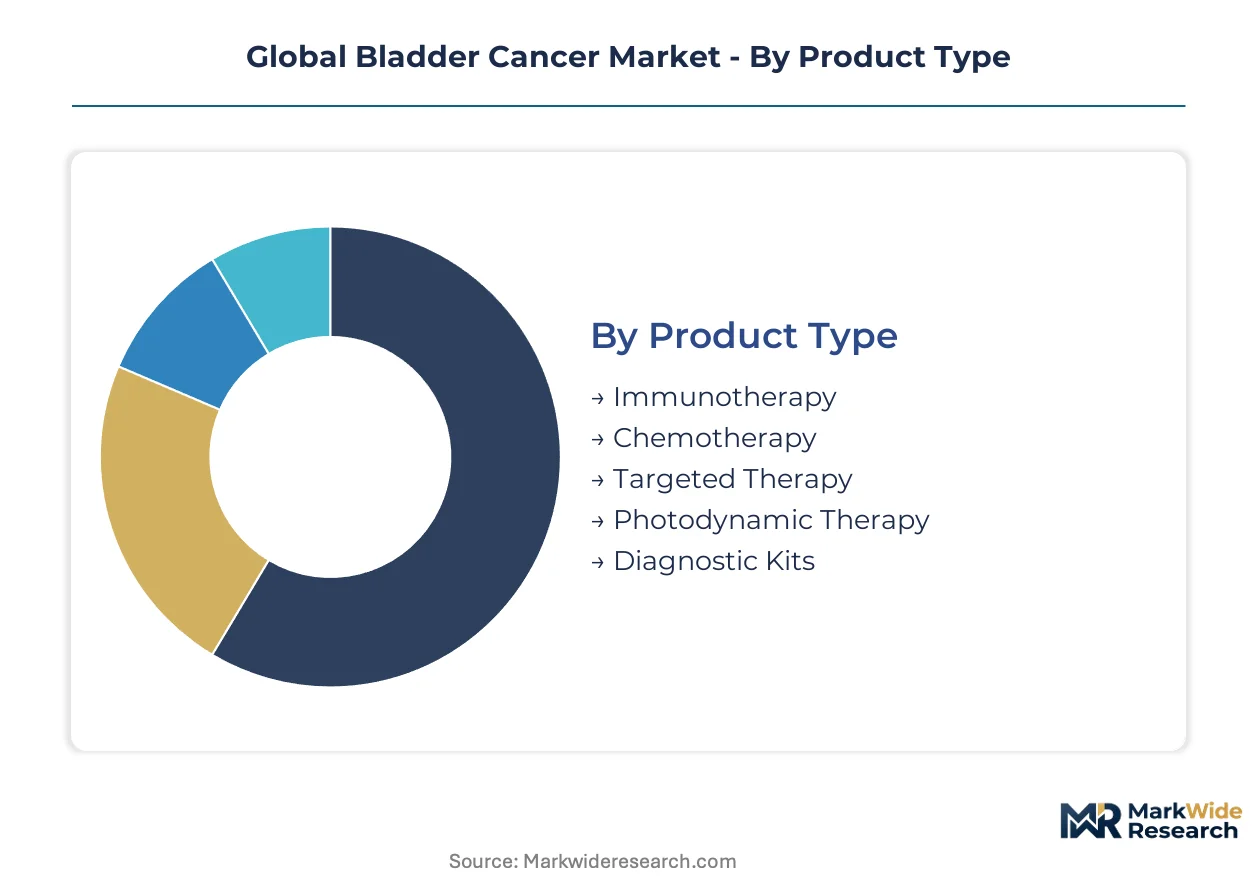
Bladder cancer market segmentation reveals divergent investment cycles across therapeutic modalities. Diagnostic and therapeutic segments operate on fundamentally different capital turnover timelines, reshaping how manufacturers allocate R&D resources and commercial infrastructure.
Product Type:
Immunotherapy and diagnostic kits turn inventory fastest, while chemotherapy and photodynamic therapy face extended replacement cycles due to protocol stickiness and equipment amortization.
- Immunotherapy:Checkpoint inhibitors targeting PD-1 and PD-L1 pathways require cold chain distribution and specialized infusion infrastructure. United States oncology centers concentrate demand through Medicare outpatient reimbursement codes, compressing site-of-care economics toward community-based networks.
- Diagnostic Kits:Urine-based NGS assays and methylation biomarker panels displace repeat cystoscopic surveillance through non-invasive sampling protocols. German urology practices prioritize liquid biopsy platforms for monitoring, driven by EU MDR elevation of clinical evidence requirements for companion devices.
- Chemotherapy:Neoadjuvant platinum-based regimens retain substantial procedural volume despite biosimilar margin compression across European tender markets.
- Targeted Therapy:FGFR inhibitor formulations address molecularly defined patient subsets with concentrated uptake in academic medical center molecular tumor boards.
- Photodynamic Therapy:Photosensitizer agents combined with laser activation systems serve carcinoma in situ cases with limited penetration beyond specialized European urology clinics.
Immunotherapy dominates installed base. Diagnostic kits are where expansion concentrates.
Application:
Cost tier stratification separates curative-intent surgical adjuncts from chronic management protocols, with metastatic segments commanding premium pricing despite smaller addressable populations.
- Metastatic Bladder Cancer:First-line checkpoint inhibitor combinations anchor revenue concentration despite intensifying competitive entry. FDA accelerated approval pathways compress Phase II-to-launch timelines for novel agents, enabling earlier revenue recognition.
- Muscle-Invasive Bladder Cancer:Neoadjuvant chemotherapy followed by radical cystectomy represents the standard curative pathway with established reimbursement. Japan and Germany concentrate perioperative protocol innovation through investigator-sponsored trial networks.
- Superficial Bladder Cancer:Intravesical BCG and mitomycin installations retain high procedural frequency with lower per-treatment economics.
- Recurrent Bladder Cancer:Salvage immunotherapy and antibody-drug conjugate protocols address progressive disease with concentrated demand in tertiary referral centers.
Muscle-invasive disease anchors reimbursement benchmarks. Metastatic applications are climbing the fastest.
End User:
Customer type fragmentation splits procurement authority between centralized hospital systems and distributed ambulatory networks, reshaping sales force deployment and channel economics.
- Oncology Centers:Community-based infusion networks capture Medicare-reimbursed immunotherapy volume through outpatient administration codes, displacing hospital-based units.
- Academic Research Institutions:Phase I-II trial sponsorship concentrates in United States NCI-designated centers and German comprehensive cancer centers with established early-phase infrastructure.
- Specialized Clinics:High-throughput ambulatory surgery centers equipped for same-day biopsy and molecular profiling capture patient-driven surveillance scheduling demand.
- Diagnostic Laboratories:European reference laboratories pilot AI-enabled histological grading tools aligned with EMA qualification pathways for novel biomarker categories.
Oncology centers dominate patient throughput. Academic institutions are where pipeline access concentrates.
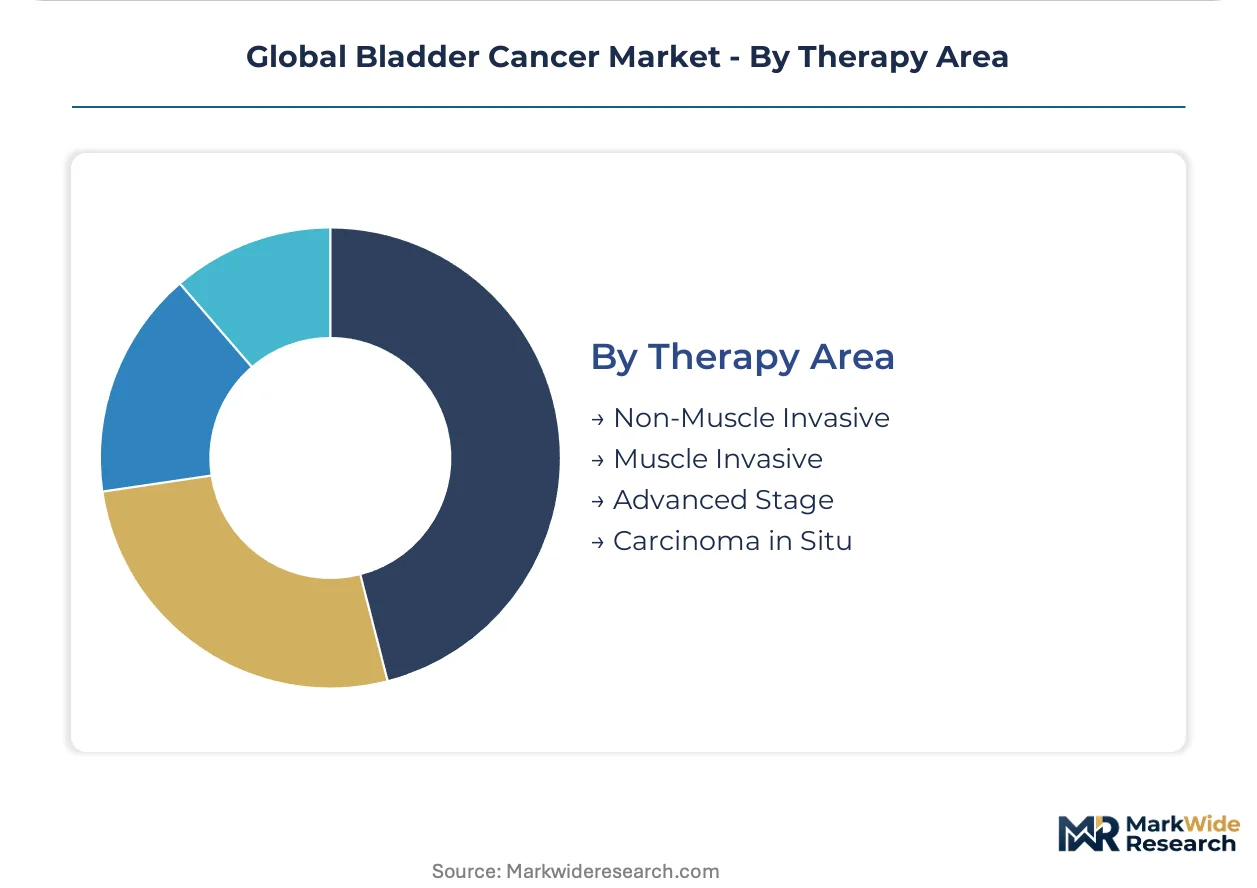
Therapy Area:
Maturity gradients separate established BCG-responsive populations from emerging ADC-addressable segments, with staging precision determining addressable market boundaries.
- Non-Muscle Invasive:Intravesical immunotherapy and chemotherapeutic installations constitute the highest-volume segment with established surveillance protocols and defined reimbursement.
- Muscle Invasive:Perioperative systemic therapy combined with radical local treatment represents the curative standard with concentrated surgical expertise in major metropolitan clusters.
- Advanced Stage:Metastatic and locally unresectable disease management concentrates checkpoint inhibitor utilization with evolving combination regimen development.
- Carcinoma in Situ:High-grade flat neoplasia demands aggressive local therapy with BCG-refractory cases driving photodynamic and device-based intervention demand.
Non-muscle invasive disease dominates procedural frequency. Muscle invasive applications are where therapeutic innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized oncology centers in the United States concentrate the highest-value immunotherapy demand, while German diagnostic networks and Japanese perioperative trial sites fragment procurement authority across distinct buyer archetypes.
United States
Medicare outpatient reimbursement codes for PD-1 inhibitors channel patient volume toward community-based infusion networks. FDA accelerated approval pathways compress Phase II-to-launch timelines for novel agents. The Greater Boston corridor anchors early-phase investigator-sponsored trial infrastructure.
Germany
Comprehensive cancer centers prioritize liquid biopsy platforms for non-invasive surveillance scheduling. EU MDR elevation of clinical evidence requirements reshapes notified body submission priorities for IVD manufacturers. The Munich-Düsseldorf corridor concentrates reference laboratory capacity for AI-enabled histological grading.
Japan
PMDA parallel review pathways for chemo-immunotherapy combinations create synchronized market entry opportunities. METI funding for cold chain logistics addresses ADC payload distribution constraints. The Tokyo-Osaka corridor dominates perioperative protocol innovation through academic medical center networks.
China
NMPA priority review vouchers accelerate domestic checkpoint inhibitor approvals for metastatic indications. National reimbursement directory negotiations concentrate demand among tertiary hospital oncology departments. The Yangtze River Delta cluster scales biosimilar manufacturing capacity for neoadjuvant platinum agents.
United Kingdom
NICE technology appraisals demand comparative effectiveness data against existing standards of care for combination regimens. NHS England site-of-care policies favor ambulatory administration for immunotherapy-eligible patients. The London-Southeast corridor concentrates molecular tumor board infrastructure for FGFR-directed therapy selection.
Global Bladder Cancer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market segments. Large-cap pharmaceutical developers anchor commercial infrastructure through established immuno-oncology portfolios. Mid-tier biotech developers concentrate on antibody-drug conjugate payloads for muscle-invasive indications. Diagnostic platform developers fragment across urine-based assay and computational pathology niches. Dominant competitive moves include strategic partnerships for biomarker assay harmonization and geographic licensing agreements for cold chain distribution.
Within the large-cap pharmaceutical tier, Bristol Myers Squibb Company, Merck & Co. Inc., and AstraZeneca PLC exemplify distinct competitive positioning archetypes. Bristol Myers Squibb occupies a channel-controlling position through scale advantages in checkpoint inhibitor commercial infrastructure. Merck & Co. anchors its position through extensive investigator-sponsored trial network density. AstraZeneca PLC represents the antibody-drug conjugate specialization vector with concentrated development focus on muscle-invasive disease payloads.
| Leading Market Players |
|---|
| Bristol Myers Squibb Company |
| Merck & Co. Inc. |
| AstraZeneca PLC |
| Johnson & Johnson |
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc. |
| Astellas Pharma Inc. |
| Eli Lilly and Company |
| GlaxoSmithKline plc |
| Others |
Supply & Pricing Matrix
Cold chain logistics providers in Germany and Switzerland anchor margin capture for antibody-drug conjugate payloads, concentrating pricing power with distributors capable of maintaining validated temperature corridors from manufacturing through infusion site delivery.
Pricing Analysis
Certification level creates the primary spread between premium FDA-breakthrough-designated checkpoint inhibitors and standard-of-care chemotherapy agents. Three-tier pricing structure across premium, standard, and economy levels reflects reimbursement tiering by Medicare outpatient codes, EU health technology assessment thresholds, and biosimilar penetration depth. Pricing pressure stems from carboplatin and gemcitabine biosimilar substitution across European tender markets, compressing neoadjuvant regimen margins. Community oncology centers exhibit highest price sensitivity due to Medicare reimbursement rate compression, while academic medical centers prioritize clinical efficacy data over acquisition cost.
Supply Chain Analysis
Lonza and Samsung Biologics hold dominant contract manufacturing capacity for monoclonal antibody production serving bladder cancer indications. Active pharmaceutical ingredient sourcing concentrates in Switzerland, Ireland, and Singapore for high-potency cytotoxic payloads. Supply chains draw from platinum-group metal refiners, recombinant protein fermentation capacity, and specialized vial containment systems. Single-source vulnerability persists for nectin-4-targeted ADC linker technologies. Distribution runs through specialty pharmacy networks and hospital-based infusion centers with direct-to-site cold chain validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of validated biomarker assay platforms capable of harmonizing PD-L1 scoring across 22C3 and SP142 antibodies constrains trial enrollment velocity and companion diagnostic commercialization timelines.
For Market Incumbents: Entrench commercial infrastructure through backward integration into liquid biopsy platform development, securing proprietary urine-based NGS assay access. Expand investigator-sponsored trial network density in Germany and Japan to preempt ADC competitor entry. Counter biosimilar margin erosion by shifting volume toward outpatient administration codes that concentrate patient flow through owned infusion networks. For New Entrants and Emerging Players: Establish a beachhead in AI-enabled histological grading tools aligned with EMA qualification pathways for novel biomarker categories. Target European reference laboratories piloting automated PD-L1 scoring as the most penetrable customer segment. Pursue licensing agreements with comprehensive cancer centers in the Munich-Düsseldorf corridor to secure clinical validation data and reimbursement precedent. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier diagnostic platform developers with established QMS infrastructure and EU MDR submission readiness for urine-based methylation biomarker panels. Long-term viability favors assets capable of spanning therapeutic monitoring and minimal residual disease detection applications. Watch FDA breakthrough therapy designation velocity for nectin-4 and TROP2-targeted ADCs as the signal indicating competitive inflection in muscle-invasive disease segments.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Assay Harmonization Partnership | Aligns 22C3 and SP142 PD-L1 scoring platforms to streamline clinical trial enrollment across Bristol Myers Squibb and Merck protocols. |
| Cold Chain Distribution Expansion | Addresses ADC payload temperature sensitivity through METI-funded logistics infrastructure in Japan's Tokyo-Osaka corridor. |
| EU MDR Companion Diagnostic Submission | Secures notified body prioritization for urine-based NGS assays through prospective validation data packages. |
| Outpatient Infusion Network Acquisition | Captures Medicare-reimbursed immunotherapy volume concentration in United States community oncology settings. |
| Antibody-Drug Conjugate Licensing Agreement | Accelerates muscle-invasive disease pipeline access through investigator-sponsored trial network density in German comprehensive cancer centers. |
Research Methodology
Cross-validation between investigator-sponsored trial registry data and Medicare reimbursement code utilization anchors the qualitative findings. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers informed therapeutic adoption patterns. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare claims data. Bottom-up patient-flow modeling and top-down revenue triangulation reconciled segmentation outputs.
Calibration against historical approval-to-launch intervals for checkpoint inhibitors and ADC classes refined growth trajectory assumptions. Segmentation dimensions span treatment line, administration route, regional regulatory cluster, and site-of-care setting. CAGRs were derived from fitted adoption curves incorporating reimbursement policy shifts and competitive entry timelines. Forecast inputs include investigator-sponsored trial initiation rates and health technology assessment body publication schedules.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, EU MDR implementation timelines, or biosimilar tender pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway velocity and competitive pipeline maturation. Quarterly review of FDA breakthrough therapy designations, EMA conditional marketing authorizations, and NICE technology appraisal timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Urology Forceps Market
Urology
Global Bladder Cancer Therapeutics Market
Urology
Urology Laser Fibers Market
Urology
Voiding Cystourethrogram Market
Urology
Global Urinary Tract Infections Therapeutics Market
Urology
Prostatic Arterial Embolization (PAE) Market
Urology
Uropathy Treatment Market
Urology
Self-Intermittent Catheters Market
Urology
Europe Urology Devices Market
Urology
Global Prostate Cancer Market
Urology
Suprapubic Catheters Market
Urology
Botulinum Toxin in Urology Market
Urology
Pyelonephritis Treatment Market
Urology
Urology Devices Market
Urology
Acute Pyelonephritis Treatment Market
Urology
Global Lithotripsy Market