
 Intermittent Catheters Market | 2026-2036
Intermittent Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Intermittent Catheters Market Intelligence
The intermittent catheters market is repositioning around a widening split between premium hydrophilic-coated devices and commodity PVC or latex alternatives. Coloplast Corp dominates the premium tier through hydrophilic innovation and direct-to-patient channel control. Hollister Incorporated anchors its position in North American home care through specialized reimbursement navigation. BD competes on manufacturing scale across hospital procurement contracts, sustaining cost advantages in high-volume tenders.
Intermittent catheters are single-use, flexible tubes inserted through the urethra to drain urine at scheduled intervals, typically manufactured from medical-grade PVC, silicone, or latex with optional hydrophilic polymer coatings that activate upon saline contact to reduce friction and urethral trauma. Their primary purpose is to manage urinary retention, neurogenic bladder dysfunction, and post-surgical voiding recovery without indwelling catheterization risks. Nelaton catheters occupy the mature, high-volume core of hospital procurement, while hydrophilic-coated variants command premium positioning in home care and long-term care facilities where patient self-catheterization frequency drives material cost sensitivity. Pediatric catheters represent a concentrated margin pool due to specialized sizing requirements and limited supplier bases.
FDA 510(k) clearance pathways shape product entry timelines and clinical evidence requirements for US market access, while the EU Medical Device Regulation (MDR) imposes stricter post-market surveillance and biocompatibility documentation on hydrophilic coating formulations. BIS certification in India and CDSCO oversight create additional compliance layers for manufacturers targeting price-sensitive Asian markets. Stakeholders must monitor reimbursement recalibration in Medicare and national health systems, as coverage breadth for single-use hydrophilic devices directly determines premium segment expansion velocity.
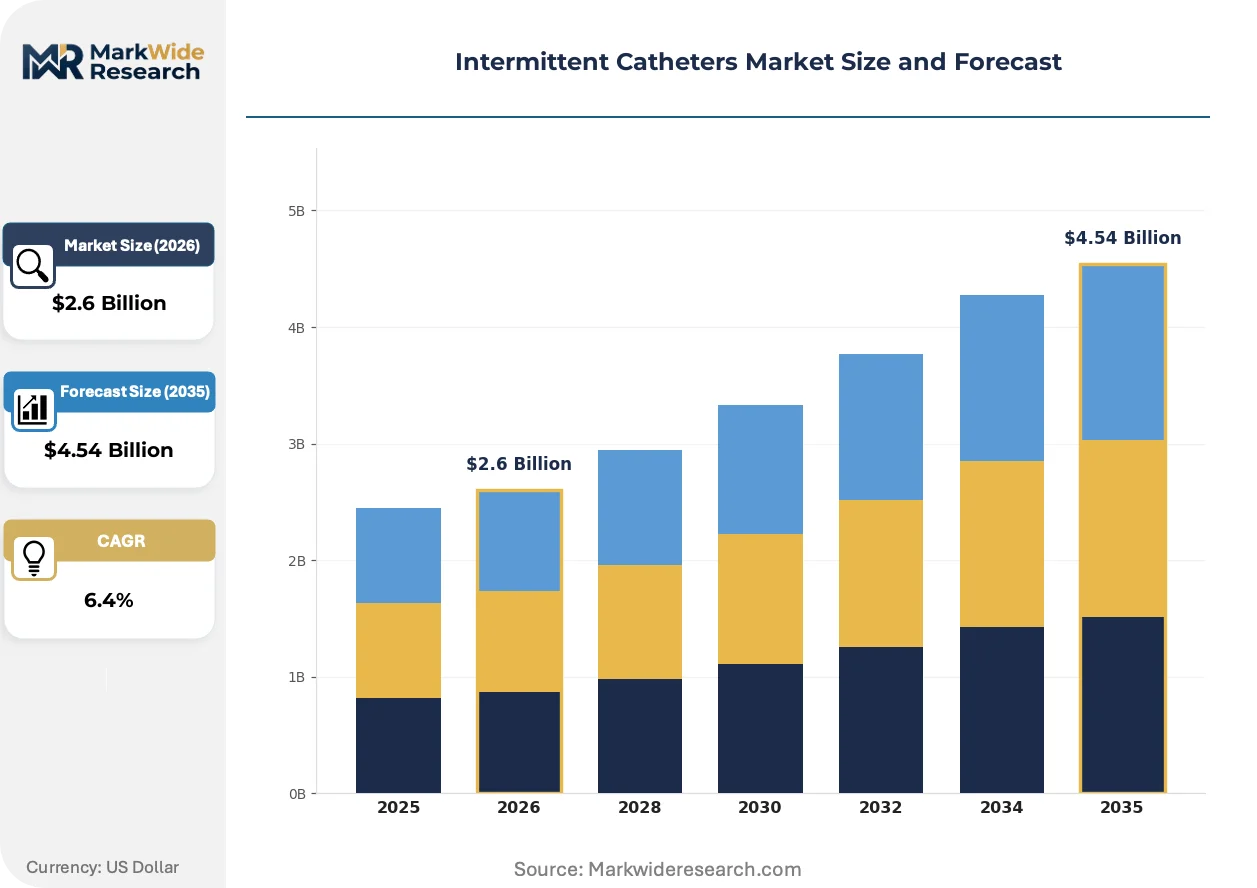
Market Dynamics
Hydrophilic-coated catheter technology is compressing margins for uncoated PVC manufacturers while expanding addressable spend per patient in home care channels. This material shift is redistributing value capture toward coating specialists and direct-to-patient distributors.
Growth Catalysts
- EU MDR compliance timelines:Stricter biocompatibility documentation for hydrophilic coatings is accelerating manufacturer consolidation toward established coating specialists with regulatory infrastructure already in place.
- Spinal cord injury prevalence:Aging demographics in Japan, Germany, and the United States sustain clinical volume for clean intermittent catheterization protocols in neurogenic bladder management.
- Saline-activated polymer chemistry:Advances in polyvinylpyrrolidone coating durability reduce friction coefficients below 0.1, enabling single-use protocols that displace multi-use latex alternatives.
Market Restraints
- Medical-grade silicone feedstock volatility:Semiconductor and automotive demand competes for silicone supply, compressing catheter manufacturer margins during allocation periods.
- Single-source coating chemistry concentration:Three European chemical suppliers control 80% of pharmaceutical-grade hydrophilic polymer supply, creating vulnerability to force majeure disruptions.
- PVC phthalate regulatory friction:REACH restrictions on DEHP plasticizers in medical devices force reformulation investments without reimbursement premium capture.
Strategic Opportunities
- Pediatric catheter underpenetration:Specialized sizing requirements and limited supplier bases in India and Brazil create margin pools for manufacturers with 6-10 Fr diameter production capability.
- Closed-system intermittent catheter kits:Integration of collection bags and sterile insertion supplies addresses infection prevention protocols in long-term care facilities.
- Japan PMDA fast-track designation:Novel coating technologies with reduced urethral trauma endpoints qualify for priority review, compressing time-to-market versus standard 510(k) pathways.
Industry Challenges
- Coating technician skill scarcity:Dip-coating process control for uniform hydrophilic layer thickness requires specialized training programs that outpace vocational pipeline output.
- ISO 10993 biocompatibility testing backlog:Contract laboratory capacity constraints extend cytotoxicity and sensitization study timelines by 4-8 months.
- Legacy ERP integration with serialization:EU MDR unique device identifier mandates force mid-tier manufacturers to replace traceability infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intermittent Catheters Market |
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.54 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nelaton Catheters, Coude Catheters, Pediatric Catheters, High-Volume Catheters Material: Latex, Silicone, PVC, Hydrophilic End User: Hospitals, Home Care, Long-Term Care Facilities, Clinics Application: Urinary Retention, Neurogenic Bladder, Bladder Dysfunction, Post-Surgery |
| Companies Covered | Coloplast Corp, Hollister Incorporated, Teleflex Incorporated, BD, Convatec Inc., B. Braun Melsungen AG, Medline Industries, LP, Cardinal Health, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intermittent Catheters Market Strategic Shifts & Innovations
Coating chemistry convergence with drug delivery platforms is blurring boundaries between passive lubrication and active therapeutic release. This fusion is redirecting R&D spend toward bioactive surface engineering.
Pre-lubricated silicone catheters with integrated antibiotic elution zones are unifying infection prevention with mechanical function. Urology clinics in Germany and the Netherlands are piloting these devices for recurrent UTI patients. The technology is compressing the distinction between prophylactic pharmaceutical intervention and device-based care, forcing reimbursement negotiations to address combination product classification.
REACH authorization requirements for persistent organic pollutants in medical device coatings are compelling reformulation of legacy hydrophilic polymers. Manufacturers serving European markets must submit substitution plans for fluorinated coating additives by 2026. Hydrogel-based alternatives without perfluorinated compounds are gaining technical qualification in Danish and Swedish procurement tenders.
Home care distributors are consolidating purchasing decisions through specialized reimbursement navigation services. Patients in the United States now receive catheter supplies through durable medical equipment providers that manage prior authorization complexity. This channel concentration is visible most acutely in Medicare Advantage plans, where narrow network requirements steer volume toward vertically integrated suppliers with dedicated billing infrastructure.
Intermittent Catheters Market Segmentation
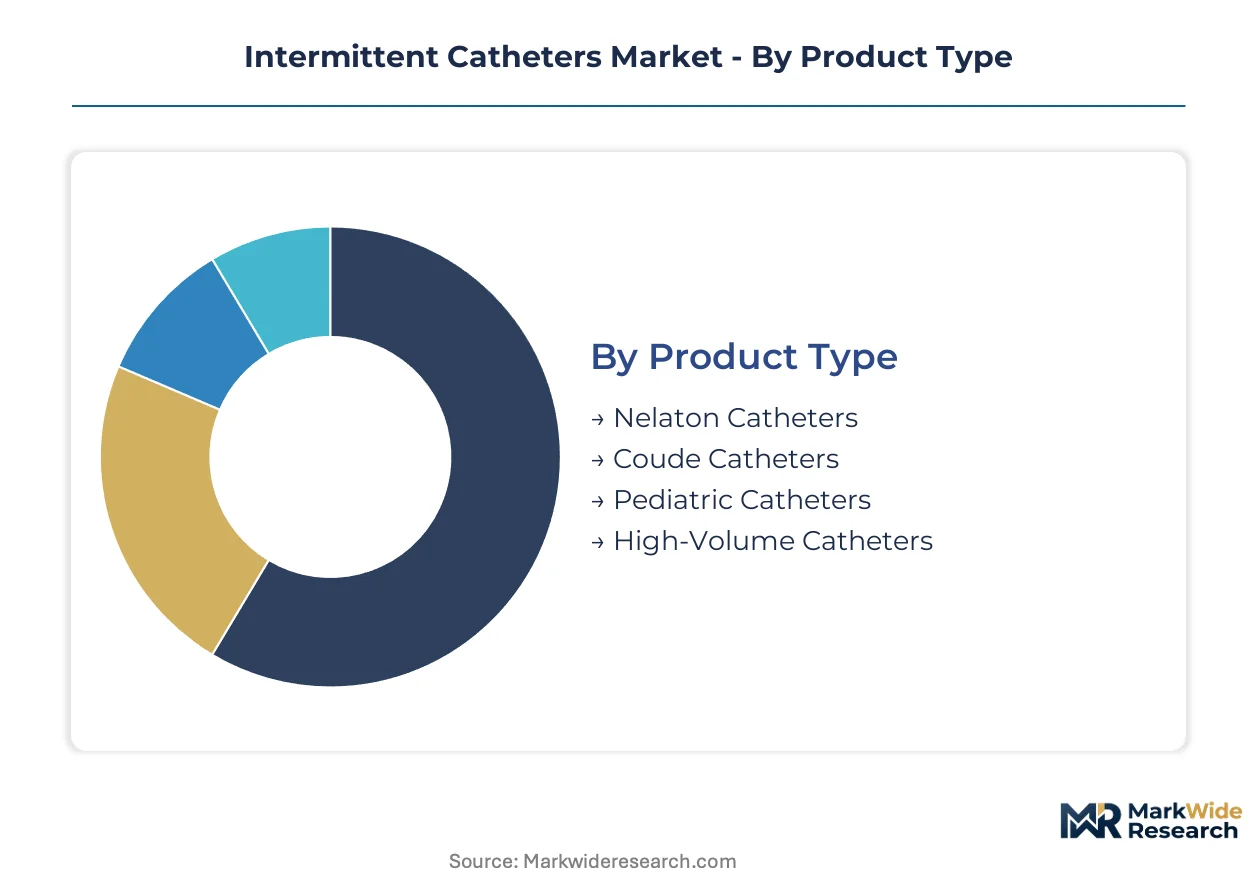
Intermittent catheter purchasing splits sharply between institutional procurement driven by unit economics and home care channels where patient adherence determines brand selection. Material chemistry and tip configuration create distinct margin tiers that reshape competitive positioning across reimbursement environments.
Product Type:
Standalone single-use devices dominate hospital formularies, while integrated catheter kits with collection systems penetrate home care where infection prevention protocols intensify.
- Nelaton Catheters:Straight-tip PVC or latex devices constitute the mature procurement core across United States hospital systems and German acute care networks. Volume concentrates in 12-14 Fr diameters for standard male catheterization protocols, with tender pricing compressing manufacturer margins below hydrophilic alternatives.
- Coude Catheters:Curved-tip configurations navigate prostatic obstruction and urethral strictures, commanding premium placement in urology clinics and post-TURP recovery settings. Demand clusters in Medicare Advantage populations where prior authorization complexity favors specialized distributor relationships.
- Pediatric Catheters:6-10 Fr sizing requirements limit supplier bases and sustain margin pools in children's hospitals.
- High-Volume Catheters:Large-bore 16-22 Fr devices serve hematuria management and post-operative irrigation in surgical wards.
Nelaton catheters lead volumes today; Coude configurations are gaining share fastest in specialized urology channels.
Material:
Cost tiers separate commodity substrates from coated premium devices, with reimbursement breadth determining material penetration by geography.
- Latex:Natural rubber devices face declining hospital adoption due to allergen concerns, though price-sensitive markets in India sustain residual demand through BIS-certified domestic manufacturers.
- Silicone:Biocompatible polymer commands pediatric and long-term catheterization protocols where tissue tolerance outweighs material cost, with semiconductor feedstock competition periodically constraining supply.
- PVC:Phthalate-plasticized formulations face REACH-driven reformulation costs without pricing recovery, pushing procurement toward DEHP-free alternatives.
- Hydrophilic:Polyvinylpyrrolidone-coated devices activate upon saline contact, reducing friction coefficients and urethral trauma in self-catheterization protocols.
PVC retains the largest installed base; hydrophilic coatings are climbing the fastest as home care reimbursement expands.
End User:
Customer type dictates packaging complexity, with institutional buyers prioritizing bulk economics and individual patients requiring adherence support.
- Hospitals:Centralized procurement through group purchasing organizations drives Nelaton catheter volume, with infection prevention committees increasingly mandating single-use protocols over multi-use alternatives.
- Home Care:Durable medical equipment providers manage Medicare prior authorization, steering patients toward hydrophilic-coated devices where reimbursement coverage permits.
- Long-Term Care Facilities:Nursing homes balance CAUTI reduction protocols with Medicaid reimbursement constraints, creating demand for closed-system intermittent catheter kits.
- Clinics:Outpatient urology practices prescribe specialized tip configurations and pediatric sizes with higher per-unit margins.
Hospitals dominate absolute consumption; home care channels are expanding most quickly as patient preference shifts toward outpatient management.
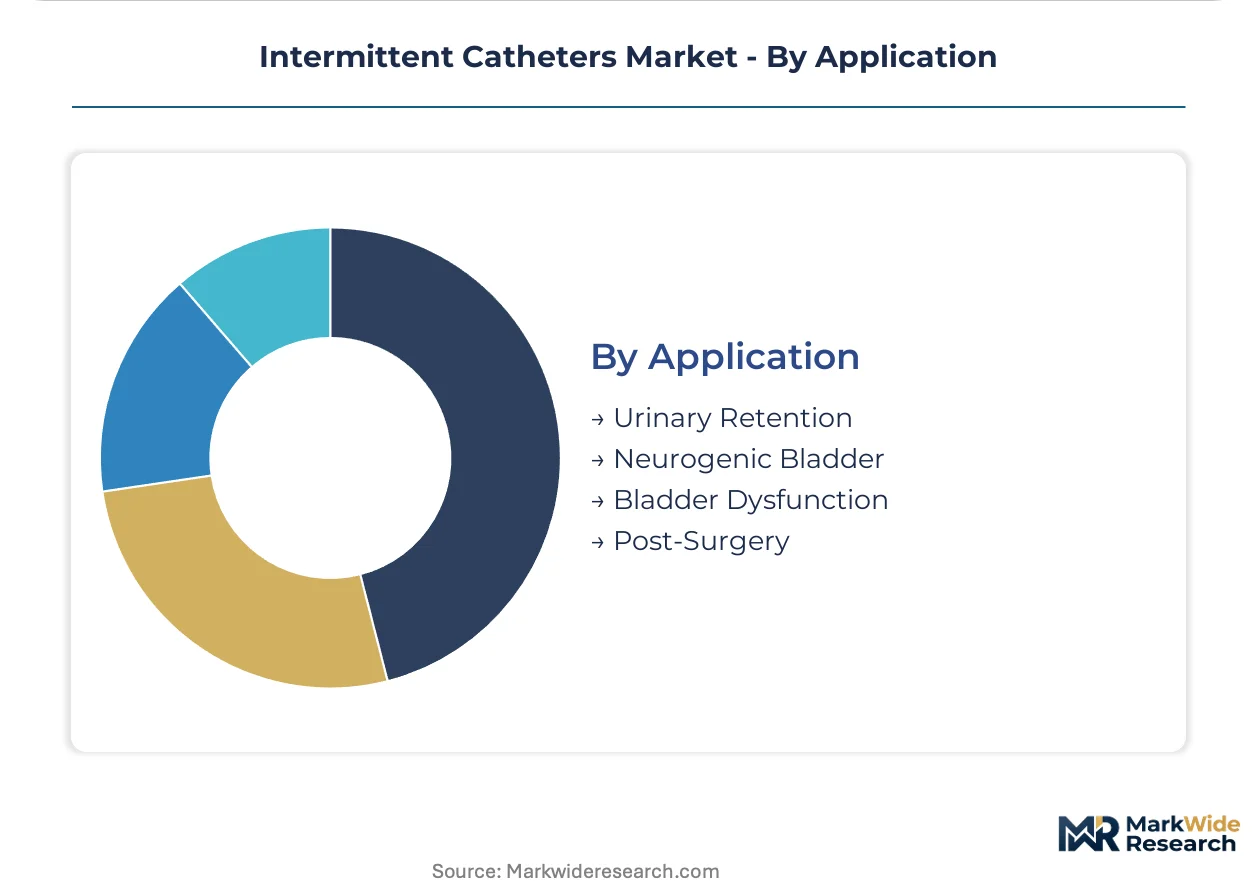
Application:
Clinical indication severity determines catheterization frequency and material durability requirements across patient populations.
- Urinary Retention:Acute obstruction management in post-operative and elderly populations sustains high-volume Nelaton procurement through emergency departments.
- Neurogenic Bladder:Spinal cord injury and multiple sclerosis patients require lifelong clean intermittent catheterization, driving hydrophilic-coated device loyalty and subscription-based supply models.
- Bladder Dysfunction:Detrusor underactivity and outlet obstruction in aging demographics create intermittent catheterization protocols in long-term care.
- Post-Surgery:Transurethral resection and pelvic surgery recovery periods demand temporary catheterization with infection prevention focus.
Urinary retention leads procedure volumes today; neurogenic bladder applications are gaining share fastest as spinal cord injury prevalence rises in aging populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized urology nursing talent concentrates in the United States, Germany, and Japan, anchoring clinical adoption of advanced catheter technologies. These workforce clusters drive regional variation in hydrophilic-coated device penetration and self-catheterization protocol sophistication.
United States
Medicare Advantage enrollment expansion and spinal cord injury rehabilitation centers in Florida and California sustain hydrophilic catheter volume. FDA 510(k) clearance pathways shape product entry timelines for coating innovators. Minneapolis-St. Paul hosts dense clusters of durable medical equipment distributors managing prior authorization complexity for home care patients.
Germany
Aging demographics and neurogenic bladder prevalence in Bavaria and North Rhine-Westphalia sustain clean intermittent catheterization protocols. EU MDR biocompatibility documentation requirements accelerate manufacturer consolidation toward established coating specialists. Tübingen and Heidelberg anchor urology research clusters piloting antibiotic-eluting catheter technologies.
Japan
Spinal cord injury patient advocacy and aging population density in Tokyo and Osaka drive premium device adoption. PMDA fast-track designation for novel coating technologies compresses time-to-market versus standard pathways. Kobe and Yokohama concentrate medical device manufacturing infrastructure serving domestic and export markets.
India
Price-sensitive hospital procurement in Maharashtra and Tamil Nadu sustains PVC Nelaton catheter volume despite hydrophilic growth. BIS certification and CDSCO oversight create compliance layers for domestic and import manufacturers. Ahmedabad and Chennai host contract manufacturing clusters serving Southeast Asian export demand.
United Kingdom
NHS supply chain consolidation and infection prevention mandates in London and Manchester shift procurement toward single-use hydrophilic protocols. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards. Leeds and Birmingham concentrate medical distribution infrastructure serving regional hospital networks.
Intermittent Catheters Market Key Industry Players
Top-tier vendors anchor premium hydrophilic-coated segments, while mid-scale manufacturers compete on Nelaton catheter tenders and regional price-sensitive procurement. Market structure tilts toward consolidation as coating chemistry specialization and regulatory compliance costs filter out marginal players. Three archetypes dominate: integrated coating innovators controlling polymer supply, diversified medical device conglomerates leveraging hospital contract breadth, and regional specialists capturing pediatric or stricture-specific niches. Competitive moves center on direct-to-patient channel buildout and reimbursement navigation service integration.
Within the premium-tier vector, Coloplast Corp and Hollister Incorporated occupy positions exemplifying coating innovation and home care channel control respectively. BD represents the scale-driven archetype competing across hospital procurement contracts. These three anchors illustrate the strategic divergence between premium patient-experience positioning and volume-driven institutional supply.
| Leading Market Players |
|---|
| Coloplast Corp |
| Hollister Incorporated |
| Teleflex Incorporated |
| BD |
| Convatec Inc. |
| B. Braun Melsungen AG |
| Medline Industries, LP |
| Cardinal Health |
| Dentsply Sirona |
| Others |
Cost & Logistics Intelligence
Medical-grade silicone price indices cascade through catheter manufacturing tiers, compressing margins on uncoated PVC devices while amplifying premium capture for hydrophilic-coated alternatives in reimbursement-rich channels.
Pricing Analysis
Service bundling splits between standalone catheter units and closed-system kits with collection bags and sterile supplies. Three-tier pricing structure across premium hydrophilic, standard silicone, and economy PVC levels separates reimbursement-eligible home care from tender-driven hospital procurement. Price differentiation hinges on coating certification grade and volume scale, with Medicare Advantage prior authorization complexity steering patients toward bundled premium offerings. Pricing pressure stems from REACH-mandated DEHP reformulation costs that manufacturers cannot pass through in commoditized Nelaton segments. Hospital GPO buyers exhibit highest price sensitivity, while neurogenic bladder patients in durable medical equipment channels accept per-unit premiums for trauma-reducing hydrophilic surfaces.
Supply Chain Analysis
Pharmaceutical-grade polyvinylpyrrolidone feedstock rests on German, Swiss, and Danish specialty chemical producers controlling coating polymer supply. Raw material dependencies span medical-grade silicone competing with semiconductor demand, DEHP-free PVC formulations, and saline-activated hydrogel precursors. Single-source vulnerability concentrates in hydrophilic polymer chemistry, where force majeure at any of three European suppliers would disrupt coating production globally. Distribution runs through durable medical equipment providers in the United States, hospital procurement consortia in Germany, and BIS-certified domestic manufacturers serving Indian price-sensitive demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intermittent catheters market functions as a stable compounder anchored by irreversible demographic shifts toward aging populations and rising spinal cord injury prevalence in developed economies.
For Market Incumbents: Anticipate EU MDR compliance cost escalation by consolidating coating chemistry partnerships with established European polymer suppliers before biocompatibility documentation deadlines filter out mid-tier competitors. Prioritize backward integration into saline-activated hydrogel formulation to secure supply continuity against single-source chemical dependency, while expanding direct-to-patient channel infrastructure to capture Medicare Advantage enrollment growth in Florida and California rehabilitation corridors. For New Entrants and Emerging Players: The premium-economy price-point gap in pediatric catheter sizing creates viable entry territory for manufacturers with 6-10 Fr production capability targeting underpenetrated Indian and Brazilian hospital networks. White-space concentration sits in closed-system intermittent catheter kits for long-term care facilities balancing CAUTI protocols with Medicaid reimbursement constraints. Pursue BIS certification pathways and CDSCO registration to access price-sensitive Asian procurement tenders where domestic manufacturing clusters in Ahmedabad and Chennai already serve regional export demand. For Investors and Strategic Acquirers: Asymmetric upside sits with coating-specialist manufacturers possessing EU MDR-compliant polymer supply relationships and existing ISO 10993 biocompatibility dossiers. Long-term viability over a 5-10 year window favors targets with demonstrated PMDA fast-track qualification experience and established durable medical equipment distribution partnerships. The signal to watch is Medicare reimbursement recalibration for single-use hydrophilic devices, which would accelerate premium segment expansion velocity and revalue coating-capable assets.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR biocompatibility documentation accelerates consolidation toward established coating specialists with regulatory infrastructure. |
| Hospital System Partnership | GPO contract penetration in United States acute care networks secures high-volume Nelaton procurement despite margin compression. |
| Reimbursement Strategy | Medicare Advantage prior authorization navigation determines hydrophilic-coated device penetration in home care channels. |
| Backward Integration | In-house polymer formulation capability reduces vulnerability to European specialty chemical supply concentration. |
| Pediatric Portfolio Expansion | 6-10 Fr diameter production capability unlocks margin pools in children's hospitals with limited supplier bases. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with urology clinicians, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and durable medical equipment distributors with secondary validation against FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement schedules, and hospital procurement contract records. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored volume estimates.
Comparable-period anchoring linked historical catheterization procedure volumes to forward projections across the analysis window, with segmentation modeling across material chemistry, tip configuration, end-user channel, and clinical indication dimensions. CAGRs derived from procedure growth trajectories, reimbursement expansion elasticity, and coating technology substitution curves informed value expansion estimates. Forecast inputs incorporated spinal cord injury prevalence demographics, REACH regulatory phase-in timelines, and saline-activated polymer chemistry adoption rates.
Caveats apply where EU MDR compliance deadline extensions, Medicare reimbursement recalibration, or medical-grade silicone supply allocation disruptions could materially shift the outlook. Forecasts reflect documented assumptions about hydrophilic coating penetration elasticity and home care channel expansion velocity. A small set of named triggers—PMDA fast-track designation outcomes, BIS certification backlog resolution, and coating technician vocational pipeline output—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Orbital Tissue Expander Market
Medical Devices
Meniscus Repair Systems Market
Medical Devices
Global Sperm Separation Devices Market
Medical Devices
Acne Treatment Devices Market
Medical Devices
China Electrocardiograph (ECG) Market
Medical Devices
Global Biopsy Punch Market
Medical Devices
Global Brachytherapy Treatment Planning Systems Market
Medical Devices
Ingestible Smart Pills Market
Medical Devices
Pacemaker Devices Market
Medical Devices
Slip Disc Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Electrophysiology Market
Medical Devices
Needle Destroyer Market
Medical Devices
Global Reflex Hammer Market
Medical Devices
Anti-Snore Device Market
Medical Devices
Esophagoscopes and Gastroscopes Market