
 Benign Prostatic Hyperplasia Market | 2026-2036
Benign Prostatic Hyperplasia Market Size, Share, and Industry Trends Forecast 2026-2036
Benign Prostatic Hyperplasia Market Analysis
Single-source reliance on branded pharmaceutical suppliers is decoupling as hospital procurement committees diversify formularies across alpha blockers and combination therapies. Astellas Pharma anchors its position through sustained manufacturing scale in oral 5-alpha reductase inhibitors. Eli Lilly differentiates via specialized urology channel partnerships. Boston Scientific competes in surgical devices with technology leadership in transurethral platforms.
Benign prostatic hyperplasia denotes a histologic and clinical condition of nonmalignant prostate enlargement arising from stromal and epithelial cell proliferation within the transition zone, typically quantified by International Prostate Symptom Score severity and measured prostate volume exceeding 30 milliliters on transrectal ultrasound. The condition obstructs bladder outflow, necessitating pharmacologic relaxation of prostatic smooth muscle or mechanical tissue reduction to restore urinary function. Alpha blockers occupy the largest revenue pool due to established first-line prescribing patterns, while surgical devices represent the fastest-expanding segment as ambulatory surgical centers adopt same-day discharge protocols. Combination therapy captures concentrated margins where payers authorize sequential pharmacologic regimens for moderate-to-severe symptom profiles.
FDA and EMA oversight of novel surgical devices shapes clinical trial requirements and post-market surveillance obligations, directly influencing product development timelines and commercial launch sequencing. The EU Medical Device Regulation intensifies conformity assessment demands for transurethral delivery systems, compressing margins for manufacturers lacking notified body relationships. Stakeholders must monitor health technology assessment body positioning on robotic versus conventional surgical platforms to anticipate reimbursement-driven demand shifts.
Market Dynamics
Transurethral minimally invasive platforms are compressing the surgical care pathway, displacing open prostatectomy as hospital systems prioritize same-day discharge capacity and ambulatory surgical center accreditation.
Growth Catalysts
- EMA reimbursement stabilization:National health technology assessment frameworks in Germany, France, and the United Kingdom now cover transurethral procedures, accelerating device procurement cycles in Western European hospital systems.
- Ambulatory surgical center expansion:United States outpatient facilities are investing in transurethral platforms to capture Medicare-reimbursable same-day procedures previously confined to inpatient settings.
- Prostate-specific antigen screening protocols:Systematic early detection programs in aging Western European populations are expanding the addressable patient pool requiring intervention.
Market Restraints
- EU Medical Device Regulation conformity costs:Intensified notified body assessment demands for transurethral delivery systems compress margins for manufacturers lacking established regulatory relationships.
- Input concentration in precision optics:German and Japanese suppliers dominate high-resolution endoscopic component supply, creating vulnerability for device assemblers elsewhere.
- Pharmacologic substitution persistence:Alpha blocker and 5-alpha reductase inhibitor maintenance therapy delays surgical intervention in moderate symptom profiles.
Strategic Opportunities
- Underpenetrated Asia-Pacific markets:Japan and South Korea present expansion potential as aging demographics converge with private hospital infrastructure investment.
- Robotic platform integration:Convergence of transurethral delivery systems with surgical robotics enables precision tissue ablation in high-volume academic medical centers.
- Combination therapy authorization:Sequential pharmacologic regimens for moderate-to-severe symptom profiles capture concentrated margins where payers authorize multi-agent protocols.
Industry Challenges
- Urological surgical specialist scarcity:Transurethral platform adoption requires fellowship-trained operators, constraining procedure volume growth in community hospital settings.
- Legacy electronic health record integration:Ambulatory surgical centers face friction connecting new device telemetry to existing patient management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benign Prostatic Hyperplasia Market |
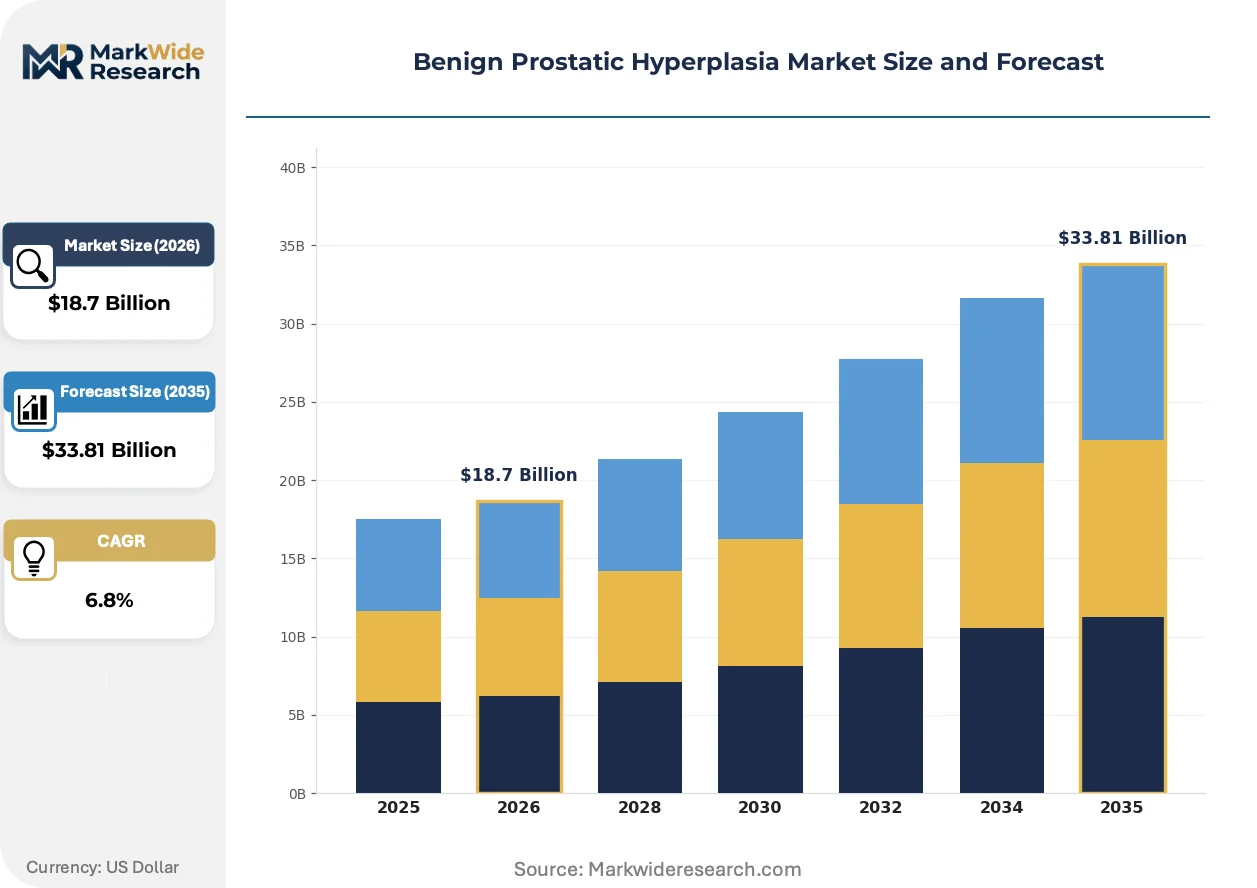
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 5-Alpha Reductase Inhibitors, Alpha Blockers, Combination Therapy, Surgical Devices End User: Hospitals, Ambulatory Surgical Centers, Clinics, Homecare Settings Delivery Mode: Surgical, Oral, Injectable, Transurethral Application: Urology, Healthcare, Research Institutions, Outpatient Care |
| Companies Covered | Astellas Pharma Inc., Eli Lilly and Company, GlaxoSmithKline, Allergan PLC, Boehringer Ingelheim, Merck & Co., Inc., Teleflex Incorporated, Boston Scientific Corporation, PROCEPT BioRobotics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benign Prostatic Hyperplasia Market Emerging Trajectories
Laser and radiofrequency ablation modalities are restructuring the competitive hierarchy among surgical device manufacturers, with energy-delivery precision becoming the primary differentiation axis.
Photoselective vaporization and holmium laser enucleation are overtaking transurethral resection of the prostate in high-volume centers. Academic medical centers in Germany and the United States are adopting these platforms at accelerated procurement cycles. The shift is compressing market share for monopolar resection systems and elevating manufacturers with integrated laser fiber supply chains.
The EU Medical Device Regulation is tightening post-market surveillance obligations for active surgical implants. Manufacturers must now maintain clinical follow-up registries for transurethral energy delivery systems. The surgical device segment is responding by front-loading clinical evidence generation and diversifying notified body relationships across multiple EU member states.
Hospital procurement committees are consolidating vendor relationships around full-service urology portfolios. Single-source reliance on branded pharmaceutical suppliers is decoupling as formulary diversification accelerates. This pattern is most visible in Western European hospital systems where procurement centralization mandates cross-category supplier performance guarantees.
Benign Prostatic Hyperplasia Market Segmentation
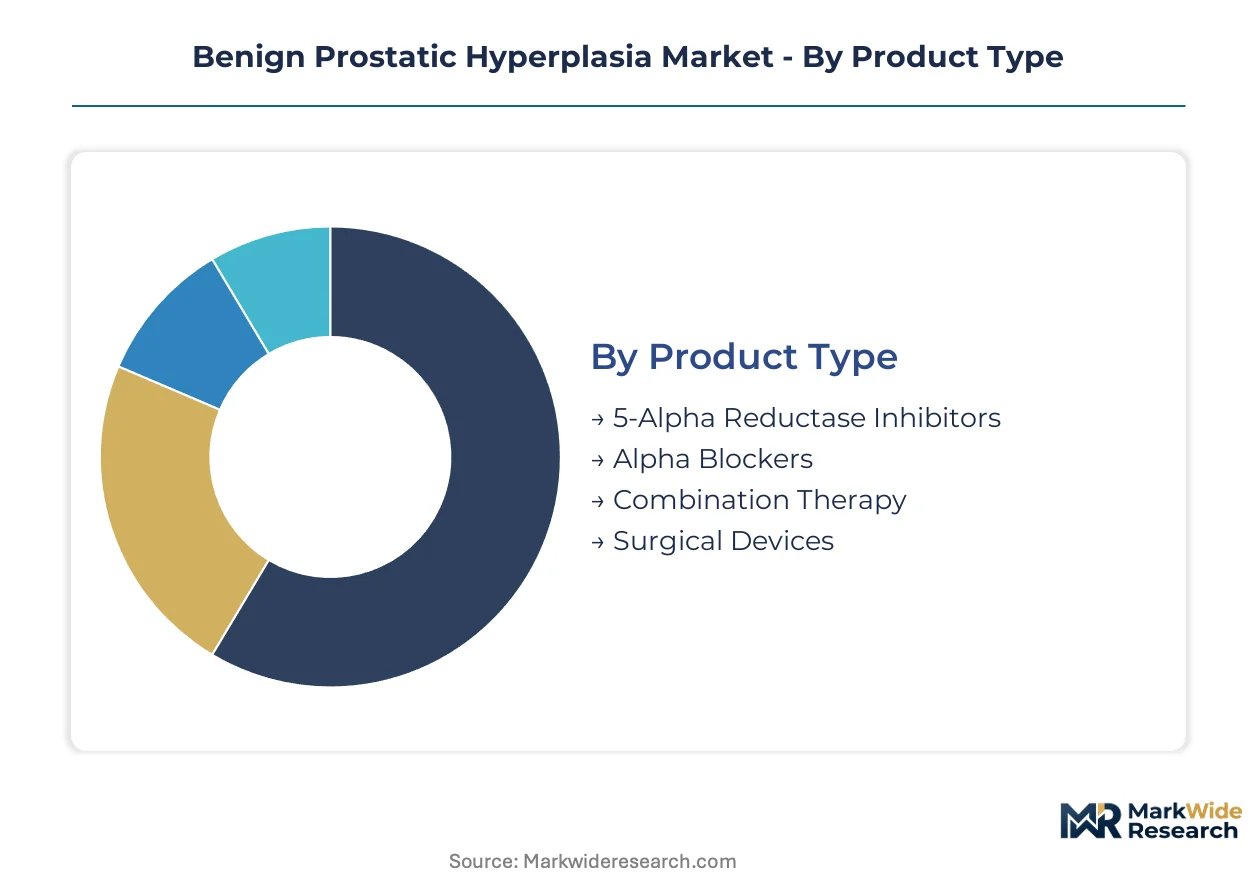
Benign prostatic hyperplasia treatment pathways diverge sharply between chronic pharmacologic management and acute surgical intervention. Procurement committees weight reimbursement status, procedure volume capacity, and patient risk stratification when allocating budget across these segments.
Product Type:
Volume concentrates in oral maintenance therapies prescribed through primary care channels, while premium margins attach to surgical platforms deployed in tertiary settings.
- Alpha Blockers:Tamsulosin and silodosin formulations dominate first-line prescribing through relaxed prostatic smooth muscle targeting. Demand clusters in United States Medicare formularies and German statutory health insurance reimbursement lists where generic substitution has compressed unit pricing.
- Surgical Devices:Transurethral laser and radiofrequency platforms command capital budgets in high-volume academic medical centers. Procurement accelerates in France and the United Kingdom where EMA-cleared devices secure national health technology assessment coverage for same-day discharge protocols.
- 5-Alpha Reductase Inhibitors:Dutasteride and finasteride target glandular volume reduction over six-month horizons.
- Combination Therapy:Sequential alpha blocker and 5-ARI regimens capture authorization in moderate-to-severe symptom profiles.
Mature deployment sits with Alpha Blockers. Newer deployment is concentrated in Surgical Devices.
End User:
Site-of-care migration from inpatient wards to outpatient facilities is redistributing procedure economics and device procurement authority.
- Hospitals:Tertiary urology departments retain complex cases requiring robotic-assisted or open conversion capabilities. German university hospitals and United States academic medical centers anchor installed base for holmium laser enucleation platforms.
- Ambulatory Surgical Centers:Medicare-reimbursable same-day transurethral procedures are expanding addressable volume beyond traditional inpatient settings. United States outpatient facilities invest in laser vaporization systems to capture migration from hospital outpatient departments.
- Clinics:Urology specialty practices manage chronic pharmaceutical therapy and preoperative staging.
- Homecare Settings:Post-procedure catheter management and medication adherence monitoring extend care continuity.
Capital intensity peaks in Hospitals. Volume expansion is climbing the fastest in Ambulatory Surgical Centers.
Delivery Mode:
Mechanical tissue reduction modalities compete with pharmacologic relaxation on speed of symptomatic relief and durability of outcome.
- Transurethral:Minimally invasive energy delivery through natural orifices eliminates abdominal incision. Adoption concentrates in Western European hospital systems where EMA device regulation and national reimbursement frameworks have stabilized coverage pathways.
- Surgical:Open and robotic-assisted prostatectomy reserves for massive gland volume or concomitant pathology. Academic medical centers in Germany and the United States maintain capability for complex reconstruction.
- Oral:Once-daily alpha blocker and 5-ARI tablets dominate chronic maintenance prescribing.
- Injectable:Intraprostatic botulinum toxin and alcohol ablation remain investigational or niche applications.
Standard-of-care maturity rests with Oral delivery. Steepest expansion trajectory belongs to Transurethral platforms.
Application:
Clinical purpose determines reimbursement coding, regulatory pathway, and evidence requirements for market access.
- Urology:Board-certified specialists direct definitive therapy selection through International Prostate Symptom Score stratification and transrectal ultrasound volume assessment. Demand concentrates in dedicated urology clinics across France, the United Kingdom, and Germany.
- Outpatient Care:Same-day diagnostic workup and procedural intervention compress total episode cost. Ambulatory surgical centers in the United States and private hospital networks in South Korea are expanding capacity.
- Healthcare:Integrated delivery networks coordinate primary screening through specialist referral.
- Research Institutions:Academic centers generate pivotal trial data for novel device and pharmaceutical submissions.
Revenue concentration aligns with Urology. Outpatient Care is gaining share fastest through site-of-care migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity optical glass manufacturing clusters in Jena and Wetzlar anchor German supply chains for transurethral surgical platforms. Precision component foundries in Aichi Prefecture feed Japanese endoscopic assembly lines. Active pharmaceutical ingredient synthesis corridors in Hyderabad and Ahmedabad supply generic alpha blocker formulations across emerging markets.
United States
Medicare reimbursement for same-day transurethral procedures and ambulatory surgical center accreditation standards drive device procurement. FDA 510(k) clearance pathways for laser vaporization systems shape competitive entry sequencing. Academic medical centers in Boston and Houston anchor installed bases for holmium laser enucleation platforms.
Germany
Statutory health insurance reimbursement lists for alpha blockers and national health technology assessment coverage for minimally invasive surgery concentrate demand. EMA device regulation and EU Medical Device Regulation conformity assessment govern transurethral platform commercialization. University hospitals in Munich and Heidelberg lead adoption of photoselective vaporization systems.
Japan
Aging demographics and prostate-specific antigen screening protocols expand the addressable patient pool requiring intervention. PMDA oversight of novel surgical devices influences clinical trial design and post-market surveillance obligations. Medical device clusters in Nagoya and Osaka supply precision endoscopic components to domestic and export markets.
United Kingdom
National Institute for Health and Care Excellence technology appraisals for combination therapies and surgical interventions determine formulary access. NHS procurement centralization mandates cross-category supplier performance guarantees for urology portfolios. Tertiary referral centers in London and Manchester coordinate complex case management and device evaluation.
France
ANSM national health technology assessment frameworks for transurethral procedures stabilize reimbursement pathways for minimally invasive platforms. HAS evaluation of robotic versus conventional surgical platforms influences hospital capital allocation decisions. Urology clinics in Paris and Lyon expand adoption of same-day discharge protocols for laser-based interventions.
Benign Prostatic Hyperplasia Market Vendor Landscape
Portfolio diversification dominates the current landscape as pharmaceutical and device manufacturers extend across pharmacologic and mechanical treatment modalities. The vendor base organizes around three strategic archetypes: multinational pharmaceutical conglomerates with urology-specialized divisions, integrated surgical device manufacturers with energy-delivery platforms, and mid-cap robotics specialists targeting precision tissue ablation. M&A activity and strategic technology licensing agreements represent the primary competitive moves as firms seek to assemble full-service urology portfolios.
Within the pharmaceutical archetype, Astellas Pharma Inc. and Eli Lilly and Company occupy positions anchored by sustained manufacturing scale and specialized channel partnerships respectively. Boston Scientific Corporation exemplifies the integrated surgical device manufacturer archetype, while PROCEPT BioRobotics Corporation represents the emerging robotics-specialist segment targeting precision transurethral delivery.
| Leading Market Players |
|---|
| Astellas Pharma Inc. |
| Eli Lilly and Company |
| GlaxoSmithKline |
| Allergan PLC |
| Boehringer Ingelheim |
| Merck & Co., Inc. |
| Teleflex Incorporated |
| Boston Scientific Corporation |
| PROCEPT BioRobotics Corporation |
| Others |
Supply Flow & Price Mechanics
EU MDR post-market surveillance mandates gate qualified supply access and premium-tier pricing authorization for transurethral surgical platforms. Manufacturers lacking clinical follow-up registry capabilities face exclusion from high-margin procurement contracts in German and French hospital systems.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier surgical platform vendors from unbundled equipment suppliers competing on capital cost alone. Pricing stratifies across premium, standard, and economy tiers based on CE marking tier under EU MDR and manufacturer scale. Cost compression in economy-tier alpha blockers intensifies because generic substitution has saturated United States Medicare formularies. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraint, while academic medical centers prioritize outcome durability over acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements for high-resolution endoscopic components now dominate procurement specifications from German and Japanese optical suppliers. Precision optics manufacturing draws from Jena-Wetzlar clusters in Germany and Aichi Prefecture in Japan, while active pharmaceutical ingredient synthesis rests on Hyderabad-Ahmedabad corridors in India. Single-source vulnerability concentrates in germanium-doped optical fiber supply for holmium laser systems. Distribution runs through hospital procurement committees consolidating around full-service urology portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The benign prostatic hyperplasia market has become a vertical-integration race, with device manufacturers pursuing backward integration into precision optical component production to secure supply and margin control.
For Market Incumbents: To counter pharmacologic substitution delaying surgical intervention, secure exclusive supply agreements with German and Japanese optical component foundries. Invest in CE marking tier elevation under EU MDR to maintain premium pricing authorization in French and British hospital systems. For New Entrants and Emerging Players: Ambulatory surgical center procurement committees represent the most penetrable channel partner type for transurethral platform market entry. Target United States outpatient facilities seeking Medicare-reimbursable same-day discharge capability. Differentiate through integrated laser fiber supply chains eliminating third-party dependency. For Investors and Strategic Acquirers: FDA 510(k) clearance for novel laser vaporization systems is the leading indicator that robotic platform convergence is accelerating. Frame long-term viability around precision tissue ablation capability in high-volume academic centers. Target mid-cap surgical robotics specialists with established PMDA relationships in Japan. Watch EMA reimbursement stabilization in additional EU member states as the inflection signal for European demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment unlocks reimbursement coverage in German statutory health insurance. |
| Hospital System Partnership | Academic medical centers in Boston and Houston anchor installed bases for novel laser platforms. |
| Backward Integration | In-house production of precision optics mitigates supply vulnerability from Japanese component suppliers. |
| Reimbursement Strategy | NICE technology appraisals determine formulary access for combination therapies in NHS England. |
| Software Companion Development | Device telemetry integration resolves EHR friction in ambulatory surgical center adoption. |
Methodological Framework
FDA 510(k) filings, EMA device registration databases, and CMS Medicare reimbursement schedules formed the secondary backbone of this analysis. Primary interviews with urology department heads, hospital procurement committee members, biomedical engineers, and GPO contracts managers validated demand assumptions. Bottom-up procedure volume estimates and top-down pharmaceutical revenue triangulation anchored market sizing across the analysis window.
Historical trendline analysis of transurethral procedure migration from inpatient to outpatient settings informed the projection framework. Segmentation modeling incorporated treatment modality, site-of-care delivery, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from weighted average of procedure volume growth and pricing trajectory assumptions, with specific inputs from prostate-specific antigen screening protocol expansion and ambulatory surgical center accreditation standards.
Caveats apply where EU MDR notified body capacity constraints or pharmacologic substitution persistence could materially shift the outlook. Deviation in EMA reimbursement stabilization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Penile Cancer Market
Urology
Urology Lasers Market
Urology
Global Urinary Tract Infections Therapeutics Market
Urology
Global Hydronephrosis Market
Urology
Prostatic Arterial Embolization (PAE) Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
Varicocele Treatment Market
Urology
Urinary Catheters Market
Urology
Ureteral Catheters Market
Urology
Global Prostate Cancer Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market
Urology
Urinary Tract Infection Testing Market
Urology
Urinary Retention Therapeutics Market
Urology
Global Bladder Scanner Market
Urology
Prostate Cancer Treatment Market