
 United States Pasta Sauce Market | 2026-2036
United States Pasta Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
United States Pasta Sauce Market Intelligence
A capital-intensity divergence between large-scale manufacturers and regional craft producers is reorganizing competitive dynamics in the United States pasta sauce landscape. Campbell Soup Company leverages its extensive distribution network and shelf-stable manufacturing infrastructure to sustain national retail presence. The Kraft Heinz Company anchors its position through backward integration into tomato processing and centralized procurement systems. Mizkan Holdings Co., Ltd. differentiates via specialized Asian-inspired and fusion sauce portfolios that occupy niche grocery segments.
United States pasta sauce comprises cooked and seasoned tomato-based or cream-based preparations, typically containing 6-12% total solids, acidified to pH 4.6 or below for shelf stability, and thermally processed for commercial distribution to foodservice and retail channels. Tomato sauce remains the dominant product type by volume, though pesto sauce commands premium shelf positioning in specialty shops and upscale supermarkets. Glass jar packaging leads in perceived quality and recycling compliance, while plastic bottles compete aggressively in convenience stores and mass-market channels. Online retail represents the fastest-growing distribution vector, reshaping how brands navigate direct-to-household fulfillment economics.
The FDA governs acidified food regulations and nutrition labeling standards that directly constrain ingredient declarations and sodium content claims in pasta sauce formulations. USDA organic certification and state-level California Proposition 65 enforcement create additional compliance layers that segment premium from conventional offerings. Stakeholders must monitor evolving clean-label enforcement thresholds and regional supply chain resilience for tomato concentrate sourcing as climate variability intensifies.
Market Dynamics
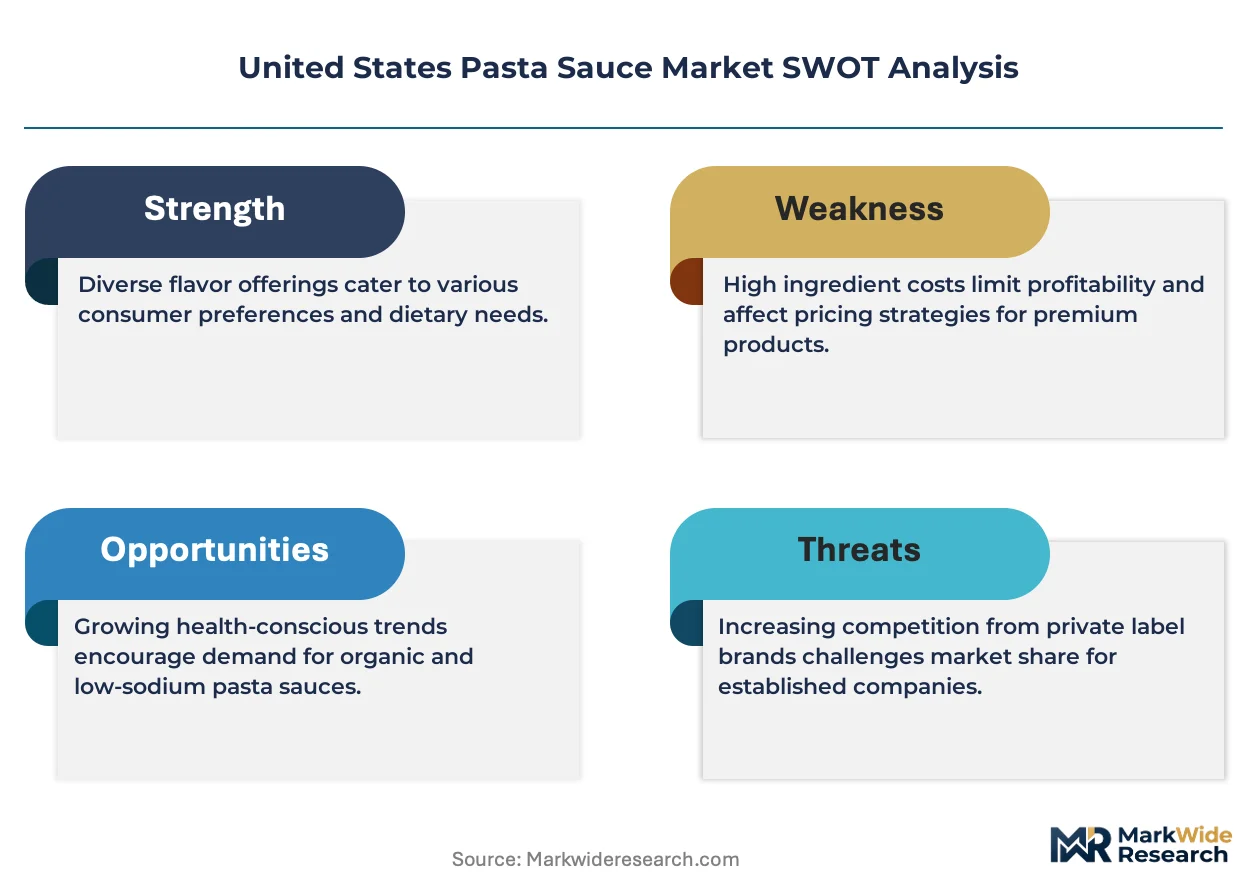
Clean-label ingredient standards and FDA sodium reduction mandates are compressing formulation flexibility while premium positioning gains traction in urban coastal markets. Manufacturers must reformulate legacy recipes without sacrificing shelf stability or taste profiles.
Growth Catalysts
- Foodservice Premiumization:Restaurant chains and catering services are expanding procurement of artisanal and organic pasta sauce variants for menu differentiation.
- California Proposition 65 Enforcement:Stricter contaminant disclosure requirements are accelerating consumer migration toward certified clean-label products.
- Direct-to-Household Fulfillment:Online retail channels are capturing household pantry replenishment cycles previously dominated by supermarket stock-up trips.
Market Restraints
- Tomato Concentrate Sourcing Concentration:California Central Valley climate variability is intensifying supply uncertainty for domestic paste processors.
- Glass Packaging Cost Structure:Energy-intensive jar manufacturing and freight weight premiums compress margins against plastic alternatives.
- Acidified Food Compliance Friction:FDA thermal processing and pH documentation requirements extend new product development timelines.
Strategic Opportunities
- Northeast Corridor Urban Density:New York and Boston metropolitan areas show concentrated demand for small-batch and ethnic fusion sauce portfolios.
- USDA Organic Certification Tailwind:Federal procurement preferences and retailer slotting fee reductions reward certified organic entrants.
- Retort Pouch Technology Convergence:Flexible packaging combined with aseptic filling is opening foodservice bulk and single-serve segments.
Industry Challenges
- Food Scientist Talent Scarcity:Acidified food formulation expertise and thermal process authority qualifications command premium compensation in tight labor markets.
- Legacy Equipment Retrofit Capex:Clean-label reformulations often require stainless steel line replacements and allergen segregation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Pasta Sauce Market |
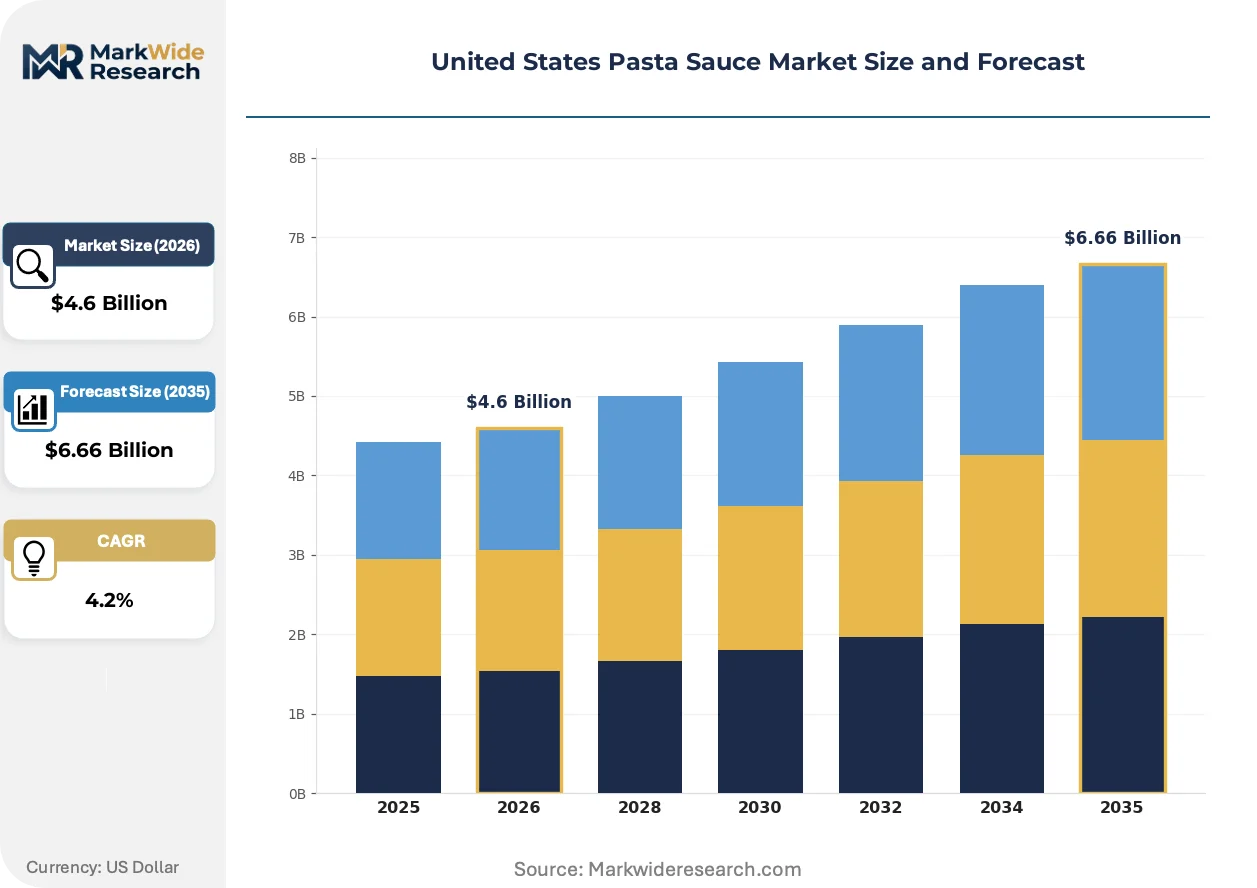
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tomato Sauce, Alfredo Sauce, Pesto Sauce, Marinara Sauce Packaging Type: Glass Jar, Plastic Bottle, Tetra Pack, Canned Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops End User: Households, Restaurants, Catering Services, Food Trucks |
| Companies Covered | Campbell Soup Company, Del Monte Foods, Inc., The Kraft Heinz Company, Mars Incorporated, Unilever, Conagra Brands Inc, Mizkan Holdings Co., Ltd., B&G Foods, Inc., Barilla G. e R. Fratelli S.p.A, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Pasta Sauce Market Strategic Shifts & Innovations
Reformulation priorities are diverging between mass-market sodium reduction and premium clean-label positioning. Technology investments concentrate on shelf-stable texture preservation and sustainable packaging formats.
High-pressure processing is fragmenting traditional thermal pasteurization dominance in refrigerated pasta sauce segments. Specialty retailers and meal-kit assemblers are adopting HPP-treated products for extended cold-chain shelf life without chemical preservatives. This technology is fragmenting the historical trade-off between clean labels and distribution reach.
FDA updated Nutrition Facts labeling requirements are mandating added-sugar disclosure and revised serving size definitions. Reformulation teams must recalculate entire product lines to maintain permissible health claims and avoid consumer backlash on sugar visibility. Shelf-stable tomato sauces face the steepest compliance costs due to concentrated tomato paste base sweetness.
Pantry replenishment behavior is compressing traditional supermarket stock-up cycles into frequent online direct orders. Mass-market brands are losing impulse purchase exposure as households subscribe to auto-delivery programs. California and Northeast urban corridors show the fastest channel migration toward platform-based grocery fulfillment.
United States Pasta Sauce Market Segmentation
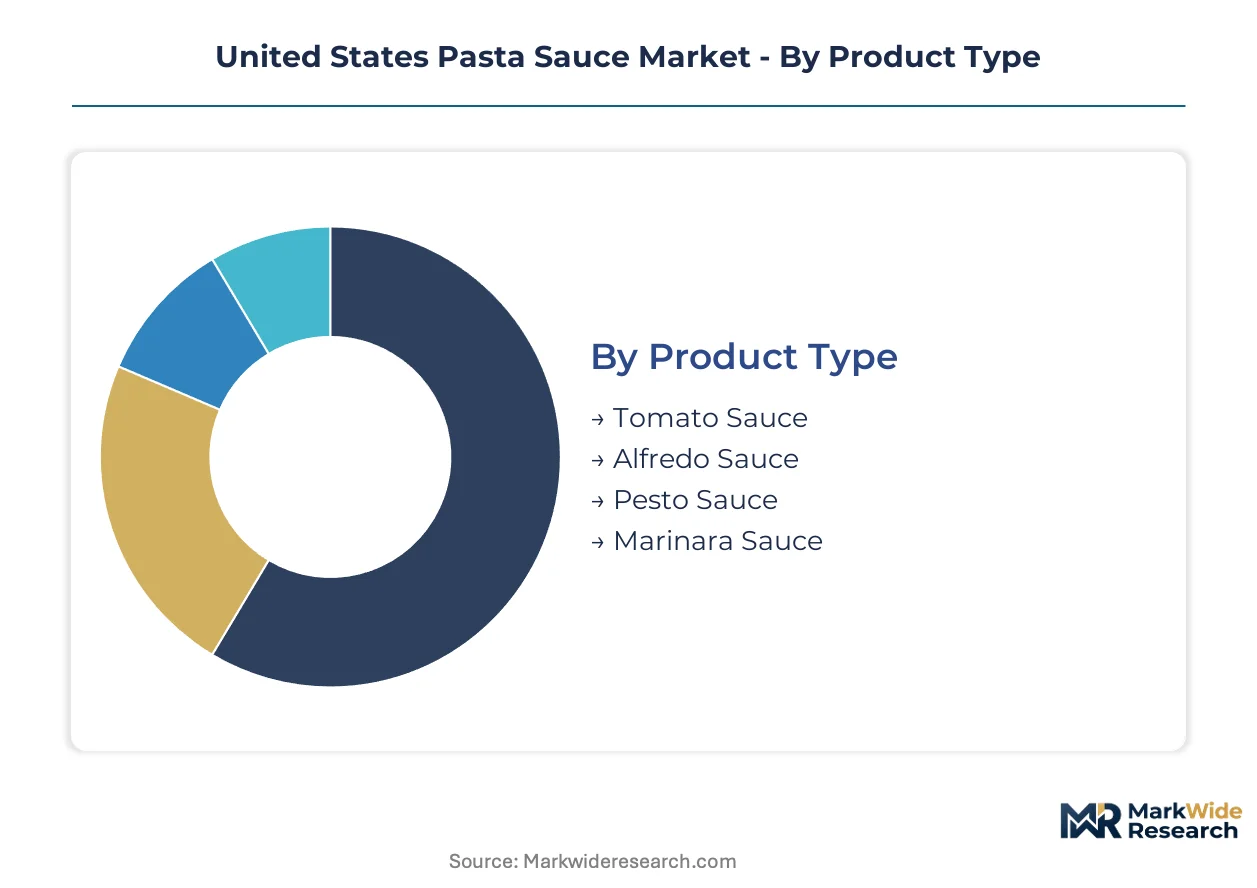
Channel economics in the United States pasta sauce landscape reward distinct formulation and packaging configurations. Manufacturers calibrate viscosity, acidification levels, and thermal processing intensity to match the replenishment cadence and shelf-space constraints of each downstream vector.
Product Type:
Glass jar SKUs concentrate in premium supermarket and specialty retail channels, while foodservice bulk formats flow through direct distribution to restaurant operators.
- Tomato Sauce:Acidified to pH 4.6 or below with 6-12% total solids, this shelf-stable staple undergoes thermal processing for national retail distribution. California and Northeast urban households favor organic and low-sodium variants, though reformulation costs compress margin structures for mass-market labels.
- Alfredo Sauce:Cream-based emulsions require refrigerated cold-chain infrastructure or retort sterilization for shelf-stable positioning. Restaurant chains and catering services in the Northeast Corridor drive procurement of bulk Alfredo formats for menu consistency.
- Pesto Sauce:Basil-forward formulations with olive oil and pine nuts command premium positioning in specialty shops and upscale supermarkets.
- Marinara Sauce:Chunky tomato-herb preparations with shorter cook times than traditional tomato sauce dominate foodservice portion-control pouches.
Tomato sauce dominates installed base. Pesto sauce is where expansion concentrates.
Packaging Type:
Cost tier alignment separates premium glass from economy plastic, with margin structures dictating channel placement and freight economics.
- Glass Jar:Inert barrier properties preserve flavor integrity and support recycling compliance claims. California urban consumers pay shelf-price premiums for perceived quality, though energy-intensive manufacturing and weight-driven freight costs erode competitiveness against plastic alternatives.
- Plastic Bottle:Lightweight PET and HDPE formats dominate convenience store and mass-market channels where price elasticity is acute.
- Tetra Pack:Aseptic carton technology enables ambient distribution with reduced carbon footprint credentials for sustainability-positioned brands.
- Canned:Steel and aluminum formats retain foodservice bulk and institutional procurement contracts with extended shelf-life requirements.
Glass jar commands premium shelf positioning. Plastic bottle is where volume expansion concentrates.
Distribution Channel:
Customer type stratification separates stock-up pantry replenishment from immediate-consumption occasions, reshaping fulfillment infrastructure investments.
- Supermarkets:Center-store placement and end-cap promotions drive impulse velocity for established brands. Traditional stock-up trips concentrate in suburban and exurban geographies where household storage capacity supports multi-jar purchases.
- Online Retail:Platform-based grocery fulfillment captures auto-replenishment subscriptions and direct-to-household delivery in California and Northeast metropolitan corridors. Logistics networks optimize for case-lot shipping and reduced last-mile costs.
- Convenience Stores:Single-serve and value-size plastic bottles address immediate-preparation demand with limited shelf space.
- Specialty Shops:Curated artisanal and ethnic fusion portfolios command slotting fee exemptions for differentiated provenance claims.
Supermarkets dominate transaction volume. Online retail is climbing the fastest.
End User:
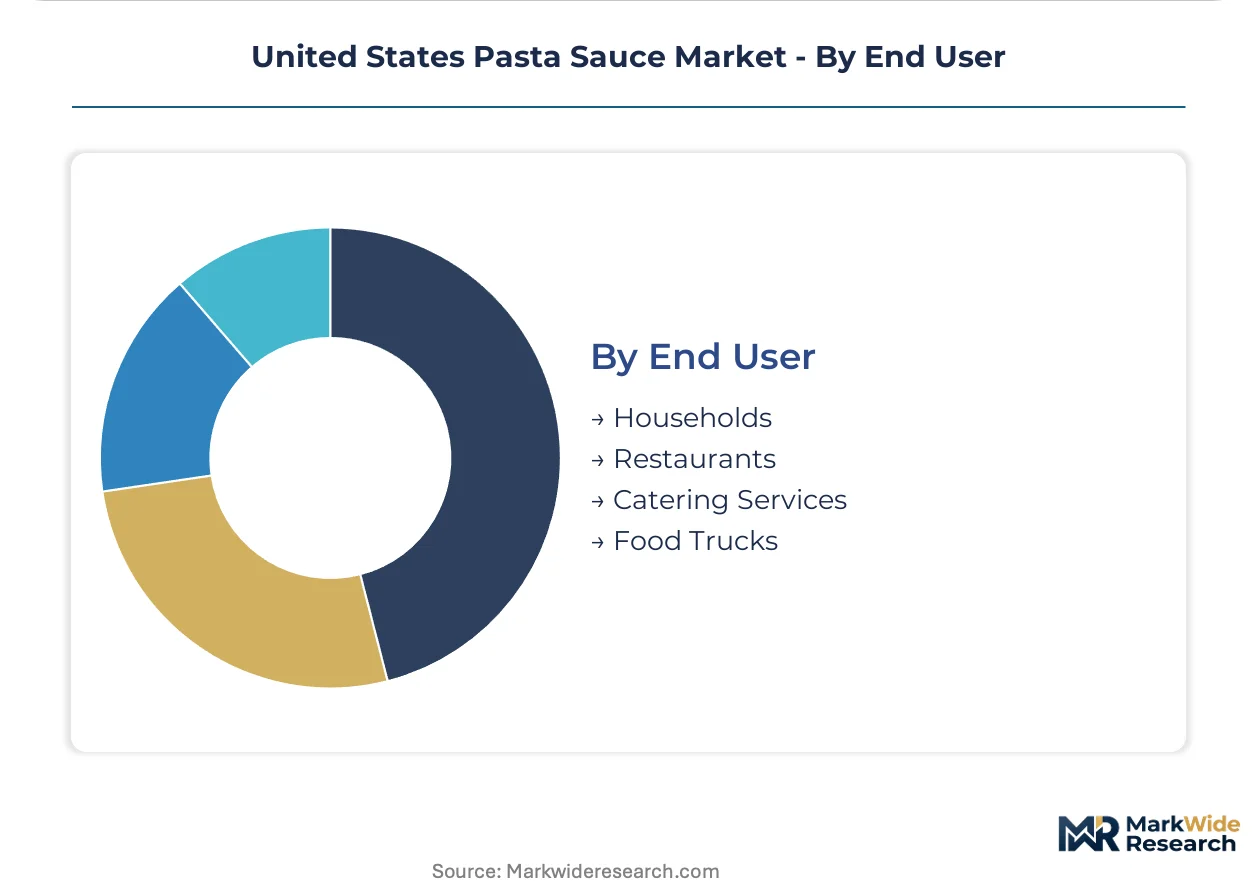
Application intensity separates high-velocity commercial kitchens from intermittent household preparation, dictating pack size and formulation concentration specifications.
- Households:Pantry replenishment cycles are compressing toward frequent smaller-format purchases as online subscription models displace traditional stock-up behavior.
- Restaurants:Chain operators specify consistent viscosity and acidification profiles across locations, driving backward integration into tomato processing for cost control.
- Catering Services:Bulk procurement of shelf-stable and refrigerated formats supports off-premise event execution with variable portion requirements.
- Food Trucks:Space-constrained mobile kitchens favor retort pouch and single-serve packaging with minimal refrigeration dependence.
Households dominate consumption volume. Restaurants are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pasta sauce market operates as a net importer of tomato paste concentrates while exporting finished shelf-stable sauces to Canadian and Mexican markets. Regional consumption patterns diverge sharply between coastal premium corridors and inland value-oriented markets.
California
Urban households in Los Angeles and San Francisco drive artisanal and organic variant demand at shelf-price premiums. FDA acidified food regulations and California Proposition 65 enforcement create dual compliance layers that favor certified clean-label entrants. The Central Valley tomato processing cluster around Fresno and Modesto supplies domestic paste but faces irrigation water allocation pressures from state drought protocols.
Northeast Corridor
New York and Boston metropolitan areas concentrate small-batch and ethnic fusion sauce procurement from specialty retailers and meal-kit assemblers. USDA organic certification unlocks federal procurement preferences and retailer slotting fee reductions for certified entrants. The Port of New Jersey handles bulk tomato concentrate imports from Italy and China that supply regional reprocessors.
Texas
Houston and Dallas-Fort Worth metroplexes anchor foodservice distribution for Mexican-inspired and Southwestern sauce variants. State health department enforcement of FDA nutrition labeling standards shapes reformulation priorities for sodium and added-sugar disclosure. The Interstate 35 corridor warehouses serve as cross-dock nodes for Mexico-imported fresh tomato supplies.
Midwest
Chicago and Detroit manufacturing bases support mass-market production for national retail distribution at economy price tiers. Interstate commerce clause preemption limits state-level formulation variations but allows Illinois and Michigan to enforce supplemental weights-and-measures inspections. The region's cold-chain infrastructure enables refrigerated Alfredo sauce distribution to foodservice accounts.
Florida
Miami and Tampa metropolitan areas exhibit concentrated demand for Italian-imported premium sauces through specialty grocers serving affluent retiree demographics. State agricultural inspection protocols for acidified food imports add documentation friction to European supplier relationships. The Port of Miami handles containerized glass jar imports that bypass domestic manufacturing cost structures.
United States Pasta Sauce Market Key Industry Players
Concentration sits with diversified food conglomerates that leverage backward integration into tomato processing and centralized procurement systems to defend margin positions. Mid-tier regional craft producers occupy specialty retail and direct-to-consumer channels with clean-label positioning. Strategic moves cluster around portfolio diversification into ethnic fusion variants and capacity expansion in retort pouch formats for foodservice bulk segments.
Within the diversified conglomerate tier, Campbell Soup Company and The Kraft Heinz Company exemplify scale-driven national retail presence through extensive distribution networks and shelf-stable manufacturing infrastructure. Mizkan Holdings Co., Ltd. occupies a specialized position representing Asian-inspired and fusion sauce portfolios that target niche grocery segments. These three anchors illustrate the archetype divergence between mass-market volume players and ethnic specialization strategists.
| Leading Market Players |
|---|
| Campbell Soup Company |
| Del Monte Foods, Inc. |
| The Kraft Heinz Company |
| Mars Incorporated |
| Unilever |
| Conagra Brands Inc |
| Mizkan Holdings Co., Ltd. |
| B&G Foods, Inc. |
| Barilla G. e R. Fratelli S.p.A |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between California Central Valley tomato processors and national sauce manufacturers lock in both paste supply access and eighteen-month price visibility against climate-driven harvest volatility. These arrangements concentrate procurement leverage with vertically integrated conglomerates while regional craft producers absorb spot-market exposure.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium organic, standard conventional, and economy private-label tiers. Price differentiation rests on USDA certification grade and volume scale commitments. Cost compression in the glass jar tier is intensifying because energy-intensive manufacturing and weight-driven freight erode competitiveness against plastic alternatives. Mass-market retailers exhibit acute price sensitivity, while specialty grocers serving Northeast Corridor urban households tolerate shelf-price premiums for perceived quality.
Supply Chain Analysis
Strategic stockpile preferences dominate among national manufacturers who maintain six-to-nine month tomato paste inventories against California drought protocols, while just-in-time fresh basil and pine nut sourcing feeds pesto production lines. Supply concentrates in the United States for tomato processing, Italy for premium imported formulations, and China for bulk concentrate imports. Raw material dependencies center on tomato paste, olive oil, and dairy cream bases. Single-source vulnerability sits with California Central Valley irrigation allocation decisions. Distribution runs through direct-to-foodservice bulk contracts and retail center-store placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States pasta sauce market is a high-growth disruption as FDA sodium reduction mandates and clean-label enforcement fragment historical formulation advantages held by legacy brands. High-pressure processing technology is redrawing the trade-off between shelf stability and preservative-free positioning.
For Market Incumbents: Compound backward integration into tomato processing with retort pouch capacity expansion for foodservice bulk segments. Defensive consolidation must address HPP-equipped refrigerated sauce entrants who capture meal-kit assembler procurement. Certification investment in USDA organic tiers unlocks federal procurement preferences and retailer slotting fee reductions.
For New Entrants and Emerging Players: Lead with ethnic fusion portfolios targeting Northeast Corridor specialty retailers where slotting fee exemptions reward provenance differentiation. The most penetrable white space sits in Asian-inspired and Southwestern variants absent from mass-market shelf sets. Go-to-market execution should prioritize platform-based grocery fulfillment subscriptions over traditional supermarket velocity.
For Investors and Strategic Acquirers: Regional craft producers with acidified food formulation expertise and established clean-label positioning represent the priority acquisition archetype. Long-term viability frames around five-to-ten year windows where climate adaptation and regulatory compliance separate consolidatable assets from stranded capacity. The signal to watch is California Proposition 65 enforcement intensity accelerating consumer migration toward certified clean-label products.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tomato Processing | Captive supply of paste insulates margin against California drought-driven spot volatility. |
| Retort Pouch Technology Adoption | Aseptic flexible packaging opens foodservice bulk and single-serve segments with reduced freight cost. |
| USDA Organic Certification Investment | Federal procurement preferences and retailer slotting fee reductions reward certified entrants. |
| High-Pressure Processing Line Addition | HPP-treated refrigerated sauces capture meal-kit assembler demand without chemical preservatives. |
| Direct-to-Consumer Platform Launch | Auto-replenishment subscriptions capture California and Northeast urban pantry replenishment cycles. |
Research Approach
Initial hypotheses were tested against primary input from brand managers, category buyers at national retailers, foodservice procurement directors, and acidified food formulation scientists, then refined against secondary validation from FDA acidified food regulation filings, USDA organic certification databases, Nielsen retail audit data, and customs import records for tomato concentrate. Bottom-up volume modeling triangulated against top-down value estimates anchored the forecast framework.
Variance decomposition across product type, packaging format, distribution channel, and end-user application segments shaped the analytical approach over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by price-tier assumptions. Forecast inputs incorporated California Central Valley irrigation allocation protocols and Northeast Corridor urban household pantry replenishment behavior shifts.
Forecasts assume regulatory continuity in FDA acidified food standards and California Proposition 65 enforcement thresholds; material policy shifts would require re-modeling. Climate-driven tomato paste supply disruption or abrupt clean-label enforcement escalation represent specific risk factors. Revision becomes warranted when HPP-equipped refrigerated sauce share crosses mass-market penetration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Sun-Dried Tomato Umami Concentrate Systems Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Fat Free Salad Dressings Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Vinegar and Vinaigrette Market
Condiments & Sauces
Horseradish Sauce Market
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
Sauce Market
Condiments & Sauces
Condiments Market
Condiments & Sauces
Latin America Pasta Sauce Market
Condiments & Sauces
Sweet and Savory Spread Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Sugar Toppings Market
Condiments & Sauces
Sour Dressings Market
Condiments & Sauces
Salad Dressings and Mayonnaise Market
Condiments & Sauces
Dips and Spreads Market