
 Sauce Market | 2026-2036
Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Sauce Market Analysis
Thailand is rewriting regional sauce production dynamics through expanded fermentation capacity and export-oriented industrial parks. Nestle SA leverages its Maggi production network across ASEAN to sustain volume leadership in liquid seasonings. Kikkoman Corporation anchors premium soy sauce positioning through controlled koji fermentation technology and disciplined channel control in North American specialty retail.
Sauce comprises liquid or semi-liquid condiments manufactured through fermentation, thermal processing, or emulsification, typically containing water, acidulants, salt, sweeteners, and flavoring agents with viscosities ranging from pourable to spoonable. The primary commercial purpose is flavor enhancement, moisture retention, and shelf-life extension for prepared foods and home cooking. Ketchup dominates volume in mature Western markets where Heinz-established taste profiles create entrenched consumer habits, while hot sauce captures the fastest expansion as Scoville-driven experimentation spreads through food service and direct-to-consumer channels. Organic ingredient sauces command margin premiums in European and North American retail, though conventional formulations retain cost advantages in emerging markets where price sensitivity governs purchasing decisions.
FDA food additive regulations and USDA organic certification requirements shape product formulation and label claims in the United States, while EU Green Deal sustainable sourcing mandates and EFSA additive safety assessments constrain ingredient portfolios across European manufacturing. BIS packaging standards and FSSAI labeling rules in India create compliance thresholds for imported and domestic sauce producers seeking organized retail placement. Stakeholders must monitor evolving sodium reduction mandates and single-use packaging restrictions as these regulatory vectors increasingly determine which formulation and material investments yield market access.
Market Dynamics
Clean-label reformulations under EU Green Deal sourcing rules are forcing ingredient substitution across fermentation-based sauce production, compressing supply chains toward traceable raw material pools and certified organic acidulants.
Growth Catalysts
- ASEAN Menu Localization:Quick-service operators in Indonesia, Vietnam, and Thailand are expanding proprietary sauce portfolios to replace traditional condiments with branded packaged alternatives, accelerating volume demand in urban retail channels.
- Fermentation Capacity Expansion:Industrial parks across Thailand are scaling controlled koji and anaerobic fermentation infrastructure, enabling export-grade soy and fish sauce output with standardized microbiological profiles.
- FSSAI Organized Retail Compliance:India's packaging standards and labeling rules are consolidating domestic production toward formal sector manufacturers capable of meeting modern trade placement requirements.
Market Restraints
- Soybean Input Volatility:Price swings in non-GMO and organic soybean supplies from Argentina and Brazil compress margin predictability for premium soy sauce producers dependent on certified traceable inputs.
- Single-Use Packaging Restrictions:EU member state implementations of Green Deal packaging mandates are forcing capital-intensive material transitions away from conventional multilayer sachets toward recyclable or compostable alternatives.
- Sodium Reduction Mandates:WHO guidelines and national health frameworks in South Korea and Singapore are constraining permissible salt content, requiring reformulation investment that alters established taste profiles and consumer acceptance curves.
Strategic Opportunities
- Vietnam Urban Penetration:Underdeveloped modern trade sauce penetration in secondary Vietnamese cities creates whitespace for branded entrants as convenience store networks expand beyond Hanoi and Ho Chi Minh City.
- Hot Sauce Scoville Experimentation:Food service channels and direct-to-consumer platforms are cultivating demand for extreme-heat formulations, enabling premium pricing for small-batch producers with proprietary pepper cultivar relationships.
- USDA Organic Certification Tailwind:North American retail buyers are tightening shelf-access criteria around certified organic claims, rewarding producers with existing supply chain certification infrastructure.
Industry Challenges
- Fermentation Microbiologist Scarcity:Industrial-scale koji and controlled fermentation operations face recruitment gaps for technicians capable of managing sterile propagation protocols and contamination prevention systems.
- Legacy Equipment Retrofit Costs:Transitioning thermal processing lines to accommodate clean-label ingredient viscosity profiles and reduced-salt formulations requires substantial capital outlay with extended depreciation timelines.
- Dual Certification Complexity:Simultaneous pursuit of EU organic, USDA organic, and FSSAI compliance creates documentation bottlenecks and audit scheduling conflicts that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sauce Market |
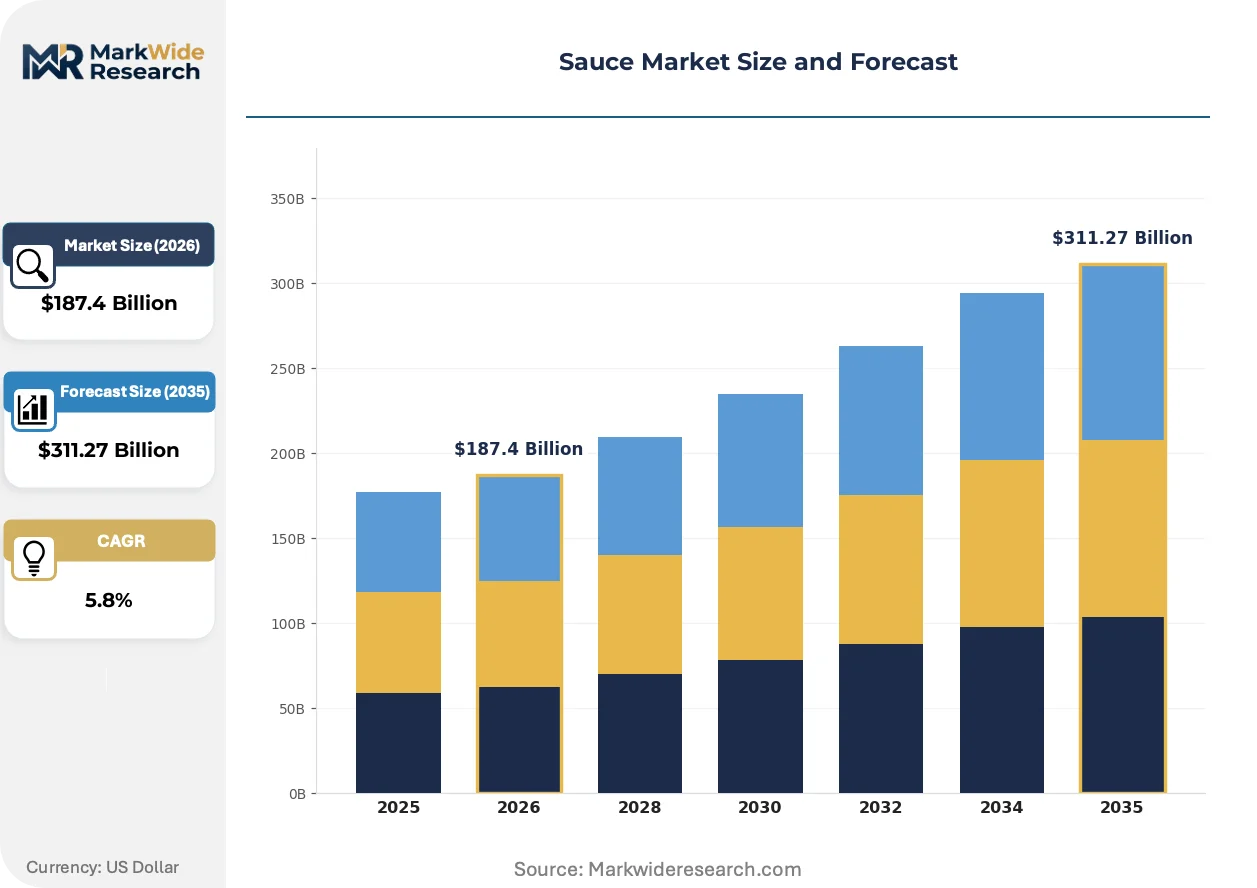
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ketchup, BBQ Sauce, Soy Sauce, Hot Sauce Ingredient Type: Organic, Gluten-Free, Low-Sodium, Non-GMO Packaging Type: Bottles, Sachets, Cans, Jars Distribution Channel: Online Retail, Grocery Stores, Food Service, Wholesalers |
| Companies Covered | Nestle SA, Campbell Soup Co., The Kraft Heinz Co., Cargill Inc., General Mills Inc., Unilever PLC, McCormick and Co. Inc., Kikkoman Corporation, Conagra Brands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sauce Market Emerging Trajectories
Fermentation science and regulatory chemistry are converging to reshape how sauces achieve shelf stability, flavor complexity, and label-friendly positioning without synthetic additive dependence.
Precision-controlled koji fermentation is migrating from artisan-scale operations to industrial volume production. North American specialty retailers and premium food service buyers are adopting these outputs for soy and miso-derived sauces at accelerating rates. This technology is migrating from niche positioning toward mainstream premium shelf placement, compressing the price gap between conventional and craft fermentation methods.
EU Green Deal sustainable sourcing mandates are tightening traceability requirements for palm oil, sugar, and spice supply chains entering European manufacturing. EFSA additive safety assessments are simultaneously constraining permitted preservative portfolios, forcing reformulation toward natural acidulants and high-pressure processing alternatives. Organic ingredient sauces in German and French retail are absorbing the steepest compliance costs, with manufacturers consolidating supplier relationships to reduce audit burden.
Urban Indonesian and Thai consumers are displacing unpackaged traditional condiments with branded bottled and sachet sauces through modern trade penetration. Convenience store chains and e-commerce platforms are capturing this switching behavior with promotional bundling and subscription models. This pattern concentrates in Jakarta, Bangkok, and emerging secondary cities where refrigerated supply chains now support fermented sauce distribution previously limited to ambient-stable alternatives.
Sauce Market Segmentation
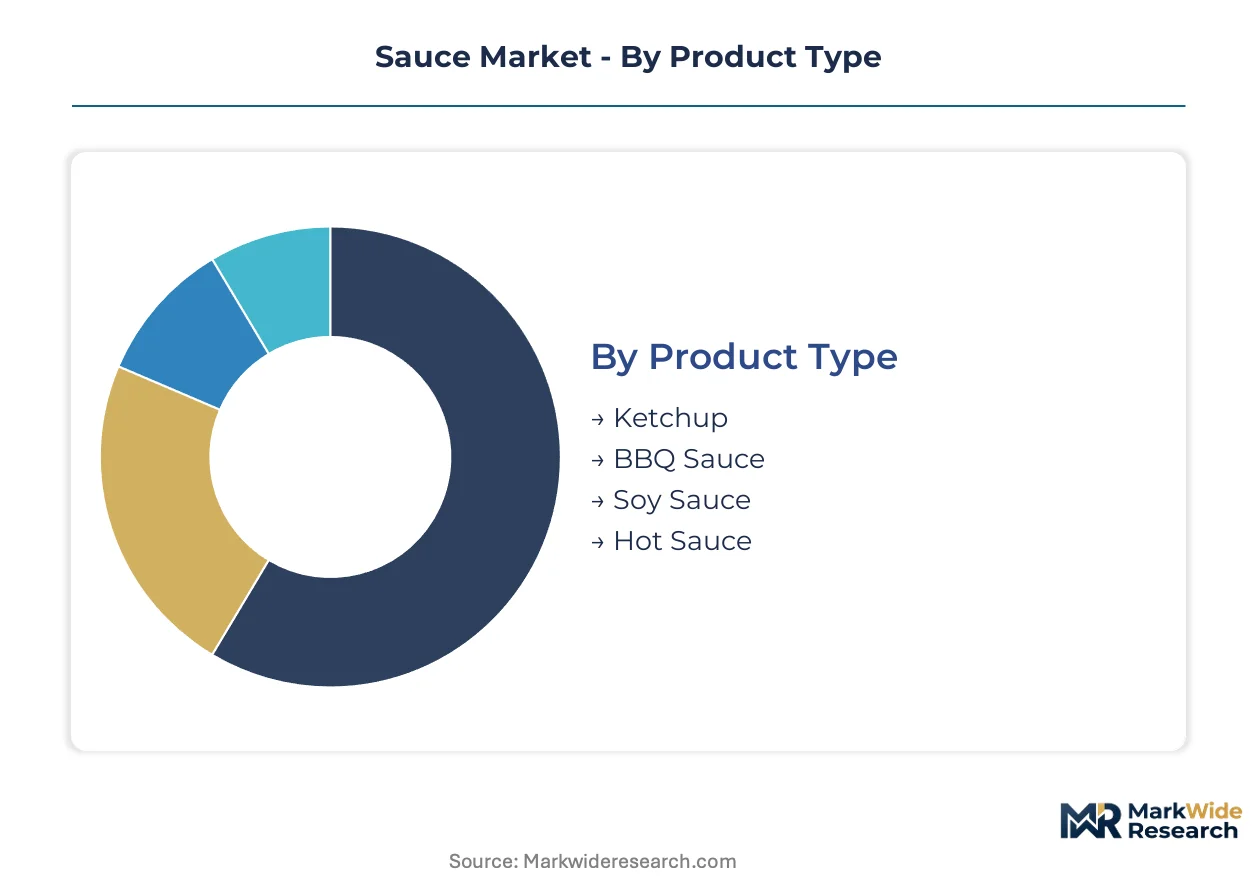
Sauce market segmentation reveals how formulation chemistry, packaging physics, and channel economics create distinct competitive arenas. Each dimension carries diverging margin structures and regulatory exposure, forcing manufacturers to prioritize capability investments against specific buyer segments.
Product Type:
Cost tier differentiation separates commodity-scale production from fermentation-intensive craft positioning across the four primary sauce categories.
- Ketchup:Tomato-based emulsions with vinegar acidulation and high-fructose corn syrup or sugar sweetening achieve shelf stability through thermal processing. Demand concentrates in US and UK retail where Heinz-established taste profiles govern household repurchase patterns, though private-label erosion compresses branded pricing power.
- BBQ Sauce:Smoke-flavored tomato or vinegar bases with molasses, mustard, or pepper infusions vary sharply by regional palate. Southern US smokehouses and Kansas City-style formulations anchor premium positioning, while mass-market variants compete on promotional depth in big-box retail.
- Soy Sauce:Wheat-soybean koji fermentation produces amino acid complexity measured by nitrogen content grades. Japanese shoyu and Chinese light/dark variants dominate Asian food service procurement, with tamari gluten-free alternatives capturing specialty retail placement.
- Hot Sauce:Capsaicin-driven Scoville ratings from chili pepper fermentation or fresh puree define intensity segmentation. Direct-to-consumer channels and food service experimentation are rotating this category up the share rankings fastest.
Ketchup holds installed capacity concentration. Hot sauce is rotating up the share rankings.
Ingredient Type:
Application-driven certification requirements are fragmenting procurement into traceable supply pools with diverging audit burdens.
- Organic:USDA and EU organic certification mandates prohibit synthetic pesticides and GMO inputs across soybean, tomato, and spice supply chains. German and French retail buyers are tightening shelf-access criteria, forcing manufacturers to consolidate supplier relationships.
- Gluten-Free:Fermentation base substitution with rice or alternative grains eliminates wheat proteins for celiac-sensitive consumers. North American specialty retail and food service channels absorb price premiums for validated gluten-free production lines.
- Low-Sodium:Potassium chloride and yeast extract replacements maintain umami intensity while complying with WHO sodium reduction guidelines. South Korea and Singapore health frameworks are constraining permissible salt content, requiring reformulation investment.
- Non-GMO:Identity-preserved soybean and corn sourcing from Argentina and Brazil supports label claims without full organic certification. Premium soy sauce producers face margin compression from input price volatility in certified traceable supplies.
Organic holds installed capacity. Low-sodium is rotating up the share rankings.
Packaging Type:
Volume throughput and material compliance costs are reshaping format selection across retail and food service channels.
- Bottles:PET and glass containers support shelf-stable distribution with resealability for home use. Modern trade penetration in Indonesia and Thailand is displacing unpackaged traditional condiments with branded bottled alternatives.
- Sachets:Multilayer flexible films enable single-serve portions at lowest per-unit cost for quick-service operators. EU Green Deal packaging mandates are forcing capital-intensive transitions toward recyclable or compostable alternatives.
- Cans:Metal packaging supports industrial-scale food service and institutional procurement with extended shelf life. Southeast Asian export-oriented manufacturing parks are scaling canning infrastructure for fish and soy sauce output.
- Jars:Glass containment with lug closures targets premium positioning in specialty retail and gift segments. Controlled fermentation producers favor jars for anaerobic stability in unpasteurized live-culture products.
Bottles hold installed capacity. Sachets are rotating up the share rankings.
Distribution Channel:
Customer type concentration determines margin capture, with direct-to-consumer platforms extracting premium pricing against wholesale volume plays.
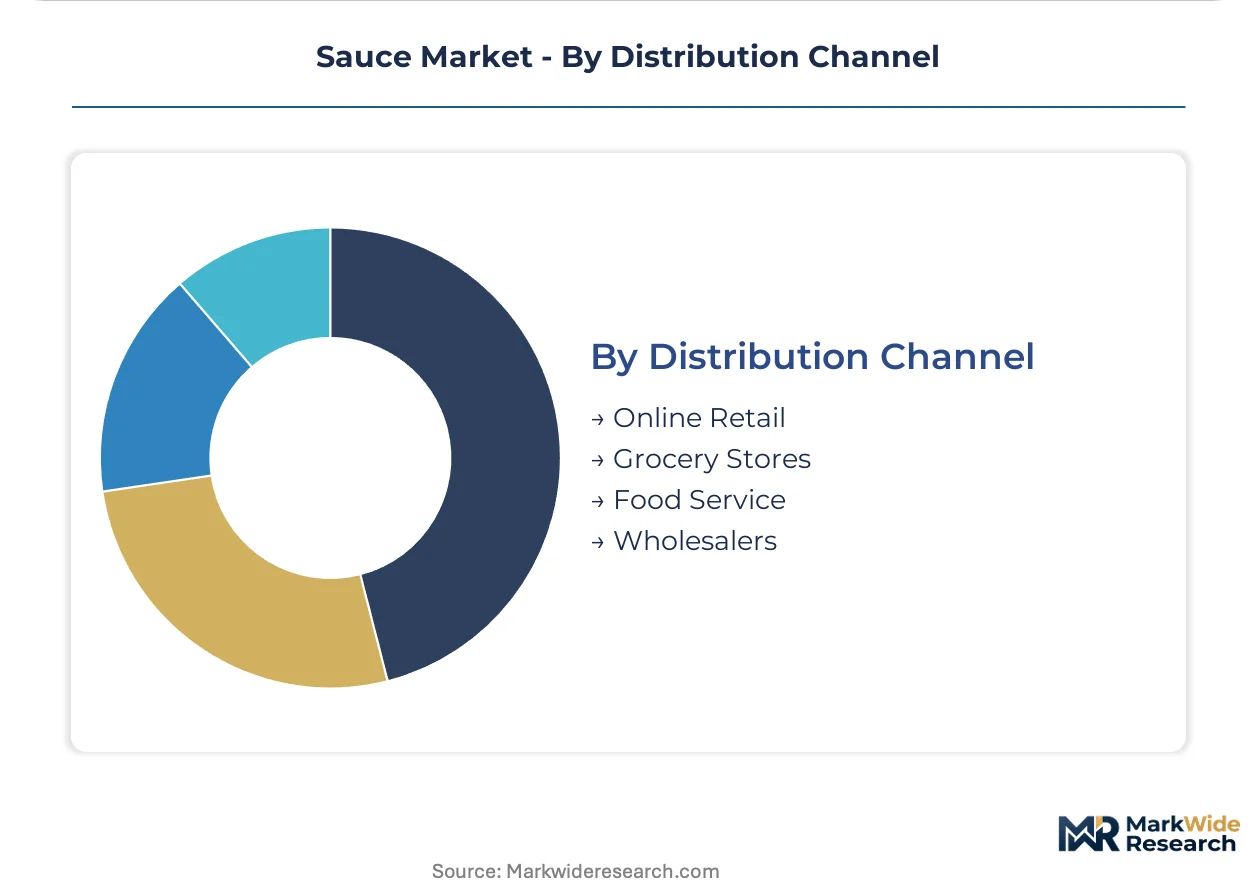
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable subscription bundling and Scoville-driven experimentation. Vietnamese e-commerce penetration in secondary cities creates whitespace for branded entrants beyond Hanoi and Ho Chi Minh City.
- Grocery Stores:Modern trade shelf placement requires FSSAI compliance in India and EFSA label adherence in Europe. Organized retail consolidation favors manufacturers with dual certification infrastructure and promotional funding depth.
- Food Service:Quick-service operators in ASEAN are expanding proprietary sauce portfolios to replace traditional condiments with branded packaged alternatives. Industrial volume contracts prioritize consistency and supply security over margin.
- Wholesalers:Cash-and-carry and distributor networks serve independent restaurants and traditional trade in emerging markets. Price sensitivity governs purchasing decisions where conventional formulations retain cost advantages.
Grocery stores hold installed capacity. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI labeling rules and organized retail compliance thresholds in India anchor the dominant geography, while EU Green Deal mandates and USDA organic certification requirements reshape procurement across secondary markets. Urbanization patterns and quick-service expansion in Southeast Asia concentrate demand generation.
United States
Heinz-established taste profiles govern ketchup repurchase patterns in household retail, while hot sauce experimentation accelerates through food service and direct-to-consumer channels. FDA food additive regulations and USDA organic certification requirements constrain permitted preservative portfolios and label claims. Chicago and Pittsburgh metropolitan clusters host major tomato processing and emulsion manufacturing infrastructure for North American distribution.
Thailand
Export-oriented industrial parks are scaling controlled koji and anaerobic fermentation capacity for standardized soy and fish sauce output. The country's national food safety regulator enforces microbiological standards for fermented products entering modern trade. Bangkok and surrounding Eastern Economic Corridor provinces concentrate fermentation infrastructure investment and regional headquarters operations for ASEAN market coordination.
Germany
Retail buyers in Berlin and Frankfurt metropolitan areas are tightening shelf-access criteria around EU organic certification and clean-label positioning. EFSA additive safety assessments and EU Green Deal sustainable sourcing mandates constrain ingredient portfolios and packaging material selection. Bavaria and North Rhine-Westphalia host reformulation R&D facilities serving pan-European manufacturing networks.
Indonesia
Jakarta and Surabaya urban consumers are displacing unpackaged traditional condiments with branded bottled and sachet sauces through convenience store expansion. BIS packaging standards create compliance thresholds for imported and domestic producers seeking organized retail placement. Java island industrial zones concentrate thermal processing and flexible packaging infrastructure for archipelago distribution.
Vietnam
Secondary cities beyond Hanoi and Ho Chi Minh City present whitespace for branded entrants as modern trade penetration deepens. The country's national food safety framework governs labeling and additive permissions for domestic and imported sauces. Da Nang and Can Tho emerging metropolitan clusters attract distribution center investment supporting convenience store network expansion.
Sauce Market Vendor Landscape
Capability concentration sits with fermentation-intensive specialists; scale advantage sits with diversified packaged goods conglomerates. The market exhibits tiered structure with premium craft positioning at one pole and commodity volume production at another. Three archetypes dominate: heritage fermentation houses with controlled koji expertise, multinational condiment platforms with ASEAN manufacturing networks, and private-label manufacturers serving price-sensitive emerging markets. Capacity expansion in Thai industrial parks and M&A activity targeting organic certification infrastructure represent the dominant competitive moves.
Within the heritage fermentation tier, Kikkoman Corporation exemplifies controlled koji technology positioning, while Nestle SA occupies a position as the diversified platform with Maggi production network scale across ASEAN. Campbell Soup Co. represents the North American condensed and ready-to-serve sauce archetype with established retail distribution density.
| Leading Market Players |
|---|
| Nestle SA |
| Campbell Soup Co. |
| The Kraft Heinz Co. |
| Cargill Inc. |
| General Mills Inc. |
| Unilever PLC |
| McCormick and Co. Inc. |
| Kikkoman Corporation |
| Conagra Brands Inc. |
| Others |
Supply Flow & Price Mechanics
Eastern Economic Corridor fermentation parks in Thailand concentrate industrial-scale koji and anaerobic capacity, translating standardized microbiological output into pricing leverage against fragmented artisan competitors across ASEAN retail channels.
Pricing Analysis
Price spreads between Jakarta modern trade shelves and Bangkok export terminals compress branded premium capture, with three-tier pricing structure across premium, standard, and economy levels governing placement economics. Certification grade—EU organic versus conventional—and volume scale differentiate contract terms, while cost compression in economy sachets intensifies because multilayer packaging transitions absorb capital. Quick-service operators in Indonesia exhibit highest price sensitivity; North American specialty retailers absorbing USDA organic premiums show least.
Supply Chain Analysis
Extended payment terms from Thai industrial park operators to Argentine non-GMO soybean suppliers strain working capital across fermentation-based production networks. Supply concentrates in Thailand, Indonesia, and Vietnam for thermal processing and flexible packaging infrastructure. Raw material dependencies rest on identity-preserved soybeans, palm oil derivatives, and glass container feedstock. Single-source vulnerability in certified organic acidulant pools threatens formulation continuity. Distribution runs through modern trade consolidation in Jakarta and Bangkok, with cash-and-carry networks serving traditional trade in secondary Vietnamese cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where FSSAI and EU Green Deal compliance entrenchment erects switching costs against unqualified entrants seeking organized retail placement.
For Market Incumbents: Insulate volume leadership by deepening backward integration into Thai Eastern Economic Corridor fermentation infrastructure and accelerating dual certification completion for EU organic plus FSSAI alignment. Emerging private-label manufacturers in Indonesian traditional trade pose substitution threats; channel control through convenience store exclusive distribution agreements provides defensive leverage.
For New Entrants and Emerging Players: Da Nang and Can Tho secondary city whitespace in Vietnam offers penetrable terrain as modern trade networks expand beyond Hanoi and Ho Chi Minh City. Hot sauce Scoville experimentation through direct-to-consumer subscription models captures premium pricing with minimal shelf-access compliance burden. Food service partnerships with ASEAN quick-service operators provide volume validation before retail scaling.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-infrastructure play because EU Green Deal traceability mandates and USDA organic tightening consolidate supplier relationships toward audit-capable platforms. Target fermentation microbiologist talent pools and controlled koji technology assets. Watch sodium reduction mandate acceleration in South Korea and Singapore as reformulation cost inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | EU Green Deal compliance unlocks German and French retail shelf access against additive-dependent competitors. |
| Fermentation Capacity Expansion | Thai industrial park scaling enables standardized export-grade soy and fish sauce output with microbiological consistency. |
| Dual Certification Infrastructure Buildout | Simultaneous USDA organic and FSSAI compliance accelerates product launch velocity across North American and Indian retail. |
| Direct-to-Consumer Platform Launch | Subscription bundling captures Vietnamese e-commerce penetration in secondary cities beyond traditional distribution reach. |
| Hot Sauce Scoville Pipeline Development | Proprietary pepper cultivar relationships enable premium pricing in food service experimentation channels. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FSSAI compliance filings, EU EFSA additive safety assessments, and ASEAN trade customs records, combining fermentation plant manager interviews with retail category buyer discussions and supply chain finance specialist input. Bottom-up volume modeling from Indonesian convenience store distribution data triangulates against top-down value aggregation from Thai industrial park capacity disclosures.
Forecast inputs span product type segmentation across ketchup, soy sauce, and hot sauce; ingredient certification tiers including organic and low-sodium; packaging format economics from sachets to glass bottles; and distribution channel evolution across online retail and food service procurement. CAGRs derive from urbanization-driven switching behavior in Jakarta and Bangkok, sodium reduction mandate compliance cost curves, and fermentation capacity utilization trajectories across the projection horizon.
Practitioners should monitor EU Green Deal packaging mandate implementation timelines and WHO sodium guideline adoption acceleration for early signals of reformulation investment cycles. Forecasts reflect assumptions around ASEAN quick-service expansion continuity and organic soybean supply price stability; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Hot Sauce Powder Market
Condiments & Sauces
Ketchup Market
Condiments & Sauces
Organic Condiments Market
Condiments & Sauces
Dry Cooking Sauces Market
Condiments & Sauces
Egg-Free Mayonnaise Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Cooking Sauces Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Salad Dressings and Mayonnaise Market
Condiments & Sauces
Chocolate Syrup Market
Condiments & Sauces
Low Calorie Peanut Sauce Market
Condiments & Sauces
Sweet and Savory Spread Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
Ketchup Concentrates Market
Condiments & Sauces
Prepared Mustard Market