
 Dips and Spreads Market | 2026-2036
Dips and Spreads Market Size, Share, and Industry Trends Forecast 2026-2036
Dips and Spreads Market Analysis
Food service operators are reorganizing procurement priorities around premium, chef-driven condiment lines. The Kraft Heinz Company anchors its position through massive retail shelf-space control and iconic brand equity. Conagra Brands Inc. competes aggressively in refrigerated dips through continuous flavor innovation. PepsiCo leverages its Frito-Lay snack ecosystem to drive bundled salsa and dip consumption across North American convenience channels.
Dips and spreads encompass semi-solid food preparations formulated from emulsified oils, legumes, vegetables, dairy proteins, or avocado pulp, typically standardized to 40-70% moisture content and pasteurized for ambient or refrigerated distribution. Their primary commercial purpose centers on flavor enhancement for bread, crackers, vegetables, and protein carriers in both retail and food service environments. Hummus and plant-based spreads lead ingredient-driven growth as vegan and flexitarian diets expand across Western Europe and North America. Salsa occupies the largest volume position due to entrenched Mexican and Tex-Mex culinary adoption. Tubs dominate packaging formats for household consumption, though pouches gain traction in single-serve food service and on-the-go retail applications.
FDA nutrition labeling requirements and USDA organic certification standards shape formulation decisions and market access thresholds for domestic manufacturers. EFSA health claims regulations and EU Green Deal agricultural sustainability targets influence import compliance and sourcing transparency for European market entry. Stakeholders must monitor evolving plant-based protein labeling disputes and emerging state-level packaging waste legislation that could fragment distribution strategies.
Market Dynamics
Clean-label reformulation mandates from the FDA are compressing product development cycles while forcing manufacturers to rebuild formulation pipelines around reduced sodium, sugar, and synthetic additive profiles.
Growth Catalysts
- Cloud Kitchen Proliferation:Delivery-native kitchens in Mexico City and São Paulo are expanding condiment SKUs to differentiate virtual brands, driving bulk salsa and hummus procurement.
- EU Green Deal Agricultural Targets:Sustainability-linked sourcing requirements are accelerating certified organic acreage expansion for chickpea and tomato suppliers across Spain and Italy.
- High-Pressure Processing:Cold pasteurization technology is extending refrigerated guacamole shelf life without thermal degradation, unlocking wider retail distribution for perishable formats.
Market Restraints
- Avocado Supply Concentration:Michoacán state in Mexico supplies over three-quarters of US avocado volume, creating weather and cartel-related disruption exposure.
- Olive Oil Price Volatility:Mediterranean drought cycles and harvest variability are compressing margins for hummus and tapenade producers dependent on extra-virgin inputs.
- Refrigerated Freight Cost Structure:Cold-chain distribution requirements for dairy-based and fresh vegetable dips impose 40-60% logistics premiums versus ambient alternatives.
Strategic Opportunities
- Fermentation-Enhanced Profiles:Live-culture processing is creating premium positioning for kimchi-based spreads and fermented salsas in South Korean and US coastal markets.
- Single-Serve Pouch Formats:Flexible packaging innovations are capturing on-the-go consumption occasions previously lost to rigid tub formats in convenience retail.
- Plant-Based Protein Labeling Clarity:Pending FDA guidance on legume-derived protein claims is creating first-mover advantage for chickpea and lentil spread marketers.
Industry Challenges
- Clean-Label R&D Talent Scarcity:Formulation chemists skilled in natural preservation and emulsion stability without synthetic additives command premium compensation and extended recruitment timelines.
- Multi-Jurisdiction Certification Overlap:Simultaneous USDA Organic, Non-GMO Project, and EU organic compliance requires redundant audit streams and documentation systems.
- Legacy Equipment Retrofit Costs:Transitioning thermal processing lines to high-pressure or aseptic cold-fill systems demands capital outlays exceeding mid-tier manufacturer balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dips and Spreads Market |
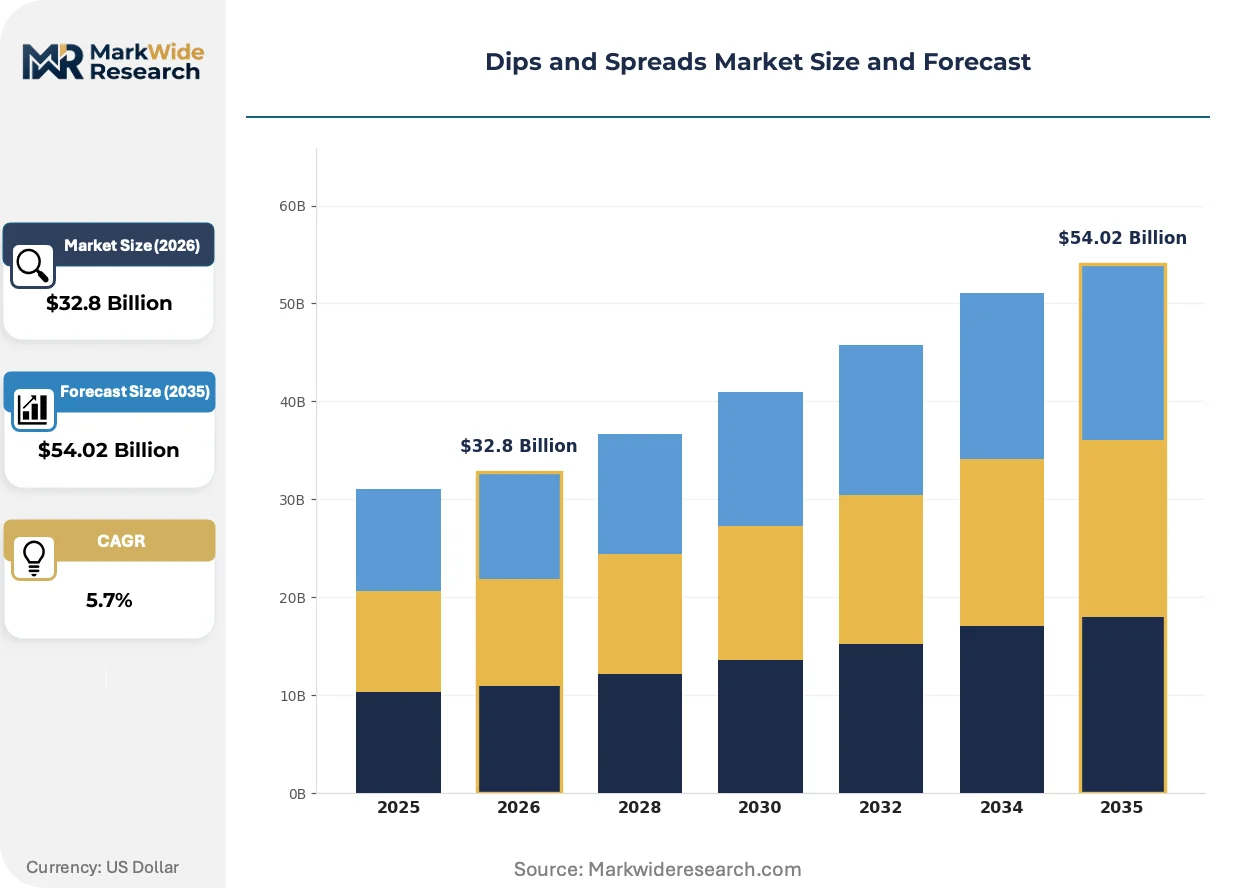
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $54.02 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hummus, Salsa, Guacamole, Ranch Packaging Type: Tubs, Pouches, Jars, Sachets Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service Ingredient Type: Organic, Gluten-Free, Dairy-Based, Plant-Based |
| Companies Covered | Greendot Health Foods Pvt Ltd, Arizona Spice Company LLC, The Kraft Heinz Company, The J.M. Smucker Company, AVT Gavia Foods Pvt. Ltd, PepsiCo, Andros Group, Conagra Brands Inc., Campbell Soup Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dips and Spreads Market Emerging Trajectories
Formulation science and packaging engineering are converging to extend freshness windows while eliminating synthetic preservatives from ingredient decks. This dual pursuit is reshaping competitive advantage around supply chain transparency and processing technology ownership.
High-pressure processing equipment is miniaturizing from industrial-scale 600-liter vessels to 100-liter modular units suitable for regional co-manufacturers. Mid-tier brands in Texas and California are adopting these systems to produce clean-label guacamole without centralized processing dependence. The technology is miniaturizing production economics, enabling distributed manufacturing networks that reduce transport miles for perishable products.
REACH chemical registration requirements and forthcoming microplastic restrictions from ECHA are forcing reformulation of packaging adhesives and barrier coatings used in flexible dip pouches. European importers are demanding full material disclosure certificates from Mexican and Turkish suppliers. Refrigerated salsa exporters to Germany and France are accelerating compliance investments to maintain shelf access ahead of 2026 enforcement windows.
Food service operators are consolidating condiment procurement through broadline distributors rather than direct manufacturer relationships, compressing supplier margins while demanding exclusive flavor development. This concentration shift is displacing regional broker networks that previously managed independent restaurant accounts. The pattern is most pronounced in Florida and Arizona, where multi-unit Tex-Mex chains are centralizing salsa and queso sourcing through Sysco and US Foodservice.
Dips and Spreads Market Segmentation
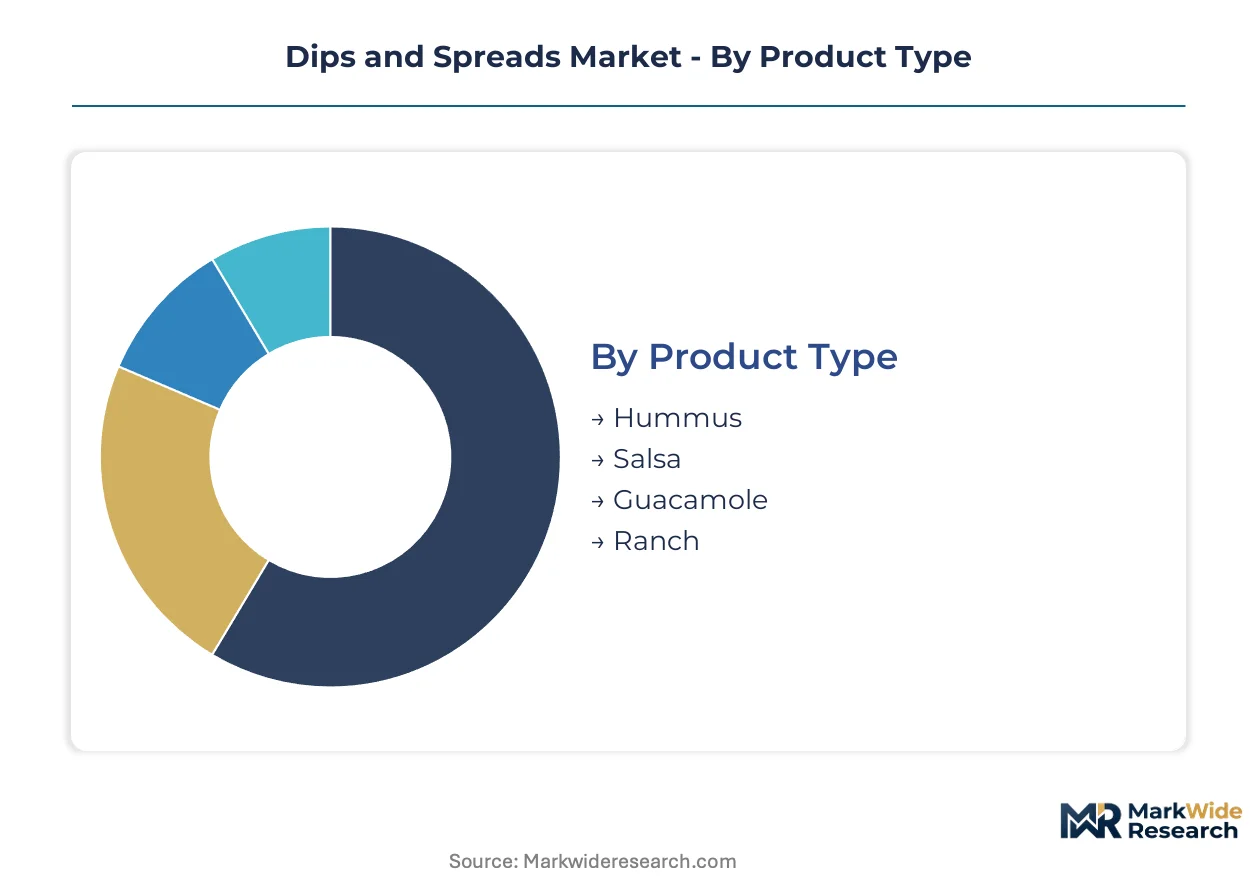
Segmentation reveals where formulation investments and channel resources generate disproportionate returns. Product type and ingredient positioning determine margin structure, while packaging and distribution choices govern access to occasion-based consumption.
Product Type:
Substitution pressure runs strongest against dairy-based formats as plant alternatives capture flexitarian trial and repeat purchase.
- Hummus:Emulsified chickpea-tahini paste with 55-70% moisture content, standardized through thermal or high-pressure processing. Demand concentrates in Germany and the United Kingdom where flexitarian diets drive refrigerated premium SKU expansion. EFSA health claim petitions for protein content are accelerating clean-label reformulation timelines.
- Salsa:Tomato-pepper-chili preparation with pH controlled below 4.6 for ambient stability or refrigerated distribution. Mexico and the southwestern United States anchor volume consumption through entrenched Tex-Mex culinary integration. Michoacán processing clusters supply both domestic retail and export-oriented manufacturing.
- Guacamole:Avocado pulp emulsion with citric acid stabilization and modified atmosphere packaging for refrigerated shelf life extension.
- Ranch:Buttermilk-herb emulsion traditionally dependent on synthetic stabilizers now facing clean-label reformulation mandates from FDA nutritional transparency requirements.
Salsa anchors the volume base while hummus gains share at the steepest rate.
Packaging Type:
Cost tier stratification separates premium convenience formats from economy bulk offerings, with material compliance costs reshaping supplier economics.
- Tubs:Injection-molded polypropylene or polyethylene terephthalate containers with tamper-evident lidding, dominating household multi-serve consumption. Supermarket deli and refrigerated retail sections in the United States and Canada standardize this format for hummus and dairy-based dips. ECHA microplastic restrictions are forcing barrier coating reformulation investments.
- Pouches:Flexible multilayer films with spout or tear-notch dispensing, capturing single-serve food service and convenience retail occasions. Cloud kitchens in São Paulo and Mexico City are accelerating bulk pouch procurement for virtual brand differentiation. REACH chemical registration requirements are elevating material disclosure documentation burdens.
- Jars:Glass containers with metal lug closures, persisting in ambient salsa and specialty import segments.
- Sachets:Small-format flexible packets for portion-controlled food service and airline catering applications.
Tubs maintain the installed base while pouches expand most quickly into delivery-native channels.
Distribution Channel:
Application concentration varies sharply between at-home meal enhancement and away-from-home flavor customization, with procurement centralization altering supplier power dynamics.
- Supermarkets:Full-line retailers controlling refrigerated case space allocation and promotional programming for branded and private-label portfolios. Kroger and Albertsons in the United States are expanding ethnic and specialty dip sets to capture demographic diversification. Shelf-space fees and slotting allowances compress mid-tier manufacturer margins.
- Food Service:Commercial kitchens, quick-service restaurants, and institutional feeders sourcing through broadline distributors. Sysco and US Foodservice are consolidating condiment procurement for multi-unit Tex-Mex chains in Florida and Arizona, displacing regional broker networks. Exclusive flavor development contracts are becoming standard tender requirements.
- Online Retail:E-commerce platforms with cold-chain fulfillment capabilities for refrigerated and frozen formats.
- Convenience Stores:Small-format retailers prioritizing grab-and-go shelf-stable and ambient-refrigerated single-serve options.
Supermarkets anchor the volume base while food service climbs the fastest as procurement centralization accelerates.
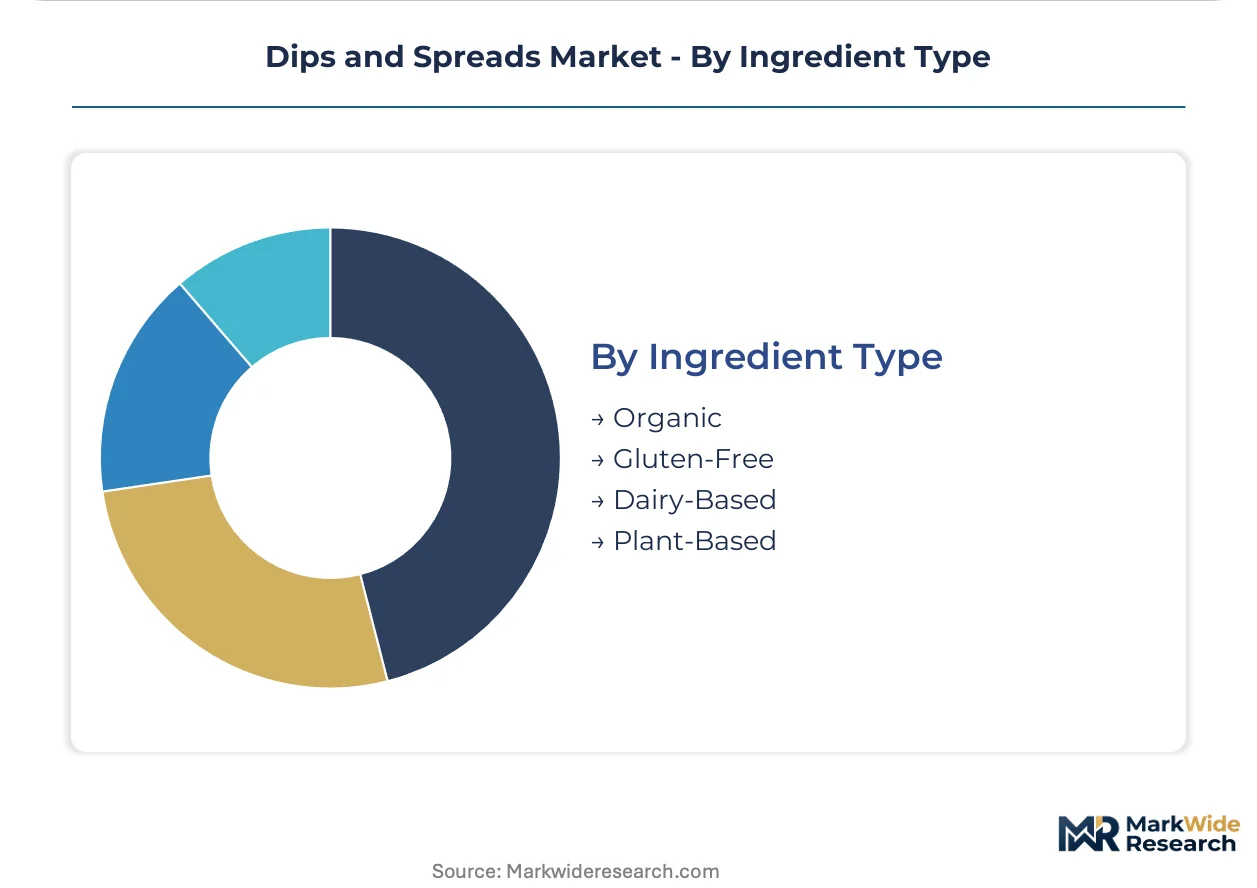
Ingredient Type:
Customer type fragmentation separates health-motivated premium purchasers from price-sensitive mainstream buyers, with certification stacking multiplying compliance overhead.
- Organic:USDA-certified or EU organic-compliant formulations with restricted synthetic input profiles and full traceability documentation. EU Green Deal agricultural sustainability targets are accelerating certified organic acreage expansion for chickpea and tomato suppliers across Spain and Italy. Simultaneous USDA Organic, Non-GMO Project, and EU organic compliance requires redundant audit streams.
- Plant-Based:Legume, vegetable, or nut-derived formulations excluding animal proteins, positioned for vegan and flexitarian dietary adherence. Pending FDA guidance on legume-derived protein claims is creating first-mover advantage for chickpea and lentil spread marketers in North American retail. Clean-label R&D talent scarcity is extending formulation timelines.
- Gluten-Free:Formulations avoiding wheat, barley, and rye inputs, with certified production protocols.
- Dairy-Based:Milk, cream, or cheese-derived preparations facing compressed growth as plant alternatives capture trial.
Organic anchors the volume base among certified segments while plant-based gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Lázaro Cárdenas on Mexico's Pacific coast anchors North American avocado logistics, handling over 80% of Michoacán's export volume to US processing facilities.
United States
Quick-service restaurants in Texas and Florida are expanding salsa and queso SKUs to capture Tex-Mex demand. FDA nutritional transparency mandates are forcing clean-label reformulations of ranch and dairy-based dips. Southern California processing clusters around Los Angeles supply refrigerated hummus and guacamole to West Coast retail chains.
Mexico
Michoacán state supplies over three-quarters of US avocado volume, creating concentrated guacamole production economics. SADER agricultural export certifications govern cross-border shipment protocols for fresh pulp products. Mexico City cloud kitchens are driving bulk salsa procurement for virtual brand differentiation.
Germany
Flexitarian diet expansion in Berlin and Hamburg is accelerating refrigerated hummus SKU proliferation. EFSA health claim petitions for protein content are reshaping formulation timelines. Bavarian chickpea suppliers are expanding certified organic acreage to meet EU Green Deal agricultural targets.
United Kingdom
Retail chains in London and Manchester are broadening ethnic dip sets to capture demographic diversification. ECHA microplastic restrictions are forcing barrier coating reformulation for flexible pouches. Midlands co-manufacturing hubs are adopting high-pressure processing for clean-label guacamole production.
Spain
Tomato and chickpea suppliers in Andalusia and Murcia are scaling certified organic production for EU export compliance. REACH chemical registration requirements are elevating material disclosure burdens for packaging exporters. Barcelona processing facilities are specializing in tapenade and olive-based spreads for Mediterranean markets.
Dips and Spreads Market Vendor Landscape
Concentration sits with diversified food conglomerates controlling retail shelf space and broadline distribution relationships. The vendor base spans three tiers: multinational packaged goods houses with refrigerated logistics networks, mid-tier regional specialists leveraging co-manufacturing flexibility, and emerging plant-based challengers capturing flexitarian trial. Dominant competitive moves include exclusive flavor development contracts with food service distributors and backward integration into high-pressure processing equipment to secure clean-label production capacity.
Among US-based packaged goods houses, The Kraft Heinz Company and Conagra Brands Inc. exemplify scale-driven archetypes with established retail presence, while PepsiCo occupies a position leveraging snack ecosystem bundling. Greendot Health Foods Pvt Ltd and AVT Gavia Foods Pvt. Ltd represent India-based specialists in plant-forward formulations, and Arizona Spice Company LLC anchors the regional seasoning-to-dip vertical within southwestern US markets.
| Leading Market Players |
|---|
| Greendot Health Foods Pvt Ltd |
| Arizona Spice Company LLC |
| The Kraft Heinz Company |
| The J.M. Smucker Company |
| AVT Gavia Foods Pvt. Ltd |
| PepsiCo |
| Andros Group |
| Conagra Brands Inc. |
| Campbell Soup Company |
| Others |
Supply Flow & Price Mechanics
Olive oil substitution for avocado pulp in premium guacamole formulations is simultaneously shifting sourcing geography toward Mediterranean suppliers and compressing margin structures for Michoacán-dependent processors. This input swap exposes manufacturers to EU agricultural volatility while creating pricing arbitrage opportunities between cold-chain perishable and ambient-stable product tiers.
Pricing Analysis
Volume-discount tiering separates national broadline contracts from regional distributor arrangements across food service procurement. Three-tier pricing structure across premium clean-label, standard conventional, and economy private-label levels stratifies buyer access to certification depth and processing technology. Pricing pressure stems from refrigerated freight premiums that impose logistics cost burdens on perishable formats. Quick-service chains exhibit highest price sensitivity due to centralized procurement leverage, while specialty retailers absorb premiums for exclusive flavor development.
Supply Chain Analysis
Just-in-time inventory preference dominates refrigerated guacamole and hummus flows, though strategic stockpiling of ambient salsa concentrates persists among broadline distributors managing Tex-Mex chain demand spikes. Supply concentrates in Mexico for avocado pulp, Spain for tomato and olive inputs, and the United States for chickpea processing. Raw material dependencies include Michoacán avocado harvests, Andalusian olive oil, and High Plains chickpea acreage. Single-source vulnerability runs through Michoacán's three-quarter share of US avocado volume. Distribution runs through Sysco and US Foodservice consolidation for multi-unit food service accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as plant-based spreads capture flexitarian trial from dairy-based formats. Defense requires preemptive clean-label positioning and supply chain control before regulatory mandates accelerate reformulation costs.
For Market Incumbents: Shield core ranch and queso positions through backward integration into high-pressure processing equipment, securing clean-label production capacity ahead of FDA sodium reduction mandates. Anchor shelf-space control via exclusive flavor development contracts with consolidating broadline distributors, neutralizing emerging plant-based challengers before they achieve retail velocity. For New Entrants and Emerging Players: Differentiate on fermentation-enhanced profiles targeting South Korean and US coastal markets where live-culture positioning commands premium placement. Capture white-space in single-serve pouch formats for cloud kitchen procurement, exploiting rigid tub displacement in delivery-native channels. Pursue co-manufacturing partnerships with regional high-pressure processing adopters to bypass capital-intensive equipment barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional salsa specialists holding Michoacán processing infrastructure but lacking clean-label R&D capabilities. Five-to-ten year viability hinges on successful reformulation pipeline execution and certification stacking for EU export access. Monitor FDA guidance finalization on legume-derived protein claims as inflection indicator for plant-based spread valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | Miniaturized 100-liter modular units enable distributed clean-label production without centralized dependence. |
| Exclusive Flavor Development Contracts | Sysco and US Foodservice consolidation demands proprietary SKU creation as tender prerequisite. |
| Certification Stacking Investment | Simultaneous USDA Organic and EU organic compliance opens German and UK retail access. |
| Flexible Pouch Format Expansion | Tear-notch and spout innovations capture on-the-go occasions previously lost to rigid tubs. |
| Backward Integration into Avocado Sourcing | Direct Michoacán orchard relationships mitigate cartel and weather disruption exposure. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA enforcement actions, USDA organic certification databases, and EU Green Deal agricultural implementation reports. Interviews with category buyers at Kroger and Albertsons, procurement directors at Sysco and US Foodservice, and formulation chemists at Conagra and Kraft Heinz provided demand-side and technical validation. Bottom-up SKU-level volume modeling triangulated against top-down retail audit data from Nielsen and Circana.
Segmentation dimensions modeled include product type, packaging format, distribution channel, and ingredient certification tier across the analysis window. CAGRs derived from trend extrapolation of cloud kitchen proliferation rates, clean-label SKU velocity indices, and refrigerated logistics cost trajectories. Forecast inputs incorporated ECHA microplastic restriction compliance timelines and pending FDA protein labeling guidance.
Decision-makers should treat outputs as directional under assumptions of sustained FDA nutritional transparency enforcement and stable Michoacán avocado supply; material deviation would warrant model refresh. Revision becomes warranted when olive oil price volatility or cartel-related disruption crosses thresholds that fundamentally alter input cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
Pasta Sauce Market
Condiments & Sauces
Culinary Sauces Market
Condiments & Sauces
Low Salt Soy Sauce Market
Condiments & Sauces
Hoisin Sauce Market
Condiments & Sauces
Salad Dressings and Mayonnaise Market
Condiments & Sauces
Table Sauce Market
Condiments & Sauces
Low Calorie Peanut Sauce Market
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
Chocolate Syrup Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Tomato Ketchup Market
Condiments & Sauces
Sauce Market