
 Prepared Mustard Market | 2026-2036
Prepared Mustard Market Size, Share, and Industry Trends Forecast 2026-2036
Prepared Mustard Market Analysis
Market Dynamics
Food processors is redrawing procurement volumes as quick-service chains and retail sauce brands reformulate mayonnaise, vinaigrette, and marinade bases with prepared mustard as a functional emulsifier and flavor carrier. The Kraft Heinz Company leverages its vertical integration from mustard seed sourcing through retail bottling to sustain cost discipline across North American grocery channels. McCormick & Company anchors its position through R&D intensity in flavor modulation, supplying foodservice operators with customized heat profiles and viscosity grades. Unilever competes in European retail through Maille's Dijon heritage positioning and controlled distribution through premium supermarket tiers.
Product Landscape
Prepared mustard denotes a condiment manufactured from ground mustard seeds blended with vinegar, water, salt, and functional stabilizers, achieving pH levels typically between 3.2 and 3.8 for shelf stability and microbial safety. The product serves as a flavoring agent, emulsifier, and preservative system across food manufacturing, foodservice, and household consumption. Dijon and yellow mustard segments occupy the largest volume pools in retail, while honey mustard captures expanding demand in quick-service dipping applications. Squeeze tubes and single-serve packets are growing fastest in foodservice and institutional catering channels where portion control and labor efficiency command premium placement.
Regulatory Environment
FDA governs prepared mustard under 21 CFR standards for acidified foods, enforcing thermal processing and pH monitoring requirements that shape manufacturing plant configurations and HACCP protocols. USDA organic certification and Non-GMO Project verification create tiered market access thresholds that filter smaller processors from premium shelf placements. EFSA and national regulators across France, Germany, and the United Kingdom enforce maximum residue limits for mustard seed pesticides and additive restrictions that dictate supplier qualification criteria. Stakeholders must monitor evolving sodium reduction mandates and clean-label enforcement trajectories that will determine which formulations retain retail distribution priority.
Market Dynamics
Clean-label reformulations and sodium reduction mandates are compressing formulation flexibility while concentrating procurement power among vertically integrated processors capable of rapid specification compliance.
Growth Catalysts
- Quick-service sauce reformulation:Chains are substituting prepared mustard for synthetic emulsifiers in mayonnaise and dressing bases, creating volume pull from food manufacturing channels.
- EFSA additive restrictions:Tightening limits on artificial preservatives in European condiments are advantaging mustard's natural antimicrobial pH profile in clean-label positioning.
- Single-serve packaging automation:Advances in aseptic pouch forming are enabling portion-controlled formats for institutional catering and airline foodservice procurement.
Market Restraints
- Mustard seed supply concentration:Canadian and Ukrainian seed origins dominate global supply, exposing processors to weather-driven harvest volatility and trade route disruptions.
- FDA acidified food compliance:21 CFR thermal processing and pH monitoring requirements impose capital-intensive plant configurations that filter smaller entrants from commercial-scale contracts.
- Vinegar price sensitivity:Input costs for distilled white and cider vinegar varieties fluctuate with grain and apple commodity cycles, compressing margin stability in value-tier formulations.
Strategic Opportunities
- Indian foodservice penetration:Quick-service chains and hotel catering in metropolitan Mumbai and Bangalore represent underdeveloped channels for Western-style condiment adoption.
- USDA organic certification tailwind:Federal organic seal requirements are creating shelf-access premiums that reward processors investing in certified seed sourcing and non-synthetic stabilizer R&D.
- E-commerce direct-to-foodservice:Digital procurement platforms are disintermediating traditional broadline distributors, enabling specialized viscosity grades to reach regional restaurant groups.
Industry Challenges
- Flavor chemist scarcity:Formulation expertise in heat-profile modulation and emulsion stability commands premium compensation, constraining mid-tier processor R&D throughput.
- Clean-label certification timelines:Non-GMO Project verification and organic audits require 12-18 month qualification cycles that delay new product launches in fast-moving retail resets.
- Legacy equipment retrofit costs:Transitioning thermal processing lines for reduced-sodium formulations demands stainless steel upgrades and automated pH monitoring integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prepared Mustard Market |
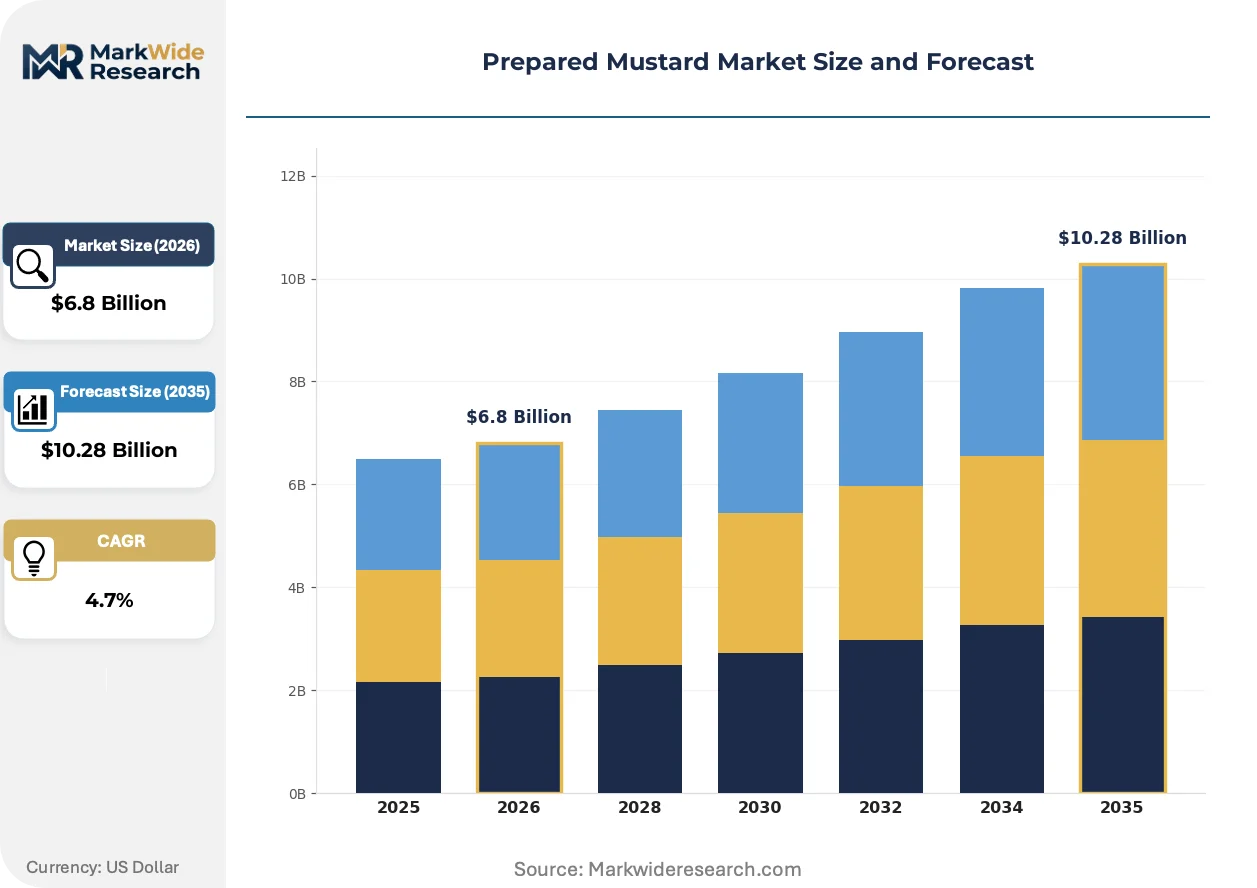
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dijon, Yellow, Spicy Brown, Honey End User: Households, Restaurants, Food Processors, Catering Services Packaging Type: Bottles, Squeeze Tubes, Packets, Jars Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale |
| Companies Covered | The Kraft Heinz Company, Conagra Brands, McCormick & Company, Unilever, French's, Maille, Plochman's, Boar's Head Brand, Woeber Mustard Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prepared Mustard Market Emerging Trajectories
Processing technology and procurement platforms are fragmenting traditional supply relationships while regulatory pressure on ingredient transparency accelerates specification turnover across retail and foodservice channels.
High-pressure processing is fragmenting thermal treatment norms in prepared mustard manufacturing. This non-thermal pasteurization technology preserves volatile allyl isothiocyanate compounds responsible for pungency while achieving FDA-mandated microbial safety thresholds. Mid-size regional processors in Germany and France are adopting HPP systems to supply foodservice operators seeking fresher flavor profiles without synthetic preservative additions.
REACH chemical registration requirements in the European Union are tightening scrutiny on mustard seed pesticide residues and processing aid residuals. EFSA-mandated maximum residue limits now cover 34 additional agrochemicals, forcing seed suppliers to document field application histories through blockchain traceability systems. German retail chains are responding by consolidating procurement to vertically integrated suppliers with captive seed sourcing.
Foodservice operators are consolidating condiment procurement through centralized purchasing cooperatives that negotiate specification-compliant supply contracts across multi-unit restaurant groups. This buyer concentration is compressing supplier margins while rewarding processors offering formulation customization and inventory management integration. The shift is most visible in North American quick-service chains, where procurement teams now specify viscosity ranges and heat profiles by regional menu requirements.
Prepared Mustard Market Segmentation
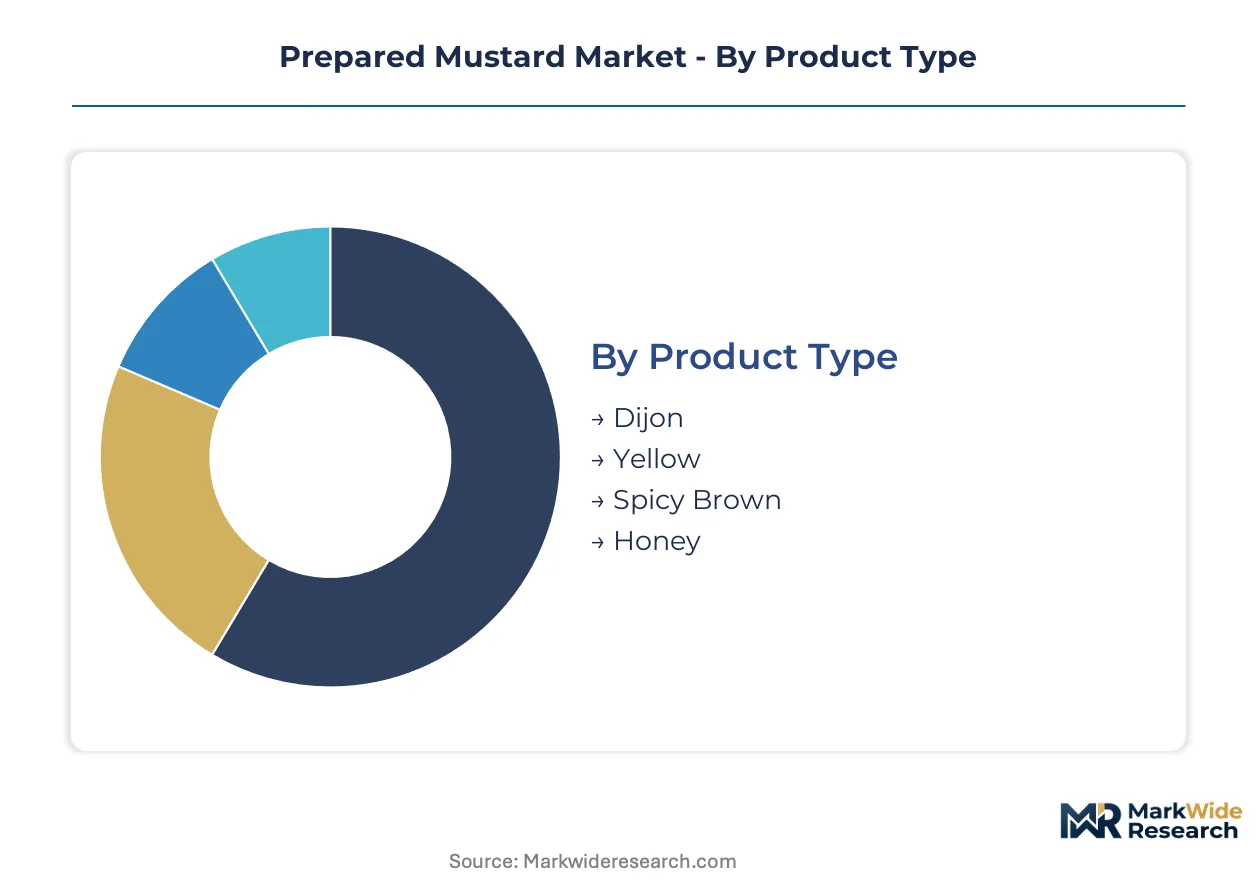
Segmentation in prepared mustard reveals how formulation chemistry, packaging engineering, and channel economics partition margin capture across distinct buyer workflows. Each category maps procurement power to specification complexity in ways that determine supplier qualification barriers.
Product Type:
Margin pools concentrate in emulsion-stable formulations that command premium placement through heritage positioning and functional versatility in food manufacturing.
- Dijon:Finely ground brown mustard seeds blended with white wine or verjuice achieve smooth, pourable consistency at lower viscosity grades. German and French retail channels anchor volume, with Maille and Grey Poupon heritage positioning sustaining shelf-price premiums despite EFSA additive restrictions tightening formulation flexibility.
- Yellow:Turmeric-colored mild mustard from yellow/white mustard seeds dominates North American household penetration through familiar flavor profiles and lower heat thresholds. Quick-service chains specify this grade for mayonnaise and dressing reformulations where emulsification properties replace synthetic stabilizers.
- Spicy Brown:Coarse-ground seeds with higher brown mustard content deliver pronounced heat profiles through retained bran layers. Delicatessen and specialty retail channels in the United States concentrate demand.
- Honey:Sweetened formulations blending mustard paste with honey or honey substitutes target dipping applications in quick-service and family dining segments. Portion-controlled packet formats are expanding fastest in this grade.
Dijon holds installed capacity. Honey is rotating up the share rankings.
End User:
Procurement scale and specification stringency diverge sharply between price-sensitive household volume and contract-negotiated food manufacturing tonnage.
- Households:Retail consumers purchase through supermarket and online channels, with brand loyalty moderating price elasticity. German households demonstrate highest per-capita consumption of Dijon and whole-grain varieties.
- Restaurants:Independent operators and multi-unit chains specify viscosity and heat profiles by menu category, with centralized purchasing cooperatives consolidating supplier relationships in North American quick-service.
- Food Processors:Industrial buyers procure bulk mustard paste for sauce, dressing, and marinade formulations where emulsification and antimicrobial pH properties reduce synthetic additive requirements. FDA acidified food compliance and thermal processing specifications filter supplier qualification.
- Catering Services:Institutional and event catering operators prioritize portion control and labor efficiency, driving single-serve packet and squeeze tube formats with extended ambient stability.
Food processors command specification authority. Catering services are rotating up the share rankings.
Packaging Type:
Unit economics and distribution logistics separate high-volume bottle formats from precision-portioned alternatives that reduce foodservice labor and waste.
- Bottles:Glass and PET containers dominate retail shelf placement, with German and French supermarkets allocating premium facings to heritage Dijon brands in swing-top and traditional bottle designs.
- Squeeze Tubes:Flexible polymer tubes with precision dispensing valves are expanding in foodservice and household channels where controlled portioning and inverted storage convenience command placement.
- Packets:Single-serve foil or film pouches serve institutional catering, airline foodservice, and quick-service drive-through applications. Aseptic forming automation is reducing per-unit cost and enabling customized branding.
- Jars:Wide-mouth glass containers target bulk household purchase and deli-counter service formats, particularly for coarse-ground and whole-grain varieties where spoon-access texture matters.
Bottles hold installed capacity. Packets are climbing the fastest.
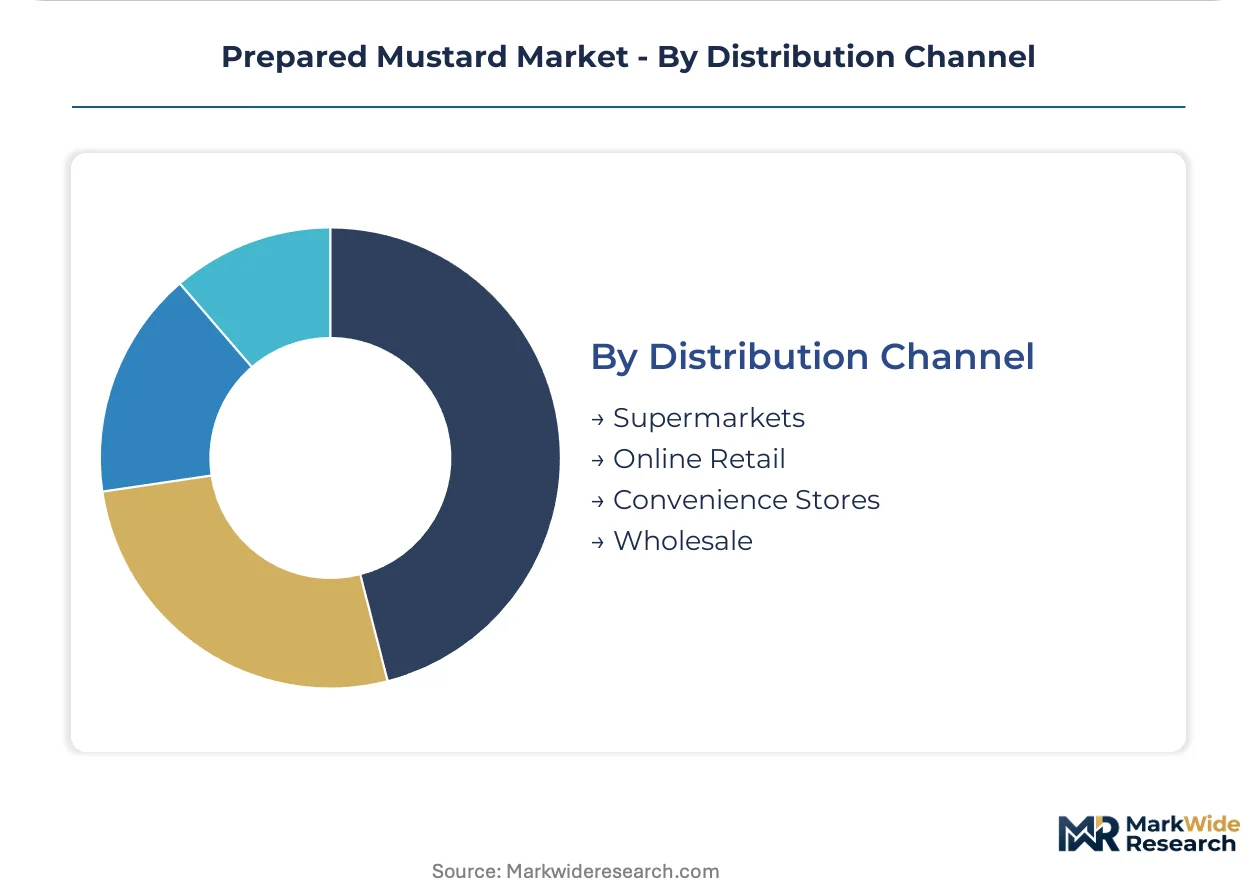
Distribution Channel:
Channel selection determines margin retention, with direct procurement platforms fragmenting traditional broadline distributor relationships in foodservice.
- Supermarkets:Multi-tier retail chains in Germany, France, and the United States control shelf access through category management negotiations, with clean-label and organic certifications gating premium placement.
- Online Retail:E-commerce platforms are enabling direct-to-foodservice procurement for specialized viscosity grades, disintermediating regional distributors and reducing lead times for restaurant group buyers.
- Convenience Stores:Limited-assortment urban and travel-format retailers stock core yellow mustard SKUs in travel-size squeeze tubes, with impulse placement driving incremental household penetration.
- Wholesale:Broadline foodservice distributors consolidate procurement for multi-unit restaurant operators, with contract specifications covering heat profiles, pH stability, and inventory management integration.
Supermarkets hold installed capacity. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors German mustard seed imports from Canada and Ukraine, while Rotterdam's container terminals distribute formulated products across Northwest Europe's retail networks.
United States
Quick-service chains in Chicago and Dallas drive bulk procurement for sauce reformulations. FDA acidified food compliance under 21 CFR shapes plant configurations in Midwest processing clusters. Pittsburgh and Cleveland house legacy mustard manufacturing facilities upgrading thermal processing lines for reduced-sodium formulations.
Germany
Dijon and whole-grain varieties anchor premium household consumption in Bavaria and Baden-Württemberg. EFSA pesticide residue limits and REACH chemical registration requirements filter supplier qualification. Düsseldorf and Cologne concentrate foodservice distribution infrastructure serving the Rhine-Ruhr metropolitan corridor.
France
Heritage Dijon production concentrates in Burgundy, with Maille maintaining controlled distribution through Parisian premium retail tiers. ANSM enforces additive restrictions that tighten formulation specifications. Lyon and Marseille serve as export logistics hubs for North African and Middle Eastern condiment markets.
Canada
Saskatchewan and Alberta prairie provinces dominate global mustard seed supply, exposing processors to weather-driven harvest volatility. Canadian Food Inspection Agency enforces maximum residue limits that shape field application protocols. Winnipeg houses primary seed cleaning and export terminal infrastructure.
India
Metropolitan Mumbai and Bangalore represent underdeveloped channels for Western-style condiment adoption in quick-service and hotel catering. FSSAI governs packaged condiment standards that create compliance thresholds for imported formulations. Gujarat's spice processing clusters supply domestic mustard powder for regional curry preparations.
Prepared Mustard Market Vendor Landscape
Concentration sits with vertically integrated food conglomerates and heritage European specialists. The vendor base spans three tiers: multinational packaged goods corporations with captive seed sourcing, regional specialists leveraging terroir positioning, and private-label manufacturers serving price-sensitive retail channels. Dominant competitive moves include backward integration into mustard seed procurement and portfolio diversification into adjacent condiment categories.
Among North American packaged goods conglomerates, The Kraft Heinz Company and Conagra Brands exemplify scale-driven archetypes with integrated supply chains from agricultural inputs through retail distribution. McCormick & Company occupies a position within the flavor-specialist tier, while Unilever and Maille represent European heritage positioning anchored by controlled premium-channel access. These five entities collectively illustrate how procurement power, regulatory compliance capability, and brand equity interact to determine shelf placement outcomes across divergent retail environments.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Conagra Brands |
| McCormick & Company |
| Unilever |
| French's |
| Maille |
| Plochman's |
| Boar's Head Brand |
| Woeber Mustard Manufacturing Company |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Canadian seed crushing facilities shapes both upstream procurement power and downstream price floors for formulated mustard products. Scale economies in Saskatchewan cleaning and export terminals concentrate volume premiums among processors with multi-year offtake agreements, while smaller regional bottlers absorb spot-market volatility in vinegar and packaging inputs.
Pricing Analysis
Volume-discount tiering structures stratify across premium heritage Dijon, standard yellow mustard, and economy private-label tiers. Price differentiation rests on organic certification grade and brand heritage positioning, with USDA organic seal commanding shelf-access premiums. Cost compression in economy tiers is intensifying because of vinegar commodity cycle exposure. Quick-service chains demonstrate lowest price sensitivity due to specification-locked contracts, while independent retailers face highest elasticity.
Supply Chain Analysis
The Port of Hamburg transit corridor underwrites European formulation supply security for Canadian and Ukrainian seed origins. Raw material dependencies center on brown and yellow mustard seed varieties, distilled white vinegar, and glass packaging substrates. Single-source vulnerability concentrates in Saskatchewan-Alberta prairie harvests exposed to drought-driven yield volatility. Distribution runs through Rotterdam container terminals for Northwest European retail networks and Chicago rail hubs for North American foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prepared mustard sits in early-cycle expansion as quick-service sauce reformulation accelerates Western condiment adoption in Indian metropolitan foodservice channels.
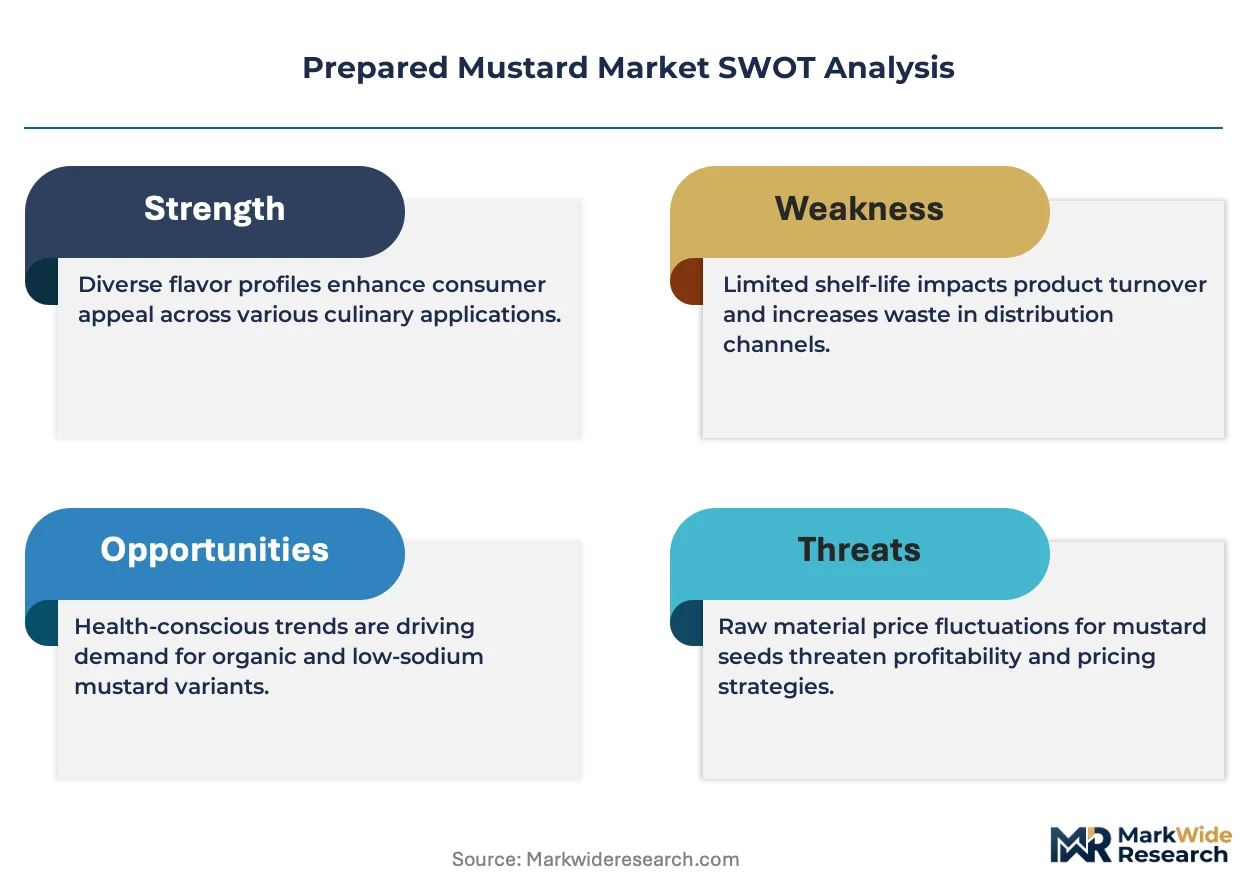
For Market Incumbents: Consolidate backward integration into certified organic seed sourcing to preempt USDA compliance bottlenecks. Lock in multi-year vinegar supply agreements to hedge commodity volatility. Prioritize thermal processing line upgrades for reduced-sodium formulation flexibility before FDA enforcement timelines tighten. For New Entrants and Emerging Players: Lead with clean-label honey mustard formulations targeting Mumbai and Bangalore hotel catering channels where Western condiment penetration remains underdeveloped. Deploy direct-to-foodservice digital procurement platforms to bypass entrenched broadline distributor relationships. Emphasize single-serve packet automation for airline and institutional catering procurement. For Investors and Strategic Acquirers: Regional specialists with captive seed sourcing and EFSA-compliant processing infrastructure represent the most defensible acquisition targets in a consolidating European landscape. Monitor FSSAI packaged condiment standard evolution as the inflection signal for Indian market entry viability. Five-to-ten year positioning hinges on clean-label certification capability rather than volume scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Seed Sourcing | Captive supply of certified mustard seed secures USDA organic shelf placement premiums against non-compliant competitors. |
| Thermal Processing Line Modernization | Automated pH monitoring integration enables reduced-sodium formulation compliance with evolving FDA 21 CFR standards. |
| Single-Serve Packet Automation Investment | Aseptic pouch forming technology captures foodservice procurement shifts toward portion-controlled institutional catering formats. |
| Direct-to-Foodservice Digital Platform Launch | E-commerce procurement disintermediation reaches regional restaurant groups with specialized viscosity grades and shorter lead times. |
| High-Pressure Processing System Adoption | Non-thermal pasteurization preserves allyl isothiocyanate pungency compounds for premium clean-label positioning in German and French markets. |
Methodological Framework
A spread of perspectives from mustard seed procurement managers, condiment formulation chemists, quick-service chain purchasing directors, and retail category buyers converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA 21 CFR filings, EFSA additive restriction databases, USDA organic certification registries, and Canadian grain export statistics. Bottom-up volume modeling triangulated against top-down category expenditure estimates.
Segmentation dimensions modeled include product type chemistry, packaging format engineering, end-user procurement scale, and distribution channel economics across the projection horizon. CAGRs derived from trend extrapolation of seed harvest volumes, vinegar commodity input cycles, and quick-service reformulation adoption curves. Industry-specific forecast inputs incorporated EFSA maximum residue limit enforcement trajectories and FSSAI packaged condiment standard development timelines.
Forecasts assume regulatory continuity in FDA acidified food standards and EFSA REACH chemical registration regimes; material policy shifts would require re-modeling of plant configuration investments and supplier qualification barriers. Practitioners should keep alternative scenarios live as Indian FSSAI enforcement intensity and Ukrainian seed export route stability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Fat Free Salad Dressings Market
Condiments & Sauces
Ketchup Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Table Sauce Market
Condiments & Sauces
Gluten-Free Soups and Sauces Market
Condiments & Sauces
Organic Condiments Market
Condiments & Sauces
Vegan Pasta Sauce Market
Condiments & Sauces
Low Fat Spaghetti Sauce Market
Condiments & Sauces
Mayonnaise Market
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Vinegar and Vinaigrette Market
Condiments & Sauces
Sauces and Condiments Market
Condiments & Sauces
Dipping Sauces Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Sandwich Spread Market