
 Sour Dressings Market | 2026-2036
Sour Dressings Market Size, Share, and Industry Trends Forecast 2026-2036
Sour Dressings Market Analytics
Food service distribution is tilting toward direct-to-operator models as operators seek fresher formats and shorter lead times. T. Marzetti Company leverages its refrigerated logistics network to sustain national penetration in food service channels. Ken's Foods anchors its position through manufacturing scale across multiple production facilities. Jimmy's Salad Dressings & Dips competes in regional markets with specialized flavor profiles targeting independent restaurants.
Sour dressings comprise acidulated condiment systems—typically pH 3.0–4.2—formulated with acetic, citric, or lactic acid bases combined with emulsified oils, stabilizers, and flavoring compounds; they function as taste-modifying agents that deliver microbial stability and organoleptic brightness across cold and hot applications. Fermented variants command premium positioning due to live-culture labeling claims and extended shelf stability without chemical preservatives. Citrus-Based formulations are gaining velocity in marinades and sauces as clean-label demand reshapes ingredient declarations across retail and food service segments.
FDA oversight of acidified food regulations and USDA grading standards for vinegar-derived ingredients shape formulation compliance and label claim substantiation throughout the United States. State-level cottage food laws and interstate commerce rules create patchwork compliance requirements for small-batch producers shipping across state lines. Stakeholders must monitor evolving FDA guidance on fermented product identity standards while evaluating backward integration into vinegar production to secure supply and margin control.
Market Dynamics
Fermentation process control technology is compressing batch-to-batch variability while FDA's updated acidified food regulations force reformulation investments across the sour dressings category.
Growth Catalysts
- Clean-label fermentation:Live-culture positioning commands shelf space as consumers reject chemical preservatives. Probiotic labeling claims differentiate premium SKUs in refrigerated sections.
- Restaurant chain expansion:Sour dressings penetrate marinades, sandwich spreads, and bowl concepts beyond traditional salad applications. Chains specify pH-stable formulations for hot-hold operations.
- USDA vinegar grading standards:Standardized acidity benchmarks enable supplier qualification at scale. Large manufacturers backward integrate into vinegar production to secure margin control.
Market Restraints
- Input cost volatility:Specialty oil and citrus concentrate prices fluctuate with climate-driven harvest variability. Formulators hedge through multi-year supply contracts.
- Supply concentration risk:Domestic vinegar production clusters in the Midwest and California. Disruption at major acetic acid facilities cascades through downstream dressing manufacturers.
- Technical limitation:Live-culture stability degrades above 40°F during distribution. Cold chain requirements constrain food service penetration in ambient-logistics channels.
Strategic Opportunities
- Underpenetrated food service segments:K-12 and healthcare cafeterias represent untapped volume for portion-controlled sour dressing formats. Operators seek cost-neutral flavor enhancement.
- Regulatory tailwind:FDA's pending fermented product identity standards will clarify live-culture labeling thresholds. First movers securing GRAS determinations gain competitive insulation.
- Technology convergence:High-pressure processing combined with modified atmosphere packaging extends refrigerated shelf life without thermal degradation. Co-packers invest in HPP lines to capture clean-label contracts.
Industry Challenges
- Food safety certification timelines:SQF and BRC audits for acidified food facilities extend 8-14 months. Startups face working capital strain during pre-revenue compliance phases.
- Talent scarcity in fermentation science:Industrial microbiologists command premium compensation. Regional producers struggle to staff R&D functions outside established food science clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sour Dressings Market |
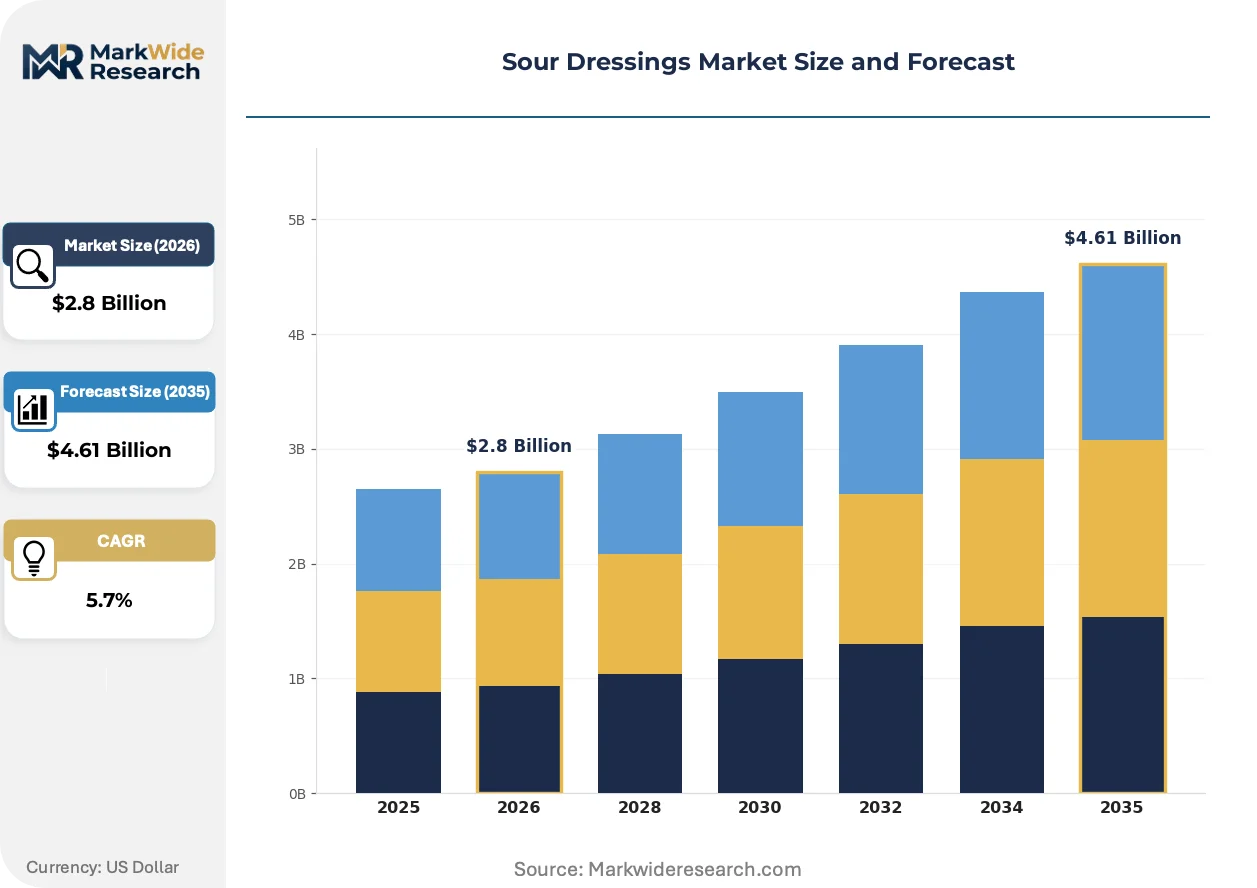
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinegars, Mustards, Citrus-Based, Fermented Application: Salad Preparations, Marinades, Sauces, Dips Distribution Channel: Supermarkets, Online Retailers, Food Service, Specialty Stores End User: Households, Restaurants, Catering Services, Food Manufacturers |
| Companies Covered | T. Marzetti Company, Jimmy's Salad Dressings & Dips, Pinnacle Foods, Old Dutch, Troyer Cheese, Hartville, AVEBE, Ken's Foods, Briannas Fine Salad Dressings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sour Dressings Market Evolving Landscape
Real-time pH monitoring and automated acidification systems are transforming how sour dressings achieve microbial stability. Three developments are compressing competitive timelines.
Inline refractometry and digital titration equipment is digitizing quality control at commercial dressing facilities. Mid-scale producers adopt these systems to reduce laboratory staffing while accelerating batch release. The technology compresses time-to-market for seasonal flavor launches by eliminating off-line testing bottlenecks.
FDA's updated labeling requirements for fermented food products are mandating live-culture count disclosures on acidified dressings. Manufacturers reformulate starter cultures to meet threshold claims while maintaining shelf stability. Refrigerated retail SKUs face the steepest compliance costs as ambient-stable competitors exploit regulatory lag.
Direct-to-operator distribution is displacing broadline food service intermediaries for fresh-format sour dressings. Independent restaurants and regional chains specify shorter lead times and customized viscosity profiles. This channel shift concentrates in metropolitan markets with refrigerated last-mile infrastructure density.
Sour Dressings Market Segmentation
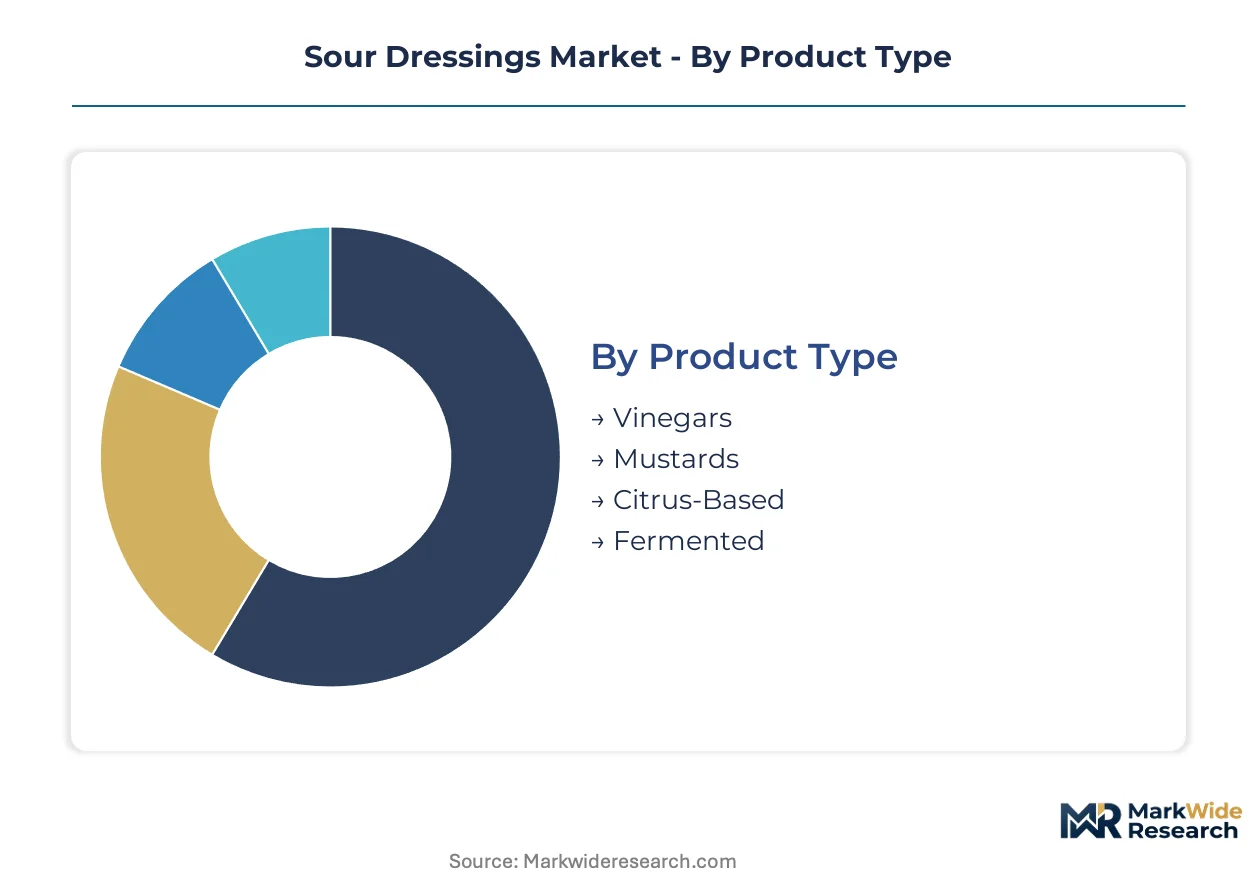
Sour dressing manufacturers calibrate formulation and packaging specifications against distinct usage contexts and procurement patterns. Each segment imposes unique pH stability, viscosity, and cold-chain requirements that reshape production economics and channel strategy.
Product Type:
Mature acidulated platforms dominate refrigerated retail while emerging fermentation technologies command premium positioning through live-culture differentiation.
- Vinegars:Acetic acid-based formulations at 4-7% acidity provide foundational microbial inhibition across ambient and refrigerated SKUs. Restaurant chains in the United States specify standardized acidity grades for hot-hold operations. This segment handles the majority of throughput; Fermented is the fastest mover on share.
- Mustards:Emulsified seed-paste systems combine allyl isothiocyanate heat with acetic acid tang for sandwich and protein applications. Independent delis and quick-service operators drive volume in metropolitan food service corridors.
- Citrus-Based:Citric and malic acid platforms from lemon, lime, and yuzu concentrates deliver clean-label brightness without synthetic acidulants. Clean-label mandates from California and Florida retail chains accelerate reformulation.
- Fermented:Lactobacillus-cultured dressings with live-cell counts above 10^8 CFU/g exploit probiotic labeling claims. FDA's pending fermented product identity standards will clarify threshold compliance for premium refrigerated placement.
Vinegar-based formulations anchor volume economics; fermentation processes capture the steepest expansion trajectory as live-culture claims reshape refrigerated shelf competition.
Application:
Volume concentrates in cold-pour categories while thermal-stable applications command formulation premiums.
- Salad Preparations:Traditional leaf-dressing applications specify pourable viscosity at refrigerated temperatures. Food service distributors push portion-control pouches to reduce waste in high-volume operations.
- Marinades:Acidulated protein tenderization systems require pH stability across extended contact times. Citrus-Based variants are gaining velocity in poultry and seafood processing lines seeking clean-label ingredient declarations.
- Sauces:Hot-hold compatible sour dressings demand modified starch and gum systems to prevent phase separation above 140°F. Chain restaurants specify these for bowl concepts and protein toppings.
- Dips:Thickened emulsions with elevated oil content target snack and appetizer occasions. Convenience retailers in Texas and New York metropolitan areas stock multi-pack formats for household penetration.
Salad applications maintain the broadest installed base; marinade applications are expanding most quickly as protein processors reformulate toward acidulated clean-label systems.
Distribution Channel:
Channel selection determines packaging format, shelf-life engineering, and margin structure.
- Supermarkets:National retail chains demand 90-120 day refrigerated shelf life with front-facing label compliance. Slotting fees concentrate volume among manufacturers with multi-regional distribution infrastructure.
- Online Retailers:Direct-to-consumer shipment requires insulated packaging and gel-pack cold-chain compliance. Subscription models for artisanal fermentation brands build recurring revenue in coastal urban markets.
- Food Service:Direct-to-operator and broadline distribution serve distinct operator tiers with gallon, pouch, and portion-control formats. T. Marzetti's refrigerated logistics network sustains national penetration against regional competitors.
- Specialty Stores:Independent grocers and natural food retailers stock small-batch and regional fermentation brands. These channels tolerate shorter shelf life and higher price points for provenance claims.
Food service channels move the largest absolute volume; online retail is climbing the fastest as cold-chain packaging innovations reduce shipping breakage.
End User:
Procurement scale and specification authority separate household from institutional demand patterns.
- Households:Retail consumers select 12-16 oz bottles based on label claims and flavor familiarity. Clean-label fermentation positioning commands price premiums in affluent suburban markets.
- Restaurants:Independent and chain operators specify viscosity, acidity, and packaging format against menu engineering requirements. Direct procurement relationships compress distributor margins for high-volume accounts.
- Catering Services:Event and institutional caterers demand bulk formats with extended ambient stability for off-site service. Portion-control packaging reduces labor cost in high-volume banquet operations.
- Food Manufacturers:Industrial buyers incorporate sour dressings as ingredient inputs for frozen meals, shelf-stable salads, and co-manufactured retail products. pH documentation and lot traceability dominate supplier qualification.
Restaurant procurement generates the highest transaction frequency; food manufacturer integration is gaining share fastest as ready-meal processors outsource sauce development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA acidified food regulations anchor formulation standards in the United States, the dominant geography for sour dressing consumption and manufacturing investment.
United States
Craft and artisanal dressing producers are gaining shelf space in specialty retail channels across California and New York metropolitan markets. FDA's updated labeling requirements for fermented food products mandate live-culture count disclosures that reshape refrigerated SKU compliance costs. Chicago and Los Angeles food service corridors concentrate direct-to-operator distribution infrastructure for fresh-format sour dressings.
Germany
Industrial food manufacturers in Bavaria and North Rhine-Westphalia integrate sour dressings as ingredient inputs for ready-meal and frozen salad production. EFSA guidance on fermented food health claims influences live-culture labeling thresholds for export-oriented producers. The Emsland region hosts specialized starch and gum suppliers supporting hot-hold compatible dressing formulations.
France
Artisanal mustard and vinegar traditions in Dijon and Orléans supply acidulated base ingredients for premium dressing lines. ANSM oversight of food supplement classifications affects probiotic-positioned fermented dressings crossing into functional food territory. Île-de-France retail chains drive clean-label reformulation mandates that cascade through supplier networks.
Japan
Convenience store operators in Tokyo and Osaka specify portion-controlled sour dressing formats for bento and salad categories. METI standards on food additive usage constrain synthetic acidulant deployment in favor of citrus-derived alternatives. The Kansai industrial corridor concentrates fermentation technology suppliers serving domestic dressing manufacturers.
Australia
Food service distributors in Sydney and Melbourne are expanding sour dressing applications into bowl concepts and protein marinades. TGA guidance on live-culture therapeutic claims creates compliance boundaries for probiotic-positioned products. Victoria's dairy and fermentation processing clusters supply cultured base ingredients for regional dressing production.
Sour Dressings Market Competitive Landscape
Scale-driven manufacturers and regional specialists split the market into distinct competitive tiers with divergent channel strategies. Refrigerated logistics capabilities and vinegar supply security separate national penetrators from metropolitan-focused operators. Two archetypes dominate: multi-facility producers leveraging manufacturing scale, and regional craft formulators exploiting flavor specialization. Backward integration into vinegar production and direct-to-operator distribution partnerships constitute the primary competitive moves reshaping market structure.
Within the scale-driven tier, T. Marzetti Company and Ken's Foods occupy positions defined by refrigerated distribution infrastructure and multi-regional manufacturing footprints. Jimmy's Salad Dressings & Dips exemplifies the regional specialist archetype, competing through specialized flavor profiles targeting independent restaurants in defined geographic markets. These three companies represent the competitive spectrum from national penetration to metropolitan concentration.
| Leading Market Players |
|---|
| T. Marzetti Company |
| Jimmy's Salad Dressings & Dips |
| Pinnacle Foods |
| Old Dutch |
| Troyer Cheese |
| Hartville |
| AVEBE |
| Ken's Foods |
| Briannas Fine Salad Dressings |
| Others |
Value Network & Pricing Analysis
Undercapacity in domestic vinegar production across the Midwest and California drives supplier consolidation and pricing leverage for acetic acid feedstock. Large manufacturers exploit tight capacity to secure multi-year supply contracts while regional dressing producers absorb spot-market volatility.
Pricing Analysis
Geographic price spreads between coastal metropolitan markets and inland production corridors reflect refrigerated logistics cost differentials. Three-tier pricing structure across premium fermentation, standard acidulated, and economy vinegar-based tiers separates live-culture certification grades. Pricing pressure stems from citrus concentrate harvest variability compressing margins on clean-label formulations. Food service distributors exhibit highest price sensitivity due to volume procurement scale; specialty retailers tolerate premium positioning for provenance claims.
Supply Chain Analysis
Export-control regimes on fermentation process technology from Germany and Japan constrain domestic producers' access to advanced batch-control systems. Acetic acid supply concentrates in the United States domestic production clusters; specialty oils draw from Mediterranean and Argentine sources; citrus concentrates rest on Florida and California harvest cycles. Single-source vulnerability pervades domestic vinegar production corridors. Distribution runs through refrigerated food service networks and broadline intermediaries serving distinct operator tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-operator service models and subscription-based artisanal delivery represent recurring-revenue layers expanding faster than base product throughput. These attach opportunities reshape margin architecture beyond transactional gallon sales.
For Market Incumbents: Pre-empt craft producer encroachment by securing exclusive direct-to-operator partnerships in Chicago and Los Angeles food service corridors. Backward integration into vinegar production neutralizes feedstock cost volatility threatening margin compression. Cold chain infrastructure investments defend national penetration against regional specialists.
For New Entrants and Emerging Players: K-12 and healthcare cafeteria segments represent the most penetrable entry point for portion-controlled clean-label formats. Independent restaurants in secondary metropolitan markets offer lower competitive density than coastal corridors. Subscription models for fermented artisanal SKUs build recurring revenue without broadline distributor dependence.
For Investors and Strategic Acquirers: Capital is best deployed toward regional fermentation specialists with established live-culture certification and refrigerated last-mile infrastructure. Five-to-ten year viability hinges on FDA fermented product identity standard compliance positioning. Monitor GRAS determination timelines as inflection signals for competitive insulation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vinegar Production | Captive acetic acid supply secures margin control against Midwest production concentration risk. |
| Direct-to-Operator Distribution Expansion | Refrigerated logistics partnerships in metropolitan corridors displace broadline intermediaries. |
| Live-Culture Certification Investment | FDA GRAS determinations for fermented SKUs create regulatory moats in refrigerated retail. |
| High-Pressure Processing Line Deployment | HPP technology adoption extends clean-label shelf life without thermal culture degradation. |
| Specialty Oil Supply Contracting | Multi-year Mediterranean and Argentine sourcing agreements hedge climate-driven harvest volatility. |
Research Methodology
The analysis maps vinegar-based, fermented, citrus-based, and mustard dressing sub-sectors, each validated through plant managers at acidified food facilities, procurement leads at restaurant chains, distribution channel partners, and fermentation R&D directors. Primary interviews combined with secondary validation from FDA acidified food filings, USDA vinegar grading standards, customs trade data on specialty oil imports, and SEC 10-K disclosures from listed manufacturers. Bottom-up volume triangulation against top-down category expenditure estimates anchored forecast calibration.
Assumption sets held FDA regulatory timelines and climate-driven citrus harvest patterns fixed while varying food service channel penetration rates and clean-label adoption curves across the projection horizon. Segmentation dimensions modeled include product type, application context, distribution channel, and end-user procurement scale. CAGRs derived from historical trajectory analysis applied to segment-specific volume elasticities, with fermentation technology diffusion curves and refrigerated logistics capacity expansion as key industry-specific inputs.
Stress conditions across acetic acid supply disruption severity, live-culture stability degradation thresholds, and cold-chain cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory guidance timing and specialty crop yield volatility. Material shifts in FDA fermented product identity standard implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Vegan Sauces Market
Condiments & Sauces
Gluten-Free Soups and Sauces Market
Condiments & Sauces
Dry Cooking Sauces Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Barbecue Sauce Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
Global Fish Sauce Market
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Sauce Making Machine Market
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
Global Hot Pot Condiment Market
Condiments & Sauces
North America Mayonnaise Market