
 Pasta Sauce Market | 2026-2036
Pasta Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Pasta Sauce Market Intelligence
Volatile tomato harvests in key agricultural regions like Italy and Spain is repositioning the supply chain for major sauce producers. Barilla G. e R. Fratelli S.p.A leverages its Italian heritage and integrated supply networks to manage ingredient quality. The Kraft Heinz Company competes on brand recognition and extensive distribution across North American supermarkets. Campbell Soup Company differentiates through its Prego brand by focusing on family-friendly flavor profiles.
Pasta sauce is a prepared culinary liquid or semi-solid, primarily based on tomatoes, cream, or oil. Formulations are controlled for specific Brix levels to ensure consistency and a pH below 4.6 for shelf stability without refrigeration before opening. Tomato-based varieties like Marinara constitute the largest product type segment by volume. In packaging, while glass jars maintain a dominant market position, flexible pouches are gaining traction in retail channels due to their convenience and lighter weight.
Food safety and labeling standards from regulators like the US FDA and the European Food Safety Authority (EFSA) dictate permissible ingredients and health claims. Compliance with global food safety management systems, such as ISO 22000, is critical for market access in many countries. Navigating the divergence between consumer demand for clean-label, organic ingredients and the cost pressures from agricultural commodity volatility will define future competitive success.
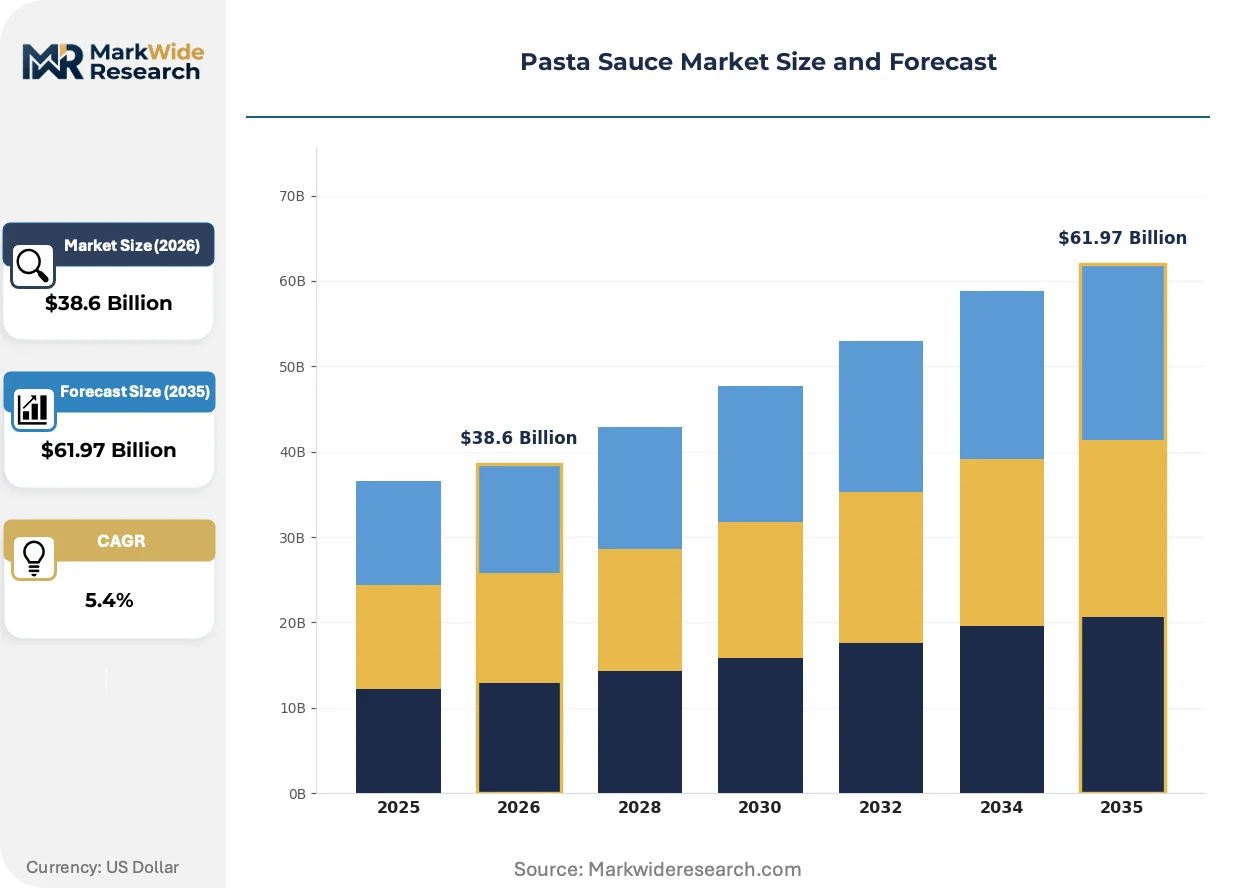
Market Dynamics
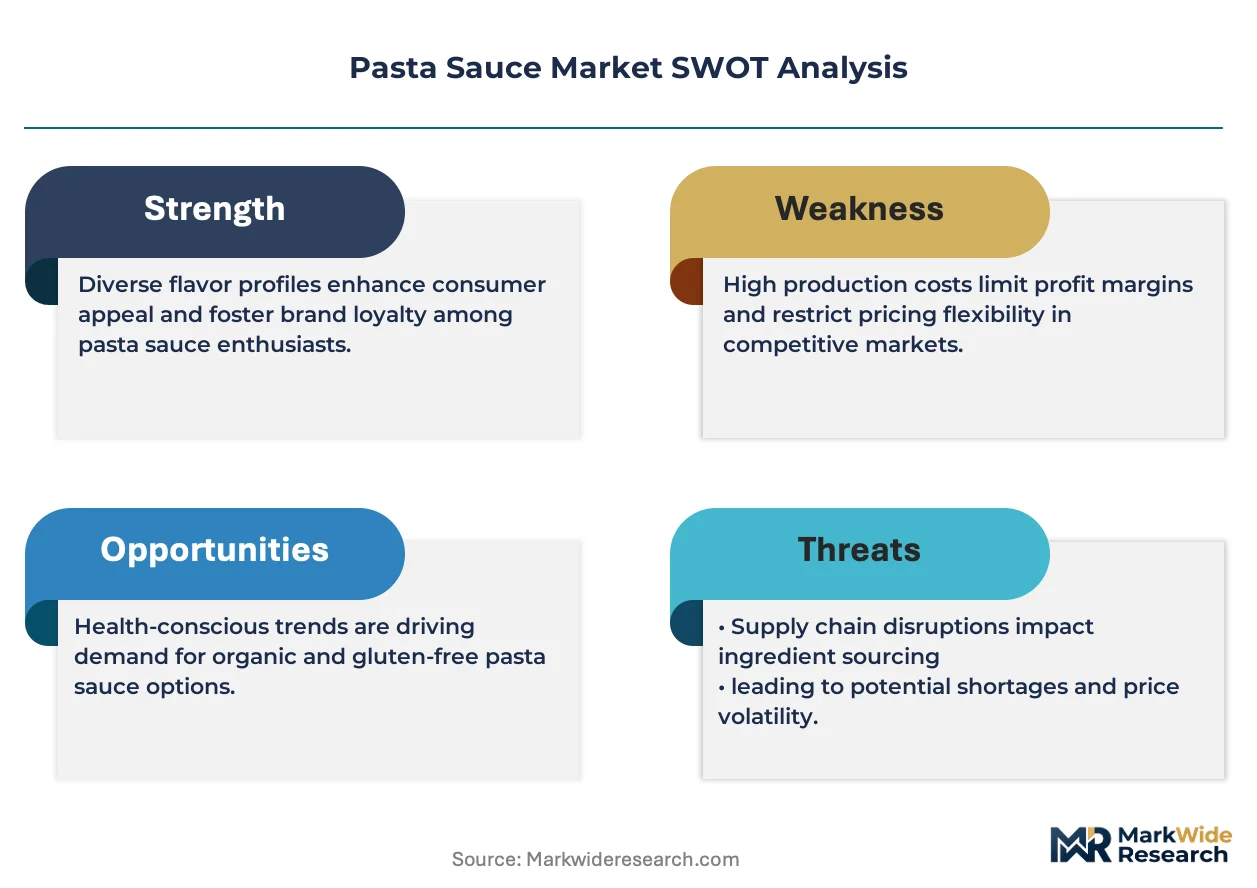
The divergence between consumer demand for clean-label, organic ingredients and the cost pressures from agricultural commodity volatility defines the central tension in the pasta sauce market, influencing formulation, pricing, and supply chain strategies.
Growth Catalysts
- Convenient Meal Solutions:
Demand from time-constrained households for quick meal preparation sustains volume for ready-to-use sauces, reducing cooking complexity.
- Clean-Label Formulations:
High-Pressure Processing (HPP) technology enables preservative-free products, meeting consumer preference for simple ingredient lists in North America and Europe.
- Global Cuisine Trends:
Consumer interest in authentic Italian recipes opens markets for specialty sauces beyond marinara, particularly in developed Asian economies.
Market Restraints
- Agricultural Volatility:
Unpredictable tomato harvests in Italy and Spain due to adverse weather create price instability and supply disruptions for manufacturers.
- Packaging Costs:
The dominance of heavy glass jars increases transportation costs and breakage rates, posing a logistical and financial challenge.
- Substitution Threat:
Private-label alternatives and the practice of home cooking from scratch present constant competitive pressure on branded product sales.
Strategic Opportunities
- Emerging Geographies:
The rising popularity of Italian cuisine in urban centers of China and India presents a growth opportunity for pasta sauce brands.
- Functional Ingredients:
Incorporating plant-based proteins or vegetable purees into sauces can attract health-conscious consumers seeking added nutritional benefits.
- Channel Expansion:
Direct-to-consumer (DTC) models and meal kit partnerships offer a new route to market, bypassing traditional retail channel constraints.
Industry Challenges
- Regulatory Complexity:
Navigating divergent food safety and labeling standards from the US FDA and European Food Safety Authority (EFSA) increases compliance costs for global exporters.
- Quality Consistency:
Maintaining consistent product quality, including specific Brix levels and pH, despite variations in perishable agricultural inputs requires significant operational control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pasta Sauce Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $61.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Marinara, Alfredo, Pesto, Arrabbiata Packaging Type: Glass Jar, Plastic Bottle, Pouch, Can End User: Households, Restaurants, Food Service, Catering Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale |
| Companies Covered | Campbell Soup Company, Mizkan America, Inc., The Kraft Heinz Company, Mars, Incorporated, Del Monte Foods, Inc., Barilla G. e R. Fratelli S.p.A, B&G Foods, Inc., Premier Foods Group Limited, ConAgra Foods, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pasta Sauce Market Strategic Shifts & Innovations
Product formulation is responding to a dual consumer mandate for authenticity and wellness. This shift influences ingredient sourcing and processing methods, pushing brands beyond traditional recipes into new functional and clean-label territories.
High-Pressure Processing (HPP) technology utilizes intense water pressure to achieve microbial inactivation without high heat. Premium sauce producers are adopting this method to meet household demand for preservative-free products with fresh-tasting attributes. This process is electrifying the premium category, enabling brands to offer refrigerated sauces with extended shelf life that bypass traditional thermal pasteurization.
The European Union's front-of-pack nutrition labeling initiatives, such as Nutri-Score, are gaining prominence across the continent. This policy pressures manufacturers to reformulate products by reducing salt, sugar, and fat content to achieve better health scores. Tomato-based sauce producers are particularly affected, investing in natural flavor enhancers to maintain taste while complying with new standards.
A consumer shift toward portion control and meal customization is altering packaging demand away from single large containers. Traditional family-size glass jars are being supplemented by single-serve flexible pouches and meal kits, especially in urban retail. This preference is most visible in the United States and the UK, where convenience and reduced food waste are primary purchase drivers.
Pasta Sauce Market Segmentation
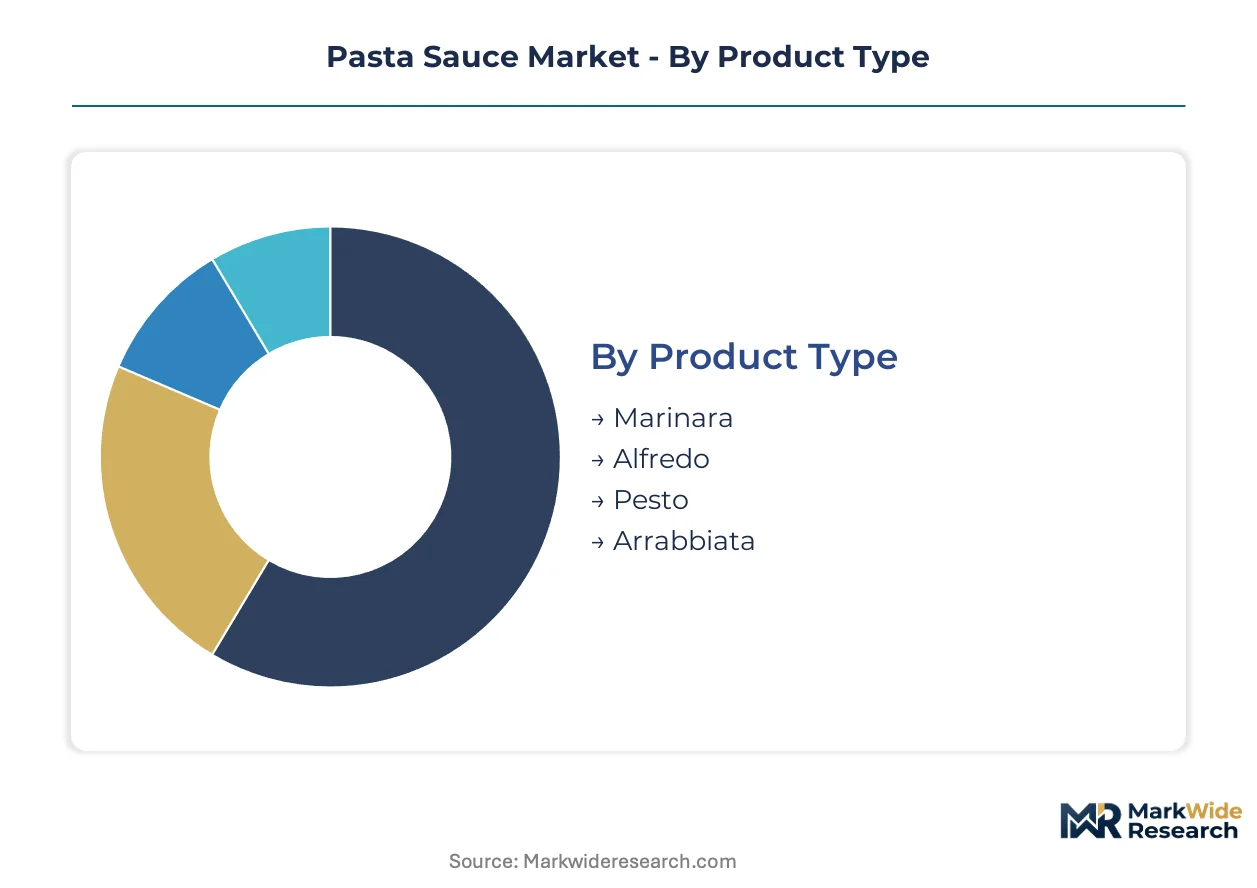
The pasta sauce market segments reflect diverse consumer preferences and operational demands, influencing product innovation and supply chain configurations. Understanding these distinct categories allows manufacturers to tailor offerings for specific consumption patterns and distribution channels.
Product Type:
The upgrade cycle for pasta sauces often involves consumers moving towards more authentic or specialized flavor profiles beyond basic tomato varieties.
- Marinara:This classic tomato-based sauce, typically seasoned with garlic, herbs, and olive oil, forms the foundational offering in most markets. Household demand in the United States drives significant volume due to its versatility and widespread use as a convenient meal solution.
- Alfredo:Characterized by its rich, creamy texture derived from butter, Parmesan cheese, and heavy cream, Alfredo sauce appeals to consumers seeking indulgent meal experiences. Its popularity in European restaurants often influences at-home consumption trends for premium options.
- Pesto:A vibrant green sauce made primarily from basil, pine nuts, garlic, Parmesan cheese, and olive oil, pesto offers a distinct aromatic profile. Specialty stores in Italy and beyond cater to consumers desiring fresh, herbaceous flavors.
- Arrabbiata:Known for its spicy kick from chili peppers, garlic, and tomatoes, Arrabbiata sauce attracts consumers seeking bolder, more adventurous flavors. Its appeal is growing among health-conscious individuals interested in Mediterranean cuisine with a twist.
Marinara sits at the top of the volume ranking, with Arrabbiata climbing the fastest.
Packaging Type:
Volume considerations heavily influence packaging choices, balancing consumer convenience with logistical efficiency and product preservation.
- Glass Jar:The traditional packaging choice, glass jars offer excellent product visibility and maintain a perception of quality and freshness. Supermarkets globally continue to stock glass jars extensively, reinforcing their position as a premium option in Europe.
- Pouch:Flexible pouches represent a modern packaging solution, offering lightweight convenience, reduced breakage, and easier storage. Urban retail environments in the United States increasingly favor pouches for their portability and reduced food waste potential.
- Plastic Bottle:Plastic bottles provide a lighter, more shatter-resistant alternative to glass, appealing to consumers prioritizing safety and ease of handling. Households often opt for plastic bottles for bulk purchases or when seeking child-friendly options.
- Can:Canned pasta sauces offer extended shelf life and cost-effectiveness, making them suitable for long-term storage and bulk procurement. Food service providers and institutional buyers frequently utilize canned options for their durability and economic benefits.
The shift towards lighter, more convenient options is evident, particularly with Pouch gaining significant traction.
End User:
Customer type dictates specific product attributes, from bulk sizing and ingredient consistency for professional kitchens to diverse flavor offerings for home cooks.
- Households:This segment comprises individual consumers and families purchasing pasta sauce for home cooking and meal preparation. Demand from North American households centers on ready-to-use sauces that offer convenience for quick meals.
- Food Service:Encompassing institutions, cafeterias, and large-scale catering operations, the food service segment requires consistent quality and bulk packaging. European food service providers prioritize cost efficiency and reliable supply for daily operations.
- Restaurants:Culinary establishments, from casual eateries to fine dining, demand specific flavor profiles and high-quality ingredients for their unique recipes. Specialty sauces catering to authentic Italian cuisine are particularly sought after by restaurants.
- Catering:Catering services, focused on events and large gatherings, require customizable solutions and large-volume packaging formats. This segment values consistency and the ability to scale production for diverse client needs.
While Households remains the largest consumer, the professional segment, including Restaurants, represents a stable demand channel.
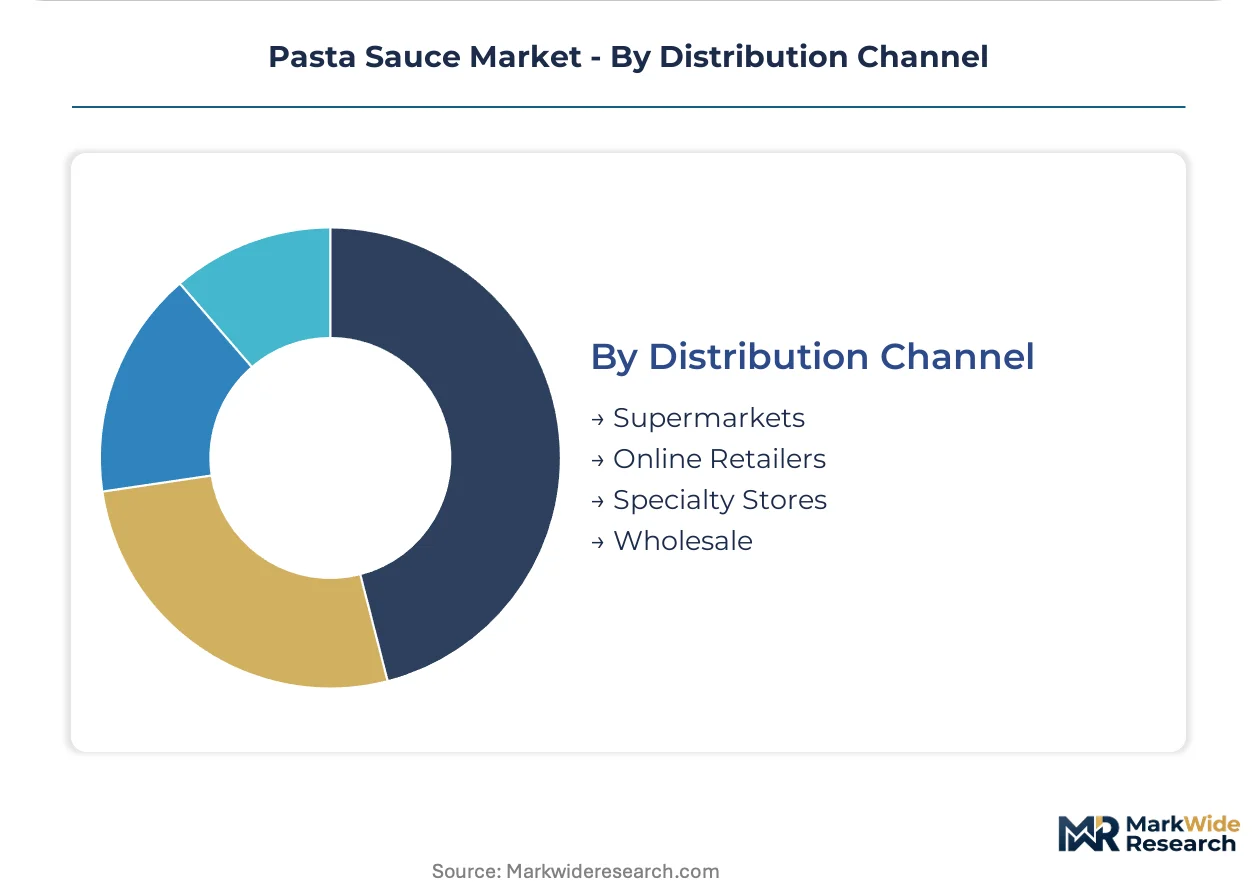
Distribution Channel:
Supply concentration patterns reveal how pasta sauces reach consumers, ranging from broad retail access to specialized or direct-to-consumer models.
- Supermarkets:These large retail chains offer broad consumer access and a wide selection of national and private-label brands. Supermarkets globally serve as the primary point of purchase, ensuring high brand visibility and competitive pricing.
- Online Retailers:E-commerce platforms facilitate direct delivery to consumers, offering convenience and access to niche or specialty brands. Urban centers in the United States show strong adoption of online retailers for their convenience and expanded product range.
- Specialty Stores:These outlets curate a selection of premium, organic, or gourmet pasta sauces, often focusing on unique ingredients and artisanal production. Discerning consumers seeking specific culinary experiences or high-quality ingredients frequent specialty stores.
- Wholesale:Wholesalers distribute pasta sauces in bulk to businesses, including restaurants, food service providers, and smaller retailers. This channel focuses on larger volumes and cost-effective procurement for commercial clients.
Traditional retail via Supermarkets continues to dominate, but Online Retailers demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence across major markets drives pasta sauce production decisions, as manufacturers balance compliance costs with supply chain efficiencies. Varying food safety and labeling standards from bodies like the US FDA and European Food Safety Authority (EFSA) influence ingredient sourcing and processing choices. This creates a regulatory arbitrage opportunity where production might shift to optimize for specific market access.
United States
Household demand for convenient meal solutions drives significant pasta sauce consumption across the United States. The US FDA's food additive regulations dictate ingredient purity and processing methods for domestic and imported products. Major food manufacturing hubs in states like California and Ohio concentrate production facilities, focusing on large-scale distribution.
Italy
Authentic Italian recipes and a strong culinary heritage underpin pasta sauce demand within Italy. European Union regulations, including EFSA's directives on food safety and origin labeling, ensure product integrity and consumer trust. The Emilia-Romagna region, known for its agro-food industry, hosts numerous specialized sauce producers emphasizing traditional methods.
China
Rising consumer interest in global cuisine, particularly Italian, stimulates pasta sauce adoption in urban centers across China. The SAMR (State Administration for Market Regulation) enforces national food safety standards and import regulations for processed food products. Major port cities like Shanghai and Guangzhou serve as key entry points and distribution hubs for international brands.
Germany
Demand for clean-label formulations and organic ingredients shapes the pasta sauce market in Germany. The EU's Nutri-Score labeling initiatives pressure manufacturers to reformulate products for healthier profiles. Food processing clusters in Bavaria and North Rhine-Westphalia focus on innovation in preservative-free and specialty sauce production.
Spain
Spain's role as a major tomato producer influences the availability and cost of primary ingredients for pasta sauce manufacturing. EFSA guidelines on pesticide residues and agricultural practices impact raw material sourcing for European processors. The agricultural regions of Andalusia and Murcia are critical for tomato cultivation, supplying both domestic and international sauce companies.
Pasta Sauce Market Key Industry Players
Established producers occupy the standard tier, leveraging brand recognition and extensive distribution, while emerging entrants pursue clean-label and specialty sauce segments. The market exhibits a tiered structure, with large multinational food conglomerates competing alongside smaller, agile artisanal brands. Strategic archetypes include heritage brands, convenience-focused manufacturers, and health-conscious innovators. Companies frequently engage in portfolio diversification and geographic expansion to capture new consumer bases.
Among heritage-driven brands, Barilla G. e R. Fratelli S.p.A exemplifies a focus on authentic Italian tradition and integrated supply networks. The Kraft Heinz Company, a prominent North American entity, occupies a position emphasizing brand recognition and broad supermarket distribution for its diverse product range. Campbell Soup Company represents a player focused on family-friendly flavor profiles and convenience within the household segment.
| Leading Market Players |
|---|
| Campbell Soup Company |
| Mizkan America, Inc. |
| The Kraft Heinz Company |
| Mars, Incorporated |
| Del Monte Foods, Inc. |
| Barilla G. e R. Fratelli S.p.A |
| B&G Foods, Inc. |
| Premier Foods Group Limited |
| ConAgra Foods, Inc. |
| Others |
Cost & Logistics Intelligence
Vertical integration into tomato sourcing anchors Barilla G. e R. Fratelli S.p.A.'s supply position, granting control over ingredient costs and influencing pricing power. This strategic choice allows major producers to manage agricultural volatility and maintain product consistency.
Pricing Analysis
Retailer markups significantly influence final consumer prices for pasta sauces across supermarkets. Pricing stratifies across premium, standard, and economy tiers, driven by brand premium for established names like Barilla and quality grade for HPP-processed, clean-label offerings. Pricing pressure stems from the constant threat of private-label alternatives and agricultural commodity volatility impacting tomato costs. Households demonstrate high price sensitivity, while restaurants prioritize specific flavor profiles and consistent quality, accepting higher prices.
Supply Chain Analysis
Single-source vulnerability sits with key agricultural regions like Italy and Spain for premium tomato inputs. Pasta sauce manufacturing draws heavily from these countries for its primary ingredient. The supply chain relies on consistent tomato harvests and olive oil availability, facing structural risk from agricultural commodity price volatility due to adverse weather. Distribution runs through established supermarkets globally, alongside expanding online retail channels for broader consumer access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pasta sauce market functions as a stable compounder, driven by sustained household demand for convenient meal solutions. This fundamental need provides a resilient growth trajectory for established brands and emerging players alike.
For Market Incumbents: Extend integrated supply networks to mitigate agricultural volatility, particularly for tomato procurement in Italy and Spain. Invest in High-Pressure Processing (HPP) technology to offer preservative-free formulations, countering private-label competition with differentiated clean-label products. This approach defends market share against cost pressures and satisfies consumer preferences for healthier options. Campbell Soup Company and Kraft Heinz Company can leverage brand recognition for these premium offerings.
For New Entrants and Emerging Players: Health-conscious consumers seeking functional ingredients represent a penetrable segment, particularly for sauces incorporating plant-based proteins or vegetable purees. Target urban centers in China and India where interest in authentic Italian cuisine is rising. Leverage direct-to-consumer (DTC) models or meal kit partnerships to bypass traditional retail barriers. Focus on unique flavor profiles like Arrabbiata or specialized pesto varieties.
For Investors and Strategic Acquirers: Roll-up economics work for food conglomerates because market fragmentation exists within the specialty and clean-label segments. The pasta sauce category offers long-term viability as an essential household staple over the next decade. Target mid-sized specialty brands with strong regional presence or innovative HPP-enabled product lines. The signal to watch is accelerated consumer adoption of flexible pouch packaging, indicating a shift in logistics and consumer preference.
| Strategic Initiative | Industry Significance |
|---|---|
| Brand Extension | Campbell Soup Company can introduce new functional ingredient sauces under Prego, expanding its product portfolio. |
| Direct-to-Consumer Launch | The Kraft Heinz Company can build direct relationships with US households for specialty pasta sauce products. |
| Premium Tier Introduction | Barilla G. e R. Fratelli S.p.A can launch HPP-processed, preservative-free sauces targeting European consumers. |
| Distribution Channel Expansion | Mizkan America, Inc. can expand its presence into meal kit partnerships across North America. |
| Sustainability Repositioning | Premier Foods Group Limited can highlight sustainable tomato sourcing from Spain to attract discerning European consumers. |
Research Approach
Multiple input streams—primary interviews, secondary validation, and proprietary databases—were reconciled to construct a robust market view. Primary engagement included product development executives, procurement managers, retail category buyers, and food safety regulators across major geographies. Secondary sources comprised US FDA public records, EFSA scientific opinions, customs trade data, and industry association reports. This approach employed both bottom-up and top-down triangulation methods.
Data stream reconciliation formed the analytical framework over the projection horizon, modeling key market segments. Segmentation dimensions included product type, packaging type, end user, distribution channel, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical trends and projected market dynamics. Forecast inputs integrated tomato harvest yields from Italy and Spain, alongside consumer convenience indices across North America.
Underlying measurement precision varies by segment; established product types like Marinara carry tighter precision than emerging specialty sauces. Forecasts reflect assumptions regarding agricultural commodity price stability and evolving food safety regulations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Oyster Sauce Market
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
Cheese Sauce Market
Condiments & Sauces
Europe Gluten-Free Soups and Sauces Market
Condiments & Sauces
Vinegar and Vinaigrette Market
Condiments & Sauces
UK Prepared Mustard Market
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
Sugar Toppings Market
Condiments & Sauces
Curry Cube Market
Condiments & Sauces
Sauces and Condiments Market
Condiments & Sauces
Fat Free Salad Dressings Market
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
Sweet and Savory Spread Market