
 Hot Sauce Market | 2026-2036
Hot Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Sauce Market Intelligence
Multi-pack bundling and sampler configurations is recalibrating how households discover new heat profiles and flavor combinations. Huy Fong Foods, Inc. leverages its iconic rooster branding and cult following to sustain direct-to-retailer relationships without traditional advertising spend. McIlhenny Company anchors its position through Tabasco's century-plus aged-barrel fermentation process, which competitors struggle to replicate at scale. Grupo Herdez competes aggressively in Latin American retail channels with region-specific chili varietals that command shelf-space loyalty.
Hot sauce comprises chili pepper-based condiments formulated with vinegar, salt, and auxiliary flavoring agents, typically achieving pungency ratings from mild to extreme via Scoville Heat Unit concentration and fermentation duration. The product serves commercial food preparation, retail consumer cooking, and table-side enhancement across casual dining and quick-service environments. Chili-based formulations dominate volume due to established agricultural supply chains and cross-cultural menu integration, while fruit-based variants generate outsized margin contribution through premium positioning in specialty retail. Sachet packaging within the foodservice channel captures institutional demand from airlines, hospitals, and contract catering operations seeking portion control and waste reduction.
FDA enforcement of Acidified Food Regulations and FSMA preventive controls governs pH thresholds, thermal processing validation, and foreign supplier verification for imported pepper mash. State-level health departments in California, Texas, and Louisiana impose additional facility inspection schedules that shape regional production siting decisions. Mexico's COFEPRIS maintains parallel labeling and additive standards that Mexican exporters must reconcile for cross-border commerce. Stakeholders should monitor evolving sodium-reduction mandates and clean-label certification requirements, as these standards increasingly determine retail distribution access and foodservice contract eligibility.
Market Dynamics
Foodservice operators now treat hot sauce as a menu-differentiation tool rather than a commodity condiment, forcing suppliers to deliver proprietary formulations and co-branded retail extensions that transcend traditional condiment economics.
Growth Catalysts
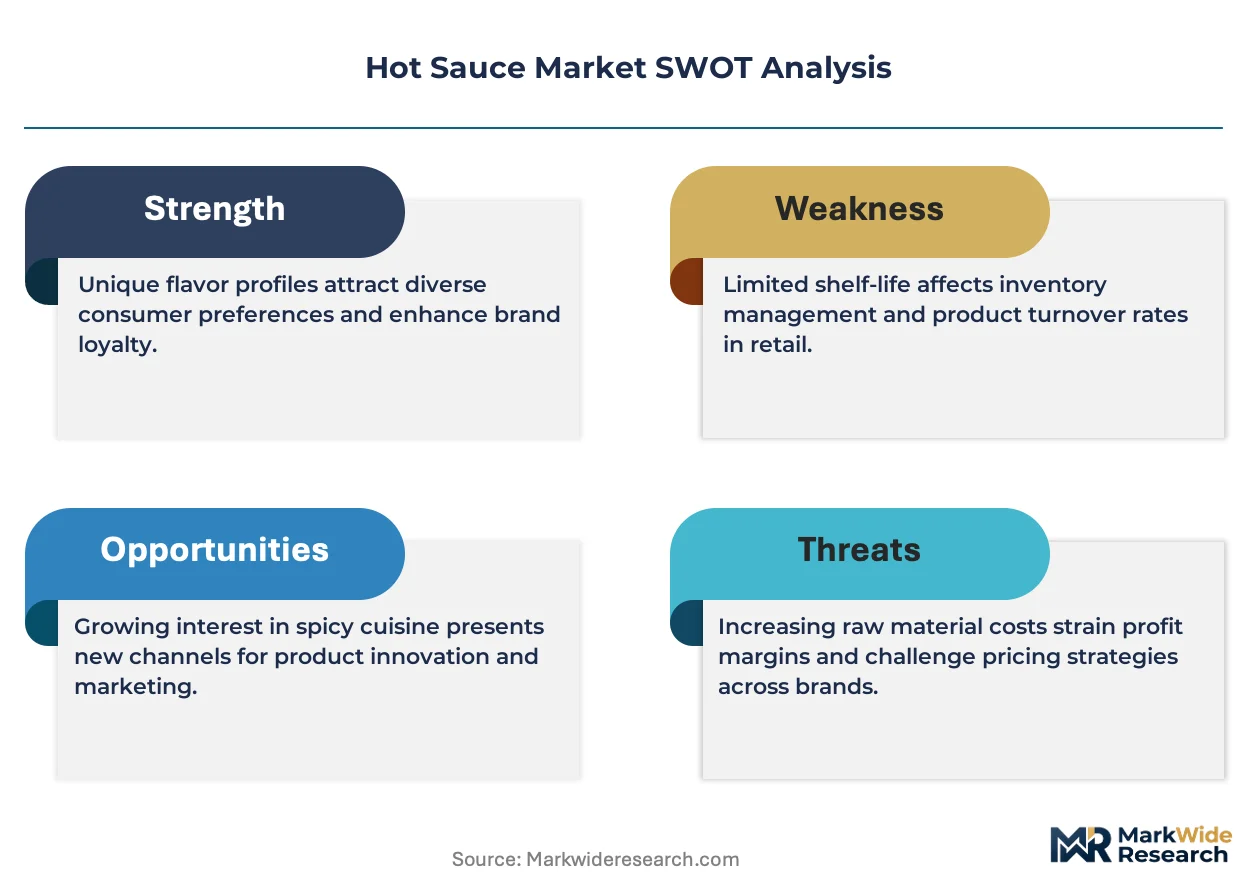
- Fermentation Process Innovation:Extended barrel-aging techniques create Scoville concentration gradients that command premium positioning in specialty retail channels.
- COFEPRIS Cross-Border Harmonization:Mexico's streamlined additive standards reduce compliance friction for pepper mash exporters entering US distribution networks.
- Airline Catering Sachet Contracts:Portion-controlled packaging formats capture institutional demand from contract catering operations seeking waste reduction protocols.
Market Restraints
- Chili Pepper Supply Concentration:Cultivation gravity in Mexico's Chihuahua and Sinaloa regions creates climate-exposure vulnerability for mash suppliers dependent on specific varietals.
- FDA Acidified Food pH Thresholds:Thermal processing validation requirements impose capital-intensive laboratory infrastructure that excludes small-batch entrants.
- Vinegar Cost Volatility:Grain-based ethanol feedstock fluctuations directly compress margins for vinegar-dependent fermentation recipes.
Strategic Opportunities
- India FSSAI Clean-Label Pathway:Sodium-reduction certification requirements create first-mover advantage for low-salt fermentation formulations in emerging retail channels.
- Direct-to-Consumer Subscription Models:Heat-profile curation services bypass traditional retail slotting fees while capturing household discovery behavior.
- Fruit-Based Premium Extensions:Mango-habanero and pineapple-scotch bonnet variants unlock specialty margins through flavor complexity differentiation.
Industry Challenges
- Scoville Calibration Talent Scarcity:Certified sensory panel operators and HPLC analytical chemists command wage premiums that inflate quality-control overhead.
- Legacy Equipment Retrofit Costs:Stainless-steel fermentation vessel upgrades to meet FSMA preventive controls require multi-year capital deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Sauce Market |
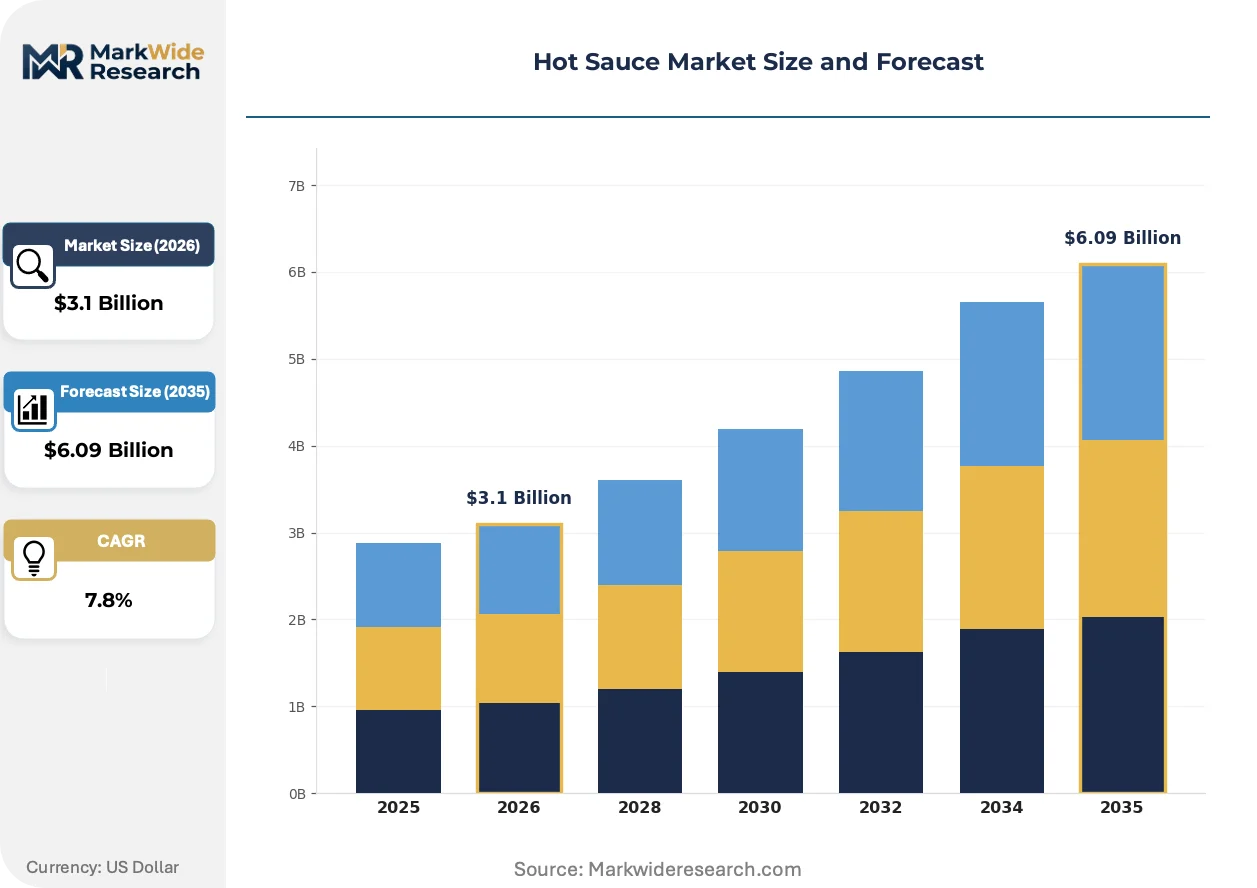
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.09 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chili-based, Fruit-based, Garlic-based, Vinegar-based, Pepper-based Flavor Profile: Spicy, Sweet, Smoky, Tangy, Savory Packaging Type: Bottle, Sachet, Jar, Box, Bulk Container Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Foodservice Providers, Convenience Stores |
| Companies Covered | Huy Fong Foods, Inc., Conagra Brands, Inc., The Kraft Heinz Company, Grupo Herdez, Campbell Soup Company, McCormick & Company, Inc., Unilever PLC, Cholula Food Company, McIlhenny Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Sauce Market Strategic Shifts & Innovations
Formulation science and packaging engineering are converging to transform how heat intensity gets delivered, measured, and experienced across consumption occasions.
Precision fermentation technology is electrifying how producers achieve consistent Scoville profiles without multi-year barrel aging. Mid-scale manufacturers in Texas and Louisiana adopt bioreactor-controlled microbial cultures to compress fermentation cycles from thirty-six months to under ninety days. This acceleration is electrifying competitive pressure on heritage brands whose aged-mash positioning now requires explicit quality justification.
EU EFSA novel food assessments are reshaping ingredient permissibility for pepper extracts and capsaicin concentrates entering European retail. The 2023 updated guidance on chili-derived compounds forces reformulation of extreme-heat products targeting Scoville thresholds above one million units. German and Dutch importers now demand batch-level toxicological documentation that US exporters rarely maintained previously.
Restaurant procurement teams are consolidating condiment suppliers into single-source agreements that bundle hot sauce with oil, vinegar, and spice categories. This consolidation is displacing standalone hot sauce distributors who lack broadline foodservice portfolios. The shift is most visible in California and Arizona quick-service chains where procurement directors negotiate enterprise-wide contracts spanning three hundred plus locations.
Hot Sauce Market Segmentation
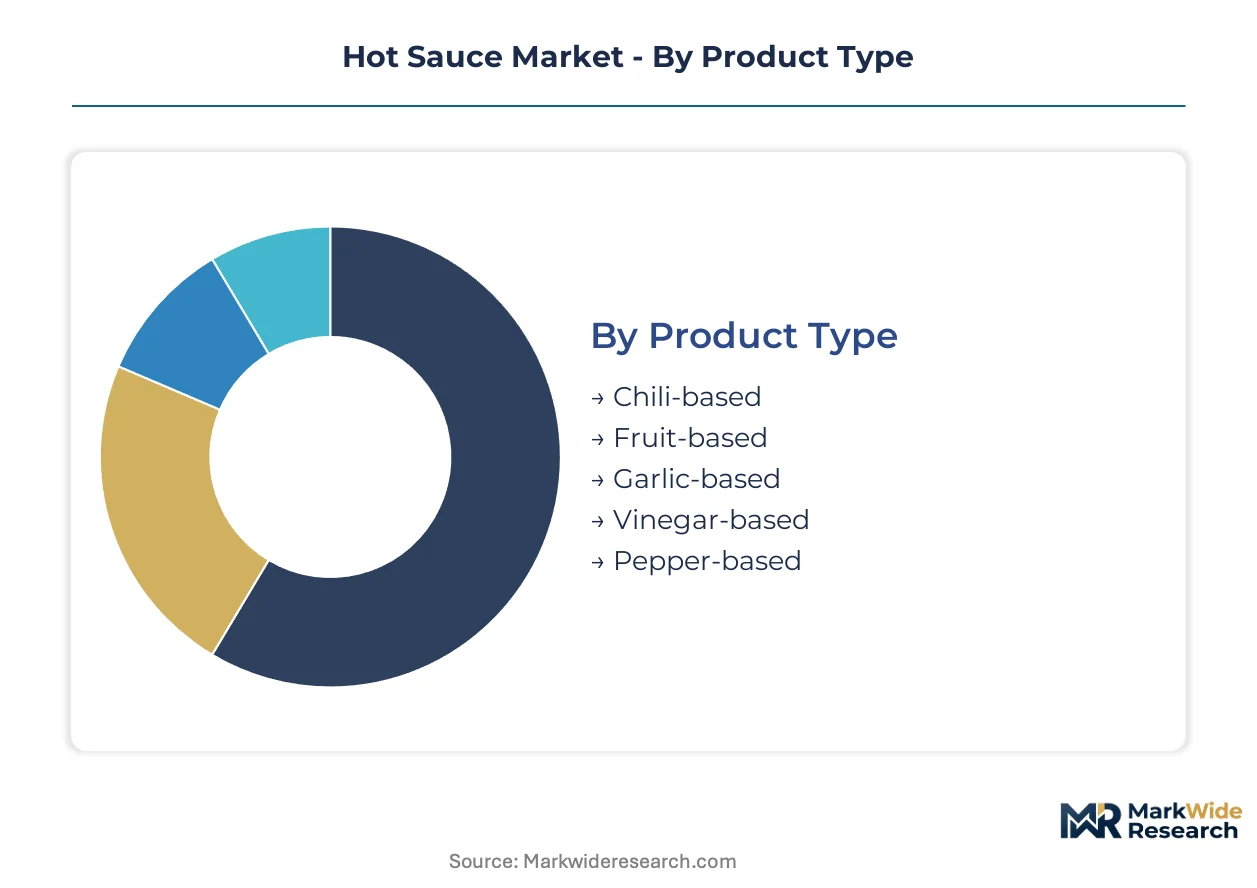
Hot sauce segmentation reveals how formulation chemistry, consumption occasion, and channel economics create distinct competitive arenas. Suppliers configure production assets and brand positioning around specific segment boundaries rather than treating the category as uniform.
Product Type:
Standalone condiment formats dominate retail shelf placement, while embedded ingredient systems penetrate food manufacturing and foodservice back-of-house operations.
- Chili-based:Fermented pepper mash formulations with Scoville ratings from 1,000 to 500,000 units anchor volume production. Demand concentrates in Mexico's Chihuahua and Sinaloa cultivation belts, where climate-exposure vulnerability for specific varietals creates supply-side risk.
- Fruit-based:Mango-habanero and pineapple-scotch bonnet blends achieve premium positioning through flavor complexity differentiation. Foodservice operators in California and Arizona quick-service chains deploy these variants as menu-differentiation tools.
- Garlic-based:Roasted garlic-chili emulsions target Mediterranean and Middle Eastern flavor preference clusters.
- Vinegar-based:Louisiana-style cayenne-vinegar blends serve institutional catering contracts seeking cost-controlled heat delivery.
- Pepper-based:Single-varietal expressions highlight specific capsaicin profiles for enthusiast retail channels.
Volume placements concentrate in chili-based formulations; the faster expansion belongs to fruit-based variants.
Flavor Profile:
Cost tier stratification separates commodity heat delivery from experiential flavor systems that command slotting fee absorption and promotional support.
- Spicy:Pure capsaicin-forward formulations prioritize Scoville intensity over auxiliary flavor layering. Texas and Louisiana mid-scale manufacturers deploy bioreactor-controlled microbial cultures to compress fermentation cycles.
- Sweet:Honey-agave or fruit-sugar balances offset heat perception for entry-level consumers. Household discovery behavior through multi-pack bundling drives trial conversion in this tier.
- Smoky:Chipotle and smoked paprika variants integrate barbecue and grilling occasion targeting.
- Tangy:Citrus-forward acidity profiles align with seafood and poultry pairing applications.
- Savory:Umami-enhanced formulations incorporating fermented soybean or mushroom extracts.
Mainstream retail velocity clusters in spicy profiles; savory extensions are climbing the fastest through specialty store penetration.
Packaging Type:
Customer type segmentation separates household pantry stocking from institutional procurement protocols with divergent unit economics and shelf-life requirements.
- Bottle:Glass and PET formats with precision-flow caps dominate household pantry replenishment. Direct-to-retailer relationships without traditional advertising spend sustain margin capture for heritage brands.
- Sachet:Single-serve foil packets serve airline catering, hospital foodservice, and contract catering operations seeking portion control and waste reduction protocols.
- Jar:Wide-mouth containers target foodservice back-of-house scoop operations.
- Box:Bag-in-box systems for high-volume fountain dispenser installations.
- Bulk Container:Food-manufacturing ingredient supply with pH-stabilized aseptic filling.
Procurement volume aggregates in bottle formats; sachet configurations are gaining share fastest through institutional contract consolidation.
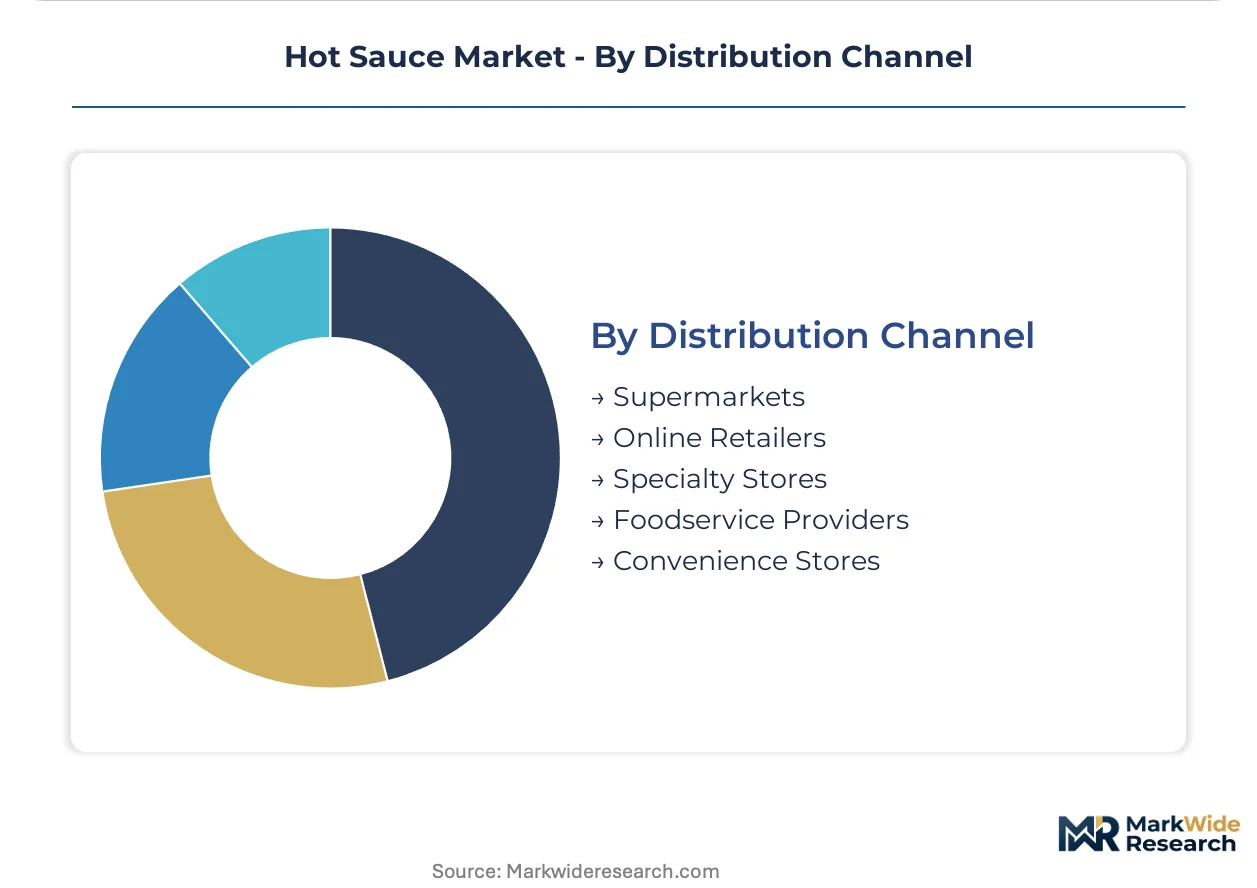
Distribution Channel:
Geographic concentration of purchasing power shapes channel investment priority, with coastal metropolitan markets subsidizing inland expansion economics.
- Supermarkets:Mass-market retail with slotting fee structures and promotional calendar dependency. Three-tier pricing structure across premium, standard, and economy levels determines shelf positioning.
- Online Retailers:Direct-to-consumer subscription models bypass traditional retail slotting fees while capturing household discovery behavior. Heat-profile curation services aggregate enthusiast demand.
- Specialty Stores:Gourmet and ethnic-format retailers with educated staff and sampling infrastructure.
- Foodservice Providers:Broadline distributors bundling hot sauce with oil, vinegar, and spice categories into single-source agreements spanning three hundred plus locations.
- Convenience Stores:Impulse-purchase oriented with limited SKU count and grab-and-go packaging.
Revenue concentration sits with foodservice providers; online retailers show the steepest expansion trajectory through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Mexico's Chihuahua and Sinaloa cultivation belts while consumption gravity sits in the United States. This divide shapes cross-border supply chain configuration and regulatory harmonization priorities across North America.
United States
Foodservice operators in California and Arizona quick-service chains deploy hot sauce as menu-differentiation tools through enterprise-wide procurement contracts. FDA Acidified Food Regulations and FSMA preventive controls govern pH thresholds and thermal processing validation for domestic manufacturers. Texas and Louisiana host mid-scale manufacturers adopting bioreactor-controlled microbial cultures to compress fermentation cycles.
Mexico
Chili pepper cultivation traditions in Chihuahua and Sinaloa anchor supply chains for pepper mash exports entering US distribution networks. COFEPRIS maintains labeling and additive standards that exporters must reconcile for cross-border commerce. Grupo Herdez competes aggressively in Latin American retail channels with region-specific chili varietals commanding shelf-space loyalty.
Canada
Health Canada and PMRA regulate imported pepper extracts and capsaicin concentrates entering Canadian retail through novel food assessments. Ontario and Quebec distribution networks channel both US and Mexican formulations into foodservice and retail segments. Institutional catering contracts in Vancouver and Toronto drive sachet packaging demand for portion-controlled applications.
Germany
EU EFSA novel food assessments reshape ingredient permissibility for extreme-heat products targeting Scoville thresholds above one million units. German importers now demand batch-level toxicological documentation that US exporters rarely maintained previously. Berlin and Hamburg retail channels show expanding velocity for fruit-based premium variants through specialty store penetration.
India
FSSAI clean-label certification requirements create first-mover advantage for low-salt fermentation formulations in emerging retail channels. Maharashtra and Gujarat distribution networks channel both domestic and imported formulations into quick-service and casual dining environments. Direct-to-consumer subscription models in Bangalore and Mumbai capture household discovery behavior through heat-profile curation services.
Hot Sauce Market Key Industry Players
The competitive structure tilts toward heritage brands with aged-mash positioning and mid-scale precision fermentation adopters. Consolidation pressure runs through broadline foodservice bundling agreements that displace standalone hot sauce distributors. Two strategic archetypes dominate: century-plus fermentation heritage players and bioreactor-enabled cycle compression specialists. Competitive moves concentrate on co-branded retail extensions and direct-to-retailer relationship cultivation without traditional advertising spend.
Within the heritage archetype, McIlhenny Company and Huy Fong Foods, Inc. exemplify contrasting positioning strategies. McIlhenny Company anchors its market presence through century-plus aged-barrel fermentation processes that competitors struggle to replicate at scale. Huy Fong Foods, Inc. leverages iconic rooster branding and cult following to sustain direct-to-retailer relationships. Grupo Herdez occupies a position representing Latin American retail channel specialization with region-specific chili varietals.
| Leading Market Players |
|---|
| Huy Fong Foods, Inc. |
| Conagra Brands, Inc. |
| The Kraft Heinz Company |
| Grupo Herdez |
| Campbell Soup Company |
| McCormick & Company, Inc. |
| Unilever PLC |
| Cholula Food Company |
| McIlhenny Company |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps in Louisiana and Texas anchor fermentation capacity while private-equity-rolled-up specialists consolidate pepper mash sourcing, tightening pricing discipline through captive supply relationships and multi-year offtake contracts with Chihuahua growers.
Pricing Analysis
Margin tightening in the standard tier reflects vinegar cost volatility and grain-based ethanol feedstock fluctuations. Pricing stratifies across premium barrel-aged, standard precision-fermented, and economy vinegar-based tiers, with differentiation driven by Scoville certification grade and fermentation duration. Cost compression accelerates as broadline foodservice bundling displaces standalone distributors. Quick-service procurement teams show least price sensitivity; contract catering operations exhibit highest.
Supply Chain Analysis
Pepper mash supply rests on Mexican cultivation belts in Chihuahua and Sinaloa, with secondary fermentation capacity concentrated in Louisiana and Texas. Raw material dependencies include cayenne and habanero varietals, white distilled vinegar, and oak barrel inventory. Climate exposure vulnerability for specific chili varietals creates single-source concentration risk. Distribution runs through cross-border cold chain logistics into US broadline foodservice distributors and direct-to-retailer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from broadline foodservice bundling agreements forces weaker standalone distributors toward exit or acquisition, favoring players with captive fermentation assets and multi-category portfolios.
For Market Incumbents: To counter displacement by bundled procurement contracts, secure backward integration into Chihuahua pepper mash supply and invest in COFEPRIS-compliant labeling infrastructure for cross-border volume capture. For New Entrants and Emerging Players: Capture white-space in direct-to-consumer subscription curation and fruit-based premium extensions, targeting California and Arizona quick-service chains with mango-habanero formulations and co-branded retail programs. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision-fermentation-enabled mid-caps in Texas with bioreactor assets and compressed cycle capabilities, with long-term viability hinging on clean-label certification positioning; watch FSSAI sodium-reduction mandates as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pepper Mash Supply | Captive sourcing from Chihuahua cultivation belts insulates margin from climate-driven supply shocks. |
| Precision Fermentation Technology Deployment | Bioreactor-controlled cultures compress aging cycles from thirty-six months to under ninety days. |
| Direct-to-Consumer Subscription Launch | Heat-profile curation bypasses retail slotting fees while capturing household discovery behavior. |
| FSSAI Clean-Label Certification Investment | Low-salt fermentation formulations unlock first-mover advantage in Indian retail channels. |
| Co-Branded Retail Extension Development | Proprietary formulations for California quick-service chains build enterprise contract stickiness. |
Research Approach
Document review covered FDA Acidified Food Regulations, COFEPRIS labeling standards, and FSMA preventive controls guidance, complemented by interviews with fermentation facility operators, broadline foodservice procurement directors, specialty retail category buyers, and chili cultivation cooperatives in Chihuahua. Secondary sources included customs trade data, SEC 10-K filings of publicly traded condiment manufacturers, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category spend estimates.
Historical shipment data cross-referenced against expert panel input on fermentation cycle compression and clean-label certification timelines. Segmentation dimensions modeled include product type, flavor profile, packaging format, and distribution channel across the analysis window. CAGRs derived from slope-log regression on normalized volume indices, with inputs from vinegar feedstock cost trajectories and airline catering contract renewal rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to climate disruption in Sinaloa growing regions and EU EFSA novel food assessment rulings on capsaicin concentrates. Forecasts reflect documented assumptions on regulatory harmonization and substitution elasticity. A small set of triggers—COFEPRIS-US FDA alignment progress, precision fermentation scale economics, and institutional sachet contract consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
Sweet and Savory Spread Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Compound Condiments Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Europe Gluten-Free Soups and Sauces Market
Condiments & Sauces
Acciughe Pasta Sauce Market
Condiments & Sauces
Mayonnaise Sauce Market
Condiments & Sauces
Tomato Ketchup Market
Condiments & Sauces
Dips and Spreads Market
Condiments & Sauces
Salad Dressings and Mayonnaise Market
Condiments & Sauces
Culinary Sauces Market
Condiments & Sauces
UK Prepared Mustard Market
Condiments & Sauces
Curry Cube Market
Condiments & Sauces
Ketchup Market