
 Low-Sodium Salt Substitute Market | 2026-2036
Low-Sodium Salt Substitute Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Sodium Salt Substitute Market Analytics
The gap between premium mineral-balanced formulations and commodity potassium chloride is expanding as health-conscious consumers trade up for taste-comparable alternatives. Cargill leverages its agricultural supply chain to secure raw material cost advantages across North America. NuTek Natural Ingredients specializes in patented bitter-blocker technology that improves sensory profiles in reduced-sodium applications. Jungbunzlauer anchors European production with fermentation-derived mineral salts that meet clean-label requirements.
Low-sodium salt substitutes are engineered mineral compositions, typically incorporating potassium chloride at 50-70% by weight alongside magnesium, calcium, or yeast-derived flavor modulators, designed to replicate sodium chloride's osmotic and sensory functions in food matrices. Potassium chloride dominates volume due to established supply chains and cost structures, though blended salts containing magnesium sulfate are capturing faster growth in premium positioning where complete electrolyte profiles command shelf space. Food manufacturers represent the most concentrated end-user segment, with processed foods and packaged snacks absorbing the majority of industrial volumes as reformulation timelines compress.
The FDA's voluntary sodium reduction targets and the EU's nutrition and health claims regulation, overseen by EFSA, are compelling manufacturers to document compositional changes and substantiate health benefit communications. Health Canada and the UK's Food Standards Agency are implementing parallel front-of-pack labeling schemes that penalize high-sodium products with warning symbols. Stakeholders must monitor evolving maximum-per-serving thresholds and pre-market notification requirements as jurisdictions compete to tighten standards.
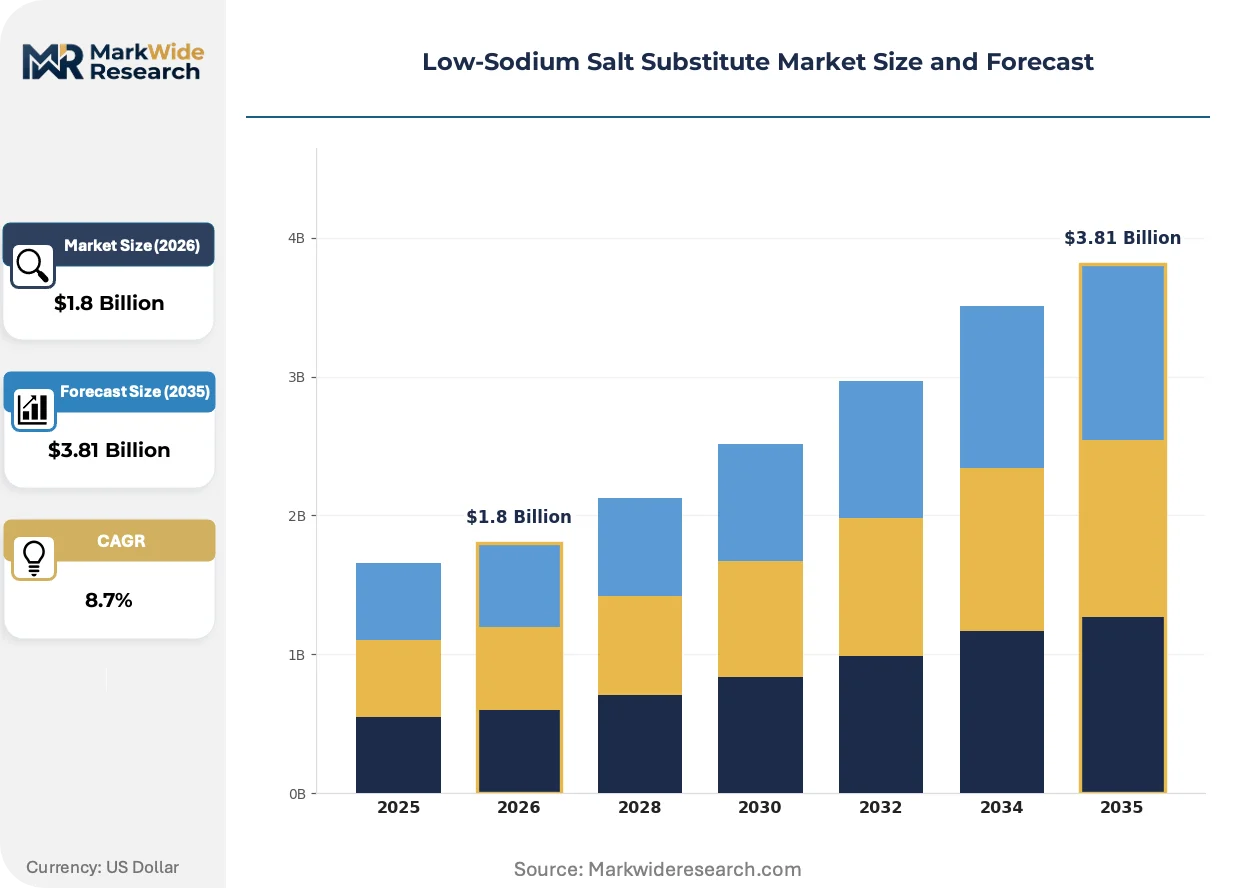
Market Dynamics
Reformulation mandates from front-of-pack labeling schemes are compressing product development cycles for processed food manufacturers. The FDA's voluntary sodium reduction targets and EFSA health claims procedures now require documented compositional changes before market entry.
Growth Catalysts
- Front-of-Pack Labeling Mandates:Health Canada and the UK's Food Standards Agency warning symbols on high-sodium products are forcing CPG brands to accelerate reformulation timelines.
- Potassium Chloride Supply Maturation:Established agricultural supply chains across the United States and Canada have stabilized input costs for mineral salt manufacturers.
- Clean-Label Fermentation:Yeast-derived flavor modulators from European biotechnology facilities are expanding the addressable market for taste-comparable sodium alternatives.
Market Restraints
- Potassium Chloride Price Volatility:Fertilizer market fluctuations and agricultural commodity cycles create input cost instability for blended salt producers.
- Bitter Taste Perception:Potassium chloride's metallic aftertaste requires expensive bitter-blocker additives or magnesium sulfate co-formulation, raising unit economics.
- Pre-Market Notification Burden:EFSA novel food assessments and FDA GRAS self-affirmation procedures extend product launch timelines by 18-24 months.
Strategic Opportunities
- Institutional Foodservice:Hospital and school cafeteria procurement standards in the United States are mandating sodium reduction, creating bulk contract opportunities.
- Complete Electrolyte Positioning:Magnesium-calcium-potassium blends targeting sports nutrition and functional beverages command premium shelf placement.
- Direct-to-Consumer Channels:E-commerce platforms and subscription models bypass traditional retail slotting fees for specialty mineral salt brands.
Industry Challenges
- Sensory Scientist Shortage:Food matrix reformulation requires rare expertise in salt taste receptor modulation and temporal flavor perception.
- Legacy Equipment Retrofit Costs:Hygroscopic potassium chloride blends corrode standard sodium chloride handling machinery, requiring stainless steel line upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Sodium Salt Substitute Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Chloride, Calcium Chloride, Magnesium Sulfate, Blended Salts Application: Food Seasoning, Processed Foods, Packaged Snacks, Bakery Products End User: Households, Food Manufacturers, Restaurants, Health Care Institutions Packaging Type: Bottles, Sachets, Bulk Packaging, Jars |
| Companies Covered | Cargill, Tate & Lyle, NuTek Natural Ingredients, Jungbunzlauer, Koninklijke DSM, Innophos Holdings, Sensient Technologies, K+S Kali GmbH, Angel Yeast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Sodium Salt Substitute Market Evolving Landscape
Mineral composition engineering and fermentation-derived flavor technologies are displacing commodity potassium chloride in premium applications. Patent activity around bitter receptor blockers and temporal taste release systems has intensified.
Fermentation-derived mineral salts from European biotechnology facilities are consolidating quality-sensitive segments. Jungbunzlauer's citrate and lactate production platforms supply clean-label electrolyte blends to organic and natural-positioned brands. The technology is consolidating supply relationships with retailers demanding supply chain transparency documentation.
EFSA's 2023 updated guidance on sodium-related health claims tightened evidentiary standards for blood pressure reduction communications. Food manufacturers must now submit human intervention studies with ambulatory blood pressure monitoring endpoints. Premium-positioned brands with clinical trial investments are capturing shelf space from commodity suppliers lacking substantiation.
Retail buyer consolidation around reduced-sodium private label programs is compressing supplier margins and switching costs. Walmart, Kroger, and Albertsons have centralized salt substitute procurement under dedicated category managers who negotiate multi-year reformulation partnerships. The United States exhibits the most concentrated buyer power, with three retail chains controlling over sixty percent of reduced-sodium product distribution.
Low-Sodium Salt Substitute Market Segmentation
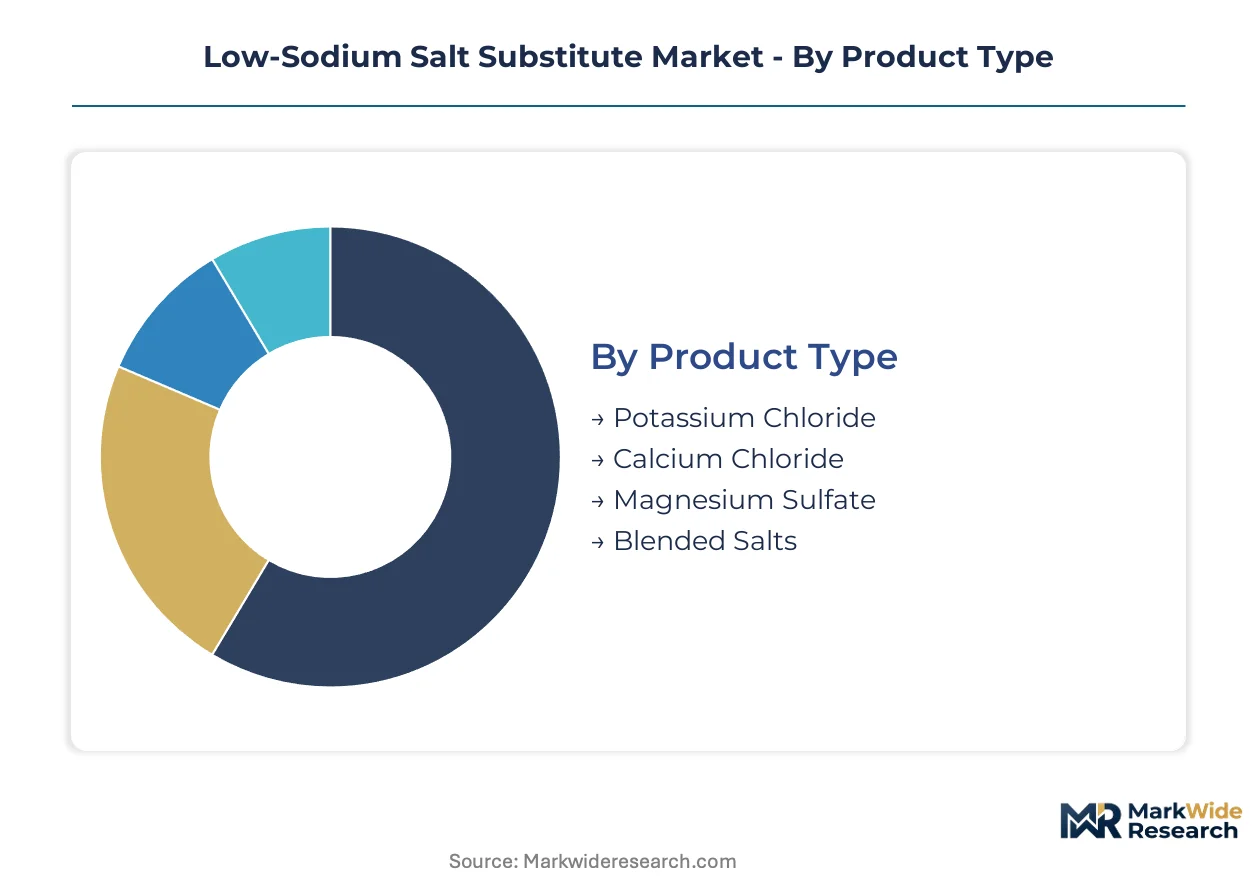
Segmentation in low-sodium salt substitutes reveals divergent capital requirements, formulation complexity, and regulatory exposure across product categories. Manufacturers allocate R&D budgets unevenly based on which segments demand clinical substantiation versus commodity scale.
Product Type:
Potassium chloride production demands the heaviest upfront investment in agricultural supply chain integration and purification infrastructure.
- Potassium Chloride:Dominates volume at 50-70% mineral composition, requiring extensive mining or agricultural byproduct processing facilities. Food manufacturers in the United States absorb the majority of industrial-grade volumes as FDA sodium reduction targets compress reformulation timelines.
- Blended Salts:Combine potassium chloride with magnesium sulfate and calcium salts to mask metallic aftertaste through electrolyte synergy. Premium positioning in European markets accelerates as EFSA health claims procedures mandate documented compositional changes for blood pressure reduction communications.
- Calcium Chloride:Functions as a secondary mineral in texture-modified applications with lower capital barriers to entry.
- Magnesium Sulfate:Supplies complete electrolyte profiles for sports nutrition and functional beverage segments with moderate processing investment.
Potassium chloride absorbs the bulk of installed capacity; blended salts are expanding most quickly.
Application:
Application segments diverge sharply in technical specification requirements, with processed foods demanding the most sophisticated matrix reformulation capabilities.
- Processed Foods:Canned soups, frozen meals, and ready-to-eat categories require precise osmotic function replication without sodium chloride. Health Canada front-of-pack labeling schemes with warning symbols on high-sodium products force CPG brands into accelerated reformulation partnerships with mineral salt suppliers.
- Packaged Snacks:Chips, crackers, and savory mixes prioritize surface adhesion and rapid flavor release over bulk matrix integration. The United Kingdom's Food Standards Agency warning symbol system concentrates demand among private label programs at major retail chains.
- Food Seasoning:Tabletop shakers and cooking salts compete on taste-comparability with simpler formulation requirements.
- Bakery Products:Yeast activation and gluten structure modification limit substitution rates, constraining addressable volume.
Processed foods command the largest formulation investment; packaged snacks are climbing the fastest as retail buyer consolidation accelerates.
End User:
End user segmentation reflects divergent procurement scale, with food manufacturers operating centralized purchasing that dwarfs household retail volumes.
- Food Manufacturers:Industrial buyers negotiate multi-year supply agreements with documented sodium reduction commitments. The United States exhibits the most concentrated buyer power, with three retail chains controlling over sixty percent of reduced-sodium product distribution through private label centralization.
- Health Care Institutions:Hospital and school cafeteria procurement standards in the United States mandate sodium reduction, creating bulk contract opportunities with strict nutritional specification requirements.
- Households:Direct-to-consumer channels bypass traditional retail slotting fees through e-commerce platforms and subscription models.
- Restaurants:Foodservice distributors represent a fragmented, price-sensitive channel with slower adoption curves.
Food manufacturers dominate procurement volume; health care institutions are gaining share fastest as mandatory nutrition standards proliferate.
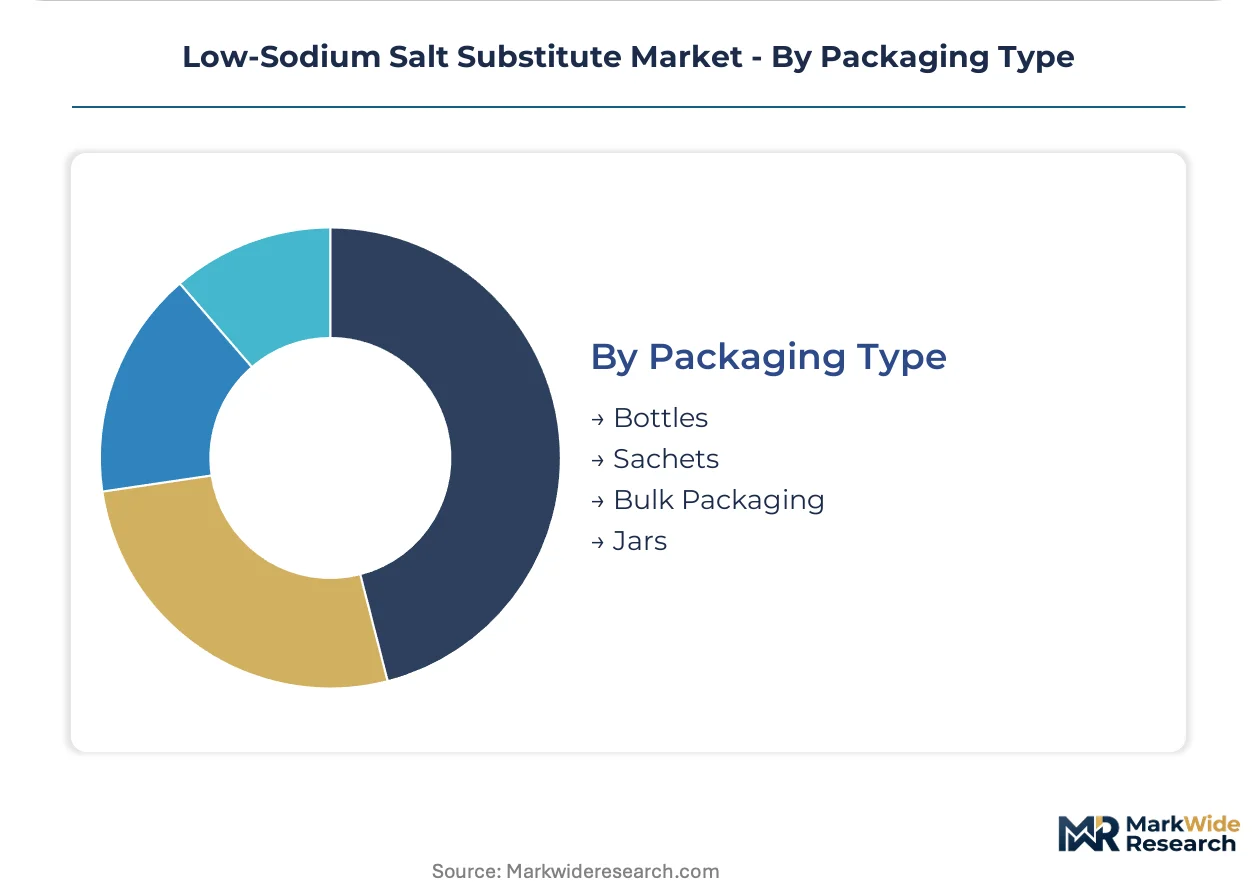
Packaging Type:
Packaging segmentation tracks hygroscopicity management requirements, with bulk formats demanding specialized moisture barrier infrastructure.
- Bulk Packaging:Industrial totes and supersacks for food manufacturers require corrosion-resistant handling systems due to potassium chloride's hygroscopic properties. Stainless steel line upgrades represent significant capital expenditure for legacy sodium chloride equipment retrofits.
- Sachets:Single-serve portions for foodservice and institutional channels balance convenience with portion control precision.
- Bottles:Tabletop containers for household retail compete on shelf stability and pour control features.
- Jars:Premium positioning formats emphasize resealability and kitchen counter visibility.
Bulk packaging handles the greatest tonnage; sachets are expanding most quickly as institutional procurement standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American low-sodium salt substitute procurement as major retail chains centralize private label reformulation programs. FDA sodium reduction targets compress supplier timelines across the region. Three retail buyers control over sixty percent of reduced-sodium distribution through consolidated category management.
United States
Health Canada front-of-pack warning symbols on high-sodium products accelerate CPG reformulation partnerships. FDA voluntary sodium targets mandate documented compositional changes before market entry. Minneapolis-St. Paul corridor hosts major agricultural processors securing potassium chloride supply chain advantages.
Germany
EFSA health claims procedures tighten evidentiary standards for blood pressure reduction communications. Clean-label fermentation facilities in Baden-Württemberg supply mineral salts to organic-positioned brands. Stuttgart region biotechnology clusters consolidate quality-sensitive segment supply relationships.
United Kingdom
Food Standards Agency warning symbol schemes concentrate demand among private label programs at major retail chains. Front-of-pack labeling mandates force accelerated reformulation timelines for packaged snacks. London procurement headquarters negotiate multi-year sodium reduction partnerships with mineral salt suppliers.
China
Dual carbon goals and clean-label fermentation investments expand addressable market for taste-comparable sodium alternatives. National food safety standards tighten maximum-per-serving thresholds for processed food manufacturers. Yangtze River Delta biotechnology facilities scale yeast-derived flavor modulator production.
Canada
Health Canada sodium reduction guidelines align with US FDA targets, creating cross-border formulation standardization. Prairie agricultural regions stabilize potassium chloride input costs through established mining and processing infrastructure. Toronto food manufacturing corridor absorbs industrial-grade volumes for reformulated processed foods.
Low-Sodium Salt Substitute Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and clinical substantiation depth. Agricultural supply chain integrators dominate volume positions while fermentation-derived mineral specialists capture quality-premium segments. Three strategic archetypes define competitive positioning: agricultural commodity processors with captive raw material access, biotechnology platforms leveraging clean-label fermentation, and mineral engineering specialists with patented taste modulation. Capacity expansion and multi-year reformulation partnerships represent the dominant competitive moves as retail buyer consolidation accelerates.
Within the agricultural-commodity tier, Cargill exemplifies supply chain integration archetypes through its North American agricultural processing footprint. Jungbunzlauer occupies the fermentation-derived mineral salt position among European biotechnology platforms. NuTek Natural Ingredients represents the taste-engineering specialist archetype with patented bitter-blocker capabilities. These three anchors illustrate how competitive positioning stratifies across raw material control, clean-label technology, and sensory science investment.
| Leading Market Players |
|---|
| Cargill |
| Tate & Lyle |
| NuTek Natural Ingredients |
| Jungbunzlauer |
| Koninklijke DSM |
| Innophos Holdings |
| Sensient Technologies |
| K+S Kali GmbH |
| Angel Yeast |
| Others |
Value Network & Pricing Analysis
Premium-to-commodity formulation gaps widen across mineral composition tiers, with patented bitter-blocker technologies commanding substantial markups over standard potassium chloride while agricultural supply chain control determines baseline cost floors. FDA sodium reduction targets and EFSA health claims procedures compress buyer timelines, forcing food manufacturers into long-term offtake contracts that lock in volume commitments ahead of spot market volatility.
Pricing Analysis
Yield-based pricing anchors premium mineral salt formulations, with food manufacturers paying premiums proportional to sodium reduction efficacy demonstrated through documented compositional changes. Three-tier pricing structure across premium, standard, and economy levels separates patented taste-engineered blends from commodity potassium chloride and unbranded agricultural byproducts. Cost compression in commodity tiers intensifies because fertilizer market fluctuations transmit directly into agricultural potassium chloride feedstock costs. Private label procurement teams at major retail chains exhibit highest price sensitivity, while health care institutions with mandatory nutrition standards accept premium positioning for clinically substantiated electrolyte profiles.
Supply Chain Analysis
Return flows of expired or off-specification mineral salts feed back into agricultural fertilizer channels, creating circular recovery economics that stabilize input cost baselines for integrated processors. Supply concentrates across the United States, Canada, and Germany, with Prairie agricultural regions and Baden-Württemberg fermentation facilities anchoring regional production clusters. Raw material flows draw from potash mining operations, yeast fermentation biomass, and magnesium sulfate chemical processing streams. Single-source vulnerability runs through concentrated potassium chloride purification infrastructure controlled by agricultural commodity processors. Distribution runs through multi-year reformulation partnerships negotiated by centralized retail category managers rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-side capacity for taste-engineered mineral formulations lags demand acceleration from front-of-pack labeling mandates, propping premium tier pricing and extending contract backlogs for validated suppliers.
For Market Incumbents: Anticipate retail buyer consolidation by securing multi-year reformulation partnerships before centralized procurement locks out secondary suppliers. Backward integration into yeast-derived flavor modulator production defends margin position against fermentation technology specialists capturing clean-label premiums. Capacity addition in Baden-Württemberg biotechnology clusters reinforces European regulatory compliance advantages as EFSA tightens novel food assessment timelines. For New Entrants and Emerging Players: Direct-to-consumer subscription channels bypass slotting fee barriers erected by consolidated retail category managers, offering immediate market access without private label procurement gatekeepers. Health care institutional procurement in the United States presents the most penetrable segment, with mandatory sodium reduction standards creating bulk contract opportunities absent entrenched supplier relationships. Taste-engineered sachet formats for foodservice channels provide a specific go-to-market angle leveraging portion control precision requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by agricultural commodity processors seeking taste-engineering capabilities to defend volume positions against biotechnology platform competitors. Long-term viability favors mineral engineering specialists with patented receptor modulation intellectual property and documented clinical substantiation investments. The signal to watch is EFSA approval velocity for novel food applications, which indicates which formulation platforms will capture shelf space from commodity suppliers lacking regulatory dossiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flavor Modulator Production | Captive supply of yeast-derived taste technologies insulates margin from biotechnology platform pricing power. |
| Clinical Trial Investment for Health Claims Substantiation | Documented blood pressure reduction endpoints satisfy EFSA evidentiary standards for premium shelf placement. |
| Multi-Year Reformulation Partnership Negotiation | Locked volume commitments with Walmart, Kroger, or Albertsons preempt competitor access to consolidated retail channels. |
| Stainless Steel Line Infrastructure Upgrade | Corrosion-resistant handling systems enable hygroscopic potassium chloride blend production without legacy equipment retrofit delays. |
| Direct-to-Consumer Channel Launch | E-commerce platforms bypass retail slotting fees and capture household segment margin otherwise surrendered to category managers. |
Research Methodology
Document review covered FDA sodium reduction target documentation, EFSA health claims guidance updates, and Health Canada front-of-pack labeling regulations, complemented by interviews with food manufacturer R&D directors, retail category buyers, mineral salt procurement leads, and sensory science specialists. Secondary validation drew from customs and trade data for potassium chloride flows, SEC filings of agricultural processors, and organic certification databases. Bottom-up demand modeling from end-use consumption patterns and top-down supply capacity assessments triangulated market sizing.
Segment-level value outputs across product type, application, end user, and packaging format dimensions fed into analytical framework projections over the analysis window. CAGRs were derived from regression analysis of historical mineral salt pricing against agricultural commodity indices and regulatory implementation timelines. Forecast inputs incorporated reformulation partnership announcement tracking and front-of-pack labeling mandate phase-in schedules.
The model holds under stable agricultural commodity price regimes and consistent regulatory enforcement intensity; deviation in fertilizer market volatility or EFSA novel food assessment throughput would shift supplier margin distributions. Practitioners should monitor Health Canada and UK Food Standards Agency warning symbol implementation rates for early signals of reformulation demand acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Calcium Inosinate Market
Food Additives and Ingredients
Wine Fining Agent Market
Food Additives and Ingredients
Global Organic Feed Additives Market
Food Additives and Ingredients
Beverage Clarifier and Stabilizer Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
Food Glazing Agents Market
Food Additives and Ingredients
Baking Enzymes Market
Food Additives and Ingredients
Global Food Bulking Agents Market
Food Additives and Ingredients
Food Coating Ingredients Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
Japan Food Emulsifiers Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
Bakery Release Agents Market