
 Horseradish Sauce Market | 2026-2036
Horseradish Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Horseradish Sauce Market Foresight
Specialized agricultural labor for horseradish root cultivation is rotating toward contracted growing operations in the Midwest and Pacific Northwest, tightening supply flexibility for processors. Silver Spring Foods leverages its vertically integrated root-to-retail pipeline to secure raw material consistency. H. J. Heinz Company anchors broad retail shelf presence through multi-channel distribution networks. Beaverton Foods differentiates with Pacific Northwest sourcing credentials and craft positioning in specialty stores.
Horseradish sauce is a prepared condiment manufactured from grated Armoracia rusticana root combined with vinegar, salt, and stabilizers, with pungency measured by allyl isothiocyanate concentration typically preserved through cold processing. The product serves primarily as a flavor adjunct for proteins, sandwiches, and prepared meals across commercial and consumer channels. Prepared Horseradish dominates volume due to its versatility across restaurant and retail applications, while Creamy Horseradish captures expanding placement in food service portion-control formats. Pouch packaging is gaining traction in food processing channels where waste reduction and line efficiency matter, though glass Jars still command premium retail positioning.
FDA oversight of acidified food regulations shapes thermal processing requirements and pH control protocols for domestic manufacturers. USDA grading standards for condiment quality influence procurement specifications from institutional buyers. The EU Food Information to Consumers regulation impacts labeling for exported products, particularly allergen declarations and origin statements. Stakeholders must monitor evolving clean-label expectations alongside root supply volatility driven by climate-sensitive growing windows.
Market Dynamics
Contracted growing operations in the Midwest and Pacific Northwest are tightening supply flexibility for processors, forcing manufacturers to lock in multi-year root supply agreements ahead of climate-sensitive planting windows.
Growth Catalysts
- Steakhouse dining expansion:Full-service restaurants across the United States are broadening menu applications for prepared horseradish and creamy variants, sustaining category loyalty through protein-centric plating.
- FDA acidified food regulations:Thermal processing requirements and pH control protocols are standardizing manufacturing quality, raising barriers that favor established processors with validated protocols.
- Pouch packaging adoption:Food processing channels are prioritizing waste reduction and line efficiency, driving format innovation that reduces material costs versus traditional glass.
Market Restraints
- Root supply volatility:Climate-sensitive growing windows for Armoracia rusticana concentrate production in specific microclimates, exposing processors to yield variability.
- Specialized agricultural labor scarcity:Contracted growing operations face recruitment challenges for root harvesting expertise, limiting supply elasticity during demand spikes.
- EU Food Information to Consumers regulation:Allergen declaration and origin statement requirements add compliance overhead for exported products, creating friction for smaller manufacturers lacking regulatory infrastructure.
Strategic Opportunities
- Clean-label formulation:Consumer preference for minimal ingredient decks creates white space for vinegar-forward recipes with reduced stabilizer loads.
- Food service portion-control formats:Single-serve creamy horseradish packets are penetrating institutional channels where waste reduction drives procurement decisions.
- Pacific Northwest sourcing credentials:Volcanic soil provenance and craft positioning unlock premium placement in specialty retail channels.
Industry Challenges
- Allyl isothiocyanate preservation expertise:Cold processing competency for pungency retention requires specialized equipment and technical knowledge that concentrates among legacy processors.
- Multi-jurisdiction labeling compliance:Simultaneous adherence to FDA acidified food rules, USDA grading standards, and EU allergen protocols strains quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horseradish Sauce Market |
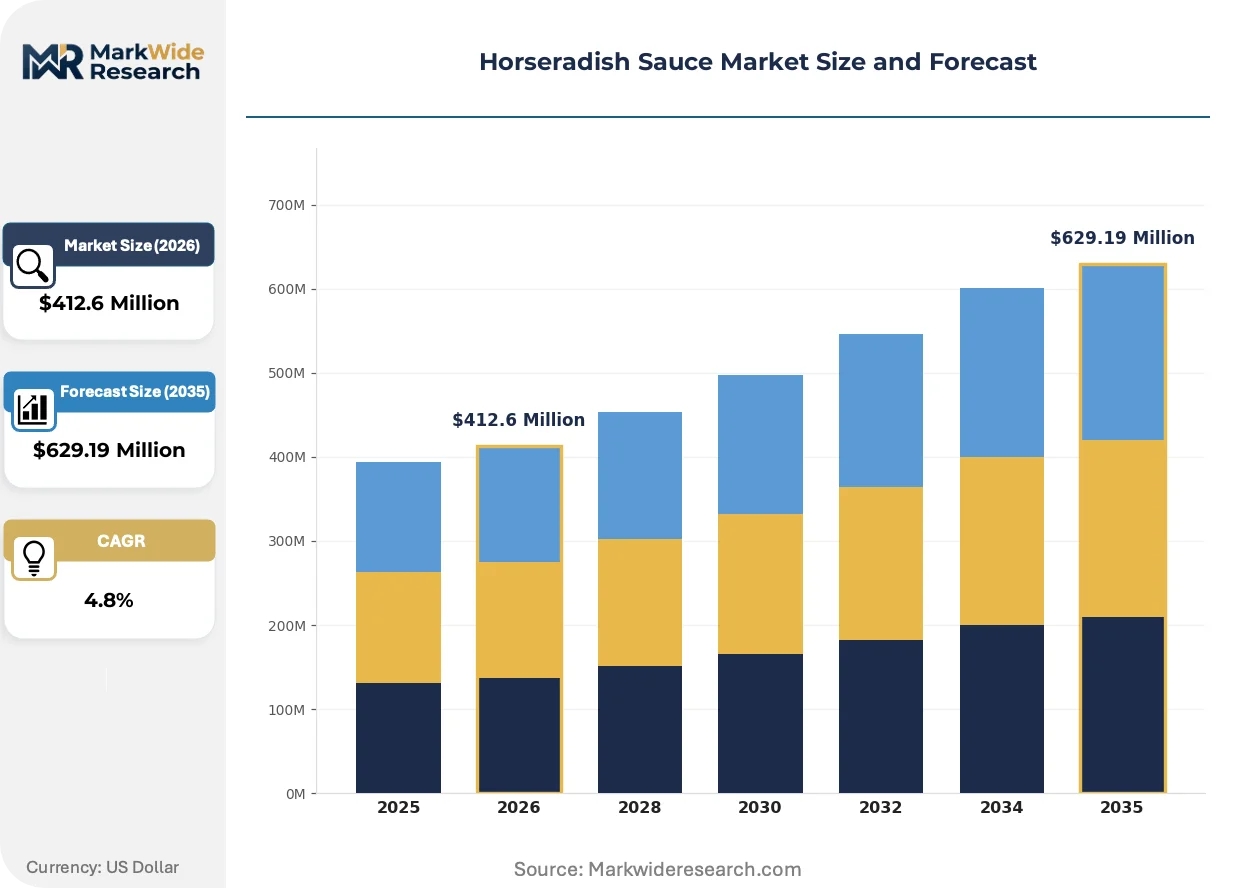
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepared Horseradish, Creamy Horseradish, Hot Sauce, Dressing End User: Restaurants, Food Processing, Retail, Food Service Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale Packaging Type: Bottles, Jars, Pouches, Bulk Containers |
| Companies Covered | Silver Spring Foods, H. J. Heinz Company, Unilever, Beaverton Foods, Woeber Mustard Company, Dietz & Watson, Gold's Pure Foods, Tulkoff Food Products, The Tracklement Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horseradish Sauce Market Shifts & Advancements
Cold processing technology and packaging format innovation are compressing traditional manufacturing economics while regulatory disclosure requirements reshape competitive positioning across export markets.
High-pressure cold processing for allyl isothiocyanate retention is displacing conventional thermal pasteurization in premium segments. Specialty sauce manufacturers are adopting these systems to preserve volatile sulfur compounds that define pungency. The technology is displacing older heat-based methods that degrade flavor intensity, forcing mid-tier processors to invest or cede premium positioning.
EU Food Information to Consumers regulation is tightening origin statement requirements for condiment exports. Manufacturers must now document root provenance across multi-source supply chains. Prepared horseradish variants with blended sourcing face the steepest compliance burden, prompting some processors to consolidate suppliers.
Direct procurement relationships between restaurant chains and root processors are shortening traditional distribution hierarchies. Steakhouse operators are negotiating captive supply agreements that bypass conventional foodservice distributors. This pattern concentrates most visibly in the United States, where condiment specification authority has shifted from distributors to corporate culinary teams.
Horseradish Sauce Market Segmentation
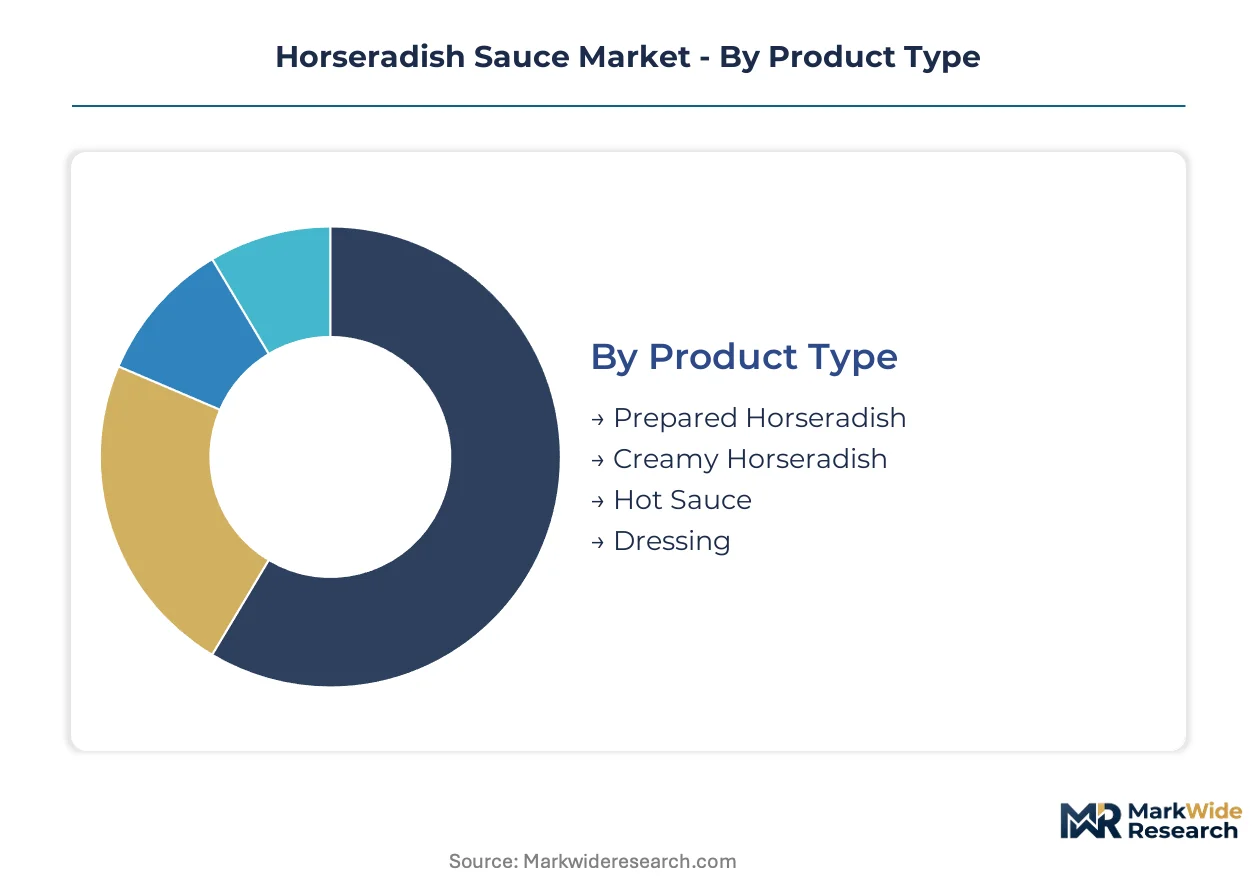
Horseradish sauce segmentation reveals distinct vulnerability profiles across product formats and channel exposures. Each category carries unique substitution threats from adjacent condiment categories and alternative flavor delivery systems.
Product Type:
Substitution pressure concentrates most intensely in commodity formats where mayonnaise-based and mustard alternatives compete directly on price and menu placement.
- Prepared Horseradish:A coarse-grained condiment combining grated Armoracia rusticana root with vinegar and salt, typically 25-30% solids content. Demand concentrates in United States steakhouse chains where protein-centric plating sustains specification loyalty despite mustard and wasabi substitution threats. Labor-intensive harvesting and climate-sensitive root supply create procurement bottlenecks that favor processors with captive growing contracts.
- Creamy Horseradish:An emulsified variant incorporating dairy or oil-based carriers to reduce pungency intensity and extend application versatility. Food service portion-control formats in institutional channels drive fastest adoption, with single-serve packets penetrating corporate dining and healthcare segments where waste reduction dictates procurement.
- Hot Sauce:Capsicum-based alternatives that compete for heat-forward menu positioning, particularly in younger demographic segments and casual dining formats seeking bolder flavor profiles.
- Dressing:Pourable formulations targeting salad and sandwich applications, facing direct competition from ranch and vinaigrette categories with broader consumer familiarity.
Prepared Horseradish retains volume leadership; Creamy Horseradish holds the steepest expansion curve.
End User:
Margin structure varies sharply across customer types, with specification authority increasingly concentrated in corporate culinary teams rather than distributor intermediaries.
- Restaurants:Full-service establishments across the United States specify prepared and creamy variants for protein accompaniment, with steakhouse chains negotiating direct root supply agreements that bypass conventional foodservice distribution hierarchies.
- Food Processing:Industrial buyers purchasing bulk formats for prepared meal incorporation, prioritizing allyl isothiocyanate consistency and cold processing documentation for quality assurance protocols.
- Retail:Consumer packaged goods channels where glass jar presentation commands premium positioning and pouch formats gain traction in value-oriented segments.
- Food Service:Institutional feeding operations including healthcare, education, and corporate dining where portion-control packaging and inventory efficiency drive procurement decisions.
Restaurants anchor revenue concentration; Food Processing demonstrates the most rapid specification evolution.
Distribution Channel:
Channel cost economics are restructuring around direct procurement relationships that compress traditional distribution markups.
- Online:E-commerce platforms capturing specialty and craft-format demand, particularly for Pacific Northwest provenance products with volcanic soil credentials.
- Supermarkets:Mass retail placement dominated by multi-brand portfolios with broad shelf presence, where FDA acidified food compliance documentation influences listing decisions.
- Specialty Stores:Premium retail channels emphasizing craft positioning and regional sourcing stories, with EU Food Information to Consumers regulation compliance enabling export-relevant assortment.
- Wholesale:Traditional foodservice distribution facing margin compression as restaurant chains consolidate procurement authority at corporate level.
Supermarkets maintain volume dominance; Online channels exhibit the most rapid share accumulation.
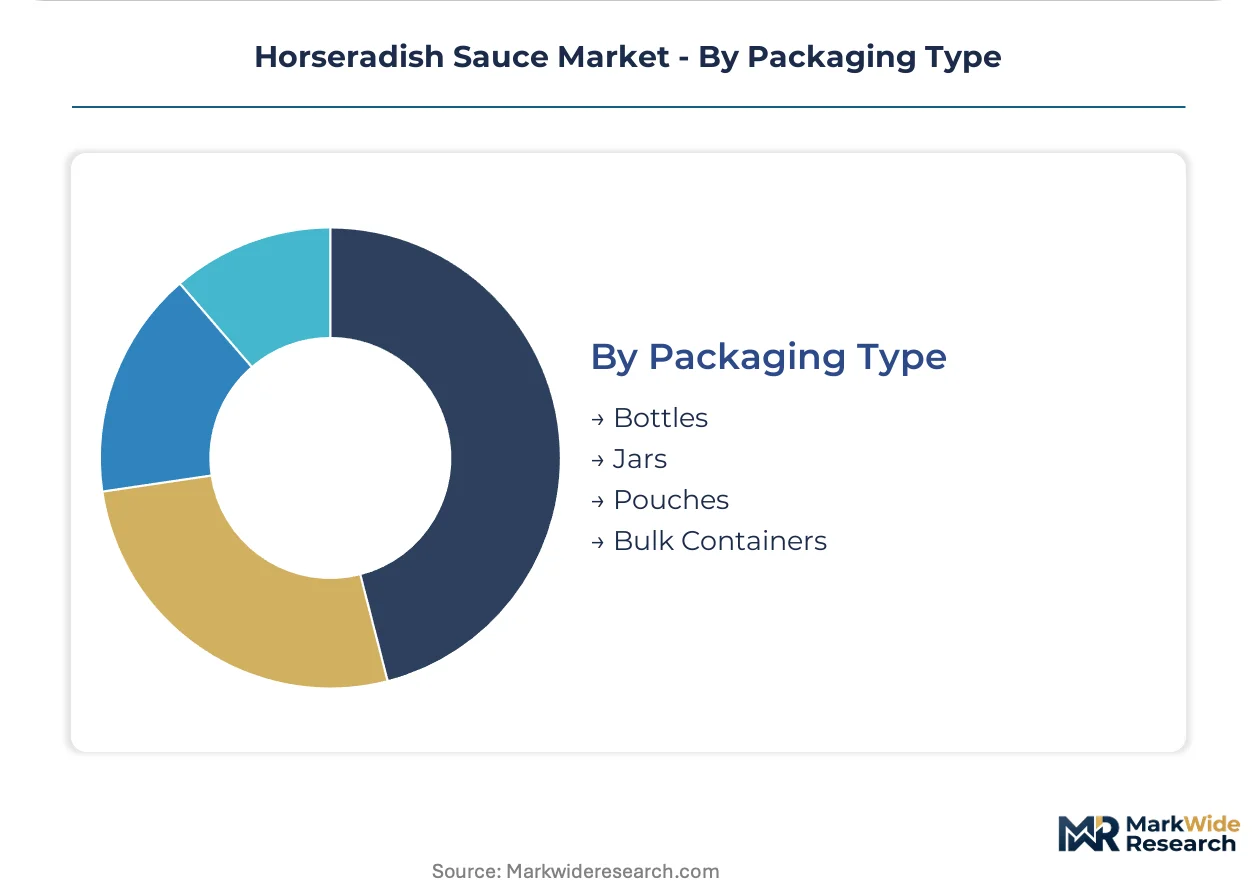
Packaging Type:
Format selection directly determines shelf positioning, shipping economics, and line efficiency for downstream customers.
- Bottles:Squeeze-format polyethylene containers targeting food service and retail convenience segments, offering portion control and reduced contamination risk versus open-jar alternatives.
- Jars:Glass containers commanding premium retail positioning and supporting extended shelf stability through hermetic sealing, though material costs and shipping weight constrain food service adoption.
- Pouches:Flexible film formats penetrating food processing and institutional channels where waste reduction and line efficiency priorities outweigh traditional presentation requirements.
- Bulk Containers:Industrial totes and drums serving food processing customers with validated cold chain protocols and high-volume consumption patterns.
Jars sustain premium positioning; Pouches are climbing the fastest across food service adoption curves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA acidified food regulations anchor the United States market, while EU Food Information to Consumers standards reshape European export compliance. Contracted growing operations concentrate in specific microclimates across both continents.
United States
Steakhouse dining chains and condiment culture sustain prepared horseradish demand across full-service restaurants. FDA thermal processing requirements and pH control protocols standardize manufacturing quality for domestic producers. Midwest growing operations in Illinois and Wisconsin concentrate root cultivation expertise, with processors locking multi-year supply agreements ahead of climate-sensitive planting windows.
Germany
Food processing channels prioritize allyl isothiocyanate consistency for prepared meal incorporation across industrial buyers. EFSA condiment safety assessments influence thermal processing documentation requirements for imported products. Bavaria and Baden-Württemberg anchor specialty retail distribution networks, with craft-positioned variants gaining placement in premium grocery channels.
United Kingdom
Sandwich and protein accompaniment applications drive retail demand for creamy horseradish variants in consumer packaged goods. FSA allergen declaration protocols align with evolving EU labeling standards for condiment exports. London and Southeast England concentrate foodservice procurement authority, with corporate culinary teams negotiating direct root supply agreements.
Canada
Cross-border supply chain integration links Canadian retail channels to United States manufacturing capacity for prepared horseradish. Health Canada food safety standards govern acidified condiment imports and domestic production requirements. Ontario and Quebec anchor mass retail distribution, with pouch format adoption accelerating in food processing channels.
France
Gourmet positioning and volcanic soil provenance marketing unlock premium placement in specialty retail channels for imported variants. ANSM food additive oversight shapes stabilizer disclosure requirements for condiment formulations. Île-de-France concentrates import distribution infrastructure, with Paris-based distributors consolidating procurement for national retail networks.
Horseradish Sauce Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the horseradish sauce market. Vertically integrated root-to-retail pipelines secure raw material consistency for established processors, while mid-tier competitors rely on contracted growing operations with limited supply flexibility. Three archetypes dominate: legacy processors with cold processing expertise, multi-brand condiment conglomerates with broad retail shelf presence, and craft-positioned specialists with regional sourcing credentials. Competitive moves concentrate on backward integration into root supply and format innovation in pouch packaging for food service channels.
Among United States-based processors, Silver Spring Foods exemplifies the vertically integrated archetype with captive growing operations, while H. J. Heinz Company anchors the multi-brand conglomerate tier through mass retail distribution networks. Beaverton Foods occupies the craft-specialist position with Pacific Northwest sourcing credentials and specialty store placement.
| Leading Market Players |
|---|
| Silver Spring Foods |
| H. J. Heinz Company |
| Unilever |
| Beaverton Foods |
| Woeber Mustard Company |
| Dietz & Watson |
| Gold's Pure Foods |
| Tulkoff Food Products |
| The Tracklement Company |
| Others |
Supply & Pricing Matrix
Ninety-day root inventory cycles in Midwest processing facilities concentrate pricing power among vertically integrated operators with captive growing contracts, while spot-market dependent manufacturers absorb yield volatility through margin compression. This inventory-to-pricing linkage tightens whenever climate-sensitive planting windows contract, forcing processors to lock multi-year supply agreements at premiums that cascade through foodservice and retail tiers.
Pricing Analysis
Geographic price spreads between Pacific Northwest volcanic-soil provenance and Midwest commodity grades run 15-40 percent at specialty retail, compressing to single digits in institutional foodservice where specification authority has shifted to corporate procurement teams. Three-tier pricing structure across premium craft-positioned, standard commercial-grade, and economy private-label levels dominates the category, with differentiation anchored in cold processing documentation and allyl isothiocyanate retention certification. Cost compression in mid-tier prepared horseradish is intensifying because pouch packaging adoption and direct restaurant chain procurement are bypassing traditional distributor markups. Food processing buyers exhibit highest price sensitivity due to bulk volume leverage and validated alternative sourcing, while steakhouse chains with specification loyalty demonstrate lowest sensitivity.
Supply Chain Analysis
The United States and Germany anchor horseradish root cultivation and processing capacity, with Illinois, Wisconsin, and Bavaria concentrating climate-adapted growing expertise and cold processing infrastructure. Root supply draws from Armoracia rusticana cultivation in volcanic soil microclimates and alluvial plains, with vinegar sourcing tethered to regional fermentation capacity and stabilizer inputs dependent on specialty chemical suppliers. Single-source vulnerability concentrates in contracted growing operations where multi-year agreements limit supply elasticity during demand spikes. Distribution runs through compressed hierarchies where direct procurement relationships between restaurant chains and root processors are displacing conventional foodservice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Horseradish sauce procurement is consolidating around platform economics as direct restaurant-to-processor agreements and cold processing documentation standards create interoperability barriers that favor integrated operators over fragmented spot-market competitors.
For Market Incumbents: Compound backward integration into captive root supply through multi-year growing contracts in Illinois and Wisconsin microclimates, locking climate-adaptive cultivation ahead of planting window contraction. Invest in high-pressure cold processing equipment to preserve allyl isothiocyanate retention certification that defends premium positioning against wasabi and mustard substitution threats in steakhouse specification battles. For New Entrants and Emerging Players: FDA acidified food compliance fast-track offers entry pathway through validated thermal processing protocols that satisfy institutional buyer quality assurance requirements. Target food service portion-control formats in healthcare and corporate dining segments where waste reduction priorities override brand loyalty, leveraging pouch packaging innovation to bypass entrenched glass jar shelf presence. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification authority concentration and regulatory compliance overhead are compressing viable processor counts toward vertically integrated archetypes with root-to-retail pipelines. Acquisition targets should concentrate on Midwest processors with locked growing contracts and cold processing documentation capabilities. Signal to watch is direct procurement agreement announcements between top-ten restaurant chains and root processors, indicating distributor displacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Root Supply | Captive growing contracts in Illinois and Wisconsin microclimates secure climate-adaptive raw material consistency against yield volatility. |
| Cold Processing Certification Investment | High-pressure allyl isothiocyanate retention systems defend premium positioning against thermal-degradation competitors in steakhouse channels. |
| Pouch Packaging Format Expansion | Flexible film adoption in foodservice and institutional channels captures waste-reduction procurement priorities from healthcare and corporate dining operators. |
| Direct Restaurant Chain Procurement | Bypassing conventional distributor hierarchies concentrates margin capture with corporate culinary teams specifying proprietary formulations. |
| EU Food Information Compliance Infrastructure | Allergen declaration and origin statement documentation enables export-relevant assortment placement in premium European specialty retail channels. |
Research Methodology
Cross-validation between primary interviews with condiment procurement directors, foodservice distribution executives, and root cultivation specialists anchors the qualitative findings, while secondary validation draws from FDA acidified food regulation filings, USDA grading standard documentation, EU Food Information to Consumers regulatory texts, and customs trade data for Armoracia rusticana root imports. Bottom-up volume modeling from processor capacity and growing contract disclosures triangulates against top-down category spend analysis across restaurant, retail, and food processing channels.
Sensitivity analysis across root yield scenarios, regulatory compliance cost trajectories, and substitution elasticity parameters shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include product type tier, end-user channel, packaging format, and regional regulatory cluster, with CAGRs derived from trend-line extrapolation of specification evolution and procurement pattern shifts. Cold processing technology adoption curves and direct procurement agreement penetration rates serve as industry-specific forecast inputs.
Underlying assumptions cover climate-stable growing windows, sustained steakhouse dining demand concentration, and regulatory compliance cost trajectories, with deviation risk concentrated in root supply volatility from extreme weather events and accelerated distributor displacement from restaurant chain consolidation. Recalibration cycles align with material shifts in FDA acidified food enforcement patterns, EU labeling regulation amendments, and direct procurement agreement announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Hot Sauce Powder Market
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
Tomato Ketchup Market
Condiments & Sauces
Global Hot Pot Condiment Market
Condiments & Sauces
Oyster Sauce Market
Condiments & Sauces
Sugar Toppings Market
Condiments & Sauces
Vegan Sauces Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
Barbecue Sauce Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
Pasta Sauce Market
Condiments & Sauces
Sour Dressings Market
Condiments & Sauces
Mayonnaise Market