
 Curry Cube Market | 2026-2036
Curry Cube Market Size, Share, and Industry Trends Forecast 2026-2036
Curry Cube Market Insights
Multi-source spice procurement is realigning how curry cube manufacturers secure raw materials across volatile turmeric and coriander markets. House Foods leverages long-term contracts with Indian spice cooperatives to stabilize input costs. S&B Foods sustains its competitive edge through specialized blending facilities in Japan that preserve volatile oil profiles. McCormick & Company anchors its supply chain through backward integration into Sri Lankan cinnamon estates, reducing exposure to commodity price swings.
Curry cubes represent dehydrated, compressed seasoning blocks composed of flour, fats, spices, and flavor enhancers that reconstitute into sauce bases upon heating with water. The manufacturing process involves low-temperature drying to preserve aromatic compounds, followed by hydraulic pressing into standardized cube geometries for portion control. Vegetarian variants command premium shelf positioning in European retail channels where plant-based dietary adherence is expanding. Sachet packaging dominates emerging-market penetration due to lower unit economics and reduced breakage rates during last-mile distribution. The food service end-user segment generates concentrated volume orders, though household channels deliver superior margin retention through branded retail pricing.
FDA oversight of color additives and GRAS flavoring substances directly impacts formulation choices for curry cubes sold in United States commerce. Japan's Food Sanitation Act and corresponding JIS labeling standards govern shelf-life claims and allergen declarations for domestic manufacturers. India's FSSAI mandates maximum permissible limits for synthetic food colors in spice mixes, compelling reformulation of legacy recipes. Stakeholders must monitor evolving sodium-reduction mandates across multiple jurisdictions, as salt content becomes a focal point for processed food regulation.
Market Dynamics
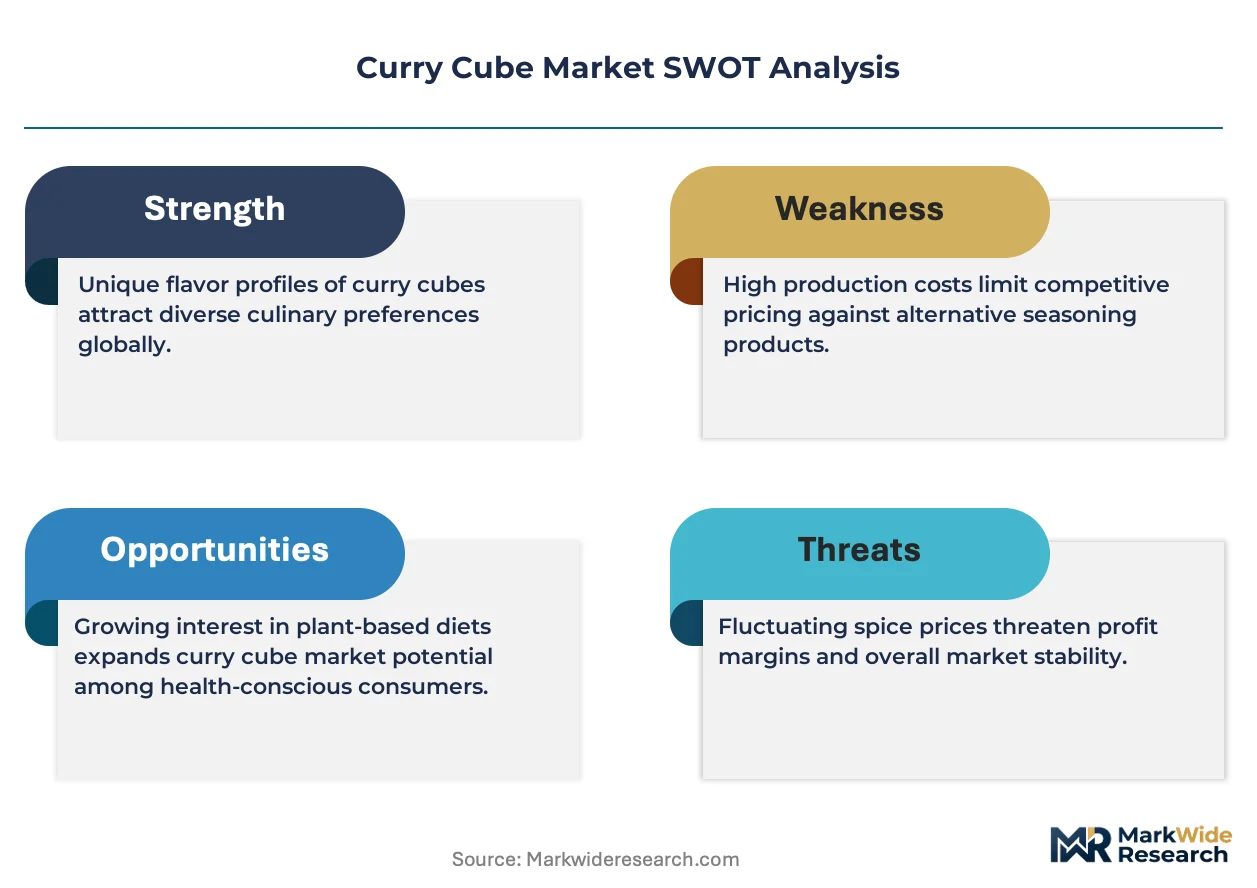
Curry cube manufacturers face intensifying pressure from sodium-reduction mandates across multiple jurisdictions, forcing wholesale reformulation of legacy recipes while preserving the umami profiles that define category identity. This regulatory compression is reshaping R&D priorities and supplier relationships simultaneously.
Growth Catalysts
- FSSAI synthetic color limits:India's tightening restrictions on artificial additives in spice mixes are accelerating clean-label innovation, opening premium positioning for natural-extract formulations.
- Food service automation:Central kitchen adoption across Southeast Asian restaurant chains is standardizing curry cube procurement at volume scale.
- Volatile oil preservation:Advanced low-temperature drying technologies are extending aromatic shelf stability, reducing spoilage losses in tropical distribution.
Market Restraints
- Turmeric-coriander price volatility:Concentrated Indian spice cooperative sourcing creates margin compression when monsoon disruptions hit the Deccan Plateau.
- Japan Food Sanitation Act compliance:Stringent JIS labeling and additive approval timelines extend product launch cycles by 8-14 months versus other Asian markets.
- Fresh curry paste substitution:Refrigerated wet formats in Thai and Vietnamese retail are capturing convenience-seeking households willing to trade shelf stability for perceived authenticity.
Strategic Opportunities
- European plant-based certification:V-Label and EU organic standards are creating premium shelf positioning for coconut milk-based vegetarian cubes in German and Dutch retail.
- Sachet format penetration:Single-serve foil pouches are unlocking rural Indian distribution through kirana store networks where cube breakage rates previously excluded the category.
- Sri Lankan cinnamon backward integration:Captive estate ownership is insulating select manufacturers from Ceylon cinnamon price spikes driven by export quota fluctuations.
Industry Challenges
- Flavor chemist scarcity:Formulation expertise in natural umami enhancement without MSG reliance is concentrated among aging specialists in Kanagawa and Osaka prefectures.
- Legacy equipment retooling:Hydraulic pressing lines require seven-figure capital outlays to achieve the precision tolerances demanded by automated European packaging lines.
- Cross-border allergen harmonization:Divergent mustard and celery disclosure requirements between Japan's Consumer Affairs Agency and EU FIC regulations complicate unified SKU strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Curry Cube Market |
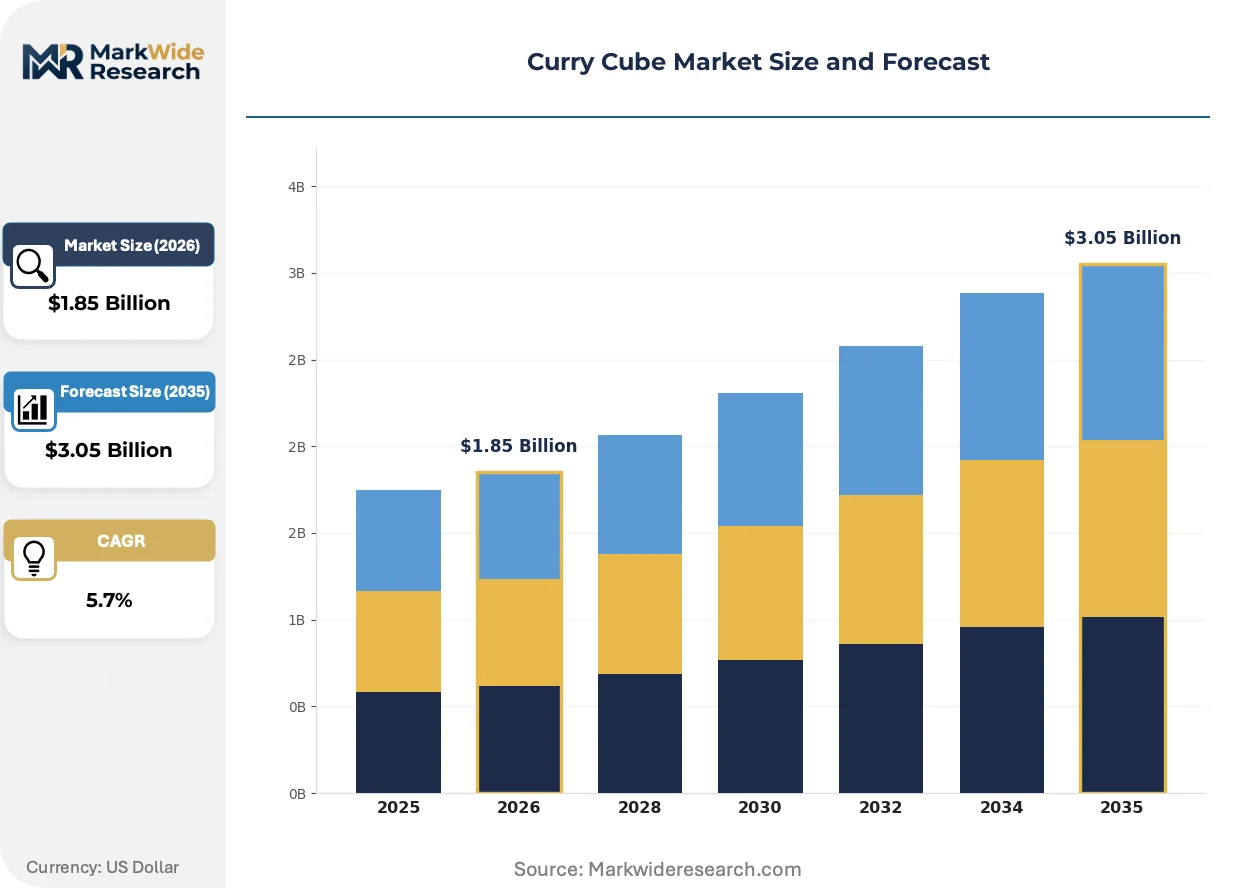
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetarian, Chicken, Fish, Spicy Packaging Type: Box, Bag, Jar, Sachet Distribution Channel: Supermarkets, Online, Specialty Stores, Wholesale End User: Restaurants, Households, Food Service, Caterers |
| Companies Covered | House Foods, S&B Foods, Maggi, Knorr, Shan Foods, MDH, Everest Spices, Glico, McCormick & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Curry Cube Market Trends and Innovations
Electrification of thermal processing and precision fermentation are converging to redefine how curry cubes deliver flavor intensity without sodium dependency. These shifts are compressing traditional extraction timelines while expanding the addressable dietary base.
Precision fermentation-derived kokumi compounds are electrifying clean-label formulation strategies by replicating the mouthfeel depth historically provided by hydrolyzed proteins. Japanese and South Korean manufacturers are integrating these inputs at pilot scale. The technology is compressing the reformulation cycle from 18 months to under 9 months for sodium-reduced variants.
REACH-compliant natural colorant sourcing is forcing European-bound manufacturers to abandon tartrazine and sunset yellow in favor of paprika oleoresin and curcumin extracts. ECHA's 2023 updated safety assessments for azo dyes have triggered supply chain audits across Indian toll processors. German and Dutch retailers are now demanding full pigment traceability back to cultivar level.
Direct-to-restaurant subscription models are fragmenting traditional distributor control in urban Indian markets. Cloud kitchen operators in Bangalore and Mumbai are bypassing cash-and-carry channels entirely, placing consolidated weekly orders through manufacturer portals. This disintermediation is most visible in the QSR segment, where procurement managers prioritize invoice consolidation over credit terms.
Curry Cube Market Segmentation
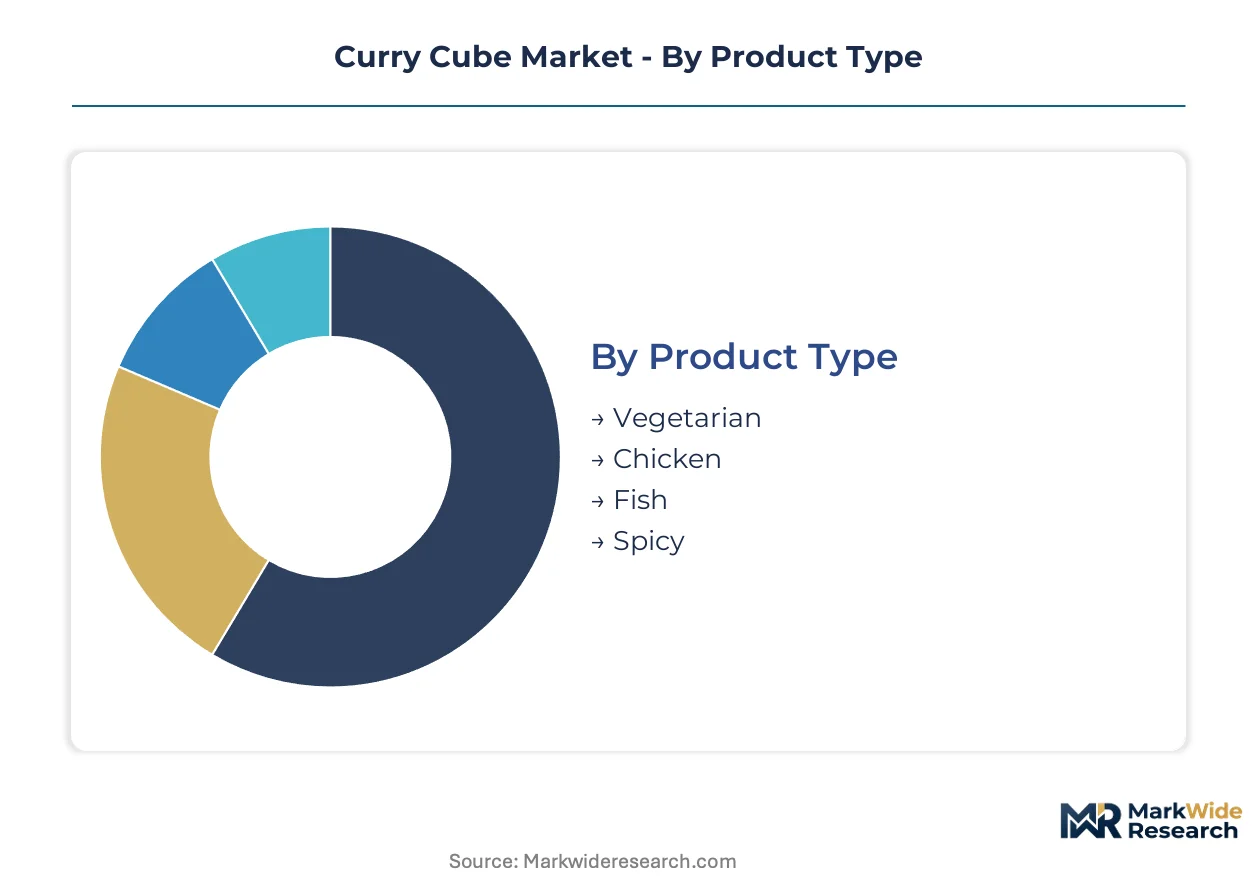
Curry cube segmentation reveals how formulation, packaging, and channel choices map to distinct regulatory burdens and margin structures. Manufacturers must align R&D and compliance investments with the specific requirements of each segment cluster.
Product Type:
Vegetarian variants require V-Label certification for European retail placement, while chicken and fish formulations trigger Japan Consumer Affairs Agency allergen disclosure protocols and FSSAI animal-source verification in India.
- Vegetarian:Coconut milk and palm oil bases replace animal fats to achieve plant-based positioning. European demand concentrates in German and Dutch retail where V-Label certification commands shelf premium and repeat purchase loyalty.
- Chicken:Hydrolyzed poultry protein delivers concentrated umami without MSG reliance. Southeast Asian restaurant chains in Bangkok and Jakarta standardize procurement around this variant for mass-market curry applications.
- Fish:Dried bonito and anchovy extracts provide traditional Japanese curry depth. Compliance with Japan's Food Sanitation Act additive schedules extends formulation timelines versus other protein bases.
- Spicy:Capsicum oleoresin and black pepper formulations target heat-tolerant palates in South India and Sri Lanka.
Leading the category by volume: Chicken. Growing fastest: Vegetarian.
Packaging Type:
Cost tier stratification separates premium jar formats from economy sachets, with breakage rates and unit economics determining rural versus urban penetration strategies.
- Box:Paperboard cartons with foil blister packs dominate Japanese household retail. METI packaging waste regulations drive recyclable material transitions that add per-unit cost.
- Bag:Flexible pouches with resealable zippers capture North American club store volumes. The format sacrifices shelf stability versus rigid alternatives in tropical humidity.
- Jar:Glass containers with twist-lock lids position as gift-tier products in Japanese department store channels. Fragility limits last-mile distribution to urban courier networks.
- Sachet:Single-serve foil laminates unlock rural Indian kirana penetration where cube breakage previously excluded the category.
Lowest unit cost: Sachet. Highest margin retention: Jar.
Distribution Channel:
Channel selection dictates working capital intensity, with supermarkets demanding 90-120 day payment terms versus cash-on-delivery terms in wholesale.
- Supermarkets:Modern trade shelf fees and promotional calendars compress net margins to single digits. EAN barcode and bilingual labeling requirements vary by retail banner.
- Online:Direct-to-consumer platforms in Indian metros bypass distributor markups entirely. Last-mile cold chain requirements apply only to fresh curry paste competitors, giving cubes a logistics advantage.
- Specialty Stores:Ethnic grocery channels in North America and Europe sustain premium pricing for import-labeled Japanese variants.
- Wholesale:Cash-and-carry volumes in Southeast Asia concentrate procurement for independent restaurant operators.
Widest geographic reach: Supermarkets. Fastest order consolidation: Online.
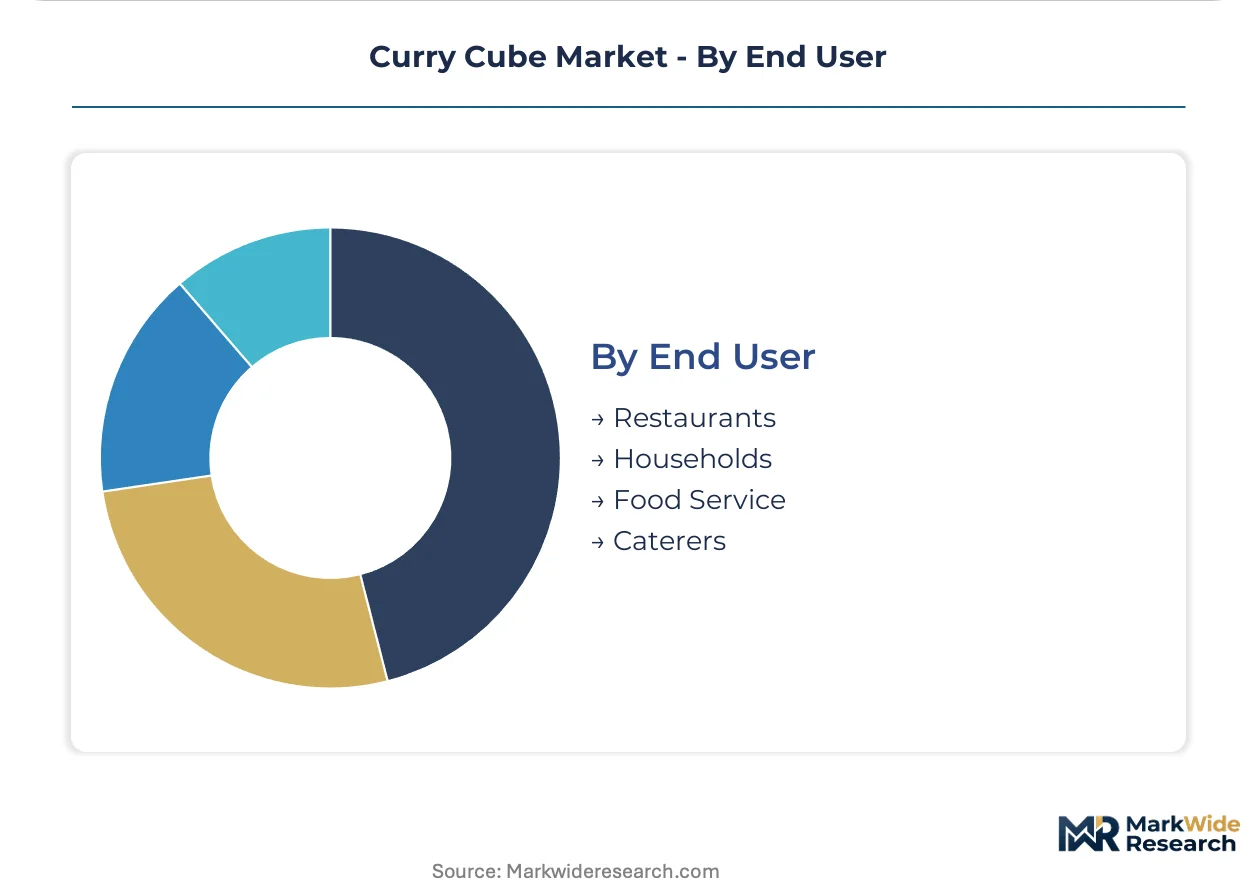
End User:
Customer type determines batch size and formulation specificity, with food service requiring institutional pack sizes and standardized Scoville profiles.
- Restaurants:Central kitchen adoption across Southeast Asian chains standardizes curry cube procurement at 10kg bulk volumes. Consistency specifications override cost minimization in vendor selection.
- Households:Retail pack sizes of 100-200g generate superior margin retention through branded pricing. Indian household cooking traditions sustain the highest per-capita consumption frequency globally.
- Food Service:Institutional caterers and airline meal suppliers demand 1kg blocks with extended ambient shelf stability for inventory flexibility.
- Caterers:Event-based demand in Indian wedding markets concentrates in seasonal procurement patterns with volatile order timing.
Highest volume concentration: Restaurants. Steepest margin structure: Households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turmeric cultivation across the Deccan Plateau anchors raw-material sourcing for curry cube manufacturers worldwide, while processing clusters concentrate in Japan and Thailand where precision blending technology preserves volatile oil profiles.
India
Household cooking traditions in Maharashtra and Gujarat sustain the highest per-capita consumption frequency globally. FSSAI synthetic color limits are accelerating clean-label reformulation among domestic manufacturers. Spice processing clusters in Unjha and Erode concentrate toll manufacturing capacity for export-bound curry cube brands.
Japan
Central kitchen adoption across Tokyo and Osaka restaurant chains standardizes procurement at institutional volumes. METI packaging waste regulations drive recyclable material transitions that add per-unit cost. Kanagawa and Osaka prefectures host concentrated flavor chemistry expertise for natural umami enhancement.
Thailand
Bangkok-based QSR operators are bypassing traditional distributor channels through direct manufacturer portals. The country's national food and drug administration maintains additive approval timelines that extend product launch cycles. Processing facilities in Samut Prakan leverage proximity to refrigerated wet curry paste competitors for format diversification.
Germany
V-Label certification requirements in Berlin and Hamburg retail are creating premium shelf positioning for coconut milk-based vegetarian variants. ECHA's updated safety assessments for azo dyes have triggered supply chain audits across Indian toll processors. German retailers now demand full pigment traceability back to cultivar level.
United States
FDA oversight of color additives and GRAS flavoring substances directly impacts formulation choices for curry cubes sold in domestic commerce. Specialty ethnic grocery channels in California and New York sustain premium pricing for import-labeled Japanese variants. Cloud kitchen operators in Los Angeles and Chicago are consolidating weekly orders through manufacturer-direct portals.
Curry Cube Market Competitive Landscape
Backward integration into captive spice estates dominates the current landscape as manufacturers seek insulation from commodity price volatility. The vendor base spans multinational seasoning conglomerates, regional spice specialists, and Japanese precision-blending houses. Three strategic archetypes have emerged: vertically integrated raw-material owners, formulation-technology specialists, and brand-driven FMCG platforms. M&A activity and geographic licensing partnerships represent the dominant competitive moves as players seek rapid market entry without greenfield facility investment.
Within the Japanese formulation-technology tier, House Foods and S&B Foods exemplify precision-blending capabilities that preserve volatile aromatic compounds through low-temperature processing. Among North American seasoning conglomerates, McCormick & Company occupies a position representing backward integration strategies through estate ownership in key spice origins. These three entities anchor distinct competitive vectors: technology-driven aromatic preservation, supply-chain control through upstream asset ownership, and brand equity in retail channels.
| Leading Market Players |
|---|
| House Foods |
| S&B Foods |
| Maggi |
| Knorr |
| Shan Foods |
| MDH |
| Everest Spices |
| Glico |
| McCormick & Company |
| Others |
Pricing and Supply Chain Analysis
Central kitchen operators across Southeast Asian restaurant chains wield concentrated procurement power that compresses margins on bulk chicken and fish curry cube contracts. This buyer concentration forces manufacturers to absorb input cost volatility while preserving umami profiles through natural extraction methods.
Pricing Analysis
After-sales technical support for flavor calibration and recipe standardization is bundled into premium-tier food service contracts but stripped from economy sachet sales to rural Indian kirana stores. Three-tier pricing structure across premium, standard, and economy levels separates V-Label certified vegetarian variants in German retail from unbranded bulk packs in Southeast Asian wholesale. Price differentiation rests on certification grade and volume scale, with METI-compliant recyclable packaging adding per-unit cost in Japanese household channels. Pricing pressure stems from sodium-reduction R&D investments, with food service buyers exhibiting lowest price sensitivity due to consistency specifications.
Supply Chain Analysis
Return flows of damaged or expired curry cube inventory are minimal given ambient shelf stability, though European retailers are piloting packaging take-back schemes under extended producer responsibility frameworks. Raw material sourcing concentrates in India, Sri Lanka, and Thailand, with turmeric and coriander harvests from the Deccan Plateau feeding global formulation lines. Captive cinnamon estate ownership in Sri Lanka and long-term spice cooperative contracts in Gujarat insulate select manufacturers from commodity price swings. Distribution runs through layered wholesale networks in Southeast Asia, while direct-to-restaurant portals are fragmenting traditional channel control in Indian metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation-derived kokumi compounds are displacing hydrolyzed protein bases in sodium-reduced formulation, compressing R&D timelines and expanding clean-label addressability. This technology transition favors manufacturers with existing fermentation partnerships or in-house biotechnology capabilities.
For Market Incumbents: Deepen backward integration into Sri Lankan cinnamon estates and Indian turmeric cooperatives to lock in volatile oil supply ahead of monsoon-driven price spikes. Invest in Kanagawa and Osaka flavor chemistry talent retention as natural umami expertise concentrates among aging specialists. Defend against fresh curry paste substitution in Thai and Vietnamese retail by accelerating sachet format penetration with breakage-resistant foil laminates. For New Entrants and Emerging Players: Begin with European plant-based certification pathways, where V-Label and EU organic standards create shelf positioning advantages for coconut milk-based vegetarian variants in German and Dutch retail. Target cloud kitchen operators in Bangalore and Mumbai through direct manufacturer portals, bypassing entrenched cash-and-carry distributors. Prioritize sachet format economics to unlock rural Indian kirana networks previously excluded by cube breakage rates. For Investors and Strategic Acquirers: The window for entry favors formulation-technology specialists with precision-blending capabilities in Japan and backward-integrated spice estate owners in Sri Lanka and India. Long-term viability hinges on sodium-reduction compliance across multiple jurisdictions and clean-label certification traction in European retail. Monitor ECHA safety assessment updates for azo dyes and FSSAI synthetic color limit enforcement as regulatory inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spice Estates | Captive Sri Lankan cinnamon and Indian turmeric supply insulates margins from monsoon-driven commodity volatility. |
| Precision Fermentation Partnership | Kokumi compound sourcing from South Korean biotech firms accelerates sodium-reduced formulation cycles below nine months. |
| V-Label Certification Investment | European plant-based standards unlock premium shelf positioning in Berlin and Hamburg retail channels. |
| Sachet Format Manufacturing Scale-Up | Foil laminate production lines penetrate rural Indian kirana stores where rigid cube breakage previously excluded the category. |
| Direct-to-Restaurant Portal Launch | Bangalore and Mumbai cloud kitchen procurement consolidation bypasses traditional distributor markups entirely. |
Research Methodology
Trade databases, FSSAI additive regulation filings, and ECHA safety assessment records formed the secondary backbone of this analysis. Primary interviews with flavor chemists in Kanagawa prefecture, procurement managers at Southeast Asian QSR chains, spice cooperative representatives in Gujarat, and packaging engineers at Japanese toll manufacturers were cross-referenced against customs data and retail audit records. Bottom-up volume modeling and top-down value triangulation were applied across the analysis window.
Bottom-up modeling aggregated unit consumption by packaging format, protein base, and distribution channel, while top-down validation checked aggregate value against import-export flows and manufacturer revenue disclosures. Segmentation dimensions included product type, packaging configuration, distribution channel, and end-user category. CAGRs were derived from trend extrapolation of historical consumption patterns adjusted for regulatory phase-in timelines and technology adoption curves. Sodium-reduction mandate enforcement schedules and precision fermentation scale-up trajectories served as key forecast inputs.
Underlying measurement precision varies by segment; sachet-format rural Indian consumption and direct-to-restaurant online channels carry tighter precision than fragmented wholesale volumes in Southeast Asia. Forecasts reflect assumptions regarding FSSAI clean-label transition pacing and ECHA azo dye restriction timelines. Practitioners should monitor monsoon disruption severity on the Deccan Plateau and cloud kitchen consolidation rates in Indian metros for early signals of supply constraint or channel shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
UK Prepared Mustard Market
Condiments & Sauces
Culinary Sauces Market
Condiments & Sauces
Fat Free Salad Dressings Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Low Fat Spaghetti Sauce Market
Condiments & Sauces
Mayonnaise Sauce Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Sugar Toppings Market
Condiments & Sauces
Pesto Sauces Market
Condiments & Sauces
West Africa Mayonnaise Market
Condiments & Sauces
Compound Condiments Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Europe Pasta Sauce Market
Condiments & Sauces
Organic Condiments Market
Condiments & Sauces
Sweet and Savory Spread Market