
 Low Fat Pasta Sauce Market | 2026-2036
Low Fat Pasta Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Pasta Sauce Market Analytics
Asset-light co-manufacturing arrangements is fragmenting competitive entry barriers across the low fat pasta sauce landscape. Nestlé leverages its refrigerated supply chain infrastructure to maintain shelf-space dominance in premium grocery channels. Kraft Heinz Company anchors its position through backward integration into tomato processing operations in California's Central Valley. Barilla G. e R. Fratelli S.p.A. specializes in Mediterranean formulation heritage, competing on authenticity credentials rather than price positioning.
Low fat pasta sauce denotes tomato-based or cream-based condiments engineered with reduced lipid content, typically achieving less than 3 grams of fat per serving through skim milk substitutions, vegetable puree extensions, or modified starch stabilization systems, designed for calorie-conscious meal preparation in residential and foodservice settings. Marinara formulations occupy the mature volume base, while organic and vegan ingredient certifications command disproportionate margin pools in specialty retail. Pouch packaging is accelerating fastest among convenience-oriented distribution channels, though glass jar formats sustain premium positioning in supermarket perimeter displays.
FDA nutrition labeling mandates and USDA organic certification requirements shape permissible health claims and ingredient disclosure protocols across North American supply chains. EFSA health claim regulations and EU Green Deal agricultural standards govern European market access, with REACH compliance affecting additive formulations. Stakeholders must monitor evolving sodium reduction thresholds and front-of-package warning systems across multiple jurisdictions to anticipate reformulation cycles and label redesign investments.
Market Dynamics
Clean-label reformulation mandates from the FDA and USDA are compressing formulation cycles across the low fat pasta sauce supply chain, forcing manufacturers to replace modified starches with natural thickeners and achieve sodium reduction targets without sacrificing shelf stability.
Growth Catalysts
- FDA Sodium Reduction Targets:Mandatory sodium thresholds in processed foods are pulling reformulation investment toward low fat variants, as manufacturers consolidate SKUs to meet dual health claims.
- Suburban Household Concentration:Health-conscious meal preparation in United States metropolitan corridors is expanding the addressable base for reduced-fat condiments beyond traditional diet segments.
- Pouch Packaging Technology:Flexible barrier films are unlocking convenience-oriented distribution through club stores and direct-to-consumer channels previously inaccessible to glass-dependent formats.
Market Restraints
- Tomato Input Volatility:California Central Valley water allocation uncertainty and processing tomato contract pricing swings are compressing margin stability for sauce manufacturers.
- Natural Thickener Supply Concentration:Guar gum and tapioca starch sourcing depends on concentrated Indian and Thai supplier bases, exposing formulations to geopolitical and climate disruption.
- Clean-Label Shelf-Life Tradeoff:Elimination of synthetic preservatives under USDA organic protocols is shortening distribution windows and raising cold-chain dependency costs.
Strategic Opportunities
- United Kingdom Premium Positioning:EFSA health claim authorization pathways for reduced-fat products remain underexploited by North American exporters relative to domestic European competitors.
- Foodservice White-Label Supply:Contract manufacturing for restaurant chains seeking menu transparency is displacing in-house sauce production across casual dining networks.
- EU Green Deal Agricultural Standards:Compliance with regenerative sourcing requirements is creating preferential access to European retail banners prioritizing carbon-labeled supply chains.
Industry Challenges
- Reformulation Talent Scarcity:Food chemists capable of balancing fat reduction, clean-label compliance, and cost targets command premium compensation in a shallow talent pool.
- Dual Certification Timelines:Simultaneous USDA organic and Non-GMO Project verification processes extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Pasta Sauce Market |
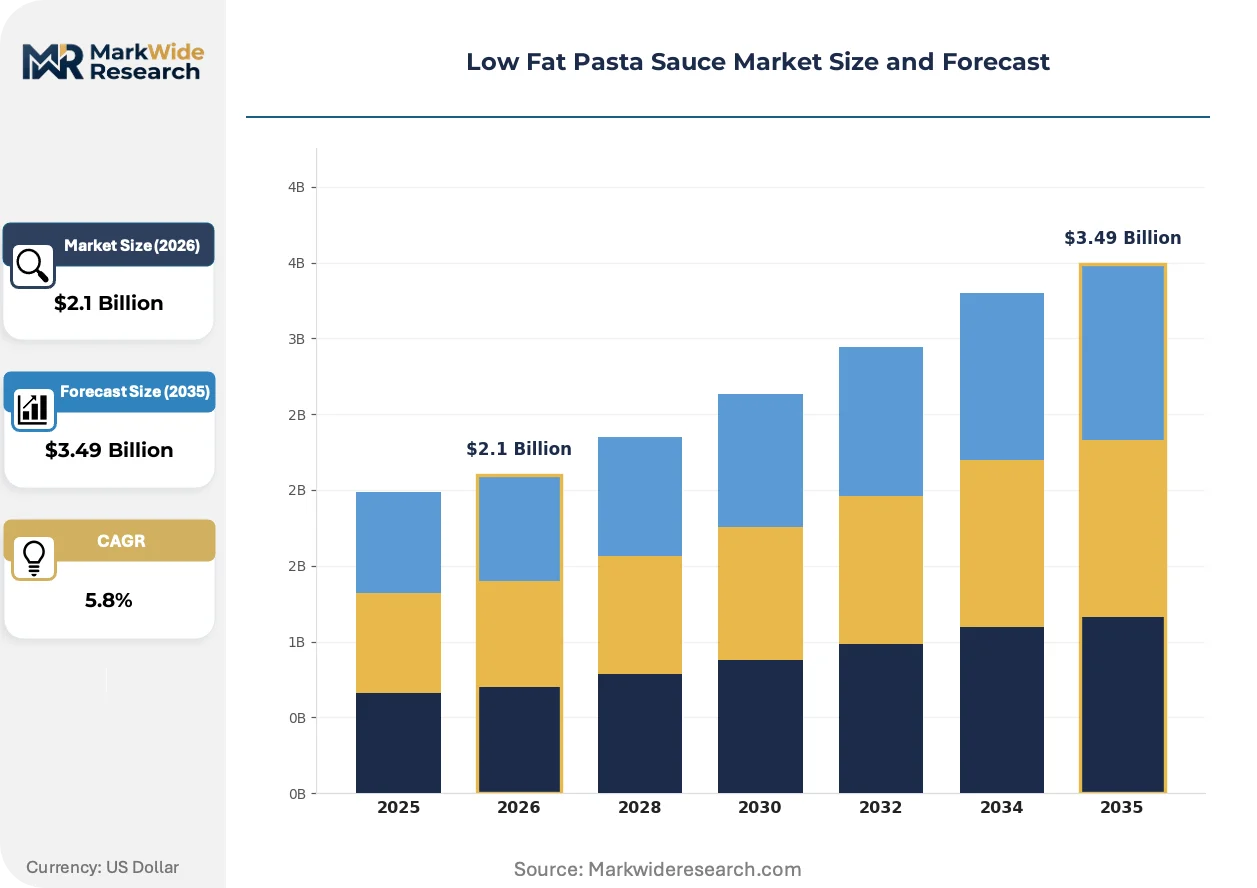
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Marinara, Alfredo, Pesto, Garlic Ingredient Type: Organic, Gluten-Free, Low Sodium, Vegan Packaging Type: Bottle, Jar, Pouch, Can Distribution Channel: Supermarket, Online Retail, Specialty Stores, Distributors |
| Companies Covered | Del Monte Foods, Campbell Soup Company, Kraft Heinz Company, Barilla G. e R. Fratelli S.p.A., Conagra Brands, Nestlé, McCormick and Company, Mizkan Holdings, B and G Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Pasta Sauce Market Evolving Landscape
Formulation science and packaging engineering are converging to redefine competitive advantage in reduced-fat condiments, with natural stabilization systems and sustainable materials displacing legacy approaches.
Vegetable puree extension systems utilizing cauliflower and butternut squash bases are collapsing the fat-replacement cost structure for cream-style sauces. Suburban United States households are adopting these variants at accelerating rates through meal-kit subscription channels. The technology is collapsing the premium pricing umbrella that previously separated low fat from conventional formulations.
REACH compliance requirements for additive transparency are forcing disclosure of processing aids previously treated as proprietary. European manufacturers are reformulating to eliminate titanium dioxide whitening agents ahead of ECHA restriction timelines. The United Kingdom retail channel is responding fastest, with major grocers delisting non-compliant SKUs ahead of regulatory deadlines.
Direct-to-pantry subscription models are fragmenting traditional grocery channel concentration for shelf-stable sauces. United States metropolitan households are bypassing perimeter displays in favor of algorithm-curated replenishment services. This behavioral shift is most visible in coastal urban corridors where delivery density supports cold-chain logistics for refrigerated low fat variants.
Low Fat Pasta Sauce Market Segmentation
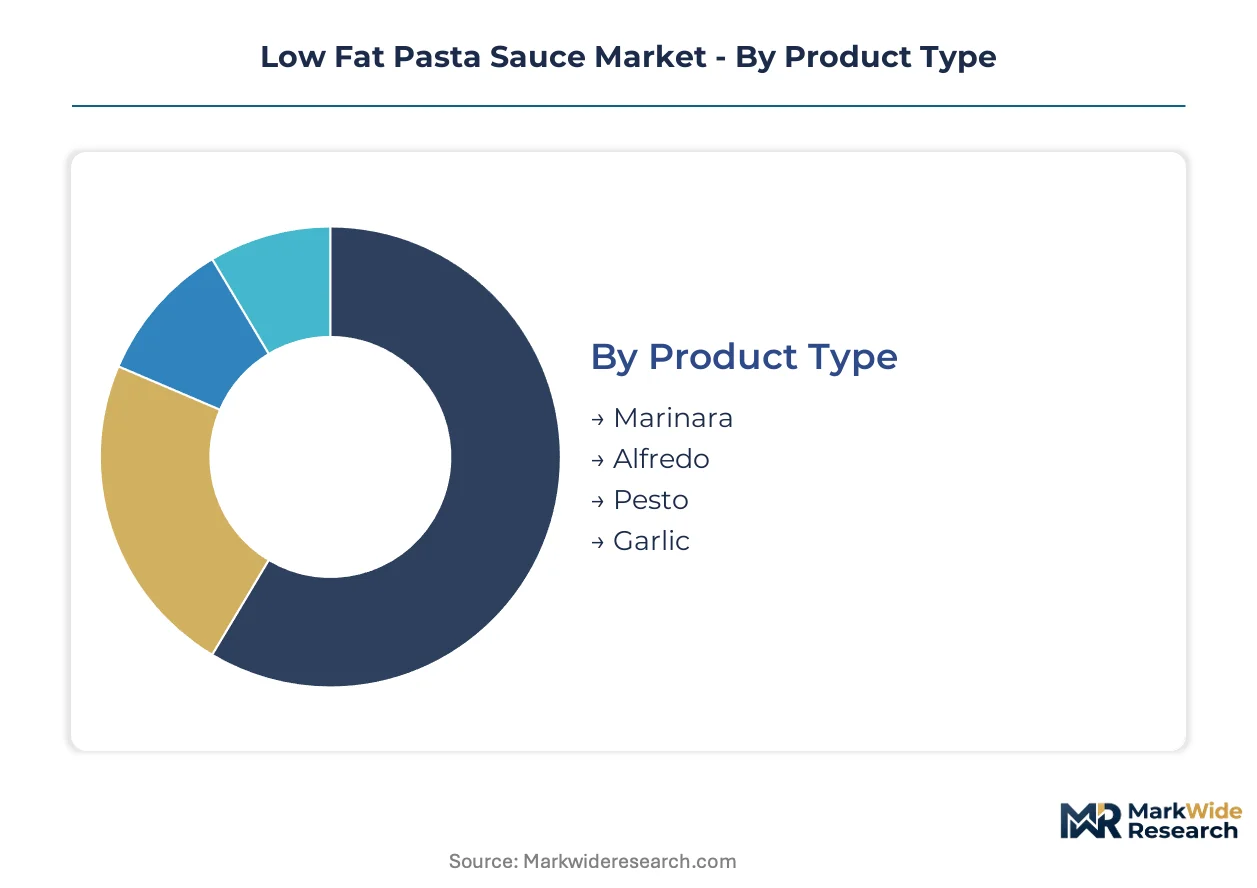
Low fat pasta sauce segmentation reveals how formulation complexity and packaging engineering create distinct margin architectures. Each dimension carries unique supply chain implications and regulatory exposure profiles that reshape competitive positioning across retail and foodservice channels.
Product Type:
After-sales service intensity varies sharply across sauce formats, with cream-based variants demanding refrigerated logistics support and technical troubleshooting that tomato-based lines rarely require.
- Marinara:Tomato-herb formulations with reduced oil content achieve sub-3 gram fat targets through extended vegetable puree bases. Demand concentrates in United States suburban households seeking weeknight meal solutions compatible with USDA school nutrition guidelines.
- Alfredo:Cream-style sauces engineered with skim milk solids and modified starch stabilization systems present the most complex reformulation challenges under FDA sodium reduction mandates. Metropolitan United Kingdom grocers are expanding shelf space for these variants faster than any other product type.
- Pesto:Basil-oil emulsions reduced to sub-3 gram fat servings through nut butter substitution and portion-controlled formats.
- Garlic:Oil-infused tomato bases with lipid content compressed via roasted garlic puree extension systems.
By volume, Marinara leads. By growth pace, Alfredo is expanding most quickly as health-conscious households seek indulgence without penalty.
Ingredient Type:
Cost tier stratification runs deepest here, with certification premiums creating three distinct price bands that manufacturers must navigate simultaneously.
- Organic:USDA-certified formulations excluding synthetic pesticides and fertilizers command shelf-space premiums in United States natural grocery channels. California Central Valley sourcing contracts dominate supply, with EFSA equivalence recognition unlocking limited European access.
- Gluten-Free:Celiac-safe protocols with dedicated production lines and third-party testing add 12-18% manufacturing overhead. United States metropolitan households with diagnosed gluten sensitivity drive disproportionate per-capita consumption.
- Low Sodium:Sub-140mg per serving targets aligned with FDA hypertension reduction initiatives.
- Vegan:Plant-based formulations excluding all dairy derivatives, capturing meal-kit subscription demand in coastal United States urban corridors.
By volume, Low Sodium leads. By growth pace, Vegan is gaining share fastest as plant-based dietary patterns mainstream beyond niche adoption.
Packaging Type:
Application context determines format selection, with convenience-oriented channels fragmenting traditional glass-jar concentration.
- Bottle:Squeeze-dispense polyethylene terephthalate formats dominate United States foodservice portion-control applications. Quick-service restaurant chains specify these for back-of-house efficiency, driving contract manufacturing specialization.
- Jar:Glass containers sustain premium positioning in supermarket perimeter displays across the United Kingdom and Canada, where tactile quality signals command shopper attention.
- Pouch:Flexible barrier films with spout fitments are climbing the fastest among direct-to-consumer subscription channels.
- Can:Steel containers retain institutional foodservice and emergency pantry stocking applications.
By volume, Jar leads. By growth pace, Pouch shows the steepest expansion trajectory as cold-chain logistics mature for refrigerated variants.
Distribution Channel:
Customer type concentration varies dramatically, with household purchasing patterns diverging sharply from institutional procurement behaviors.
- Supermarket:Perimeter display placement and end-cap promotional cycles determine velocity in United States metropolitan grocery corridors. Slotting fee structures favor manufacturers with refrigerated supply chain scale.
- Online Retail:Algorithm-curated replenishment and subscription bundling are displacing impulse purchasing in coastal United States urban markets.
- Specialty Stores:Natural grocery and gourmet formats emphasize certification density and origin storytelling.
- Distributors:Broadline foodservice networks aggregate demand from independent restaurants and institutional kitchens.
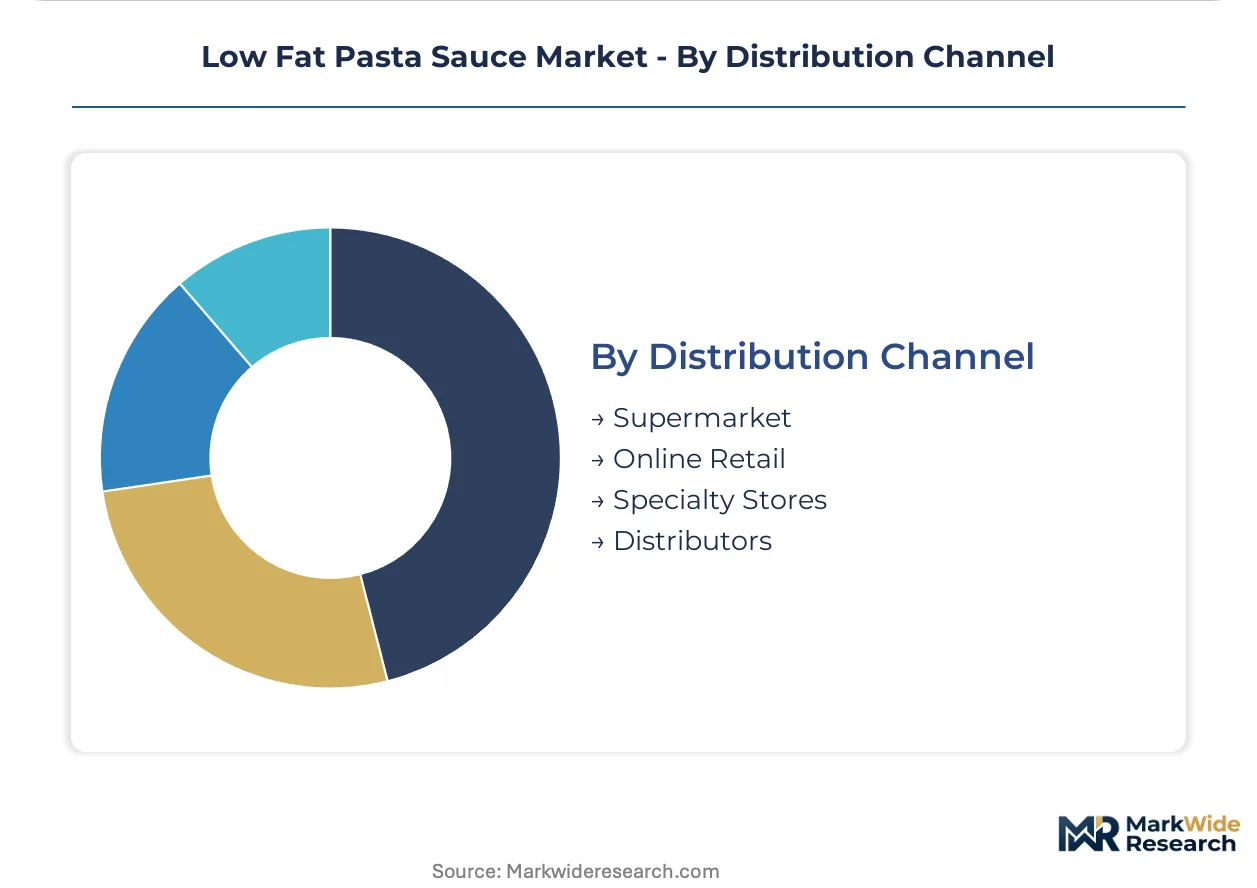
By volume, Supermarket leads. By growth pace, Online Retail is climbing fastest as delivery density economics improve for temperature-controlled fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in United Kingdom metropolitan grocery corridors while United States suburban households drive volume absorption through club-store procurement. Metropolitan Canada anchors cold-chain logistics innovation for refrigerated variants. Germany's reformulation laboratories set technical standards for clean-label stabilization systems.
United States
Suburban households in metropolitan corridors expand reduced-fat meal preparation beyond traditional diet segments. FDA sodium reduction targets pull reformulation investment toward dual health-claim SKUs. California's Central Valley processing tomato operations anchor backward integration strategies for major manufacturers.
United Kingdom
Metropolitan grocers expand shelf space for Alfredo variants faster than any other product type. EFSA health claim authorization pathways for reduced-fat products remain underexploited by North American exporters. London-based retail banners prioritize carbon-labeled supply chains under EU Green Deal agricultural standards.
Canada
Health-conscious households in suburban corridors drive refrigerated variant adoption through meal-kit subscription channels. Health Canada nutrition labeling mandates shape permissible health claims across North American supply chains. Toronto-Vancouver logistics corridors mature cold-chain infrastructure for temperature-controlled fulfillment.
Germany
REACH compliance requirements for additive transparency force disclosure of processing aids previously treated as proprietary. ECHA restriction timelines accelerate reformulation away from titanium dioxide whitening agents. Bavaria-based food technology clusters pioneer natural thickener substitution systems.
Italy
Mediterranean formulation heritage commands authenticity premiums in specialty retail channels. EU Green Deal regenerative sourcing requirements create preferential access for compliant suppliers. Emilia-Romagna tomato processing traditions inform clean-label stabilization approaches without synthetic preservatives.
Low Fat Pasta Sauce Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in natural thickener and barrier film supply. The vendor base concentrates among multinational food conglomerates with refrigerated supply chain scale and regional specialists competing on formulation authenticity. Three archetypes dominate: conglomerate platform operators with backward integration into agricultural inputs, Mediterranean heritage specialists leveraging regional formulation credibility, and private-label contract manufacturers serving foodservice transparency demands. Competitive moves center on co-manufacturing partnerships that fragment entry barriers and pouch packaging technology licensing that unlocks direct-to-consumer channels.
Within the conglomerate platform tier, Nestlé and Kraft Heinz Company exemplify divergent infrastructure strategies. Nestlé leverages refrigerated supply chain networks to maintain shelf-space dominance in premium grocery channels. Kraft Heinz Company anchors its position through captive tomato processing operations in California's Central Valley. Barilla G. e R. Fratelli S.p.A. occupies a distinct position as a Mediterranean heritage specialist, competing on authenticity credentials rather than price positioning in European and North American specialty retail.
| Leading Market Players |
|---|
| Del Monte Foods |
| Campbell Soup Company |
| Kraft Heinz Company |
| Barilla G. e R. Fratelli S.p.A. |
| Conagra Brands |
| Nestlé |
| McCormick and Company |
| Mizkan Holdings |
| B and G Foods |
| Others |
Value Network & Pricing Analysis
Indian guar gum and Thai tapioca starch suppliers command disproportionate leverage over formulation economics, concentrating margin capture upstream while finished goods pricing fragments across certification tiers and channel formats downstream. This input concentration compresses cost flexibility for manufacturers reformulating under clean-label mandates.
Pricing Analysis
Configured-to-order pricing for organic and vegan-certified variants commands spreads exceeding standard marinara lines by certification premiums and cold-chain logistics bundling. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic SKUs from conventional reduced-fat lines and private-label foodservice offerings. Price differentiation rests on dual certification density and refrigerated supply chain scale. Cost compression in economy tiers is intensifying because California Central Valley tomato contract volatility feeds through processing cost structures. Foodservice procurement teams exhibit highest price sensitivity, while metropolitan United Kingdom grocers absorb premium positioning for Alfredo variants.
Supply Chain Analysis
Extended payment terms from major United States retailers now reach 90-120 days, forcing mid-tier manufacturers toward supply-chain finance facilities anchored by receivables-backed credit. Geographic supply concentration centers on India for guar gum, Thailand for tapioca starch, and California's Central Valley for processing tomatoes. Raw material dependencies include vegetable puree bases, skim milk solids, and natural stabilizer systems. Single-source vulnerability in Indian gum supply exposes formulations to monsoon disruption and export policy shifts. Distribution runs through refrigerated broadline networks for foodservice and direct-to-pantry subscription channels for coastal United States households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low fat pasta sauce demand cycles with suburban household health-consciousness and regulatory reformulation waves, positioning the market for recovery as FDA sodium reduction timelines accelerate manufacturer SKU consolidation.
For Market Incumbents: Build refrigerated supply chain moats through captive cold-chain infrastructure in metropolitan United States corridors and Toronto-Vancouver logistics networks. Consolidate position by acquiring pouch packaging technology licenses to unlock direct-to-consumer channels. Defend against private-label contract manufacturers by deepening backward integration into California Central Valley tomato operations and accelerating USDA organic certification density above competitor baselines. For New Entrants and Emerging Players: United Kingdom Alfredo variant shelf space expansion represents the most penetrable entry point, as EFSA health claim pathways remain underexploited by North American competitors. Vegan meal-kit subscription channels in coastal United States urban corridors offer second white-space target with lower slotting fee barriers than supermarket perimeter displays. Go-to-market angle should emphasize carbon-labeled supply chains compliant with EU Green Deal agricultural standards to secure preferential retail banner access. For Investors and Strategic Acquirers: Capital is best deployed toward Mediterranean heritage specialists with Emilia-Romagna formulation credibility and existing clean-label stabilization capabilities. Long-term viability across the analysis window favors manufacturers with dual USDA organic and Non-GMO Project verification infrastructure already operational. Signal to watch: ECHA restriction timeline acceleration on titanium dioxide whitening agents forcing delisting cascades among non-compliant SKUs.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | Natural thickener substitution ahead of FDA sodium mandates protects shelf-space positioning. |
| Pouch Packaging Technology Licensing | Flexible barrier films unlock club store and subscription channel distribution previously inaccessible. |
| Backward Integration into Tomato Processing | Captive California Central Valley supply insulates margin stability from water allocation uncertainty. |
| Dual Certification Acceleration | Simultaneous USDA organic and Non-GMO Project verification compresses launch cycle timelines. |
| Carbon-Labeled Supply Chain Repositioning | EU Green Deal compliance secures preferential access to London-based retail banners. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at multinational food conglomerates, category buyers at United States metropolitan grocers, supply planners managing refrigerated logistics networks, and formulation scientists at natural food specialists, then refined through secondary validation against FDA nutrition labeling guidance documents, USDA organic certification databases, EFSA health claim registers, Nielsen retail audit data, and customs records tracking tomato paste and stabilizer imports. Bottom-up SKU-level volume modeling and top-down macroeconomic demand projections were triangulated to converge estimates.
Demand-supply-balance framing anchored the analytical framework across the modeling period, with segmentation dimensions including product type, ingredient certification tier, packaging format, and distribution channel intensity. CAGRs were derived through logistic adoption curve fitting for emerging formats and linear extrapolation for mature marinara volumes. Industry-specific forecast inputs incorporated California Central Valley water allocation scenarios and ECHA additive restriction timeline probabilities.
Stress conditions across tomato input pricing volatility, Indian monsoon disruption severity, and FDA sodium threshold acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about suburban household health-consciousness persistence and regulatory reformulation cycle timing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
West Africa Mayonnaise Market
Condiments & Sauces
Latin America Pasta Sauce Market
Condiments & Sauces
Low Salt Soy Sauce Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Oyster Sauce Market
Condiments & Sauces
Cooking Sauces Market
Condiments & Sauces
Horseradish Sauce Market
Condiments & Sauces
Dipping Sauces Market
Condiments & Sauces
Compound Condiments Market
Condiments & Sauces
Condiments Market
Condiments & Sauces
Sauces and Condiments Market