
 Salad Dressings and Mayonnaise Market | 2026-2036
Salad Dressings and Mayonnaise Market Size, Share, and Industry Trends Forecast 2026-2036
Salad Dressings and Mayonnaise Market Outlook
Multi-pack bundling of single-serve pouches with family-size bottles is consolidating pantry and on-the-go purchase occasions into unified brand relationships. Kraft Heinz Company leverages its retail shelf-space dominance to anchor bundled promotions across club and mass channels. Unilever PLC sustains global formulation expertise that competes with regional taste preferences in Europe and Asia. McCormick & Company differentiates through flavor-forward specialty lines that occupy premium positioning in grocery perimeter sets.
Salad dressings and mayonnaise comprise emulsified or suspended oil-and-acid preparations, typically containing 30-80% vegetable oil by weight, stabilized with egg yolk lecithin, mustard, or modified food starch, manufactured through high-shear mixing or colloid milling to achieve particle sizes below 5 microns for shelf stability and mouthfeel. These products serve as moisture barriers, flavor carriers, and texturizers in commercial food production and home meal assembly. Vinaigrettes lead volume in foodservice channels where pourable consistency reduces labor cost, while creamy dressings command higher retail margins due to ingredient complexity and refrigerated distribution requirements. Low-fat dressings represent the fastest-growing formulation segment as hydrocolloid and protein-stabilized emulsions displace traditional oil-heavy recipes without sacrificing viscosity.
FDA nutrition labeling rules and USDA organic certification standards shape ingredient sourcing, sodium reduction timelines, and front-of-pack claim permissibility across the United States market. The EPA regulates wastewater discharge from condiment manufacturing facilities, influencing plant location and treatment capital allocation for producers scaling output. Stakeholders must monitor evolving clean-label enforcement thresholds and bioengineered food disclosure deadlines to align formulation pipelines with compliance windows.
Market Dynamics
Clean-label reformulation mandates from FDA and USDA are forcing manufacturers to replace modified starches and artificial emulsifiers with clean-label alternatives, compressing formulation cycles and elevating R&D spend across the condiment sector.
Growth Catalysts
- Foodservice Menu Expansion:Restaurant chains in the United States are deploying refrigerated dressing lines across salad bowls, grain bowls, and protein plates, pulling volume through commercial distribution.
- USDA Organic Certification:Retailers are mandating organic certification for perimeter-set placement, accelerating farmer contracting for non-GMO oilseed inputs.
- Hydrocolloid Stabilization:Protein and gum-based emulsion systems are enabling 50%+ oil reduction without viscosity loss, opening low-fat formulation pipelines.
Market Restraints
- Egg Yolk Supply Concentration:Iowa and Ohio account for the majority of U.S. lecithin-grade egg production, exposing emulsion stability to avian influenza disruptions.
- Soybean Oil Price Volatility:Crude vegetable oil futures transmit directly to manufacturing cost structures, squeezing margin on economy-tier products.
- Refrigerated Distribution Infrastructure:Cold-chain requirements for clean-label dressings limit rural retail penetration and foodservice reach.
Strategic Opportunities
- Single-Serve Pouch Formats:Foodservice operators are adopting portion-control packaging to reduce waste and labor, creating white space in contract manufacturing.
- FSSAI Clean-Label Harmonization:India's alignment with international additive standards is opening export pathways for U.S. and European formulation expertise.
- Plant-Based Emulsifier Convergence:Pea protein and sunflower lecithin technologies are merging to replace egg yolk in vegan mayonnaise lines.
Industry Challenges
- Clean-Label Reformulation Timelines:FDA bioengineered food disclosure deadlines are compressing ingredient sourcing windows, forcing parallel supplier qualification.
- Colloid Milling Capacity Constraints:Sub-5 micron particle size requirements for shelf-stable emulsions demand capital-intensive equipment upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salad Dressings and Mayonnaise Market |
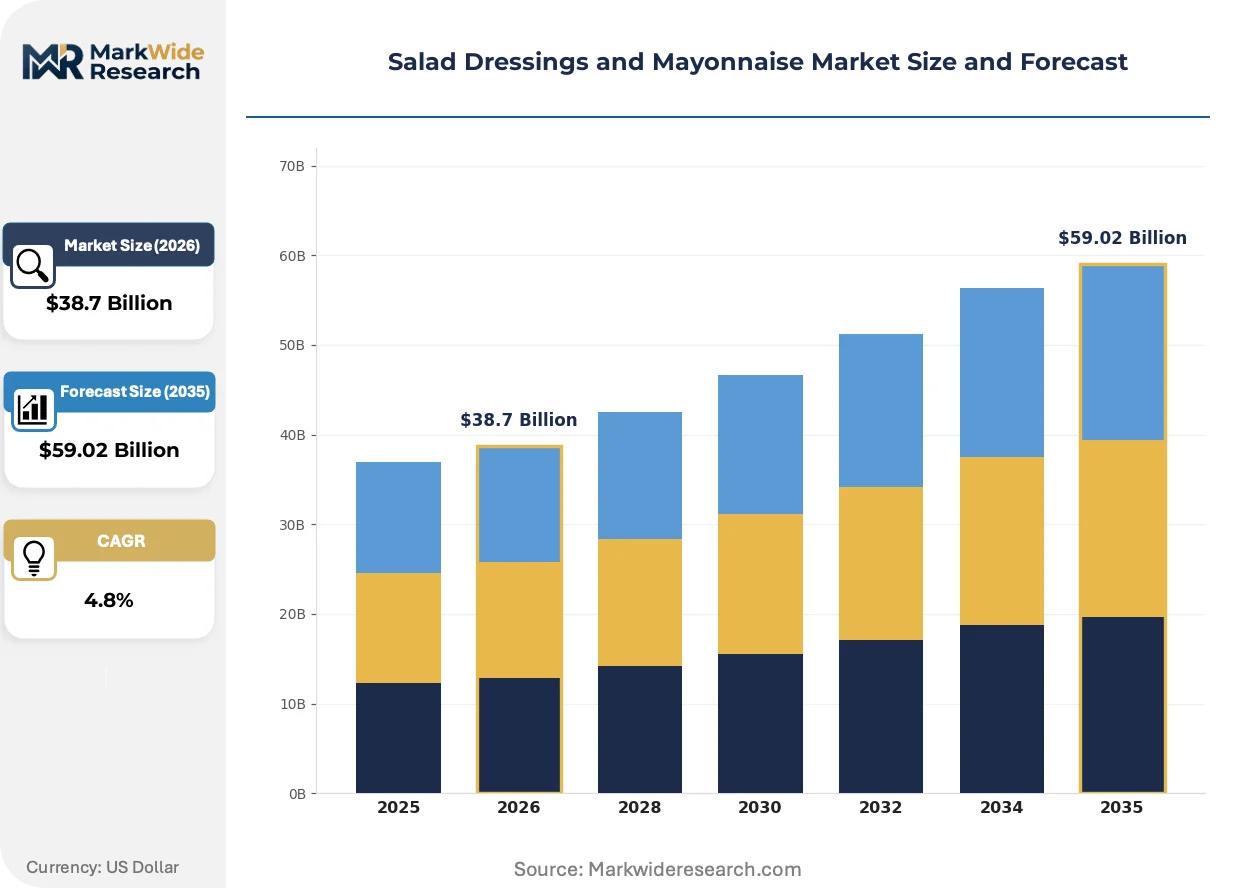
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinaigrettes, Creamy Dressings, Mayonnaise, Low-Fat Dressings Ingredient Type: Organic, Natural, Non-GMO, Conventional Packaging Type: Bottles, Sachets, Jars, Pouches Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Food Stores |
| Companies Covered | Kraft Heinz Company, Unilever PLC, McCormick & Company, Ken's Foods, Kewpie Corporation, Nestlé, T. Marzetti Company, Clorox Company, Campbell Soup Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salad Dressings and Mayonnaise Market Strategic Shifts
Formulation science and distribution technology are converging to reshape how emulsified condiments reach end-users, with implications for manufacturing scale, regulatory compliance, and consumption occasions.
High-pressure processing is decentralizing pasteurization away from centralized thermal tunnels. Mid-size regional manufacturers are adopting HPP equipment to produce refrigerated clean-label lines without massive retort infrastructure. This technology is decentralizing production geography, enabling smaller plants in secondary markets to compete with national brands on freshness claims.
EU F-Gas Regulation phase-down schedules are accelerating refrigeration equipment retrofits across European distribution networks. Cold-chain operators face compressor replacement timelines that compress capital deployment windows. Foodservice distributors in Germany and France are responding by consolidating refrigerated SKUs and prioritizing high-velocity dressing lines over niche variants.
Direct-store-delivery networks are fragmenting procurement relationships between manufacturers and retail perimeter departments. Grocery chains are bypassing traditional warehouse distribution for refrigerated dressings, instead receiving frequent small-lot shipments from local copackers. This pattern is most visible in the United States, where Albertsons and Kroger are expanding DSD partnerships to reduce out-of-stocks in produce-adjacent sets.
Salad Dressings and Mayonnaise Market Segmentation
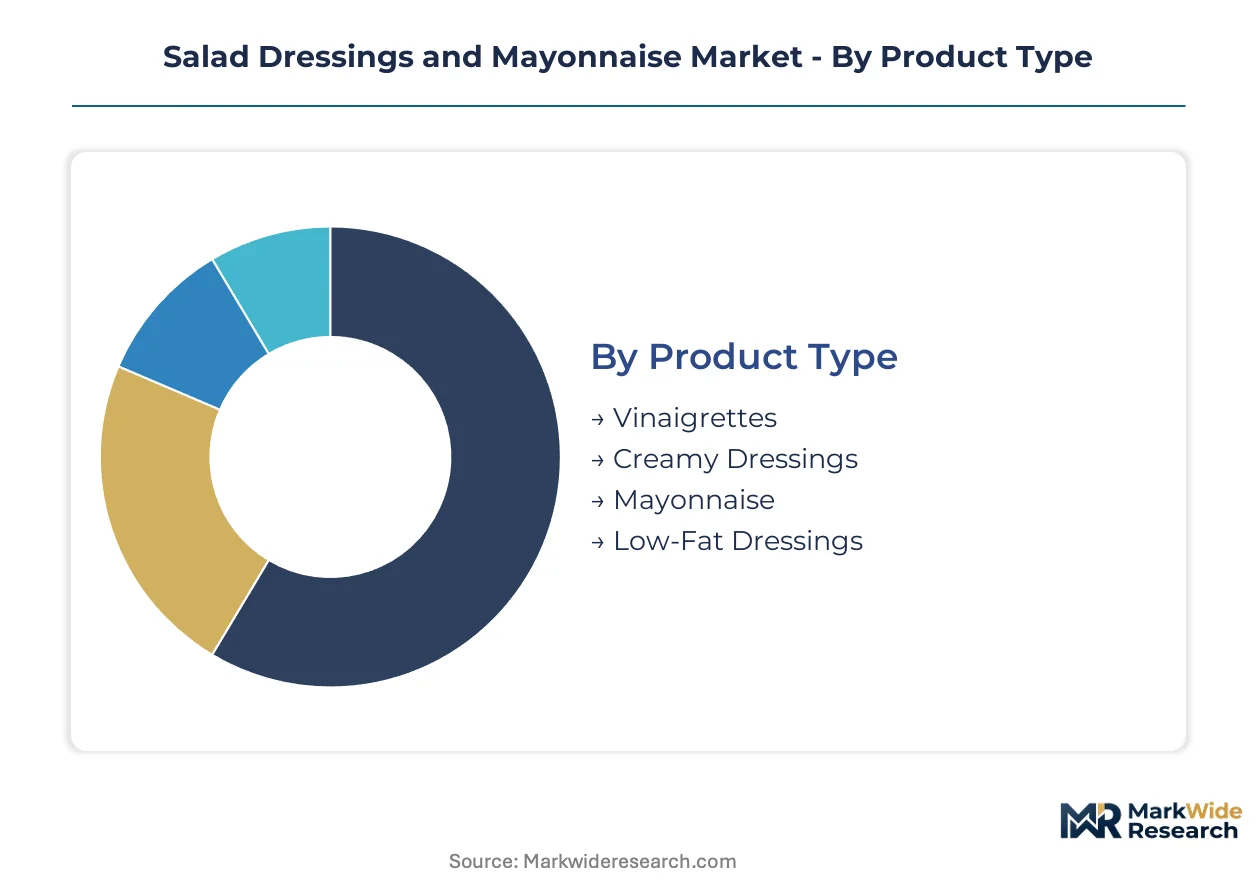
Segmentation in salad dressings and mayonnaise reveals divergent capital requirements across manufacturing footprints. Product formulation complexity and cold-chain dependencies create tiered investment thresholds that reshape competitive entry barriers.
Product Type:
Capital intensity peaks with refrigerated creamy lines requiring HPP equipment and continuous cold-chain infrastructure, while shelf-stable vinaigrettes demand lower upfront outlay.
- Vinaigrettes:Oil-acid emulsions with minimal stabilizer load achieve shelf stability through ambient distribution. Foodservice demand concentrates in United States restaurant chains seeking pourable labor efficiency, though margin compression from commodity oil inputs constrains premium positioning.
- Creamy Dressings:High-shear colloid milling and egg yolk lecithin stabilization necessitate sub-5 micron particle control systems. United States retail perimeter placement drives refrigerated distribution investments, with USDA organic certification gating access to high-velocity produce-adjacent sets.
- Mayonnaise:Dense emulsions at 70-80% oil weight require specialized high-shear capacity and pasteurization infrastructure.
- Low-Fat Dressings:Hydrocolloid and protein-stabilized systems displace traditional oil-heavy recipes, demanding R&D-heavy reformulation pipelines.
Most installed capacity flows through Creamy Dressings. Expansion is steepest in Low-Fat Dressings.
Ingredient Type:
Certification tiering separates procurement cost structures, with organic and non-GMO segments commanding upstream farmer contracting premiums that conventional lines avoid.
- Organic:USDA certification mandates three-year transition windows for oilseed growers, locking in supply scarcity before volume scaling. United States retailers now mandate organic credentials for perimeter-set placement, concentrating farmer contracting in Iowa and Ohio soy and canola belts.
- Natural:Clean-label positioning without full organic certification captures price-sensitive consumers seeking ingredient transparency, though FDA bioengineered disclosure rules complicate sourcing documentation.
- Non-GMO:Identity-preserved supply chains require segregation infrastructure from crush through packaging.
- Conventional:Commodity soybean and canola oil inputs minimize raw material costs but expose margins to futures volatility.
Organic commands the highest procurement premiums. Natural is gaining share fastest among mid-tier retail positioning.
Packaging Type:
Format selection determines filling line capital allocation, with aseptic pouch systems requiring distinct equipment from glass jar infrastructure.
- Bottles:PET and glass formats dominate retail shelf presence, with ergonomic grip designs and label real estate driving consumer pickup rates in United States supermarket condiment aisles.
- Sachets:Single-serve portion control reduces foodservice waste and labor, with quick-service chains in United States markets adopting standardized pack sizes for bowl and plate applications.
- Jars:Wide-mouth glass formats retain premium positioning for mayonnaise and specialty spreads.
- Pouches:Flexible stand-up formats reduce shipping cube and material weight, though filling speed lags behind rigid containers.
Bottles carry the largest installed base. Pouches are climbing the fastest on sustainability and logistics efficiency gains.
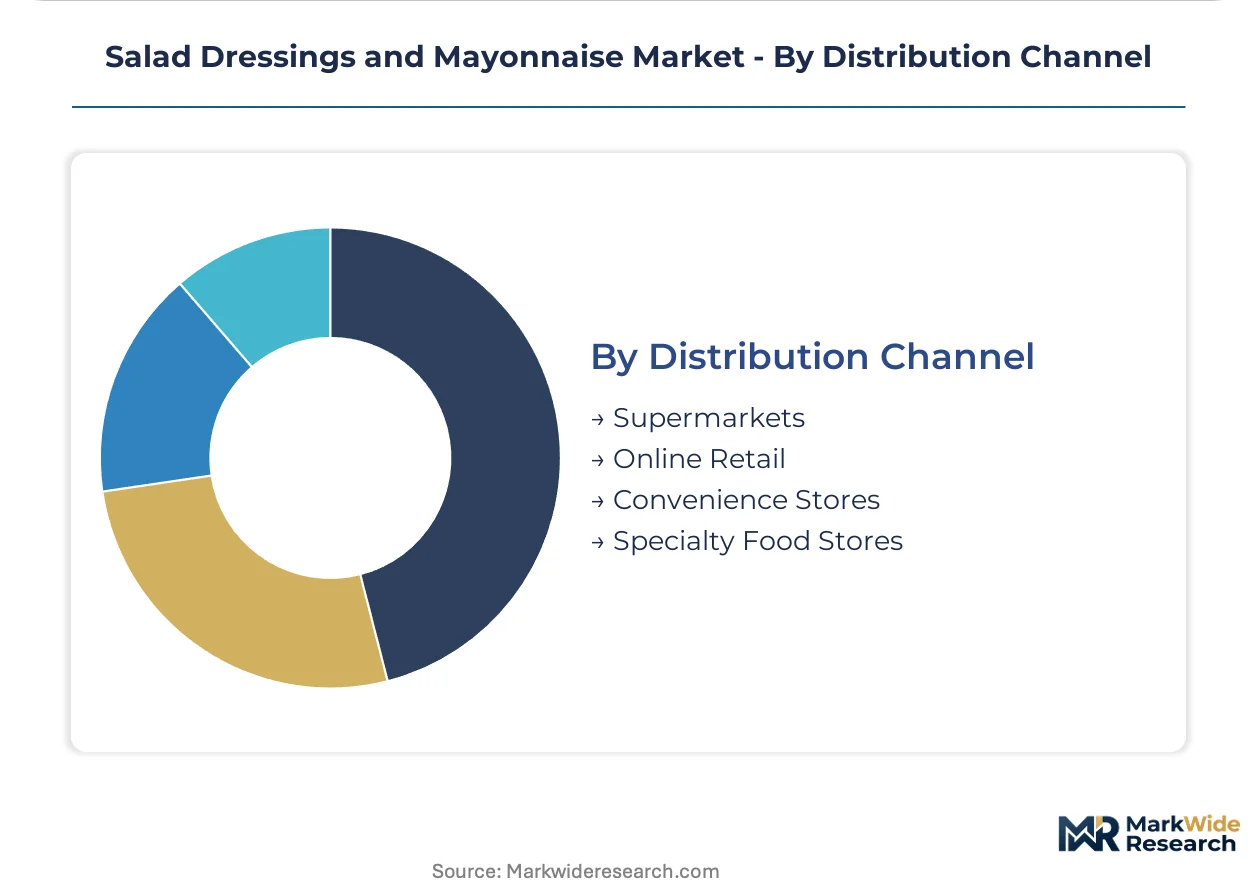
Distribution Channel:
Channel mix dictates working capital intensity, with direct-store-delivery relationships requiring fleet investment that centralized warehouse distribution avoids.
- Supermarkets:United States chains including Albertsons and Kroger are expanding DSD partnerships for refrigerated dressings, bypassing traditional warehouse distribution to reduce out-of-stocks in produce perimeter sets.
- Online Retail:Cold-chain last-mile requirements constrain ambient-stable SKU expansion, though subscription bundling of multi-pack formats builds recurring revenue streams.
- Convenience Stores:Limited refrigerated case space favors shelf-stable vinaigrettes and single-serve mayonnaise packets.
- Specialty Food Stores:Premium and artisanal lines command placement fees for local and regional brand access.
Supermarkets absorb the majority of volume flow. Online Retail shows steepest expansion trajectory on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial mayonnaise production originated in New York City during the early 20th century, establishing the United States as the historical center of emulsified condiment manufacturing. This lineage shapes contemporary demand patterns and regulatory frameworks across key production clusters.
United States
Foodservice chains in the United States are deploying refrigerated dressing lines across salad bowls and protein plates, pulling volume through commercial distribution networks. FDA bioengineered food disclosure deadlines and USDA organic certification standards compress ingredient sourcing windows for manufacturers. Chicago and Pittsburgh anchor Midwest production corridors where colloid milling capacity concentrates for creamy dressing output.
Germany
Retailers in Germany mandate clean-label positioning for perimeter-set placement, accelerating reformulation investments across domestic manufacturers. EU F-Gas Regulation phase-down schedules force refrigeration equipment retrofits across distribution networks, consolidating refrigerated SKU portfolios. The Rhine-Ruhr industrial belt hosts specialized emulsion processing facilities serving Central European markets.
Japan
Japanese consumers exhibit strong preference for mayonnaise as a cooking ingredient rather than sandwich spread, sustaining distinct formulation specifications with higher egg content. METI guidelines on food additive labeling shape clean-label migration timelines for domestic producers. The Kansai region around Osaka maintains dense clusters of fermentation-based condiment expertise that extends into emulsion technology.
India
Quick-service restaurant expansion in India is adopting Western-style dressing applications for localized menu formats, creating new demand for shelf-stable emulsions. FSSAI alignment with international additive standards opens pathways for imported formulation expertise and domestic contract manufacturing growth. Maharashtra and Gujarat host emerging processing infrastructure serving urban consumption centers.
Brazil
Brazilian foodservice operators are standardizing mayonnaise specifications for churrasco and sandwich applications, driving volume consolidation among regional brands. ANVISA nutrition labeling requirements shape sodium reduction timelines and front-of-pack claim strategies. São Paulo state concentrates production capacity for soy-based oil inputs that supply domestic emulsion manufacturers.
Salad Dressings and Mayonnaise Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification tiers, with organic and clean-label lines commanding placement fees that conventional products cannot match. The vendor base stratifies into three tiers: multinational conglomerates with retail shelf-space dominance, mid-size regional specialists with foodservice relationships, and private-label contract manufacturers serving club and discount channels. Dominant competitive moves include direct-store-delivery network expansion to bypass traditional warehouse distribution, and high-pressure processing equipment investments to enter refrigerated clean-label segments without retort infrastructure.
Among North American-based manufacturers, Kraft Heinz Company and McCormick & Company exemplify divergent strategic archetypes within the premium tier. Kraft Heinz occupies a position anchored in retail shelf-space dominance and bundled promotion capabilities across mass and club channels. McCormick & Company represents the flavor-forward specialty positioning that commands premium placement in grocery perimeter sets. Unilever PLC, as a European-domiciled conglomerate, sits within the global formulation expertise tier competing across regional taste preferences in multiple continents.
| Leading Market Players |
|---|
| Kraft Heinz Company |
| Unilever PLC |
| McCormick & Company |
| Ken's Foods |
| Kewpie Corporation |
| Nestlé |
| T. Marzetti Company |
| Clorox Company |
| Campbell Soup Company |
| Others |
Value Chain & Pricing Dynamics
USDA organic certification mandates from retailers are forcing manufacturers to lock in three-year oilseed transition contracts with Iowa and Ohio growers, compressing procurement flexibility and transmitting upstream scarcity premiums into refrigerated dressing price points. This demand-side specification cascade reshapes how supply chains absorb cost volatility across conventional and certified ingredient tiers.
Pricing Analysis
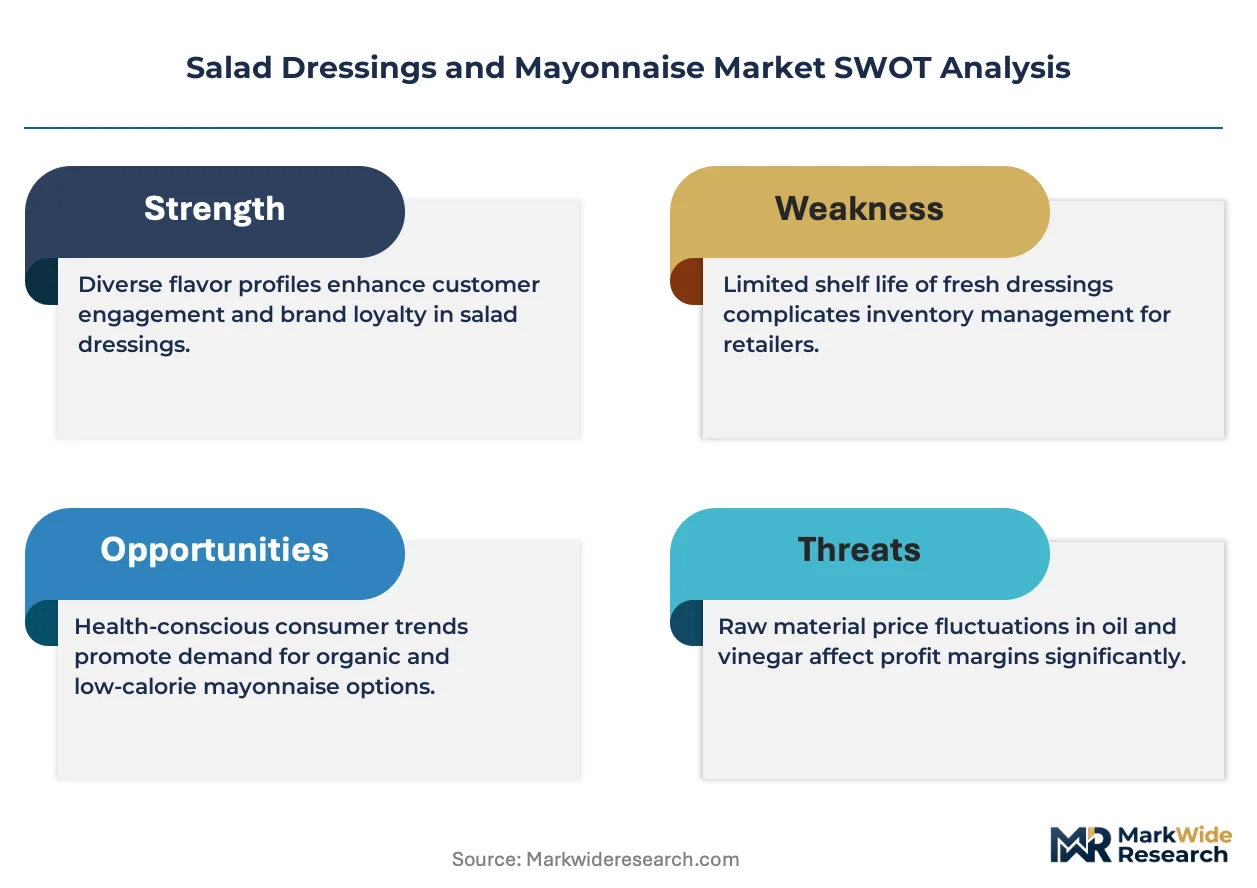
Three-tier pricing structure across premium, standard, and economy levels separates USDA organic lines commanding placement fees from natural-positioned mid-tier products and commodity soybean-oil-based economy offerings. Price differentiation rests on certification grade and cold-chain delivery cost, with refrigerated distribution infrastructure adding margin compression that ambient-stable vinaigrettes avoid. Pricing pressure stems from soybean oil futures volatility squeezing economy-tier margins, while foodservice buyers exhibit highest price sensitivity and specialty retail channels show lowest.
Supply Chain Analysis
Workforce availability constraints in Midwest colloid milling corridors and Kansai fermentation clusters are tightening operational flexibility for manufacturers scaling high-shear capacity. Supply concentrates in the United States, Germany, and Japan, with dense emulsion processing anchored in Chicago-Pittsburgh production belts and Osaka-region technical expertise. Raw material dependencies draw from Iowa-Ohio egg yolk lecithin, Brazilian soy crush, and identity-preserved non-GMO oilseed streams. Single-source vulnerability in lecithin-grade egg production exposes emulsion stability to avian influenza disruptions. Distribution runs through direct-store-delivery networks bypassing traditional warehouse channels for refrigerated perimeter placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA bioengineered food disclosure deadlines and USDA organic certification standards continuously reset procurement and formulation requirements, creating sustained demand for compliance-capable suppliers.
For Market Incumbents: Cement shelf-space dominance through bundled promotion architectures across club and mass channels while locking in backward integration into Iowa-Ohio oilseed contracting. High-pressure processing equipment investments defend against regional copackers encroaching on refrigerated clean-label segments without retort infrastructure. For New Entrants and Emerging Players: Foodservice distributors seeking portion-control packaging present the most penetrable entry vector, with single-serve pouch formats for quick-service bowl applications offering white space outside incumbent retail concentration. Target contract manufacturing relationships with regional chains standardizing dressing specifications across salad and protein plate menus. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-size regional specialists possessing established foodservice relationships and HPP-equipped facilities in secondary markets. Long-term viability favors acquisition targets with validated clean-label formulation pipelines and DSD network density in produce-adjacent retail sets. Watch FSSAI harmonization progress in India as inflection indicator for export pathway expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Pipeline | FDA disclosure deadlines force parallel supplier qualification accelerating R&D spend. |
| High-Pressure Processing Investment | HPP equipment enables regional plants to compete on freshness without retort infrastructure. |
| Direct-Store-Delivery Expansion | DSD partnerships with Albertsons and Kroger reduce out-of-stocks in perimeter sets. |
| Organic Oilseed Backward Integration | Three-year grower transition contracts lock in supply scarcity before volume scaling. |
| Single-Serve Pouch Format Entry | Portion-control packaging addresses foodservice waste reduction and labor efficiency demands. |
Study Parameters
Bottom-up foodservice and retail channel modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with R&D formulation directors, foodservice procurement managers, retail category buyers, and cold-chain logistics operators combined with secondary validation from FDA labeling guidance documents, USDA organic certification databases, EPA wastewater discharge records, and customs trade flow data. Triangulation across stakeholder inputs and regulatory filings ensures segmentation integrity.
Historical trendline analysis of volume flows through vinaigrette, creamy dressing, mayonnaise, and low-fat formulation segments established baseline growth patterns across the projection horizon. Modeled dimensions span product type, ingredient certification tier, packaging format, and distribution channel, with CAGRs derived from elasticity-adjusted demand curves and capacity expansion timelines. Forecast inputs incorporate colloid milling equipment deployment cycles and refrigerated SKU consolidation patterns in European distribution networks.
Revisions become necessary when avian influenza disruptions to Iowa-Ohio egg supply, EU F-Gas Regulation compressor replacement timelines, or FSSAI additive standard harmonization materialize outside baseline assumptions. Forecasts reflect documented assumptions about clean-label enforcement thresholds and bioengineered disclosure compliance windows. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Cooking Sauces Market
Condiments & Sauces
Dips and Spreads Market
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Condiments Market
Condiments & Sauces
Ketchup Market
Condiments & Sauces
Vegan Pasta Sauce Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
Acciughe Pasta Sauce Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Tomato Ketchup Market
Condiments & Sauces
Barbecue Sauce Market
Condiments & Sauces
Australia and New Zealand Tomato Sauce Market
Condiments & Sauces
Table Sauce Market