
 North America Mayonnaise Market | 2026-2036
North America Mayonnaise Market Size, Share, and Industry Trends Forecast 2026-2036
North America Mayonnaise Market Intelligence
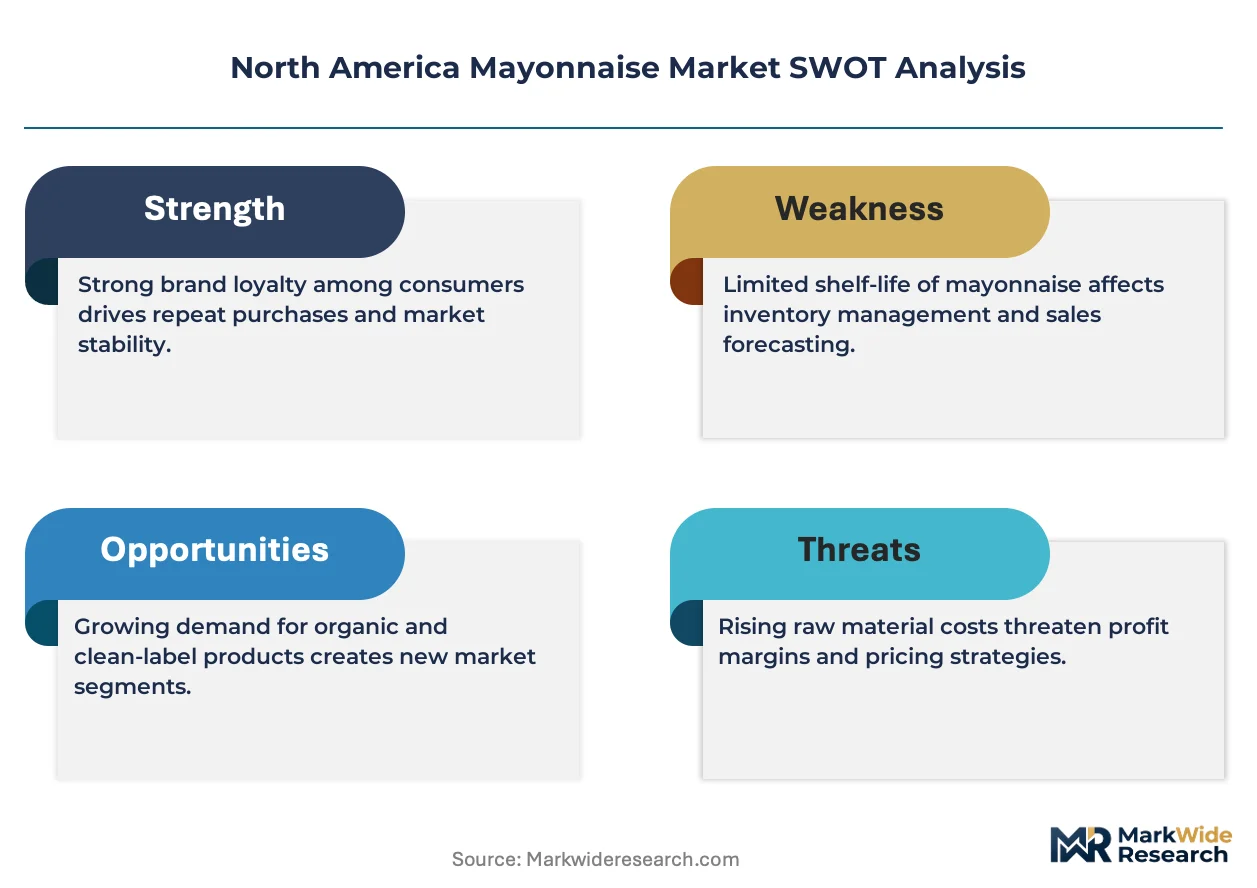
Clean-label emulsification technology is reconfiguring how North American mayonnaise manufacturers formulate shelf-stable products without artificial stabilizers. Kraft Heinz leverages its extensive R&D infrastructure to develop proprietary egg-reduction systems that maintain texture integrity. Unilever sustains competitive pressure through its Hellmann's brand, which dominates retail shelf space across the United States and Canada. Sir Kensington's differentiates through avocado-oil-based formulations that command premium positioning in specialty grocery channels.
Mayonnaise is an oil-in-water emulsion containing minimum 65% vegetable oil by weight, acidified with vinegar or lemon juice and stabilized by egg yolk lecithin, functioning primarily as a cold sauce base and binding agent across foodservice and packaged food applications. The organic product type segment captures expanding margin pools as consumers trade up from conventional formulations, while the food service distribution channel anchors volume throughput through institutional procurement contracts with restaurant chains and cafeteria operators. Flavored variants, including sriracha and chipotle infusions, represent the fastest-growing product type as younger demographics seek bold taste profiles.
The FDA governs mayonnaise identity standards under 21 CFR 169.140, which mandates minimum oil content and restricts ingredient substitutions that would trigger relabeling as "dressing" rather than mayonnaise. USDA FSIS oversight applies to mayonnaise used as a component in meat and poultry products, creating dual compliance pathways for food manufacturers. Health Canada regulates similar standards through its Food and Drug Regulations, requiring bilingual labeling for cross-border products. Stakeholders must monitor emerging state-level sodium reduction mandates in California and New York, which could cascade into broader North American formulation requirements.
Market Dynamics
Clean-label emulsification systems are forcing North American mayonnaise manufacturers to rebuild formulation pipelines around egg-reduction technologies that maintain texture without artificial stabilizers.
Growth Catalysts
- Quick-service restaurant expansion:Chains across the United States and Canada are broadening menu applications for mayonnaise-based sauces, driving institutional procurement volumes through foodservice distribution channels.
- FDA nutrition labeling updates:The FDA's revised sodium disclosure requirements are compelling manufacturers to reformulate toward lower-sodium profiles that qualify for cleaner front-of-package claims.
- Flavor innovation pipelines:Sriracha, chipotle, and globally-inspired infusions are capturing younger consumer cohorts seeking differentiated taste experiences beyond conventional mayonnaise.
Market Restraints
- Input cost volatility:Egg yolk and vegetable oil prices fluctuate with commodity cycles, compressing margins for producers without backward integration into oilseed crushing or egg supply.
- Regulatory identity standards:FDA 21 CFR 169.140 mandates minimum 65% oil content and restricts ingredient substitutions, blocking formulation flexibility that would reduce cost or improve nutrition profiles.
- Plant-based substitution threat:Egg-free and vegan emulsion products labeled as "dressing" rather than mayonnaise are capturing shelf space and consumer trial among flexitarian households.
Strategic Opportunities
- Organic premium tier expansion:The organic product segment offers margin expansion potential as consumers trade up from conventional formulations in specialty grocery channels.
- Avocado-oil base innovation:Premium positioning through alternative oil bases commands price premiums and differentiation in health-focused retail segments.
- State-level sodium mandates:California and New York regulatory trajectories on sodium reduction could cascade into broader North American formulation standards, rewarding early reformulation investments.
Industry Challenges
- Clean-label emulsification expertise gap:Food science talent capable of developing stable egg-reduction systems without synthetic stabilizers remains scarce, slowing product pipeline velocity.
- Dual compliance pathway complexity:Manufacturers supplying both retail and meat/poultry processing channels must navigate simultaneous FDA and USDA FSIS oversight, extending certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Mayonnaise Market |
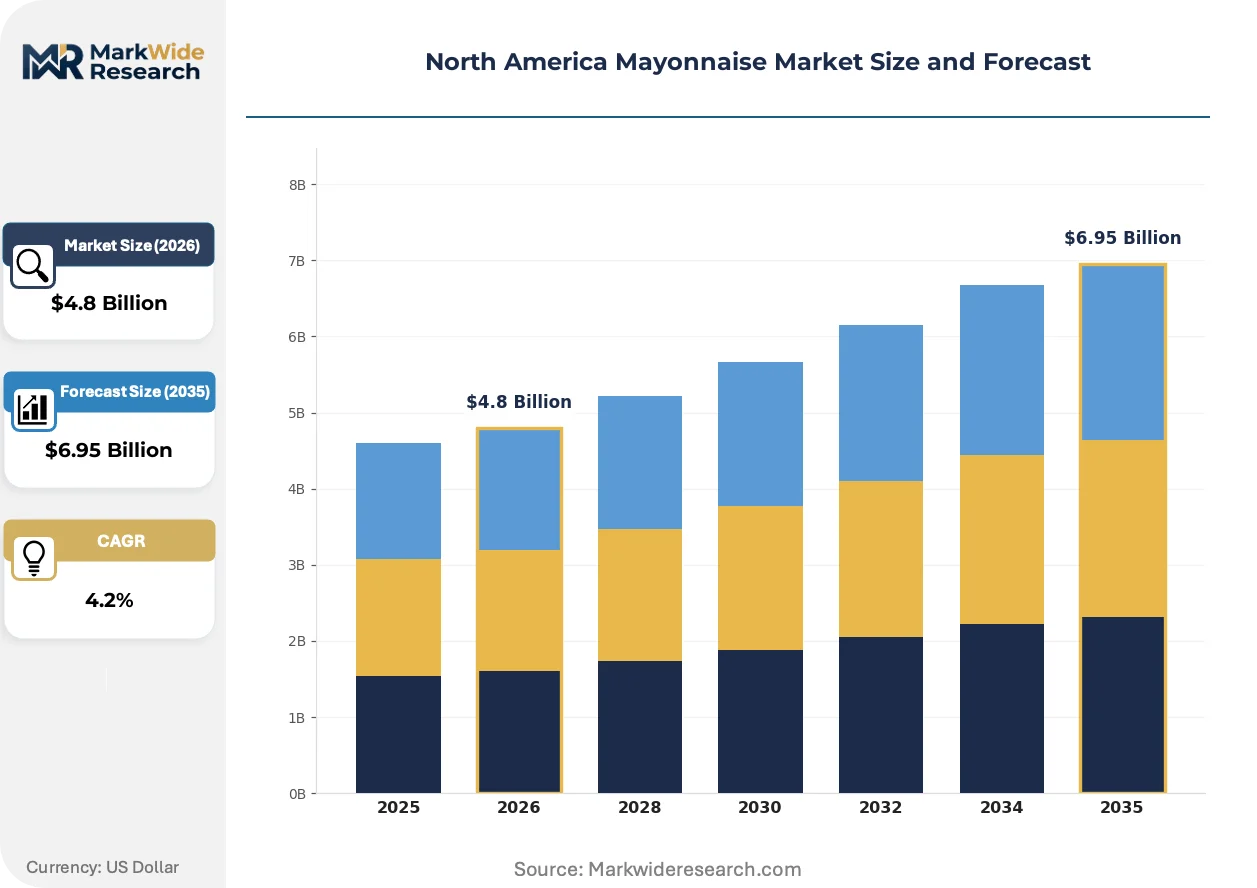
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Low-Fat, Organic, Flavored Packaging Type: Glass Jar, Plastic Bottle, Pouch, Bulk Container Distribution Channel: Online, Supermarket, Convenience Store, Food Service End User: Households, Restaurants, Cafeterias, Food Manufacturers |
| Companies Covered | Kraft Heinz, Unilever, McCormick & Company, Best Foods, Duke's, Hellmann's, Sir Kensington's, Blue Plate, Del Monte Foods, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Mayonnaise Market Strategic Shifts & Innovations
Reformulation around alternative emulsification systems is the dominant technical trajectory, with manufacturers racing to deliver shelf-stable products that satisfy clean-label demands without sacrificing texture integrity.
High-pressure processing is migrating from niche organic lines toward mainstream mayonnaise production as a non-thermal pasteurization method. Mid-size manufacturers in the Southeast food manufacturing corridor are adopting HPP equipment to extend refrigerated product shelf life without chemical preservatives. This technology is migrating from premium-positioned SKUs toward standard retail tiers, compressing the price premium previously commanded by clean-label products.
FDA enforcement of updated 21 CFR 101.9 nutrition labeling rules is reshaping sodium disclosure practices across packaged mayonnaise. The regulation requires single-serve condiment packets to display full nutrition facts, compelling foodservice suppliers to reformulate or risk losing chain restaurant contracts. Food manufacturers supplying institutional channels are most affected, accelerating sodium reduction timelines to maintain procurement relationships.
Foodservice buyers are consolidating procurement through direct manufacturer relationships, bypassing traditional broadline distributors for mayonnaise and sauce categories. Regional restaurant chains in the Midwest are negotiating direct supply agreements with producers, capturing volume discounts and custom formulation services. This concentration is most visible in the quick-service segment, where procurement teams prioritize supply security and cost transparency over distributor convenience.
North America Mayonnaise Market Segmentation
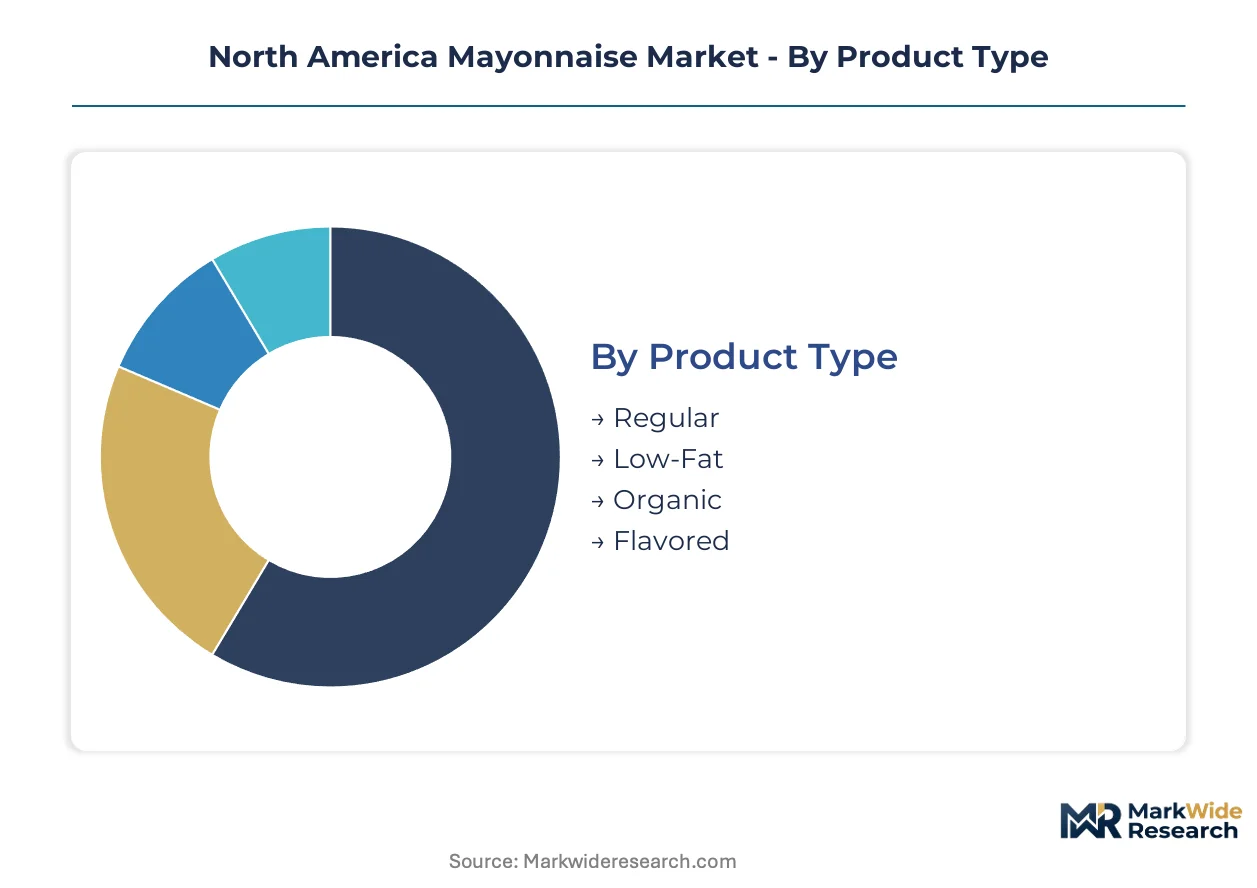
Segmentation in the North America mayonnaise market reveals distinct velocity patterns across product tiers and channel structures. Manufacturers must align production cycles with the turnover differential between institutional foodservice contracts and retail pantry-stock purchasing.
Product Type:
Regular mayonnaise turns over slowest due to pantry-stock purchasing patterns, while flavored variants cycle fastest through specialty retail channels driven by novelty-seeking behavior.
- Regular:Standard oil-in-water emulsion meeting FDA 21 CFR 169.140 identity standards with minimum 65% vegetable oil content. Demand concentrates in the Southeast and Midwest food manufacturing corridors where institutional buyers anchor volume procurement for quick-service restaurant chains.
- Flavored:Emulsion base infused with sriracha, chipotle, or globally-inspired taste profiles that command premium positioning. Younger demographics in urban United States markets drive the steepest velocity through specialty grocery channels seeking differentiated taste experiences beyond conventional mayonnaise.
- Low-Fat:Reformulated emulsions with reduced oil content that fall outside FDA mayonnaise identity standards, requiring "dressing" labeling. Health-conscious households in California and New York states generate primary demand.
- Organic:Certified organic egg and oil inputs with clean-label positioning. Specialty grocery channels in the United States and Canada capture expanding margin pools as consumers trade up from conventional formulations.
Regular mayonnaise anchors the volume base while flavored variants gain share at the steepest rate.
Packaging Type:
Cost tier structures separate premium-positioned formats from economy bulk procurement, with material choice directly determining shelf-life extension capabilities and logistics economics.
- Glass Jar:Premium-positioned format with superior barrier properties supporting extended shelf stability. Northeast United States and Canadian urban markets concentrate demand among consumers prioritizing sustainability perceptions and pantry aesthetics.
- Plastic Bottle:Standard retail format balancing cost efficiency with squeeze-dispensing convenience. Midwest United States supermarket channels generate the highest throughput volume.
- Pouch:Flexible single-serve and family-size formats reducing shipping cube and retail shelf footprint. Foodservice distributors across the United States favor pouches for back-of-house efficiency.
- Bulk Container:Foodservice-grade pails and totes for institutional procurement. Quick-service restaurant chains in the Southeast United States negotiate direct supply agreements capturing volume discounts.
Plastic bottles dominate unit volume while pouches expand most quickly through foodservice channel consolidation.
Distribution Channel:
Customer type concentration splits between household pantry replenishment and institutional procurement, with diverging service requirements and margin structures.
- Supermarket:Primary retail channel with extensive SKU variety across conventional and premium tiers. United States conventional grocery chains anchor volume through promotional programming and private-label placement.
- Food Service:Institutional supply to restaurants, cafeterias, and food manufacturers through broadline and specialty distributors. Direct manufacturer relationships are consolidating procurement in the Midwest United States quick-service segment.
- Online:E-commerce platforms and direct-to-consumer fulfillment capturing subscription and bulk purchasing patterns. Urban United States households drive velocity through convenience-oriented replenishment.
- Convenience Store:Limited assortment of single-serve and travel-size formats for immediate consumption. Highway corridor locations across the United States generate impulse purchasing.
Supermarkets anchor the volume base while foodservice channels gain share at the steepest rate through procurement consolidation.
End User:
Application maturity separates established household consumption from emerging industrial formulation demand, with distinct specification requirements and technical service needs.
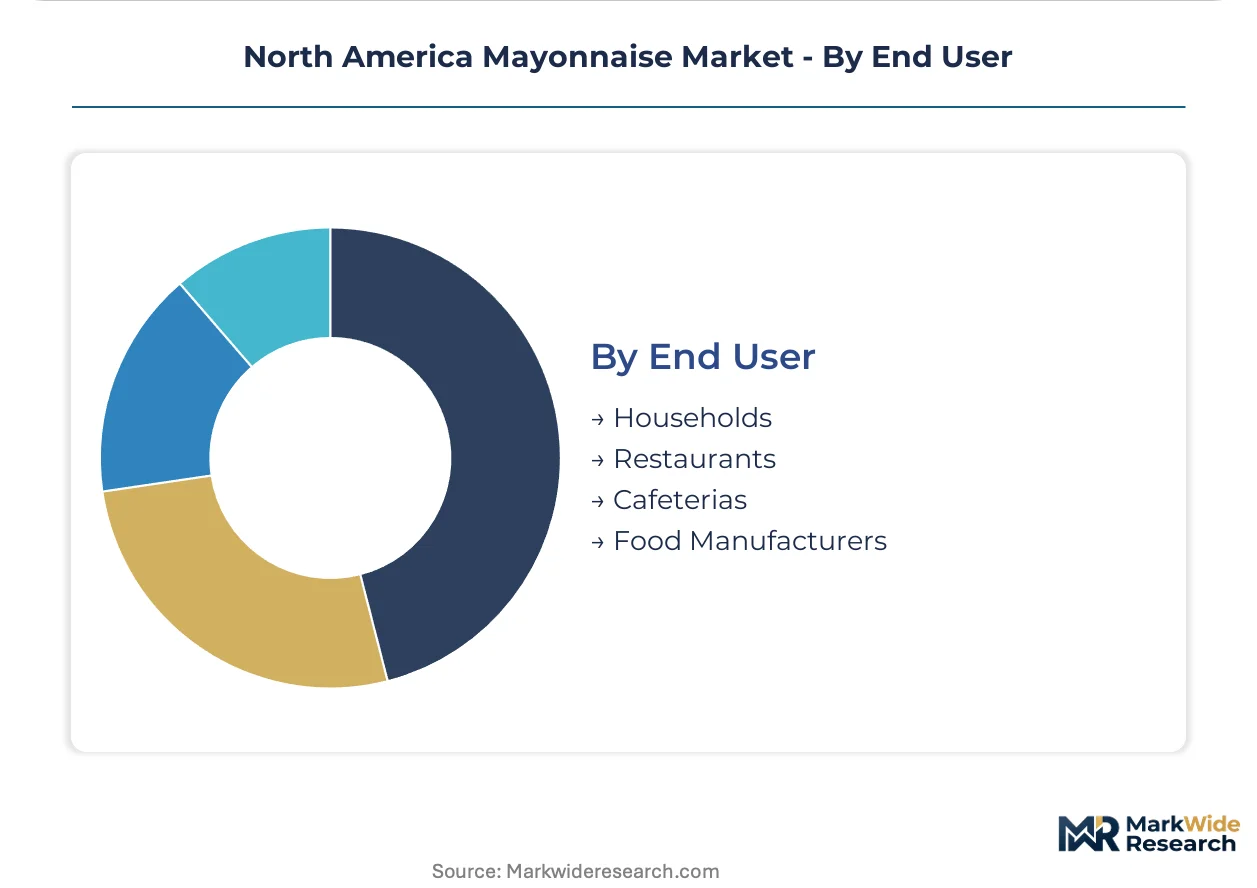
- Households:Consumer pantry purchasing for home meal preparation and sandwich applications. United States suburban and rural markets sustain the largest consumption base per capita.
- Restaurants:Back-of-house sauce preparation and condiment service across independent and chain operations. Quick-service chains across the United States and Canada are broadening menu applications for mayonnaise-based sauces.
- Food Manufacturers:Industrial ingredient supply for packaged salads, sandwiches, and sauce formulations. USDA FSIS compliance requirements apply to mayonnaise components in meat and poultry products.
- Cafeterias:Institutional feeding operations including schools, hospitals, and corporate dining. State-level sodium reduction mandates in California and New York are accelerating reformulation timelines for this channel.
Households anchor the volume base while food manufacturers gain share at the steepest rate through industrial formulation outsourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian mayonnaise production flows primarily into United States foodservice channels through cross-border procurement agreements with quick-service restaurant chains.
United States
Quick-service restaurant chains in the Southeast and Midwest drive institutional procurement volumes for mayonnaise-based sauces. FDA enforcement of updated 21 CFR 101.9 nutrition labeling rules compels sodium reduction across packaged formulations. Chicago anchors food manufacturing corridor activity where direct supply agreements between producers and restaurant chains are consolidating procurement relationships.
Canada
Specialty grocery channels in Toronto and Vancouver generate premium-tier demand for organic and clean-label mayonnaise variants. Health Canada bilingual labeling requirements under the Food and Drug Regulations shape cross-border product specifications. Quebec's food processing cluster supplies reformulated lower-sodium products meeting anticipated California and New York state mandate trajectories.
Mexico
Expanding quick-service restaurant penetration in Mexico City and Monterrey metro areas drives mayonnaise volume growth through localized sauce applications. COFEPRIS food safety standards govern import specifications for United States and Canadian suppliers. Bajío Region food manufacturing parks host co-packing operations serving North American retail private-label programs.
North America Mayonnaise Market Key Industry Players
On the supply side, the industry is bifurcated between multinational packaged food conglomerates and premium-positioned specialty players. Kraft Heinz and Unilever anchor the mass-market tier through dominant retail shelf space and foodservice distribution infrastructure. Sir Kensington's occupies the clean-label premium segment with alternative oil-base formulations. Strategic moves concentrate on direct procurement relationships with quick-service chains and reformulation investments targeting sodium reduction compliance.
Within the multinational tier, Kraft Heinz and Unilever exemplify scale-driven competitive positioning through extensive R&D infrastructure and institutional channel penetration. Sir Kensington's represents the specialty archetype, commanding premium price positioning in avocado-oil-based formulations. These three entities collectively illustrate the market's structural division between volume-anchored incumbents and margin-focused challengers.
| Leading Market Players |
|---|
| Kraft Heinz |
| Unilever |
| McCormick & Company |
| Best Foods |
| Duke's |
| Hellmann's |
| Sir Kensington's |
| Blue Plate |
| Del Monte Foods |
| Others |
Cost & Logistics Intelligence
The I-95 freight corridor linking Southeast food manufacturing clusters to Midwest distribution hubs transmits cost volatility directly into mayonnaise pricing tiers, with fuel surcharges and refrigerated transport rates compressing margins for producers lacking backward integration into oilseed crushing or egg supply operations.
Pricing Analysis
Clean-label emulsification technology creates a three-tier pricing structure across premium, standard, and economy levels, with HPP-processed organic variants commanding shelf premiums over conventional formulations while private-label squeeze bottles anchor value positioning. Price differentiation hinges on certification tier (USDA Organic, Non-GMO Project) and volume scale, with institutional procurement contracts capturing steepest discounts. Cost compression in the standard tier is intensifying because egg yolk and vegetable oil commodity cycles squeeze mid-size manufacturers without captive supply. Quick-service restaurant chains exhibit lowest price sensitivity due to supply security priorities, while independent cafeterias face acute margin pressure from state-level sodium mandate compliance costs.
Supply Chain Analysis
Tariff exposure between the United States and Canadian cross-border ingredient flows dominates supply chain risk assessment for mayonnaise manufacturers serving dual-jurisdiction markets. Production gravity centers on the United States, Canada, and Mexico through integrated North American oilseed processing and egg supply networks. Raw material dependencies draw from soybean and canola oil crushing, egg yolk lecithin extraction, and vinegar acidification feedstocks. Single-source vulnerability concentrates in Midwest egg supply contracts during avian influenza cycles. Distribution runs through foodservice broadline distributors, retail supermarket chains, and direct manufacturer relationships with quick-service restaurant procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mayonnaise procurement platform consolidation among quick-service chains creates network-effects inflection, where direct manufacturer relationships displace distributor intermediaries and interoperability of custom formulation specifications becomes the competitive moat.
For Market Incumbents: Harden formulation IP around egg-reduction emulsification systems to defend against plant-based dressing substitution threats from emerging clean-label entrants. Expand backward integration into Southeast oilseed crushing capacity to neutralize input cost volatility. Secure FDA sodium reduction compliance ahead of California and New York mandate cascades to lock in institutional procurement relationships. For New Entrants and Emerging Players: Establish a beachhead in the organic avocado-oil premium segment where Sir Kensington's has validated consumer willingness to pay for alternative oil bases. Target specialty grocery channels in Canadian urban markets with bilingual-labeled clean-label variants. Leverage high-pressure processing equipment partnerships with Southeast co-packers to bypass capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors clean-label emulsification specialists with proprietary HPP capabilities and direct quick-service chain relationships over legacy volume players facing margin compression. The 5-10 year viability window rewards acquisition targets with sodium-reduction formulation pipelines and cross-border regulatory compliance infrastructure. Monitor California state assembly sodium mandate progression as the inflection signal for broader North American reformulation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Procurement Relationship | Bypasses broadline distributors to capture quick-service chain volume discounts and custom formulation contracts. |
| Sodium Reduction Reformulation | Aligns with FDA 21 CFR 101.9 disclosure rules and anticipated California state mandate trajectories. |
| Avocado-Oil Base Innovation | Commands premium positioning in health-focused retail segments and specialty grocery channels. |
| High-Pressure Processing Adoption | Extends refrigerated shelf life without chemical preservatives for clean-label product lines. |
| Cross-Border Regulatory Compliance | Enables seamless United States-Canada product flow under dual FDA and Health Canada standards. |
Research Approach
Operator-level perspectives from quick-service restaurant procurement directors, mayonnaise manufacturing plant managers, foodservice distribution channel partners, and regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation through FDA 21 CFR filings, USDA FSIS guidance documents, Health Canada Food and Drug Regulations, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs across the analysis window.
Scenario-bracketing framed the analytical approach with base, optimistic, and conservative demand trajectories across the projection horizon. Segmentation dimensions modeled include product type tier, packaging format, distribution channel structure, and end-user application intensity. CAGRs derived from historical trend extrapolation adjusted for regulatory inflection points and technology adoption S-curves. Forecast inputs incorporated quick-service restaurant expansion pipelines, state-level sodium mandate legislative tracking, and clean-label emulsification technology maturity curves.
Stress conditions across egg commodity price spikes, avian influenza supply disruptions, and tariff regime shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about quick-service menu application expansion rates and regulatory compliance timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
West Africa Mayonnaise Market
Condiments & Sauces
Mayonnaise Sauce Market
Condiments & Sauces
Barbecue Sauce Market
Condiments & Sauces
Australia and New Zealand Tomato Sauce Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Cheese Sauce Market
Condiments & Sauces
Low Calorie Peanut Sauce Market
Condiments & Sauces
Pesto Sauces Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Compound Condiments Market
Condiments & Sauces
Pasta Sauce Market
Condiments & Sauces
Sour Dressings Market
Condiments & Sauces
Ketchup Concentrates Market
Condiments & Sauces
Vegan Cheese Sauce Market
Condiments & Sauces
Vegan Sauces Market
Condiments & Sauces
Latin America Pasta Sauce Market