
 Latin America Pasta Sauce Market | 2026-2036
Latin America Pasta Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Pasta Sauce Market Intelligence
Brazilian tomato processing capacity is hardening as domestic paste producers expand output to serve sauce manufacturers. Unilever PLC leverages its refrigerated logistics network to anchor shelf-stable distribution across southeastern Brazil. Nestlé S.A. competes through Maggi brand recognition in lower-income households, while Grupo Herdez sustains share in Mexico's central highlands through regional recipe familiarity.
Latin America pasta sauce comprises tomato-based, cream-based, and oil-based emulsions formulated with acidity regulators, preservatives, and flavor compounds for shelf-stable or chilled retail and food service application. Marinara formulations dominate volume due to lower input costs and cross-cultural acceptance, though Alfredo sauces generate higher per-unit margins in Brazilian and Mexican urban supermarkets. Pouch packaging is expanding fastest among convenience-oriented urban households, while glass jars retain primacy in premium-positioned supermarket channels across the region.
ANVISA governs additive thresholds and nutritional labeling in Brazil, while Mexico's COFEPRIS enforces contaminant limits that shape import acceptance criteria for regional suppliers. Argentina's national food code mandates origin disclosure for tomato content, influencing sourcing strategies for manufacturers operating across Mercosur trade zones. Stakeholders must monitor evolving front-of-pack warning label requirements, as Chile's existing octagon system pressures neighboring regulators toward stricter consumer communication standards.
Market Dynamics
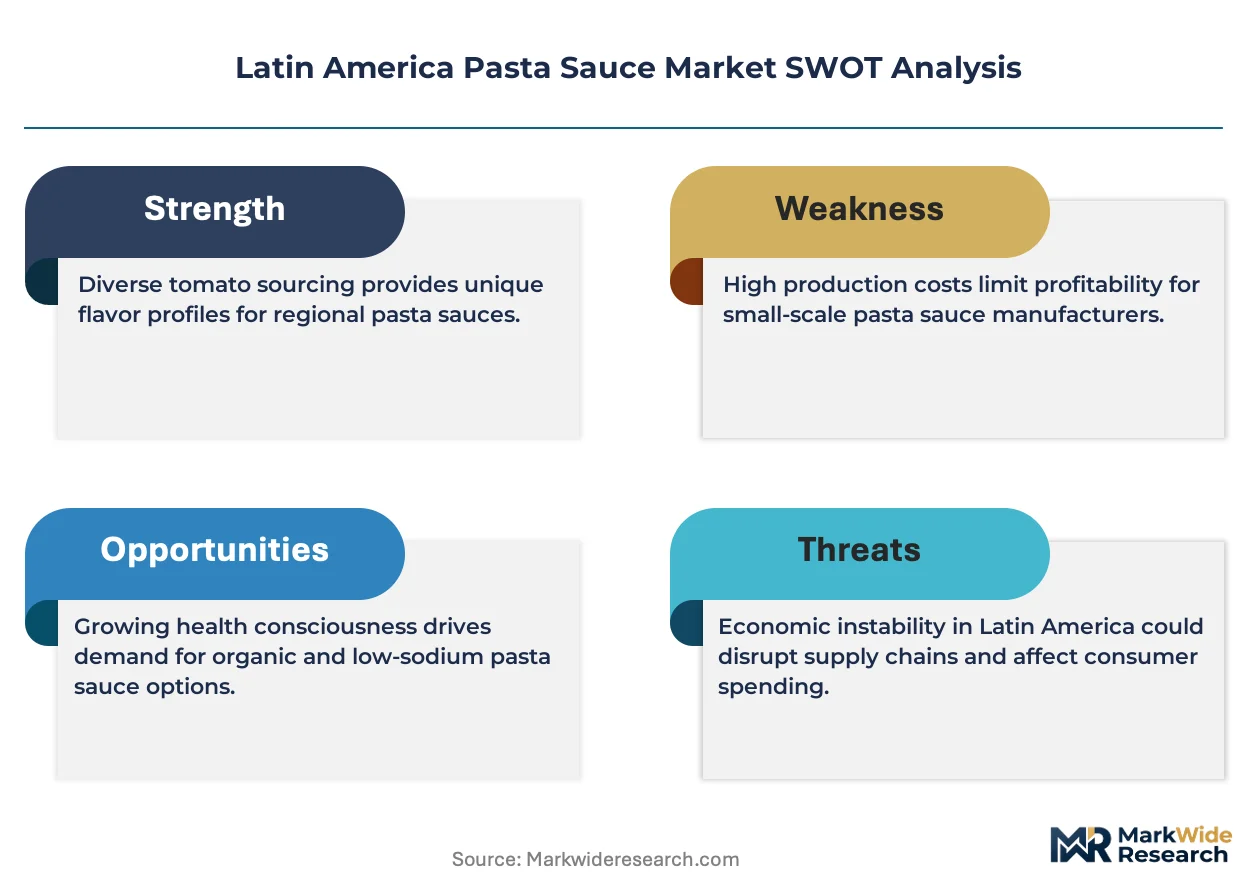
ANVISA's tightening front-of-pack warning label requirements are forcing reformulation across Brazil's pasta sauce sector, compressing margins for manufacturers dependent on sodium and sugar-heavy formulations while accelerating clean-label investment cycles.
Growth Catalysts
- Food service expansion:Brazilian, Mexican, and Argentine restaurant operators are broadening pasta menu portfolios, pulling packaged sauce procurement volumes upward through institutional channels.
- COFEPRIS contaminant standards:Mexico's enforcement of stricter import acceptance criteria is elevating quality thresholds for regional suppliers, filtering out subscale competitors and consolidating compliant manufacturers.
- Pouch packaging adoption:Convenience-oriented urban households in São Paulo and Mexico City are driving rapid format migration from glass to flexible packaging, reducing logistics costs and expanding distribution reach.
Market Restraints
- Tomato paste input volatility:Brazilian domestic paste production expansion has not eliminated seasonal price swings, squeezing sauce manufacturer margins during harvest gaps.
- Mercosur origin disclosure mandates:Argentina's national food code requires explicit tomato provenance labeling, complicating cross-border sourcing strategies for manufacturers operating across trade zones.
- Chilled distribution infrastructure gaps:Refrigerated logistics networks remain concentrated in southeastern Brazil, limiting premium chilled sauce penetration into northern and central markets.
Strategic Opportunities
- Central Mexican highlands penetration:Regional recipe familiarity in states surrounding Mexico City creates white space for heritage-formula sauces tailored to local palate preferences.
- Chilean octagon warning spillover:Anticipated regulatory convergence across southern cone markets positions early clean-label adopters to capture share as neighboring jurisdictions tighten disclosure rules.
- Alfredo margin expansion:Cream-based formulations command higher per-unit economics in Brazilian and Mexican urban supermarkets, rewarding manufacturers with dairy supply chain control.
Industry Challenges
- Reformulation timeline compression:Accelerating regulatory cycles in Brazil demand faster clean-label transitions than existing R&D pipelines can accommodate without external formulation partnerships.
- Cross-border certification complexity:Divergent additive thresholds between ANVISA, COFEPRIS, and Mercosur harmonization delays force manufacturers to maintain multiple product specifications for integrated regional operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Pasta Sauce Market |
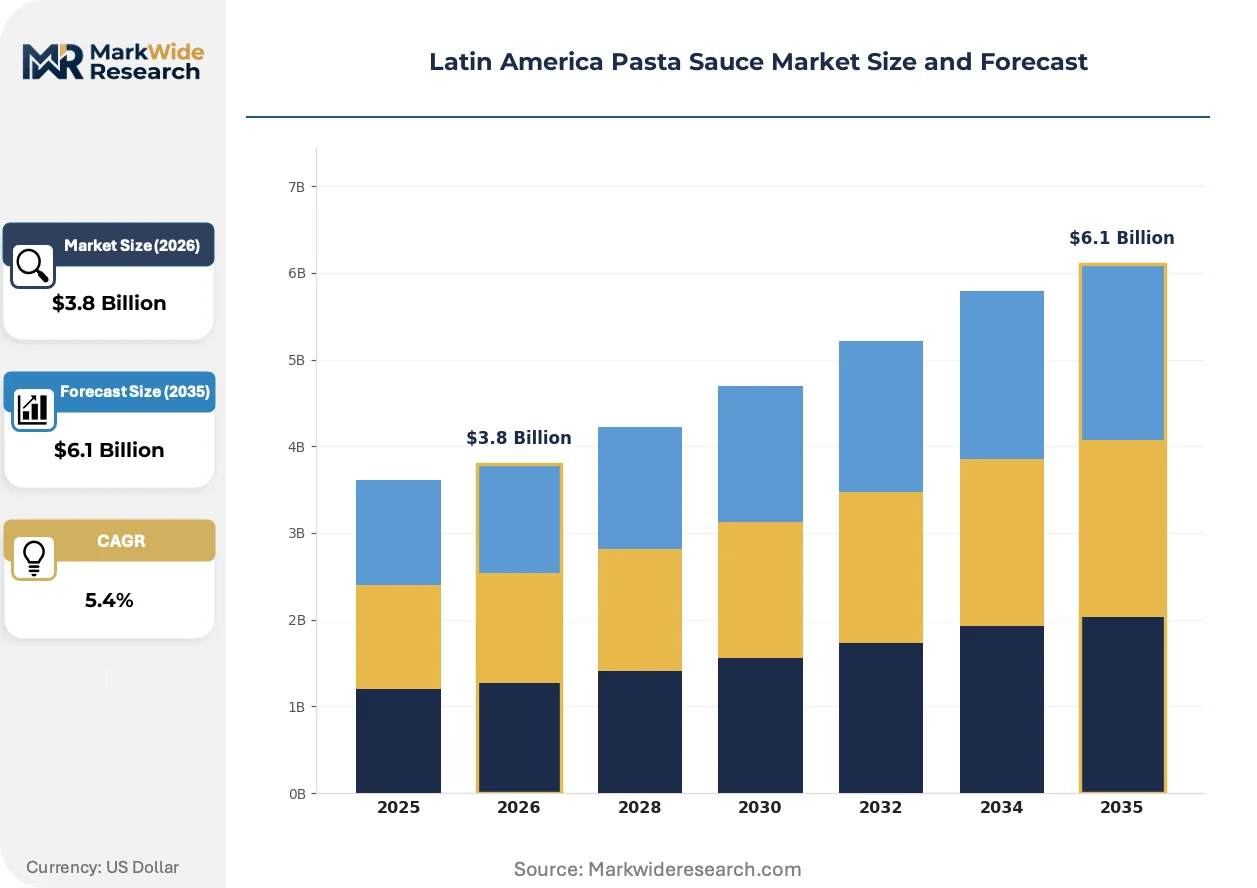
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Marinara, Alfredo, Pesto, Arrabbiata End User: Households, Restaurants, Food Services, Catering Distribution Channel: Supermarkets, Online Stores, Convenience Stores, Wholesale Packaging Type: Bottles, Jars, Tetra Packs, Pouches |
| Companies Covered | Unilever PLC, Bertolli (Deoleo S.A.), Nestlé S.A., La Moderna, Grupo Herdez, Barilla Group, Mizkan America Inc., Grupo Nutresa, The Kraft Heinz Company, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Pasta Sauce Market Strategic Shifts & Innovations
Refrigerated logistics integration is blurring the boundary between shelf-stable and chilled sauce categories, enabling new product architectures that trade extended ambient stability for cleaner ingredient panels and fresher positioning.
Retort pouch technology is modularizing production economics for mid-scale manufacturers. Brazilian packaging converters are installing high-speed form-fill-seal lines capable of handling acidic tomato emulsions at throughput rates previously reserved for glass jar operations. This equipment democratization is compressing minimum efficient scale thresholds and enabling regional challengers to contest national brand dominance in specific state markets.
ANVISA's evolving front-of-pack warning label framework is restructuring competitive positioning around sodium disclosure. Manufacturers operating in São Paulo state are pre-emptively reducing salt content to avoid octagon placement, accepting flavor profile modifications to maintain shelf placement in premium supermarket channels. This regulatory anticipation is spreading formulation standards northward into markets where formal enforcement remains less stringent.
Urban household purchasing is fragmenting across channel types. Traditional supermarket sauce sections in Mexico City and Buenos Aires are losing traffic to convenience store impulse purchases and direct-to-restaurant food service supply relationships. Manufacturers are responding with channel-specific pack sizes and formulation variants rather than uniform national SKUs, multiplying portfolio complexity.
Latin America Pasta Sauce Market Segmentation
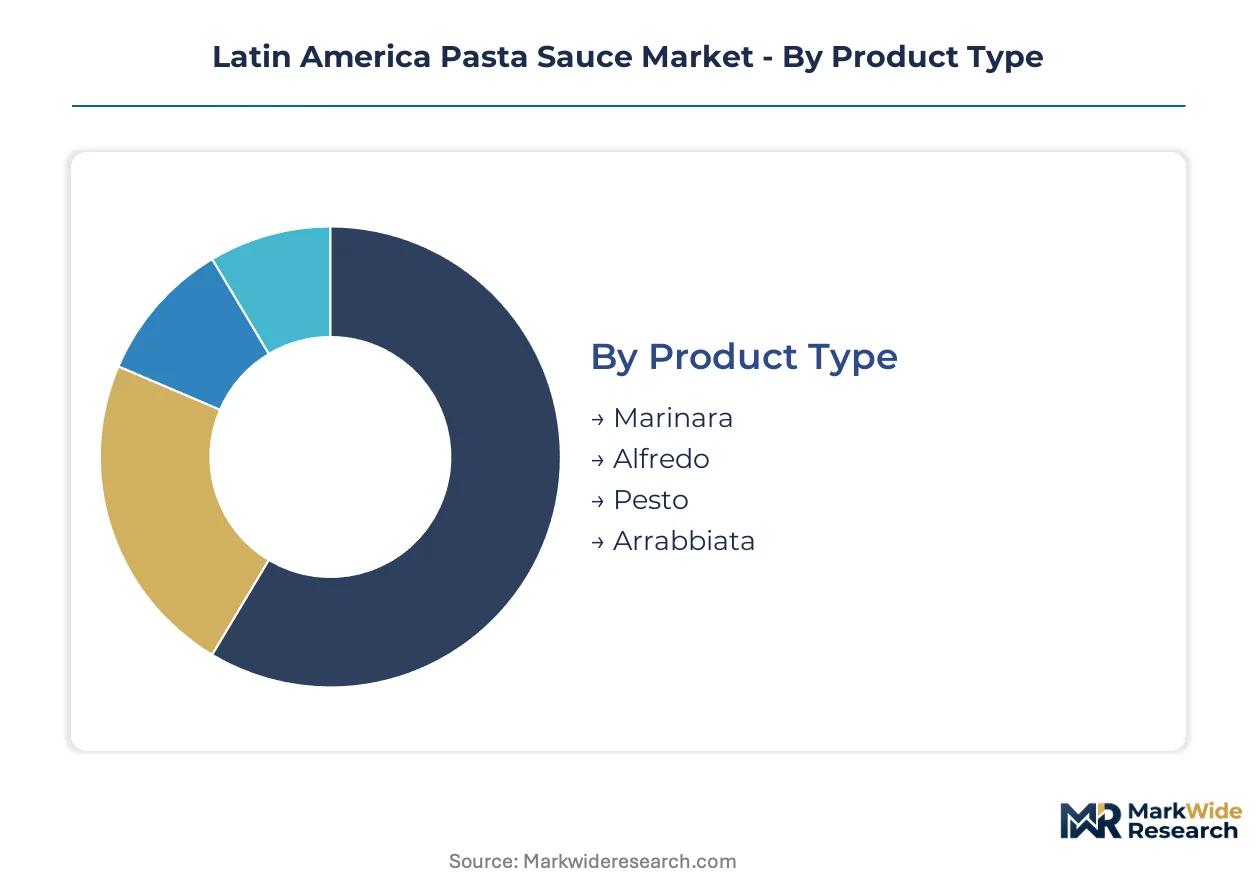
Pasta sauce manufacturers in Latin America must navigate divergent technical requirements and channel economics across product formulations, end-use applications, and packaging formats. ANVISA labeling mandates and COFEPRIS import standards force segment-specific reformulation strategies that reshape competitive positioning.
Product Type:
Tomato paste supply concentration in São Paulo state and dairy processing clusters in Minas Gerais dictate regional production economics for sauce categories.
- Marinara:Tomato-based emulsion with acidity regulators and shelf-stable preservatives formulated for ambient distribution. Brazilian food service operators in Rio de Janeiro and São Paulo drive procurement volumes through institutional channels, though ANVISA sodium disclosure thresholds pressure salt reduction.
- Alfredo:Cream-based dairy emulsion requiring refrigerated logistics or retort processing for ambient stability. Urban supermarkets in Mexico City and São Paulo generate higher per-unit margins, rewarding manufacturers with captive dairy supply arrangements.
- Pesto:Oil-based herb suspension with pine nut or walnut particulates, typically oil-preserved without thermal processing. Brazilian import dependency for European pine nuts creates input cost volatility.
- Arrabbiata:Chili-infused tomato variant with elevated capsaicin content and regional spice profiles. Mexican central highlands consumption concentrates around heritage recipe preferences.
Marinara absorbs the bulk of installed capacity; Alfredo is expanding most quickly.
End User:
Channel-specific formulation requirements separate mass-market retail from food service procurement economics.
- Households:Individual and family-size packaging with front-of-pack labeling compliance for supermarket retail. São Paulo state urban penetration of premium-positioned SKUs outpaces northern Brazilian markets.
- Restaurants:Bulk-format procurement with institutional pricing and consistent batch specifications. Brazilian pasta menu expansion drives sauce volume through distributor relationships.
- Food Services:Central kitchen and chain restaurant supply with customized viscosity and flavor profiles. COFEPRIS contaminant standards filter supplier qualification in Mexican operations.
- Catering:Event and institutional volume procurement with extended ambient stability requirements. Argentine Mercosur origin disclosure mandates complicate cross-border sourcing.
Households command the largest revenue base; food services are climbing the fastest.
Distribution Channel:
Logistics infrastructure maturity determines format accessibility and margin capture across urban and peripheral markets.
- Supermarkets:Premium jarred sauce placement with front-of-pack positioning competition. Glass jar primacy persists in Brazilian and Mexican urban premium channels.
- Online Stores:Direct-to-consumer fulfillment with expanded SKU availability beyond physical shelf constraints. São Paulo and Mexico City last-mile density enables chilled sauce experimentation.
- Convenience Stores:Impulse-oriented small-format purchasing with pouch and single-serve positioning. Urban traffic fragmentation redirects volume from traditional supermarket sections.
- Wholesale:Institutional and restaurant supply through distributor networks with volume pricing structures. Brazilian southeastern logistics concentration limits northern market penetration.
Supermarkets retain the dominant share; online stores are gaining share fastest.
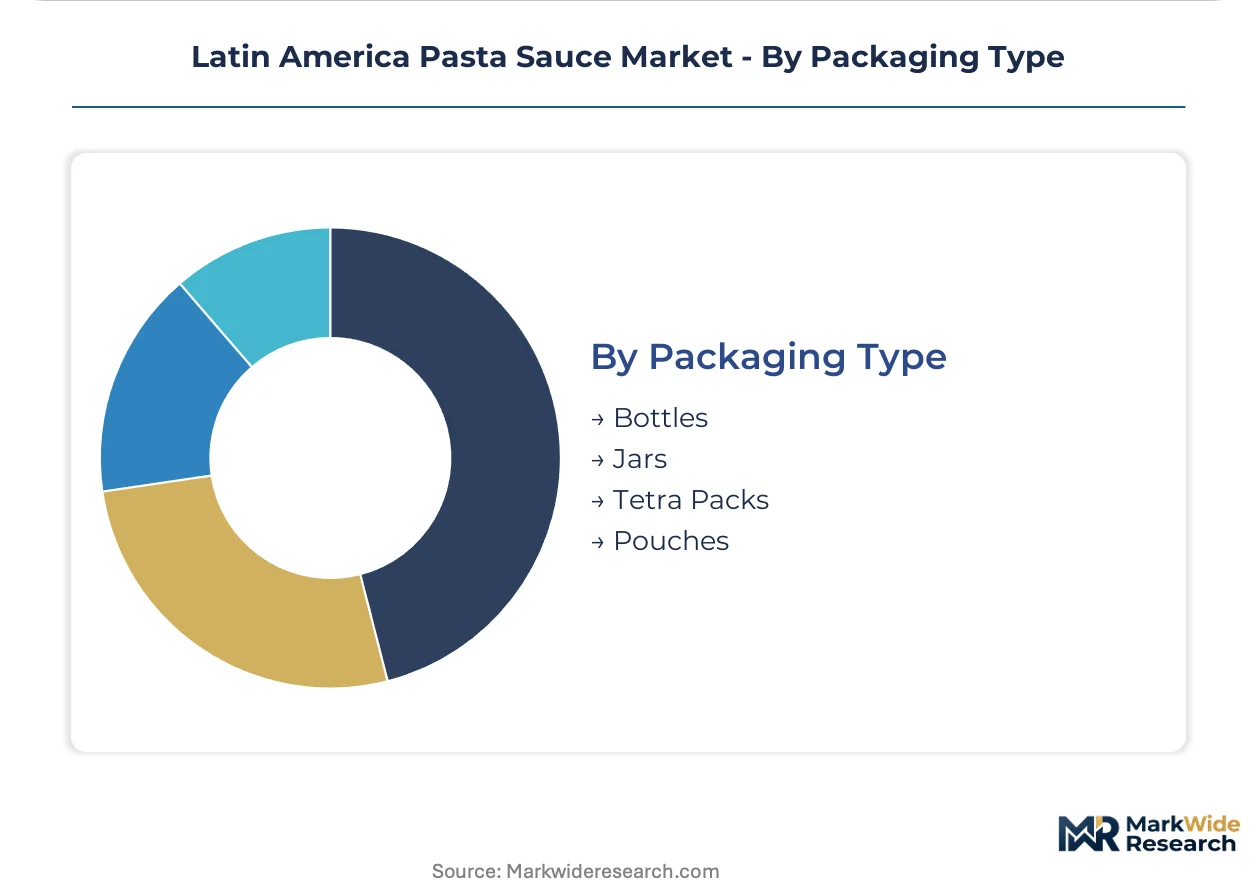
Packaging Type:
Equipment investment thresholds and material cost trajectories reshape competitive entry barriers across format categories.
- Bottles:PET and HDPE containers for squeezable dispensing with reduced breakage versus glass. Brazilian converter capacity expansion enables mid-scale manufacturer access.
- Jars:Glass containers with premium positioning and established consumer trust in traditional retail. ANVISA recycling disclosure requirements add labeling complexity.
- Tetra Packs:Aseptic carton technology for extended ambient shelf life with rectangular logistics efficiency. European equipment dependency elevates capital requirements.
- Pouches:Flexible retort or form-fill-seil formats with reduced shipping weight and expanded distribution reach. Brazilian packaging converter investment is compressing minimum efficient scale thresholds.
Jars retain the largest installed base; pouches show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's tomato processing belt anchors Latin American pasta sauce manufacturing, concentrating paste production capacity that feeds formulation facilities across Brazil's southeastern industrial corridor.
Brazil
ANVISA's front-of-pack warning label mandates are forcing sodium reduction across São Paulo-based manufacturers. Urban households in Greater São Paulo drive premium sauce penetration rates that outpace northern states. Unilever PLC leverages refrigerated logistics networks to anchor shelf-stable distribution throughout the southeastern cluster.
Mexico
COFEPRIS contaminant enforcement elevates import acceptance thresholds for tomato paste suppliers. Mexico City Metro restaurants are expanding pasta menu portfolios, pulling institutional sauce procurement through distributor channels. Grupo Herdez sustains market presence in the central highlands through regional recipe familiarity.
Argentina
Mercosur origin disclosure requirements under the national food code complicate cross-border tomato sourcing strategies. Buenos Aires supermarkets retain glass jar primacy for premium-positioned sauces. Domestic paste producers in Mendoza province are expanding output to serve reformulating manufacturers.
Chile
The octagon warning label system pressures neighboring regulators toward stricter consumer communication standards. Santiago's urban retail channels are experimenting with chilled sauce distribution where refrigerated infrastructure permits. Early clean-label adopters position to capture share as regulatory convergence spreads.
Colombia
Bogotá's convenience store networks are redirecting household purchasing from traditional supermarket sauce sections. Pouch packaging adoption accelerates among urban households seeking format convenience. Colombian distributors are expanding procurement relationships with Brazilian paste suppliers to bypass import cost volatility.
Latin America Pasta Sauce Market Key Industry Players
Global majors compete with regional champions across formulation expertise and channel access. The market structures around three tiers: multinational CPG conglomerates with refrigerated logistics scale, regional heritage brands with recipe authenticity positioning, and mid-scale challengers exploiting pouch packaging equipment democratization. Strategic moves concentrate on clean-label reformulation partnerships and state-level distributor acquisitions.
Within the heritage-formula tier, Grupo Herdez exemplifies regional recipe anchoring, while La Moderna occupies a position bridging industrial pasta and sauce supply integration. Among multinational conglomerates, Nestlé S.A. represents mass-market penetration through brand recognition in lower-income households. These three archetypes illustrate the competitive vectors shaping procurement relationships and formulation investment cycles.
| Leading Market Players |
|---|
| Unilever PLC |
| Bertolli (Deoleo S.A.) |
| Nestlé S.A. |
| La Moderna |
| Grupo Herdez |
| Barilla Group |
| Mizkan America Inc. |
| Grupo Nutresa |
| The Kraft Heinz Company |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap tomato processors across São Paulo state and Minas Gerais anchor supply discipline through generational control of paste production capacity, translating concentrated upstream ownership into pricing power that resists commodity volatility during harvest gaps.
Pricing Analysis
Warranty and freshness guarantees remain unbundled from base product pricing, with chilled sauce premiums capturing cold-chain service costs separately from shelf-stable equivalents. Three-tier pricing structure across premium, standard, and economy levels stratifies by sodium disclosure compliance and ingredient panel complexity under ANVISA rules. Pricing pressure stems from tomato paste input seasonality squeezing manufacturer margins when Brazilian harvest volumes dip. Food service buyers exhibit highest price sensitivity due to bulk procurement volumes, while São Paulo urban households absorb premium positioning with lower elasticity.
Supply Chain Analysis
Freight cost differentials between glass jar and pouch formats are restructuring distribution economics across Brazil's southeastern logistics corridor versus northern peripheral markets. Supply concentrates in Brazil, Mexico, and Argentina, with Brazilian paste production feeding formulation facilities across Mercosur trade zones. Raw material dependencies center on domestic tomato paste, imported European pine nuts for pesto variants, and dairy cream inputs from Minas Gerais processing clusters. Single-source vulnerability runs through São Paulo state tomato belt concentration. Distribution runs through wholesale distributor networks for institutional channels and supermarket retail for household penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazilian tomato paste capacity expansion has not eliminated harvest-gap bottlenecks, propping manufacturer pricing power during seasonal supply contractions and sustaining margin capture for integrated processors.
For Market Incumbents: Lock in refrigerated logistics partnerships across southeastern Brazil to defend chilled sauce positioning against emerging pouch-format challengers. Secure backward integration into Minas Gerais dairy supply to capture Alfredo margin premiums. ANVISA sodium disclosure tightening threatens legacy formulations; accelerate clean-label R&D cycles through external formulation partnerships.
For New Entrants and Emerging Players: Begin with pouch packaging deployment targeting São Paulo convenience store networks where format migration outpaces incumbent adaptation. Mexico's central highlands present white-space opportunity for heritage-formula Arrabbiata variants tailored to regional palate preferences. Direct-to-restaurant supply relationships bypass supermarket slotting fee barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Brazilian manufacturers with installed retort pouch capacity and ANVISA compliance infrastructure during reformulation cost crunches. Long-term viability hinges on clean-label transition completion and dairy supply chain control. Monitor COFEPRIS enforcement intensity as signal for Mexican market consolidation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Partnership | ANVISA sodium thresholds force faster R&D cycles than internal pipelines accommodate. |
| Pouch Packaging Capacity Expansion | Brazilian converter investment democratizes format access for mid-scale challengers. |
| Refrigerated Logistics Network Extension | Unilever's southeastern cold-chain infrastructure anchors premium chilled distribution. |
| Heritage Recipe Regional Positioning | Grupo Herdez demonstrates central highlands familiarity sustains share against global brands. |
| Dairy Supply Chain Integration | Minas Gerais cream sourcing control captures Alfredo margin premiums in urban supermarkets. |
Research Approach
Document review covered ANVISA regulatory filings, COFEPRIS import standards, Mercosur trade documentation, and Brazilian customs records, complemented by interviews with tomato paste procurement managers at sauce manufacturers, category buyers at São Paulo supermarket chains, food service distribution executives, and packaging converter operations directors. Secondary validation drew from Nielsen retail audit data, national food code amendments, and industry association processing statistics. Bottom-up volume modeling triangulated against top-down macro consumption trends.
Cross-referencing historical price transmission patterns with panel input from supply chain stakeholders anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product formulation type, end-use channel, packaging format, and regional regulatory cluster. CAGRs derived from iterative reconciliation of input cost trajectories, volume elasticity assumptions, and penetration rate projections for emerging formats. Tomato paste harvest cycle variability and front-of-pack warning label implementation timelines served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; pouch packaging adoption rates and online channel penetration carry tighter precision than long-term regulatory convergence assumptions across southern cone markets. Forecasts reflect documented assumptions about ANVISA enforcement intensity and COFEPRIS import screening rigor. Stakeholders should weight assumptions against their own operating context and regional supply chain exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Global Fish Sauce Market
Condiments & Sauces
Global Hot Pot Condiment Market
Condiments & Sauces
Dry Cooking Sauces Market
Condiments & Sauces
Sweet and Savory Spread Market
Condiments & Sauces
Low Calorie Peanut Sauce Market
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Table Sauce Market
Condiments & Sauces
Barbecue Sauce Market
Condiments & Sauces
Cooking Sauces Market
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Ketchup Market
Condiments & Sauces
Cheese Sauce Market
Condiments & Sauces
Cocktail Syrups Market