
 Condiments Market | 2026-2036
Condiments Market Size, Share, and Industry Trends Forecast 2026-2036
Condiments Market Intelligence
Single-serve sachet and pouch bundling is expanding across food service channels, altering how restaurants and cafeterias manage portion control and inventory turnover. The Kraft Heinz Company leverages its manufacturing scale to dominate ketchup and mayonnaise supply contracts with major quick-service chains. Kikkoman Corporation anchors its position through in-house brewing of naturally fermented soy sauce, sustaining premium pricing in Asian and Western markets simultaneously. Unilever PLC competes across multiple condiment categories through its global distribution network and brand portfolio depth.
Condiments comprise shelf-stable flavor-enhancing preparations including emulsified sauces, fermented liquids, acidified relishes, and oil-based infusions, typically formulated with vinegar, salt, sugar, spices, and stabilizers to achieve pH below 4.6 for ambient preservation and food safety. These products serve industrial food manufacturers, food service operators, and retail consumers seeking taste customization, moisture retention, and visual appeal in prepared dishes. Soy sauce and hot sauce represent the fastest-growing product type segments, driven by Asian cuisine proliferation and heat-preference trends in younger demographics. Bottles retain dominance in retail channels, while sachets and pumps capture margin pools in food service and institutional catering where labor efficiency dictates packaging choice.
FDA oversight of acidified food regulations and EFSA enforcement of additive labeling under EU frameworks shape formulation transparency and import compliance requirements for multinational suppliers. The USDA's organic certification and EPA guidelines on packaging sustainability further constrain material selection and supply chain design for condiment producers. Stakeholders must monitor evolving sodium reduction mandates and plastic packaging restrictions across multiple jurisdictions to anticipate reformulation costs and channel access barriers.
Market Dynamics
Clean-label reformulations and sodium reduction mandates from the FDA and EFSA are forcing condiment manufacturers to rebuild formulation pipelines and renegotiate supply contracts with food service buyers.
Growth Catalysts
- Asian Cuisine Proliferation:Soy sauce and fermented chili pastes are displacing traditional Western sauces in quick-service and casual dining menus across North America and Europe.
- Food Service Automation:Pump dispensers and portion-control packaging are accelerating throughput in high-volume cafeteria and catering operations.
- Clean-Label Mandates:EFSA enforcement of additive transparency under EU frameworks is pulling reformulated products onto retail shelves ahead of compliance deadlines.
Market Restraints
- Input Cost Volatility:Soybean and chili pepper harvest fluctuations in Argentina and India are compressing margin stability for fermented sauce producers.
- Supply Concentration Risk:Glass bottle manufacturing clusters in China dominate global packaging supply, exposing brands to freight rate spikes and port congestion.
- Technical Limitation:Natural preservation methods struggle to achieve shelf stability below 4.6 pH without synthetic acidulants, constraining clean-label claims.
Strategic Opportunities
- Underpenetrated Geography:Sub-Saharan African markets show minimal penetration for premium hot sauce and ethnic condiment categories.
- Regulatory Tailwind:USDA organic certification incentives are opening shelf space in US natural grocery channels for small-batch producers.
- Channel Innovation:Direct-to-foodservice subscription models are bypassing traditional distributor markups for independent restaurant chains.
Industry Challenges
- Reformulation Timeline Compression:FDA sodium reduction targets are forcing R&D cycles below 18 months for major ketchup and mayonnaise portfolios.
- Packaging Transition Costs:EPA guidelines on plastic sustainability are requiring capital redeployment into recyclable film and paper-based sachet alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Condiments Market |
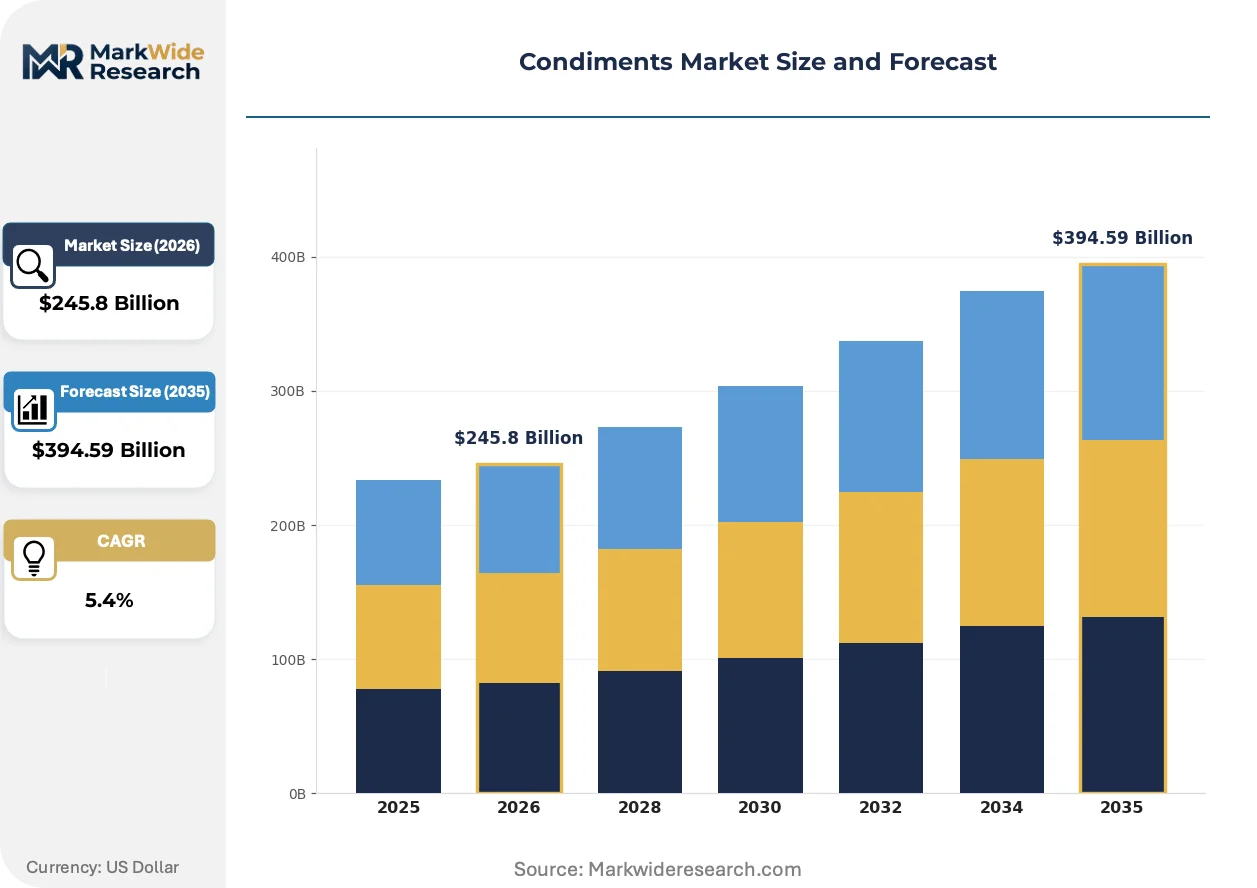
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $394.59 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ketchup, Mayonnaise, Mustard, Soy Sauce, Hot Sauce, Relish Packaging Type: Bottles, Sachets, Jars, Tubs, Pumps, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Food Service, Specialty Stores, Wholesalers End User: Household Consumers, Food Manufacturers, Restaurants, Catering Services, Hotels, Cafeterias |
| Companies Covered | Conagra Brands Inc., Kikkoman Corporation, The Kraft Heinz Company, Kewpie Corp, Hormel Foods Corporation, Unilever PLC, Nestle SA, Lee Kum Kee Company Ltd, McCormick & Company Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Condiments Market Strategic Shifts & Innovations
Condiment innovation is bifurcating between artisanal fermentation revival and industrial automation, with regulatory pressure acting as the forcing mechanism for both tracks.
High-pressure processing technology is consolidating shelf-stable sauce manufacturing by eliminating thermal degradation of volatile flavor compounds. Mid-sized regional producers in California and Lombardy are adopting HPP lines to compete with retort-based national brands. This consolidation is compressing the traditional advantage of large-scale thermal processing infrastructure.
EFSA's tightened enforcement of additive labeling under EU frameworks is mandating front-of-pack disclosure for artificial preservatives and colorants. Industrial manufacturers are reformulating with cultured dextrose and fruit-derived acids to maintain shelf life. Premium private-label programs in German and French retail are most affected, accelerating clean-label certification timelines.
Food service procurement is fragmenting as independent restaurant groups bypass broadline distributors for direct relationships with specialty condiment co-packers. This disintermediation is most visible in US coastal metropolitan markets where chef-driven concepts prioritize provenance storytelling over national brand recognition. Smaller producers are capturing margin pools previously absorbed by distributor markups.
Condiments Market Segmentation
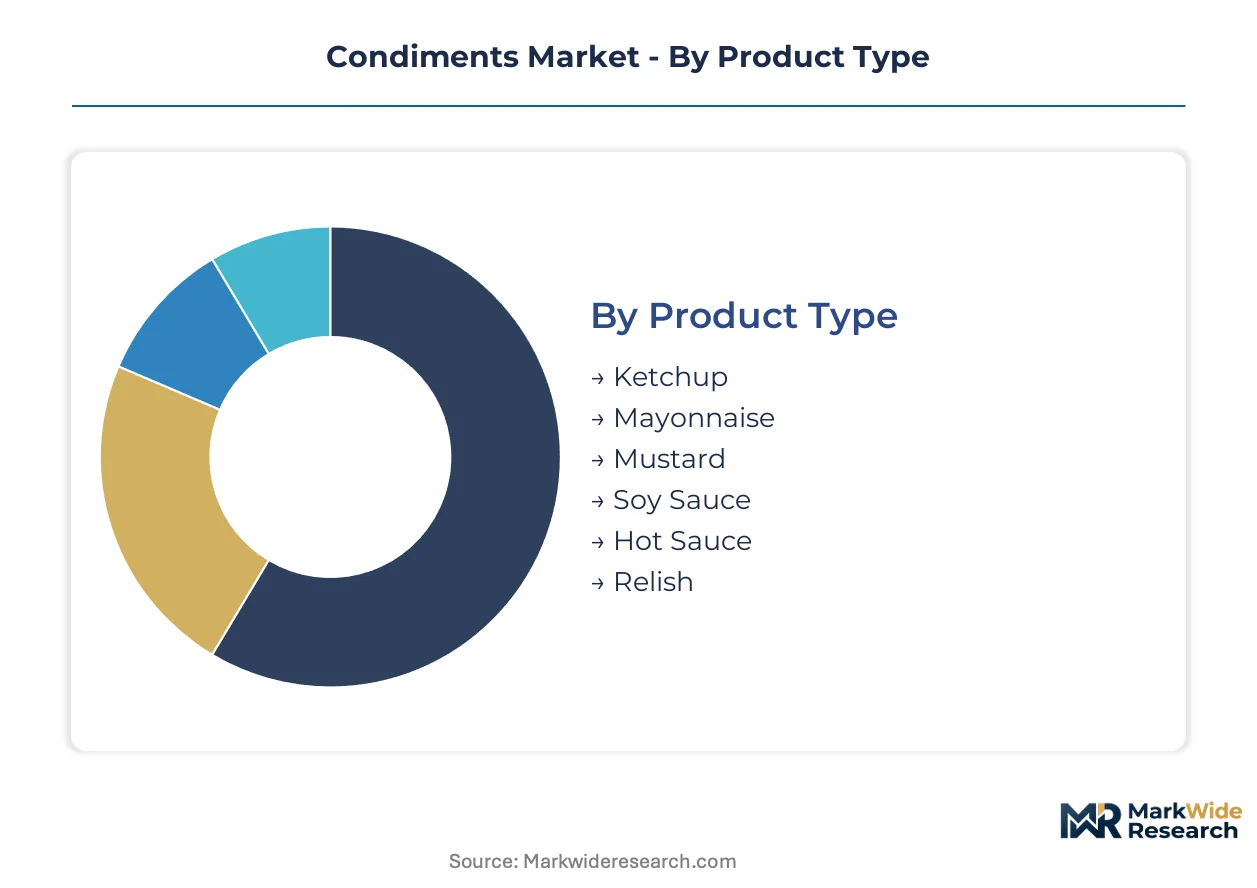
Condiment manufacturers deploy capital asymmetrically across product lines and packaging formats. Fermentation infrastructure, acidification systems, and packaging automation drive divergent investment profiles that reshape competitive positioning.
Product Type:
Fermentation-based categories command the steepest upfront capital outlays for brewing vessels, climate-controlled aging facilities, and microbiological quality systems.
- Soy Sauce:Naturally brewed variants require 6-12 month fermentation cycles in temperature-controlled cedar or stainless vats. Demand concentrates in Japanese and Korean restaurant supply chains across California and New York, driven by umami-forward menu engineering in fast-casual concepts.
- Hot Sauce:Pepper mash fermentation demands acid-resistant equipment and extended barrel aging for complexity. Texas and Louisiana bottlers supply quick-service chains seeking Scoville-rated heat customization for younger demographics.
- Ketchup:Tomato paste concentration and high-speed filling lines dominate capital allocation for mass-market producers.
- Mayonnaise:Emulsification equipment and cold-chain stability systems anchor production economics.
- Mustard:Seed milling and vinegar stabilization require moderate fermentation capacity.
- Relish:Brining tanks and vegetable processing lines complete the acidified preservation workflow.
Ketchup absorbs the bulk of installed capacity; hot sauce is expanding most quickly.
Packaging Type:
Food service automation is reshaping procurement toward portion-control formats that reduce labor and waste.
- Sachets:Multi-layer film laminates with oxygen barriers enable ambient shelf stability for single-serve hospitality use. Institutional cafeterias in Germany and France are converting from bulk dispensers to pre-portioned sachets for hygiene compliance.
- Pumps:Precision dosing mechanisms integrate with quick-service counter layouts for throughput optimization. Major chains in Illinois and Georgia specify pump compatibility for condiment bar standardization.
- Bottles:Glass and PET formats retain retail dominance despite freight weight penalties.
- Jars:Wide-mouth designs serve spoonable condiments in deli and specialty channels.
- Tubs:Food service bulk formats for back-of-house portioning.
- Pouches:Flexible alternatives for e-commerce shipping efficiency.
Bottles retain the largest installed base; sachets are climbing the fastest.
Distribution Channel:
Channel selection determines margin capture and brand control intensity.
- Food Service:Direct supply contracts with broadline distributors or specialty co-packers bypass retail slotting fees. Independent restaurant groups in coastal US metros are disintermediating traditional distributors for provenance-driven condiment sourcing.
- Supermarkets:Private-label penetration and shelf-space negotiations dominate volume economics.
- Convenience Stores:Grab-and-go formats for travel and impulse consumption.
- Online Retailers:Subscription models and direct-to-consumer artisanal discovery.
- Specialty Stores:Ethnic and premium positioning in curated assortments.
- Wholesalers:Consolidated procurement for institutional and independent food service.
Food service commands the highest contract values; online retailers are gaining share fastest.
End User:
User type dictates formulation complexity and regulatory exposure.
- Restaurants:Menu-specific customization and back-of-house efficiency requirements drive bulk procurement with pump or tub formats. Chains in Florida and Arizona prioritize shelf-stable concentrates for kitchen workflow standardization.
- Food Manufacturers:Industrial-scale ingredient sourcing for sauce inclusion in processed foods requires batch consistency certification and HACCP documentation.
- Household Consumers:Retail packaging diversity and clean-label claims dominate purchase drivers.
- Catering Services:Event-scale portion control and transport stability.
- Hotels:In-room and breakfast service presentation standards.
- Cafeterias:Institutional nutrition compliance and cost-per-serving optimization.
Restaurants absorb the bulk of food service volume; food manufacturers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in China and India supply fermented sauce inputs to consumption centers in the United States and Germany, creating transoceanic supply dependencies that freight volatility amplifies. Manufacturing gravity concentrates in East Asian brewing facilities and North American emulsification plants, while regulatory divergence between FDA sodium mandates and EFSA additive rules fragments formulation standards.
United States
Private-label penetration and premium artisanal segments are gaining shelf space in conventional retail, while quick-service chains expand procurement of pump-dispensed formats. FDA sodium reduction timelines are compressing R&D cycles for ketchup and mayonnaise portfolios below eighteen months. Chicago and Atlanta anchor food service automation clusters where major chains standardize condiment bar specifications.
Germany
Institutional cafeterias are converting from bulk dispensers to pre-portioned sachets for hygiene compliance, pulling demand toward multi-layer film laminates. EFSA enforcement of additive transparency under EU frameworks is accelerating clean-label certification timelines for private-label programs. The Rhine-Ruhr corridor concentrates glass bottle manufacturing and acidified sauce co-packing capacity serving Central European retail.
China
Glass bottle manufacturing clusters dominate global packaging supply, exposing brands to port congestion and freight rate spikes from Shanghai and Ningbo terminals. The country's national food safety regulator maintains acidified food standards that constrain export formulation flexibility. Sichuan and Guizhou provinces anchor chili pepper mash fermentation for hot sauce complexity.
Japan
Naturally brewed soy sauce variants command premium positioning in domestic and export markets through six-to-twelve month cedar vat aging cycles. METI standards on fermentation process labeling reinforce consumer preference for traditional brewing methods. Chiba and Hyogo prefectures concentrate heritage brewing infrastructure supplying California and New York restaurant supply chains.
India
Chili pepper harvest fluctuations in Andhra Pradesh and Karnataka are compressing margin stability for fermented sauce producers dependent on domestic raw material sourcing. FSSAI enforcement of additive disclosure is pulling reformulated products toward clean-label positioning ahead of compliance deadlines. Mumbai and Delhi-NCR serve as distribution hubs for ethnic condiment exports to Sub-Saharan African markets.
Condiments Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across fermentation infrastructure, emulsification capacity, and distribution reach. The vendor base organizes into three tiers: multinational CPG houses with global brand portfolios, mid-sized regional producers with HPP-adopted lines, and artisanal specialists with provenance-driven positioning. Consolidation pressure operates through M&A activity targeting fermentation capacity and direct-to-foodservice channel access.
Within the multinational tier, The Kraft Heinz Company and Unilever PLC exemplify scale-driven positioning across multiple condiment categories, while Kikkoman Corporation anchors the fermentation-specialist archetype through in-house brewing infrastructure. These three entities occupy positions that span retail shelf dominance, food service contract volume, and premium export positioning respectively.
| Leading Market Players |
|---|
| Conagra Brands Inc. |
| Kikkoman Corporation |
| The Kraft Heinz Company |
| Kewpie Corp |
| Hormel Foods Corporation |
| Unilever PLC |
| Nestle SA |
| Lee Kum Kee Company Ltd |
| McCormick & Company Inc. |
| Others |
Cost & Logistics Intelligence
High-pressure processing adoption is compressing thermal processing economics while concentrating production among mid-sized regional producers who can amortize HPP line investments faster than national retort-based competitors.
Pricing Analysis
Margin tightening in mass-market emulsified sauces reflects soybean oil and egg input volatility coupled with FDA sodium reduction compliance costs. Three-tier pricing structure across premium naturally fermented, standard clean-label, and economy conventional levels separates Kikkoman-style heritage brewing from private-label mayonnaise. Food service buyers exhibit highest price sensitivity due to direct-to-co-packer disintermediation, while retail premium segments absorb formulation premiums for EFSA-compliant additive-free positioning.
Supply Chain Analysis
Regional distribution centers in Chicago and Atlanta anchor hub-and-spoke patterns serving quick-service chain specification standardization. Glass bottle manufacturing clusters in China, chili pepper mash fermentation in Sichuan and Guizhou provinces, and tomato paste concentration in California's Central Valley create transoceanic dependencies. Single-source vulnerability in Shanghai-Ningbo port corridors exposes brands to freight rate spikes. Distribution runs through broadline food service distributors, though independent restaurant groups increasingly bypass these channels for direct specialty co-packer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity scarcity props pricing for naturally brewed soy sauce and barrel-aged hot sauce, constraining volume expansion for clean-label portfolios.
For Market Incumbents: Hedge against input volatility through backward integration into chili pepper farming cooperatives in Andhra Pradesh and cedar vat brewing infrastructure in Hyogo prefecture. Defend food service contract renewals by embedding pump-dispenser compatibility specifications that raise switching costs for quick-service chains. For New Entrants and Emerging Players: Independent chef-driven restaurant groups in coastal US metros represent the most penetrable buyer archetype, prioritizing provenance storytelling over national brand recognition. Capture margin pools through direct-to-foodservice subscription models bypassing distributor markups. Lead with USDA organic certification to unlock natural grocery channel shelf space ahead of compliance-driven incumbent reformulation timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in fermentation-specialist acquisition by multinational CPG houses seeking clean-label credibility. Five-to-ten year viability favors mid-sized regional producers with HPP-adopted lines and direct food service channel access. Watch FDA sodium reduction mandate acceleration as inflection indicator for reformulation cost spikes and portfolio consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FDA and EFSA mandates force R&D pipeline rebuilds for ketchup and mayonnaise portfolios. |
| Fermentation Capacity Expansion | Naturally brewed soy sauce aging infrastructure commands premium positioning in Japanese and Korean restaurant supply chains. |
| Direct-to-Foodservice Channel Development | Independent restaurant disintermediation captures margin pools previously absorbed by broadline distributor markups. |
| High-Pressure Processing Adoption | HPP lines in California and Lombardy compress retort-based national brand advantages through flavor preservation. |
| Sustainable Packaging Transition | EPA guidelines drive capital redeployment into recyclable film and paper-based sachet alternatives for institutional cafeterias. |
Research Approach
Document review covered FDA acidified food regulations, EFSA additive labeling frameworks, USDA organic certification standards, and trade customs data, complemented by interviews with fermentation facility managers, quick-service chain procurement directors, specialty co-packer operations heads, and retail category buyers. Secondary validation drew from EPA packaging sustainability guidelines, FSSAI enforcement disclosures, and METI fermentation process standards. Bottom-up volume modeling triangulated against top-down market sizing.
Market value and volume outputs trace demand-side segmentation across product type, packaging format, distribution channel, and end-user archetype, with regional production cluster overlays for fermentation infrastructure and emulsification capacity. CAGRs derive from trend-line extrapolation adjusted for regulatory compliance cost absorption and channel shift velocity. Input variables include soybean and chili pepper harvest forecasts, glass bottle freight rate indices, and food service automation adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA sodium reduction timeline acceleration, EFSA additive disclosure enforcement stringency, and port congestion recurrence in Chinese manufacturing clusters. Forecasts reflect assumptions around clean-label reformulation cost pass-through rates and food service procurement fragmentation persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Egg-Free Mayonnaise Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Compound Condiments Market
Condiments & Sauces
GCC Condiment Sauces (for Hospitality Sector) Market
Condiments & Sauces
Barbecue Sauce Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Low Salt Soy Sauce Market
Condiments & Sauces
Hot Sauce Powder Market
Condiments & Sauces
Tomato Ketchup Market
Condiments & Sauces
Vegan Sauces Market
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Table Sauce Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
Dips and Spreads Market
Condiments & Sauces
Europe Pasta Sauce Market