
 Vinegar and Vinaigrette Market | 2026-2036
Vinegar and Vinaigrette Market Size, Share, and Industry Trends Forecast 2026-2036
Vinegar and Vinaigrette Market Analytics
Premium aged and DOP-designated tier upgrades is reorganizing competitive positioning in the vinegar and vinaigrette sector. Mizkan Holdings leverages its fermentation technology leadership to sustain dominance in Asian rice vinegar exports. Carl Kühne KG anchors European retail shelf presence through deep distribution networks across Germany and neighboring markets. De Nigris differentiates through heritage positioning in Italian balsamic traditions.
Vinegar and vinaigrette encompass acidified liquid condiments and emulsified oil-acid dressings, typically formulated at 4-7% acetic acid concentration through aerobic bacterial fermentation of ethanol substrates, serving primarily as flavoring agents, preservatives, and culinary bases across food manufacturing and household kitchens. Balsamic and apple cider categories occupy the highest margin pools, with aged balsamic commanding premium pricing through protected geographic origin frameworks while apple cider vinegar expands fastest in wellness-oriented household applications. The food industry application segment leads absolute volume, though specialty stores and online retail channels are capturing disproportionate growth in organic and fruit-based ingredient source variants.
EU EFSA standards and FDA food additive regulations govern acetic acid thresholds and labeling claims across the market, with REACH compliance additionally constraining packaging material specifications for European exporters. USDA organic certification and EU organic labeling requirements are reshaping ingredient sourcing strategies, particularly for grain-based and fruit-based supply chains. Stakeholders must monitor evolving clean-label enforcement intensity and geographic indication expansion as determinants of premium segment access and margin sustainability.
Market Dynamics
Clean-label enforcement intensity under EU EFSA and FDA frameworks is compressing formulation flexibility while concentrating margin capture among heritage producers with verified supply chains. This regulatory pressure is restructuring competitive positioning across premium and mass-market tiers simultaneously.
Growth Catalysts
- EU Organic Labeling Requirements:Certification mandates for grain-based and fruit-based supply chains are accelerating ingredient traceability investments. Producers with verified organic sourcing are capturing shelf space in specialty retail channels.
- Foodservice Premiumization:Restaurant sector demand for aged and specialty vinegars is expanding volume in DOP-designated categories. Culinary applications in fine-dining establishments are normalizing higher price points for heritage balsamic production.
- Modena Production Cluster:Geographic concentration of traditional balsamic craftsmanship in Italy's Emilia-Romagna region is anchoring high-value export capacity. Protected origin frameworks are limiting competitive entry from non-designated producers.
Market Restraints
- Acetic Acid Feedstock Volatility:Ethanol substrate costs fluctuate with grain and fruit commodity markets. Input price instability compresses margins for mass-market vinegar producers without long-term supply contracts.
- REACH Packaging Compliance:European chemical safety regulations constrain material specifications for export-bound packaging. Compliance costs disproportionately burden small-scale producers lacking technical regulatory capacity.
- Wellness-Product Substitution:Apple cider vinegar's functional positioning faces encroachment from kombucha and other fermented wellness beverages. Category boundary erosion threatens household application growth trajectories.
Strategic Opportunities
- Online Retail Channel Expansion:Direct-to-consumer platforms are capturing disproportionate growth in organic and fruit-based variants. Digital-native brands bypass traditional retail gatekeepers to access wellness-oriented households.
- USDA Organic Certification Tailwinds:Federal organic standards create premium pricing permission for compliant producers. Certification investment yields shelf placement advantages in conventional grocery channels.
- Barrel-Aging Technology Convergence:Traditional wood-cask methods combined with controlled microbiome monitoring are reducing production cycle times. Technology-enhanced heritage processes expand aged vinegar capacity without quality compromise.
Industry Challenges
- Master Acetification Specialist Scarcity:Traditional fermentation expertise concentrated in aging producer workforces lacks pipeline replenishment. Knowledge transfer gaps threaten quality consistency in heritage production methods.
- DOP Certification Timeline Compression:Geographic indication approval processes create multi-year barriers to premium market entry. Regulatory documentation burdens delay revenue realization for emerging producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinegar and Vinaigrette Market |
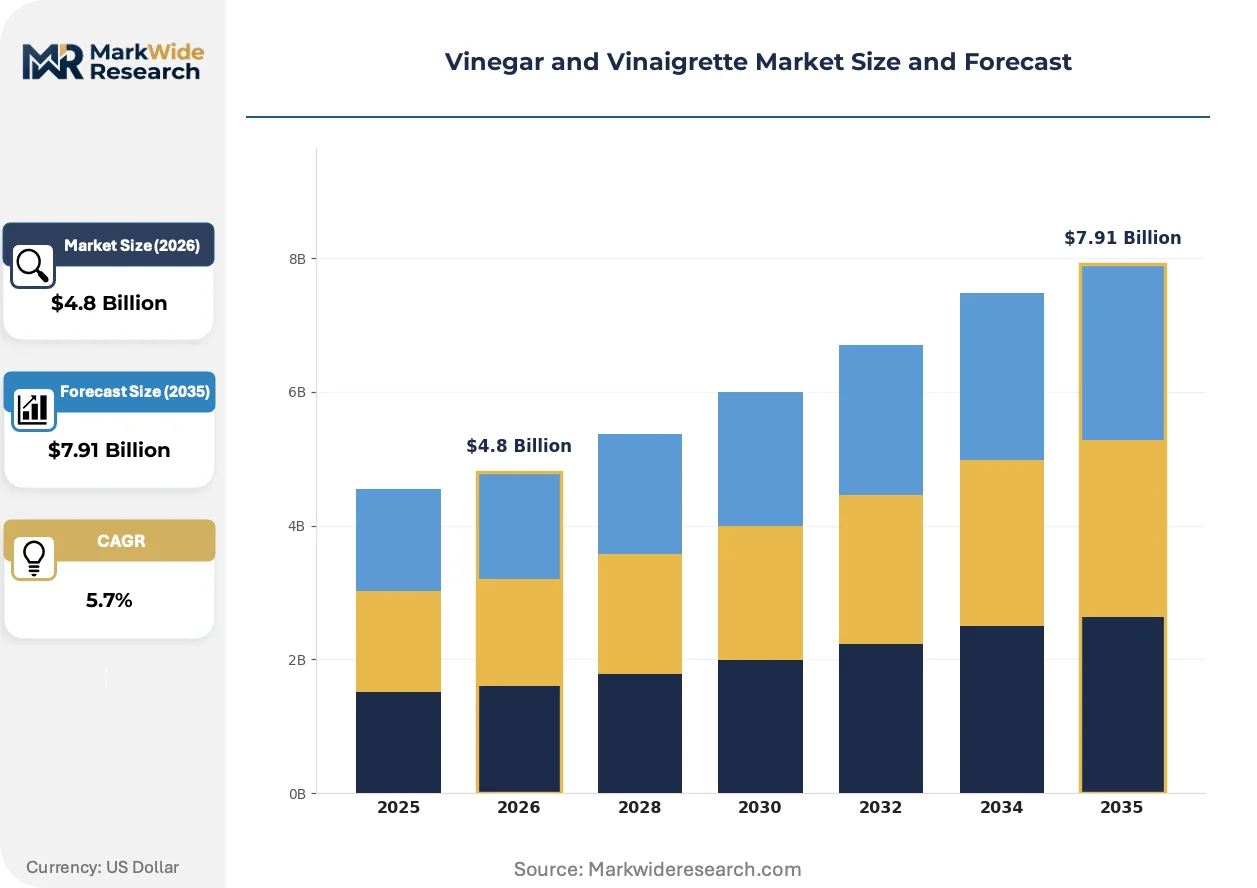
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balsamic, Red Wine, White Vinegar, Apple Cider Application: Food Industry, Household Use, Culinary Arts, Cosmetics Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Ingredient Source: Organic, Non-Organic, Fruit-Based, Grain-Based |
| Companies Covered | Carl Kühne KG, Fleischmann's Vinegar Company, Mizkan Holdings, Borges Branded Foods, Burg Groep B.V., The Kraft Heinz Company, De Nigris, Acid League, Marukan Vinegar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinegar and Vinaigrette Market Evolving Landscape
Technology-enabled fermentation monitoring and regulatory transparency requirements are converging to reshape production economics and competitive differentiation across vinegar and vinaigrette categories.
Controlled microbiome sequencing and real-time acetic acid monitoring is supplanting traditional sensory-based quality assessment in large-scale production facilities. Industrial vinegar manufacturers in Germany and Japan are adopting these systems to reduce batch variability and accelerate certification documentation. The technology is compressing quality assurance labor costs while enabling consistent output for private-label retail contracts.
EU EFSA clean-label enforcement is tightening additive disclosure thresholds for acidified condiments. Producers reformulating to eliminate synthetic preservatives face reformulation R&D costs and extended stability testing timelines. Italian balsamic producers with heritage ingredient lists are leveraging this regulatory friction to differentiate against mass-market competitors with longer additive declarations.
Direct-procurement relationships between restaurant groups and heritage vinegar producers are displacing traditional foodservice distributor intermediaries. Chef-driven specifications for barrel-aged and single-origin varieties are concentrating purchase authority in culinary procurement teams rather than broadline distribution buyers. This channel shift is most visible in Michelin-tier restaurant concentrations across France, Spain, and California.
Vinegar and Vinaigrette Market Segmentation
Vinegar and vinaigrette categories fragment across acidification methods, aging protocols, and end-use specifications. Regulatory frameworks governing acetic acid thresholds and geographic origin claims create tiered compliance burdens that reshape competitive positioning within each segment cluster.
Product Type:
EFSA and FDA acetic acid thresholds apply differentially across fermentation substrates and aging durations, concentrating compliance investment in heritage-designated categories.
- Balsamic:Aged wine must reductions achieve 6% minimum acetic acid through controlled acetification in wood casks. EU DOP frameworks in Modena and Reggio Emilia limit supply expansion while commanding premium pricing in fine-dining procurement channels.
- Apple Cider:Fermented apple juice maintains 4-6% acetic acid with retained fruit phenolics driving wellness-positioned household demand. USDA organic certification unlocks shelf placement in conventional grocery channels for compliant producers.
- Red Wine:Grape-derived acetification yields sharper acid profiles suited to Mediterranean culinary applications.
- White Vinegar:Grain-ethanol fermentation produces neutral acid bases for industrial food manufacturing and pickling operations.
Established volume favors white vinegar; emerging adoption favors apple cider.
Application:
End-use concentration determines margin capture, with food manufacturing prioritizing cost efficiency while culinary arts reward provenance documentation.
- Food Industry:Bulk acidification for sauce manufacturing, pickling operations, and processed food preservation demands consistent 4-5% acetic acid specification. Clean-label reformulation pressures are eliminating synthetic preservative additives in contract manufacturing agreements.
- Culinary Arts:Chef-driven procurement in Michelin-tier establishments specifies barrel-aged and single-origin varieties with verified geographic origin. Direct producer relationships are displacing broadline distributor intermediaries in France, Spain, and California restaurant clusters.
- Household Use:Retail-packaged condiments for domestic kitchens emphasize convenience formats and stability.
- Cosmetics:pH-adjusting acid extracts serve formulation needs in personal care manufacturing.
Margin concentration sits with culinary arts; volume scale sits with food industry.
Distribution Channel:
Channel selection determines pricing permission and consumer access, with digital platforms bypassing traditional retail gatekeepers for specialty variants.
- Online Retail:Direct-to-consumer platforms capture disproportionate growth in organic and fruit-based ingredient variants. Digital-native brands leverage wellness positioning to access households outside conventional grocery footprints.
- Specialty Stores:Curated assortments of DOP-designated and aged varieties serve enthusiast consumers with provenance preferences. Staff expertise validates premium pricing for heritage production methods.
- Supermarkets:Mass-market shelf space concentrates volume for standardized vinegar categories.
- Wholesale:Foodservice distributor networks supply restaurant and manufacturing procurement at scale.
Volume flows through supermarkets; value expansion concentrates in online retail.
Ingredient Source:
Certification requirements for organic and geographic origin claims are restructuring sourcing strategies and supplier qualification protocols.
- Organic:USDA and EU organic labeling mandates require verified supply chain documentation from fermentation substrate through packaging. Certification investment yields pricing premiums and shelf placement advantages in conventional retail.
- Fruit-Based:Apple, grape, and berry substrates support clean-label positioning with retained aromatic compounds. Weather-dependent harvests create input cost volatility requiring long-term grower contracts.
- Grain-Based:Corn and wheat ethanol feeds mass-market white vinegar production at scale.
- Non-Organic:Conventional sourcing maintains cost competitiveness for industrial food manufacturing applications.
Regulatory tailwinds favor organic; cost efficiency favors grain-based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Traditional balsamic production clusters in Italy's Emilia-Romagna region anchor high-value export capacity, while fermentation technology leadership concentrates in Japan and Germany. Regulatory divergence between EU EFSA frameworks and FDA standards creates compliance fragmentation for cross-border producers.
Italy
Modena and Reggio Emilia host the world's only EU DOP-designated traditional balsamic vinegar production, with aged wine must reductions commanding premium pricing in fine-dining procurement. EFSA clean-label enforcement tightens additive disclosure thresholds for acidified condiments. The Emilia-Romagna cluster limits competitive entry through protected geographic origin frameworks that restrict supply expansion.
United States
USDA organic certification creates shelf placement advantages for fruit-based and grain-based vinegar producers supplying wellness-oriented households. FDA food additive regulations govern acetic acid thresholds and labeling claims across domestic manufacturing. California's Napa and Sonoma wine regions support emerging wine vinegar production for culinary arts applications.
Japan
Mizkan Holdings anchors Asian rice vinegar exports through advanced fermentation technology leadership developed over centuries of specialized production. METI standards and JIS certification requirements shape quality benchmarks for export-bound products. The Aichi Prefecture concentration of rice vinegar craftsmanship supports consistent supply to foodservice and retail channels across Asia-Pacific.
Germany
Carl Kühne KG leverages deep distribution networks across Germany and neighboring markets to dominate European retail shelf presence for mass-market vinegar categories. REACH compliance constrains packaging material specifications for export-bound production. The Lower Saxony industrial corridor hosts large-scale acetification facilities serving private-label retail contracts.
Spain
Borges Branded Foods exemplifies Mediterranean olive oil and vinegar integration, with sherry vinegar production in Jerez de la Frontera supporting culinary arts demand. EU organic labeling requirements accelerate ingredient traceability investments for fruit-based supply chains. Andalusian wine regions provide substrate access for aged vinegar production targeting specialty retail channels.
Vinegar and Vinaigrette Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with heritage producers commanding premium positioning through verified supply chains while mass-market specialists compete on scale and distribution density. The market structures around three tiers: DOP-designated heritage houses with multi-decade aging inventories, mid-market brands with regional retail penetration, and private-label manufacturers serving industrial foodservice contracts. Dominant competitive moves include direct-procurement relationship building with restaurant groups and barrel-aging technology investments to compress production cycle times without quality compromise.
Within the heritage-tier segment, De Nigris represents Italian balsamic tradition anchoring, while Mizkan Holdings exemplifies fermentation technology leadership in Asian rice vinegar categories. Carl Kühne KG occupies the mass-market retail position through GmbH-structured European distribution dominance. These three archetypes illustrate the competitive divergence between provenance-based premium capture and scale-driven shelf presence.
| Leading Market Players |
|---|
| Carl Kühne KG |
| Fleischmann's Vinegar Company |
| Mizkan Holdings |
| Borges Branded Foods |
| Burg Groep B.V. |
| The Kraft Heinz Company |
| De Nigris |
| Acid League |
| Marukan Vinegar Inc. |
| Others |
Value Network & Pricing Analysis
Grain-to-fruit substrate substitution is redrawing procurement geography as mass-market producers abandon volatile corn ethanol for contracted apple and grape must supplies, simultaneously elevating input costs and compressing margins for undifferentiated white vinegar while concentrating pricing power with heritage houses holding long-term grower relationships.
Pricing Analysis
EU DOP and USDA organic certification dictates the pricing tier structure across vinegar and vinaigrette categories. Three-tier pricing separates barrel-aged DOP balsamic from certified-organic mid-market fruit vinegars from commodity white vinegar, with quality grade and certification level as the primary differentiation drivers. Cost compression in mass-market grain-based tiers is intensifying because ethanol feedstock volatility erodes contract margins. Food manufacturing buyers exhibit highest price sensitivity; Michelin-tier culinary procurement teams show least sensitivity, prioritizing provenance documentation over unit cost.
Supply Chain Analysis
Strategic stockpiling of aged inventory distinguishes heritage balsamic producers from just-in-time grain-ethanol processors in the vinegar supply chain. Supply concentrates in Italy for DOP-designated production, Japan for rice vinegar fermentation technology, and Germany for mass-market acetification scale. Raw material dependencies center on wine must, apple harvests, and grain ethanol feeds. Single-source vulnerability threatens Emilia-Romagna's concentrated traditional production. Distribution runs through foodservice distributor networks for industrial volumes, direct-procurement relationships for culinary arts, and online retail platforms bypassing conventional grocery gatekeepers for organic variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-consumer platform economics are reshaping vinegar and vinaigrette go-to-market models, with digital-native brands leveraging wellness positioning to circumvent traditional retail slotting fees and capture household demand outside conventional grocery footprints.
For Market Incumbents: Secure long-term grower contracts in Italy's Emilia-Romagna and California's Central Valley to lock in fruit-based substrate supply before organic certification demand escalates input competition. Defend DOP-designated positioning against encroaching private-label aged vinegar through accelerated barrel-aging technology investment that compresses production cycles without quality compromise. Channel control through exclusive chef relationships in Michelin-tier restaurant clusters provides margin protection against mass-market price erosion.
For New Entrants and Emerging Players: Anchor in USDA organic certification pathways for apple cider vinegar variants, the most penetrable segment for wellness-positioned household demand. White-space targets include direct-to-consumer subscription models for barrel-aged specialty varieties and clean-label vinaigrette formats for meal-kit integration. Go-to-market leverage rests on digital-native brand building through social media wellness communities rather than conventional retail slotting negotiations.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European condiment platforms seeking geographic expansion into North American organic certification markets. Long-term viability over the next decade hinges on verified supply chain documentation capabilities as EFSA and FDA clean-label enforcement intensifies. Acquisition targets should demonstrate existing organic certification infrastructure and direct restaurant group relationships. The signal to watch is DOP certification application volume as an indicator of premium segment entry attempts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Substrates | Long-term grower contracts in Modena and Napa Valley secure supply for DOP and organic tiers. |
| Barrel-Aging Technology Investment | Controlled microbiome monitoring reduces production cycles for aged balsamic without quality degradation. |
| Direct-to-Consumer Platform Launch | Digital-native brands bypass retail gatekeepers to capture wellness-oriented household demand. |
| USDA Organic Certification Program | Federal standards unlock shelf placement in conventional grocery channels for compliant fruit-based producers. |
| Chef Partnership Network Expansion | Direct procurement relationships with Michelin-tier establishments displace broadline distributor intermediaries. |
Research Methodology
Desk research of EU DOP registry filings, USDA organic certification databases, and foodservice procurement contract records preceded structured interviews with master acetification specialists, restaurant group culinary directors, specialty retail category buyers, and grain ethanol procurement managers. Primary fieldwork validated production volume estimates and aging inventory assumptions against secondary trade data and customs export records. Bottom-up facility capacity assessments triangulated against top-down category spending estimates derived from food manufacturing input cost disclosures.
Variance decomposition across product type, application, distribution channel, and ingredient source dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by price realization trends. Forecast inputs incorporated acetic acid feedstock futures curves, DOP certification approval timelines, and online retail channel penetration rates for organic variants.
Material uncertainties — regulatory enforcement intensity shifts, harvest-driven substrate cost spikes, and wellness-product substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification adoption curves and chef procurement pattern stability. Revision becomes warranted when clean-label compliance cost thresholds cross producer exit decision boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Sauces and Condiments Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Cocktail Syrups Market
Condiments & Sauces
Egg-Free Mayonnaise Market
Condiments & Sauces
Sauce Market
Condiments & Sauces
Global Hot Pot Condiment Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
Table Sauce Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Vegan Sauces, Dressings and Spreads Market
Condiments & Sauces
Pesto Sauces Market
Condiments & Sauces
Low Calorie Peanut Sauce Market
Condiments & Sauces
Vegan Cheese Sauce Market
Condiments & Sauces
Australia and New Zealand Tomato Sauce Market
Condiments & Sauces
Europe Hot Sauce Market