
 Shaker Bottles Market | 2026-2036
Shaker Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Shaker Bottles Market Intelligence
Aftermarket accessory revenue is rewriting how shaker bottle brands capture lifetime customer value. BlenderBottle Company leverages its proprietary wire-whisk technology to sustain premium positioning across North American retail channels. PROMiXX Ltd. differentiates through rechargeable vortex-motor designs that anchor its foothold in the electric mixer sub-segment.
Shaker bottles are portable mixing vessels, typically constructed from BPA-free Tritan plastic, food-grade stainless steel, or borosilicate glass, incorporating agitation mechanisms such as wire whisk balls or motorized impellers to dissolve powdered supplements into homogeneous liquid solutions for nutritional consumption. Stainless steel variants command higher margin pools due to thermal insulation properties and durability premiums, while plastic remains the volume leader across mass-market channels. Sports nutrition applications dominate end-use demand, though meal replacement and medical nutrition segments are expanding fastest as aging populations and clinical diet protocols broaden the addressable base.
FDA food-contact material standards, EU REACH chemical safety frameworks, and California Proposition 65 disclosure requirements collectively constrain polymer selection and labeling practices for manufacturers selling into regulated markets. Compliance with these regimes shapes product development timelines and determines market access eligibility for imported goods. Stakeholders must monitor evolving state-level plastic restrictions and biopolymer certification schemes to anticipate material cost shifts and sourcing realignments.
Market Dynamics
BPA-free material mandates from the FDA and EU REACH compliance are compressing product development cycles while forcing polymer substitution across manufacturing bases. These regulatory pressures concentrate cost burdens on mid-tier suppliers lacking captive resin sourcing.
Growth Catalysts
- EU REACH chemical safety frameworks:These disclosure requirements accelerate BPA-free Tritan adoption among European distributors seeking preemptive compliance certification.
- Sports nutrition end-use concentration:Protein supplement consumption in United States gym culture sustains replacement-cycle demand for wire-whisk equipped vessels.
- Meal replacement application expansion:Aging populations in Germany and Japan broaden the addressable base beyond athletic users into clinical diet protocols.
Market Restraints
- Petrochemical input volatility:Tritan copolyester resin prices fluctuate with propylene feedstock costs, compressing margin pools for plastic-focused manufacturers.
- Stainless steel supply concentration:Thermal insulation-grade 18/8 steel sourcing clusters in Chinese foundries, creating geographic vulnerability for premium-tier producers.
- California Proposition 65 litigation exposure:Warning label requirements for trace chemical content generate compliance friction and inventory segmentation costs.
Strategic Opportunities
- Medical nutrition vertical penetration:Hospital discharge protocols and home-care diet management in the United States create institutional procurement channels.
- Rechargeable vortex-motor technology convergence:Battery miniaturization and impeller design advances enable electric mixer sub-segment expansion.
- Aftermarket accessory channel development:Replacement whisk balls, insulated sleeves, and modular lids capture recurring revenue from installed base.
Industry Challenges
- Biopolymer certification timeline compression:USDA BioPreferred and OK compost HOME verification processes extend new product introduction cycles.
- Food-contact migration testing capacity:FDA extraction study backlogs delay BPA-alternative validation, constraining formulation agility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shaker Bottles Market |
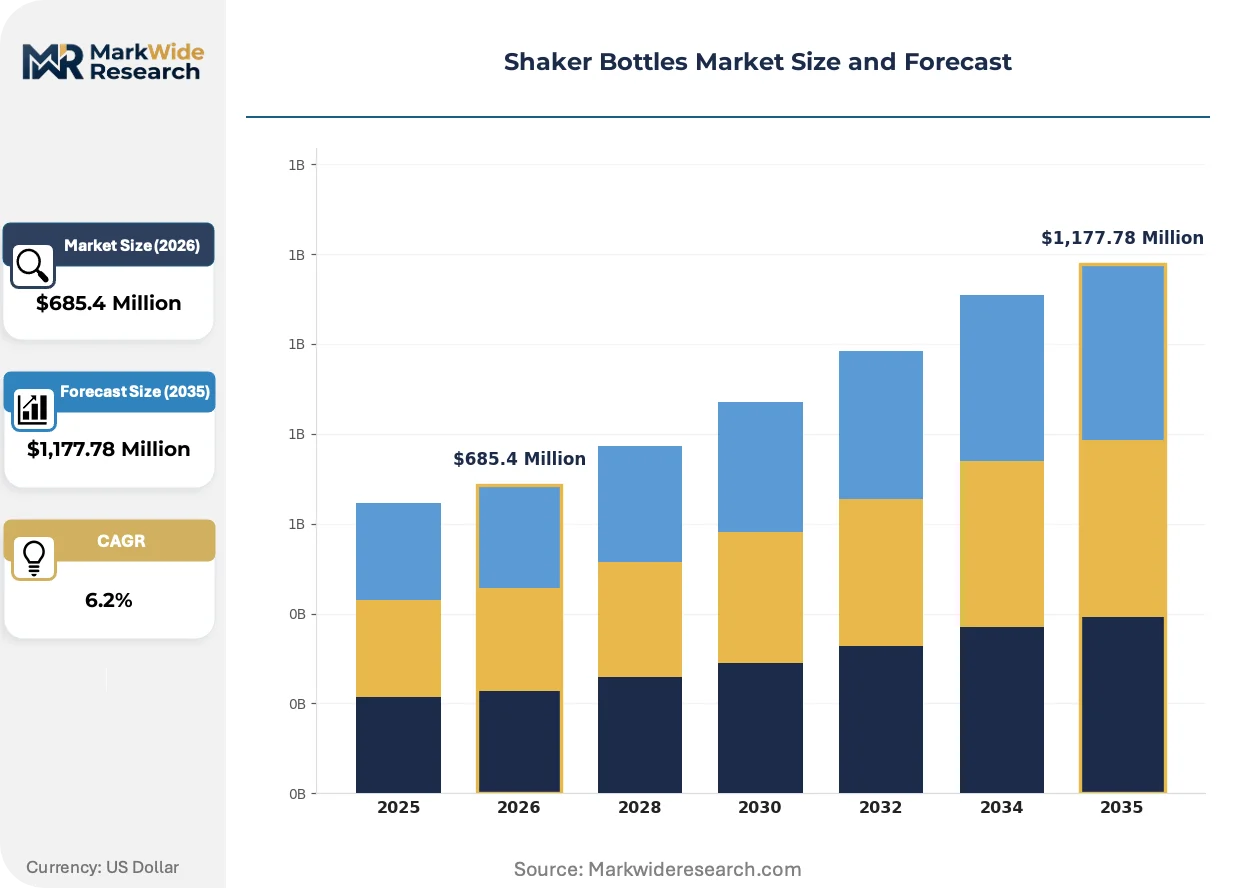
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Stainless Steel, Glass, Aluminum, Silicone Capacity: 300 ml, 500 ml, 700 ml, 1000 ml, 1500 ml Application: Sports Nutrition, Weight Management, Meal Replacement, Elderly Care, Medical Nutrition End User: Fitness Centers, Gyms, Nutritionists, Sports Clubs, Home Users |
| Companies Covered | BlenderBottle Company, Hydra Cup Inc., Newell Brands Inc., Contigo Brands, Trove Brands LLC, GNC Holdings LLC, PROMiXX Ltd., Universal Nutrition, Smartshake AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shaker Bottles Market Strategic Shifts & Innovations
Material science advances and regulatory disclosure requirements are fragmenting competitive advantage sources across the shaker bottle value chain. Technology differentiation now concentrates in agitation mechanism patents and thermal retention engineering.
Rechargeable vortex-motor systems with lithium-polymer power cells and magnetic impeller drives are rendering obsolete manual wire-whisk designs in premium fitness segments. Boutique gym chains and personal training studios in California and New York are standardizing electric mixer procurement for member amenity programs. This electrification is compressing price premiums for passive mixing technologies while expanding addressable margin pools for motor-enabled vessels.
EU REACH Annex XVII restrictions on bisphenol analogues are forcing polymer reformulation across imported goods. Manufacturers selling into regulated European markets must validate alternative copolyesters through ECHA notification procedures. Small-batch producers lacking in-house toxicology resources are exiting German and French retail channels rather than absorbing compliance overhead.
Direct-to-consumer subscription models for replacement parts and flavor-system accessories are displacing traditional retail replenishment cycles. Fitness influencers and nutrition coaching platforms in the United States are bundling shaker vessels with supplement auto-ship programs. This channel migration concentrates customer lifetime value capture with brands owning digital fulfillment infrastructure rather than shelf-space negotiators.
Shaker Bottles Market Segmentation
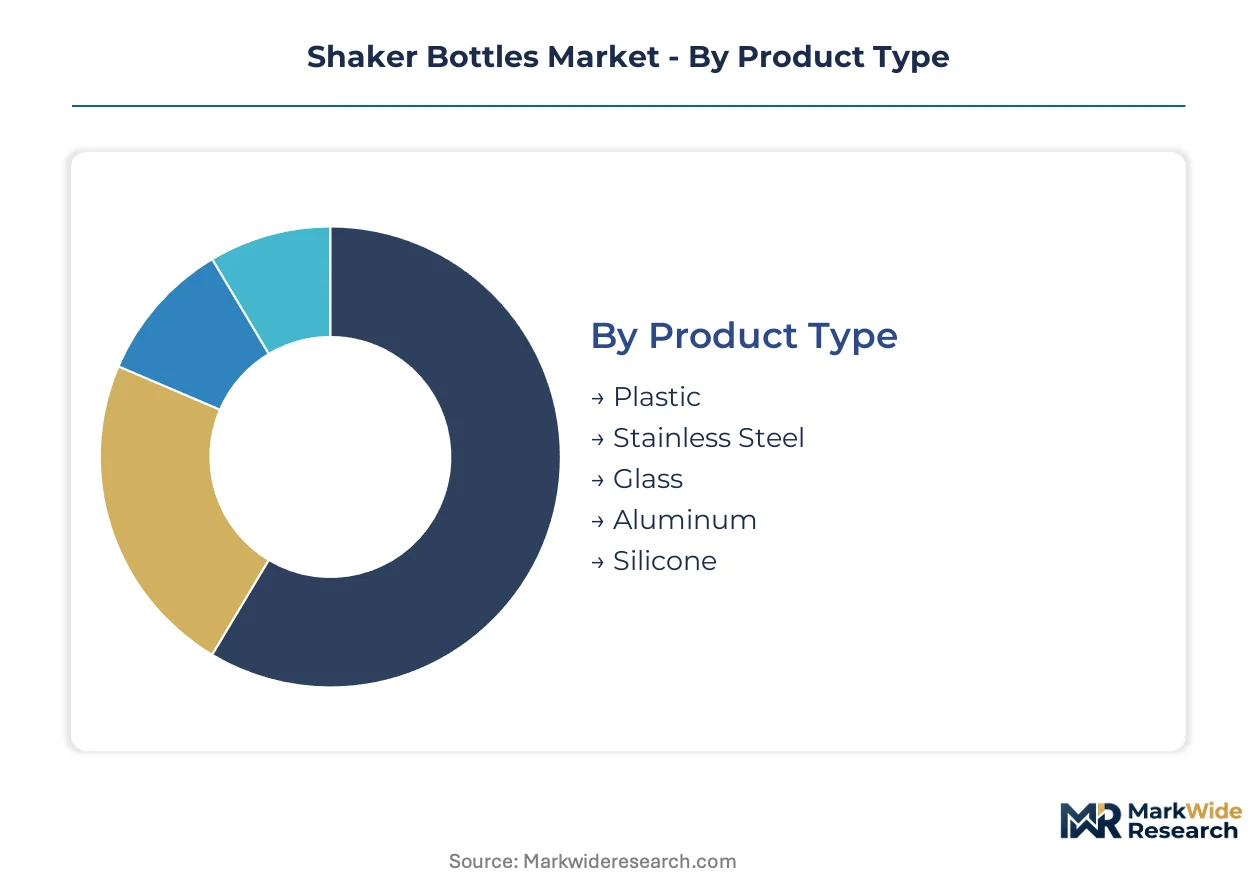
Segmentation in shaker bottles determines replacement cycle frequency, margin architecture, and aftermarket attach rates. Material selection and capacity tiering create divergent paths to customer lifetime value capture.
Product Type:
Aftermarket service intensity varies sharply across material tiers, with replacement-part ecosystems and warranty claims concentrated in specific polymer and metal categories.
- Plastic:Tritan copolyester and polypropylene formulations dominate unit economics through low per-unit production costs and color customization flexibility. Demand clusters in United States mass-market retail channels where gym-goers prioritize portability and price accessibility over thermal performance. FDA food-contact compliance mandates compress development timelines for BPA-alternative formulations.
- Stainless Steel:Double-wall 18/8 vacuum-insulated construction commands durability premiums and extended replacement cycles. Thermal retention properties anchor adoption among outdoor athletes and commuters in Germany where temperature-stable nutrition delivery matters. Chinese foundry concentration creates supply vulnerability for premium-tier producers.
- Glass:Borosilicate construction offers chemical inertness and taste neutrality for medical nutrition protocols. Fragility limits fitness-segment penetration despite superior cleaning compatibility.
- Aluminum:Lightweight metal shells suit cycling and endurance sports applications where gram reduction drives equipment selection. Anodized finishes enable brand differentiation in boutique retail.
- Silicone:Collapsible and soft-body designs address space-constrained travel and military deployment use cases. Compression molding tolerances challenge precision sealing for liquid contents.
By volume, Plastic leads. By growth pace, Stainless Steel is ahead.
Capacity:
Volume tiering aligns with consumption occasion fragmentation across pre-workout, intra-workout, and meal-replacement dosing protocols.
- 500 ml:Mid-size vessels balance single-serve protein portions with cabinet and bag portability. This specification anchors United States gym culture where 25-30 gram protein servings remain standard. BlenderBottle's Classic loop-top design established the category reference point.
- 700 ml:Expanded volume accommodates mass-gainer formulations and hydration-plus-nutrition combinations. Demand concentrates among bodybuilding communities and collegiate athletic programs requiring higher caloric density per serving.
- 300 ml:Compact format suits sample-size supplement trials and pediatric medical nutrition applications.
- 1000 ml:Liter-scale capacity serves endurance athletes and shift workers requiring extended feeding windows without refilling.
- 1500 ml:Largest format targets meal-replacement complete nutrition and institutional food-service applications.
By volume, 500 ml leads. By growth pace, 700 ml is climbing the fastest.
Application:
Use-case expansion beyond athletic performance is reshaping product specification requirements and channel access strategies.
- Sports Nutrition:Protein and pre-workout mixing remains the volume anchor, with wire-whisk equipped vessels sustaining replacement-cycle demand through wear and odor accumulation. United States gym culture and Chinese fitness industry growth concentrate end-user demand.
- Meal Replacement:Complete nutrition powders for weight management and convenience feeding are broadening addressable demand beyond athletic users. Aging populations in Germany and Japan drive clinical and home-care protocol adoption.
- Weight Management:Portion-controlled formulations and appetite-suppressing ingredients require precise measurement markings and leak-proof sealing for commuter consumption.
- Elderly Care:Dysphagia-friendly thickeners and medication mixing create institutional procurement channels in United States hospital discharge planning.
- Medical Nutrition:Disease-specific formulations for diabetes, renal conditions, and oncology support require sterilization-compatible materials and migration-tested polymers.
By volume, Sports Nutrition leads. By expansion trajectory, Meal Replacement is gaining share fastest.
End User:
Channel concentration determines pricing power, with direct institutional contracts offering volume stability and retail fragmentation enabling premium positioning.
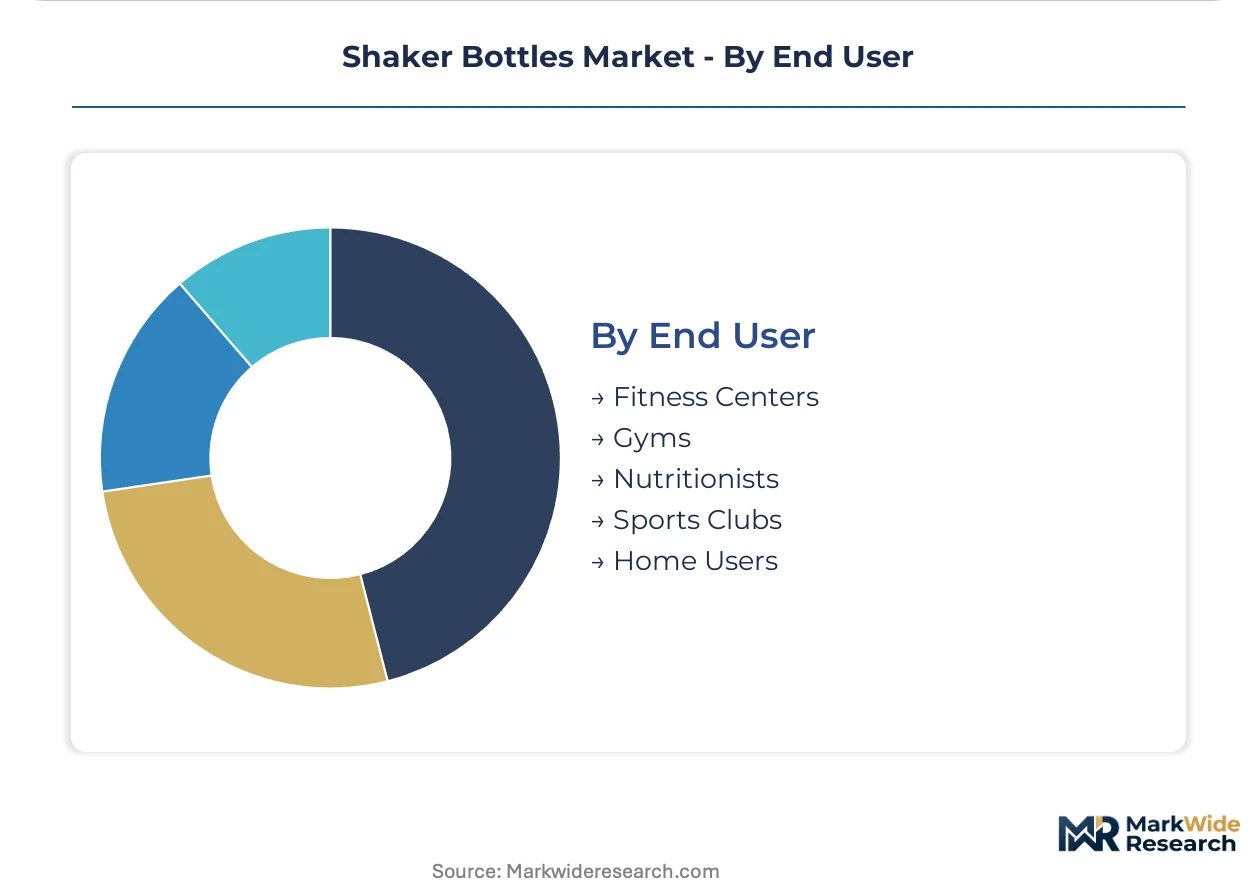
- Home Users:Individual consumers purchasing through e-commerce and mass retail represent the largest addressable base. Subscription bundling with supplement auto-ship programs in the United States concentrates customer lifetime value with digitally native brands.
- Fitness Centers:Boutique gym chains in California and New York are standardizing electric mixer procurement for member amenity differentiation. PROMiXX vortex-motor designs anchor this premium segment.
- Gyms:Large-format health clubs prioritize cost-efficient plastic vessels for new-member onboarding kits and retail resale.
- Nutritionists:Registered dietitian recommendations drive medical-grade glass and stainless steel adoption for credibility signaling.
- Sports Clubs:Collegiate and amateur league bulk purchasing emphasizes durability warranties and team customization.
By volume, Home Users lead. By growth pace, Fitness Centers is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese foundries supply the majority of thermal insulation-grade 18/8 stainless steel, creating geographic vulnerability for premium-tier producers. Demand concentrates in three national markets where gym culture and protein supplement consumption remain strongest.
United States
Fitness influencers and nutrition coaching platforms bundle shaker vessels with supplement auto-ship programs. FDA food-contact material standards constrain polymer selection for imported goods. Los Angeles and New York boutique gym chains standardize electric mixer procurement for member amenity differentiation.
Germany
Aging populations broaden addressable demand into clinical diet protocols and meal replacement applications. EU REACH Annex XVII restrictions on bisphenol analogues force polymer reformulation across imported goods. Bavarian distributors seek preemptive compliance certification for BPA-free Tritan adoption.
China
Domestic fitness industry growth concentrates end-user demand for wire-whisk equipped vessels. SAMR food-contact safety frameworks align with international migration testing protocols. Yangtze River Delta manufacturing bases process Tritan copolyester for export markets.
Japan
Home-care diet management protocols create institutional procurement channels for medical nutrition applications. METI standards govern electrical safety for rechargeable vortex-motor devices. Tokyo metropolitan fitness clubs prioritize compact 500 ml formats for commuter consumption.
United Kingdom
Registered dietitian recommendations drive medical-grade glass and stainless steel adoption. ECHA notification procedures validate alternative copolyesters for European market access. London nutrition coaching platforms bundle subscription models for replacement parts and accessories.
Shaker Bottles Market Key Industry Players
Patent-holding technology specialists and contract manufacturing aggregators split the market into divergent margin architectures. Wire-whisk incumbents defend position through aftermarket accessory ecosystems while electric mixer entrants capture premium positioning through rechargeable motor differentiation. Three strategic archetypes dominate: proprietary agitation mechanism owners, private-label contract manufacturers, and direct-to-consumer digital natives. Competitive moves concentrate on technology licensing agreements and backward integration into polymer compounding.
Within the proprietary technology tier, BlenderBottle Company and PROMiXX Ltd. exemplify divergent agitation approaches. BlenderBottle represents the wire-whisk incumbent archetype with established retail channel presence. PROMiXX occupies the electric mixer position through rechargeable vortex-motor differentiation. Among diversified consumer goods portfolios, Newell Brands Inc. and GNC Holdings LLC sit within the retail distribution aggregator archetype, leveraging existing shelf-space relationships and supplement retail footprints respectively.
| Leading Market Players |
|---|
| BlenderBottle Company |
| Hydra Cup Inc. |
| Newell Brands Inc. |
| Contigo Brands |
| Trove Brands LLC |
| GNC Holdings LLC |
| PROMiXX Ltd. |
| Universal Nutrition |
| Smartshake AB |
| Others |
Cost & Logistics Intelligence
Chinese Yangtze River Delta manufacturing bases processing Tritan copolyester concentrate cost leverage for mid-tier suppliers, while FDA and EU REACH compliance overhead migrates margin pools toward vertically integrated compounders with captive toxicology resources. This upstream geography shapes downstream pricing power across plastic, stainless steel, and electric mixer tiers.
Pricing Analysis
Aftermarket replacement whisk balls, insulated sleeves, and modular lid ecosystems anchor lifetime value capture for wire-whisk incumbents. Three-tier pricing structure across premium electric mixers, standard stainless steel vessels, and economy plastic formats segments buyers by thermal performance requirements and agitation mechanism sophistication. Cost compression in mass-market plastic tiers stems from propylene feedstock volatility and BPA-alternative formulation R&D overhead. Home users through e-commerce channels exhibit highest price sensitivity, while boutique fitness centers in California and New York demonstrate lowest sensitivity for rechargeable vortex-motor amenities.
Supply Chain Analysis
Propylene feedstock for Tritan copolyester and thermal insulation-grade 18/8 stainless steel from Chinese foundries constitute the primary raw material dependencies. Geographic supply concentration clusters in China for polymer compounding and metal forming, with secondary molding operations in Vietnam and Mexico for North American market access. Single-source vulnerability concentrates in Yangtze River Delta resin processors subject to environmental compliance shutdowns. Distribution runs through direct-to-consumer digital channels, supplement retail partnerships, and institutional procurement contracts for medical nutrition verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription bundling of shaker vessels with nutrition coaching platforms and supplement auto-ship programs signals platform-economics inflection, where customer lifetime value capture migrates from shelf-space negotiators to digital fulfillment infrastructure owners.
For Market Incumbents: Build aftermarket accessory moats through proprietary whisk-ball ecosystems and modular lid patent portfolios. Wire-whisk incumbents face substitution threat from rechargeable vortex-motor entrants capturing boutique fitness center procurement. Channel control through exclusive supplement retail partnerships and backward integration into BPA-free polymer compounding defends margin position against regulatory compliance cost migration. For New Entrants and Emerging Players: German clinical diet protocols and Japanese home-care medical nutrition applications represent underpenetrated white-space targets beyond athletic user saturation. Meal replacement verticals for aging populations offer lowest competitive density versus sports nutrition concentration. Direct-to-institutional sales to hospital discharge planners and registered dietitian recommendation networks provides credible go-to-market angle bypassing established retail gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed wire-whisk incumbents lacking electric mixer technology pipelines or digital subscription infrastructure. Five-to-ten year viability hinges on regulatory compliance scalability and aftermarket recurring revenue attach rates. Acquisition target archetype combines proprietary agitation patents with dormant direct-to-consumer fulfillment capabilities. Signal to watch: ECHA notification backlogs accelerating small-batch producer exits from German and French channels.| Strategic Initiative | Industry Significance |
|---|---|
| Rechargeable Vortex-Motor Patent Acquisition | Electric mixer differentiation captures boutique fitness center procurement in California and New York. |
| BPA-Free Polymer Compounding Integration | Captive resin sourcing insulates margin pools from FDA and EU REACH compliance cost migration. |
| Direct-to-Consumer Subscription Launch | Digital fulfillment infrastructure concentrates customer lifetime value with auto-ship bundling platforms. |
| Medical Nutrition Vertical Penetration | Hospital discharge protocols and dietitian recommendation networks unlock institutional procurement channels. |
| Aftermarket Accessory Ecosystem Expansion | Replacement whisk balls and modular lids generate recurring revenue from installed base retention. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews with brand managers at shaker bottle manufacturers, category buyers at supplement retailers, procurement leads at boutique fitness chains, and regulatory affairs specialists navigating FDA food-contact standards. Secondary validation drew from FDA extraction study filings, ECHA notification databases, SAMR food-contact safety frameworks, customs trade records for Tritan copolyester and stainless steel imports, and Nielsen retail audit data for sports nutrition accessory channels. Bottom-up unit economics modeling and top-down market sizing triangulated volume and value estimates.
Calibration against historical replacement cycle frequencies and protein supplement consumption trends anchored projection assumptions across the analysis window. Segmentation dimensions modeled include material tier, capacity specification, application use-case, and end-user channel archetype. CAGRs derived from regression analysis of gym membership growth, aging population demographics, and electric mixer technology adoption curves in premium fitness segments.
Practitioners should monitor ECHA bisphenol analogue restriction timelines, SAMR enforcement patterns, and biopolymer certification backlog durations for early signals requiring forecast revision. Cross-checking against IHRSA gym industry membership data and supplement industry association shipment reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Airline Catering Services Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Global Sushi Restaurants Market
Food Service
North America Food Service Disposable Market
Food Service
Europe Inflight Catering Market
Food Service
Food & Beverage in Asia Market
Food Service
Catering Food Warmers Market
Food Service
Breakfast Takeout Market
Food Service
Peer-To-Peer Dining Market
Food Service
Asia-Pacific Halal Food and Beverage Market
Food Service
Snack Subscription Box Service Market
Food Service
Nigeria Food Service Market
Food Service
Food Service Gloves Market
Food Service
US Food Service Market
Food Service
Light Meal Market
Food Service
Commercial Tableware Services Market