
 Sauces, Condiments, and Dressings Market | 2026-2036
Sauces, Condiments, and Dressings Market Size, Share, and Industry Trends Forecast 2026-2036
Sauces, Condiments, and Dressings Market Analytics
Food service operators is bifurcating the Sauces, Condiments, and Dressings Market away from traditional retail-centric buyers. Unilever leverages its global manufacturing footprint to supply bulk condiment formats to chain restaurants across multiple continents. The Kraft Heinz Company anchors North American retail shelf presence through iconic branded portfolios in ketchup and mayonnaise. McCormick & Company differentiates through specialized flavor systems targeting ethnic cuisine segments in both consumer and commercial channels.
Sauces, condiments, and dressings comprise formulated liquid, semi-liquid, or emulsified food preparations containing acidulants, hydrocolloids, and flavoring compounds, manufactured through thermal processing or cold-blending to achieve microbial stability and rheological consistency. Their primary commercial purpose is to enhance palatability, extend menu versatility, and standardize taste profiles across food service operations. Ketchup and mayonnaise represent mature, high-volume categories where margin compression has intensified private-label competition. Soy sauce occupies a premium position in ingredient-type segmentation driven by fermentation-authenticity positioning and umami concentration standards. Pouches and sachets within packaging type are capturing disproportionate growth in emerging-market food service and airline catering procurement.
FDA sodium-reduction targets and EU F-Gas Regulation compliance requirements for refrigerated supply chains are reshaping formulation and distribution strategies across the industry. BIS standards in India and China's SAMR food additive codes further fragment regulatory compliance obligations for multinational suppliers. Clean-label certifications from USDA Organic and EFSA-approved natural preservatives are becoming baseline market-access credentials rather than differentiators. Stakeholders must monitor evolving front-of-pack labeling mandates and decide whether to regionalize production or absorb cross-border compliance costs.
Market Dynamics
Clean-label reformulations are redirecting R&D budgets toward ingredient substitution as sodium-reduction mandates from FDA and EFSA force manufacturers to rebuild formulations without sacrificing shelf stability or taste profiles.
Growth Catalysts
- Quick-service restaurant expansion:Chain operators across Southeast Asia are standardizing procurement of single-serve sachets for delivery and takeaway formats, pulling condiment volumes into food service channels.
- EU F-Gas Regulation compliance:Refrigerated supply chain investments are unlocking cold-chain distribution for premium fermented sauces previously limited to ambient-stable categories.
- Umami concentration standards:Fermentation-authenticity positioning in soy sauce is commanding ingredient-grade premiums from commercial kitchens seeking flavor consistency.
Market Restraints
- Input cost volatility:Tomato paste and soybean futures are exposing ketchup and soy sauce margins to agricultural commodity swings without forward-contract coverage.
- Supply concentration risk:Hydrocolloid stabilizer production clusters in China are creating single-source dependencies for texture-modified dressings.
- Regulatory friction:India's BIS standards and China's SAMR additive codes are fragmenting formulation compliance, forcing regional SKU proliferation.
Strategic Opportunities
- Cloud kitchen penetration:Dark kitchen operators in Indonesia and Vietnam are adopting pouch-format condiment systems for portion-controlled waste reduction.
- USDA Organic certification tailwind:Clean-label credentials are becoming baseline market-access requirements in North American retail, rewarding early certifiers with shelf placement.
- High-pressure processing convergence:Cold-pasteurization technology paired with modified-atmosphere packaging is extending clean-label shelf life without thermal degradation.
Industry Challenges
- Fermentation microbiologist scarcity:Traditional soy sauce and miso production requires specialized talent that industrial food science programs are not producing at scale.
- Clean-label reformulation capex:Natural preservative validation and accelerated shelf-life testing demand pilot plant investments that mid-tier manufacturers cannot absorb.
- Legacy ERP integration:Lot-traceability requirements for USDA Organic and EFSA natural preservative audits are forcing replacement of decade-old manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sauces, Condiments, and Dressings Market |
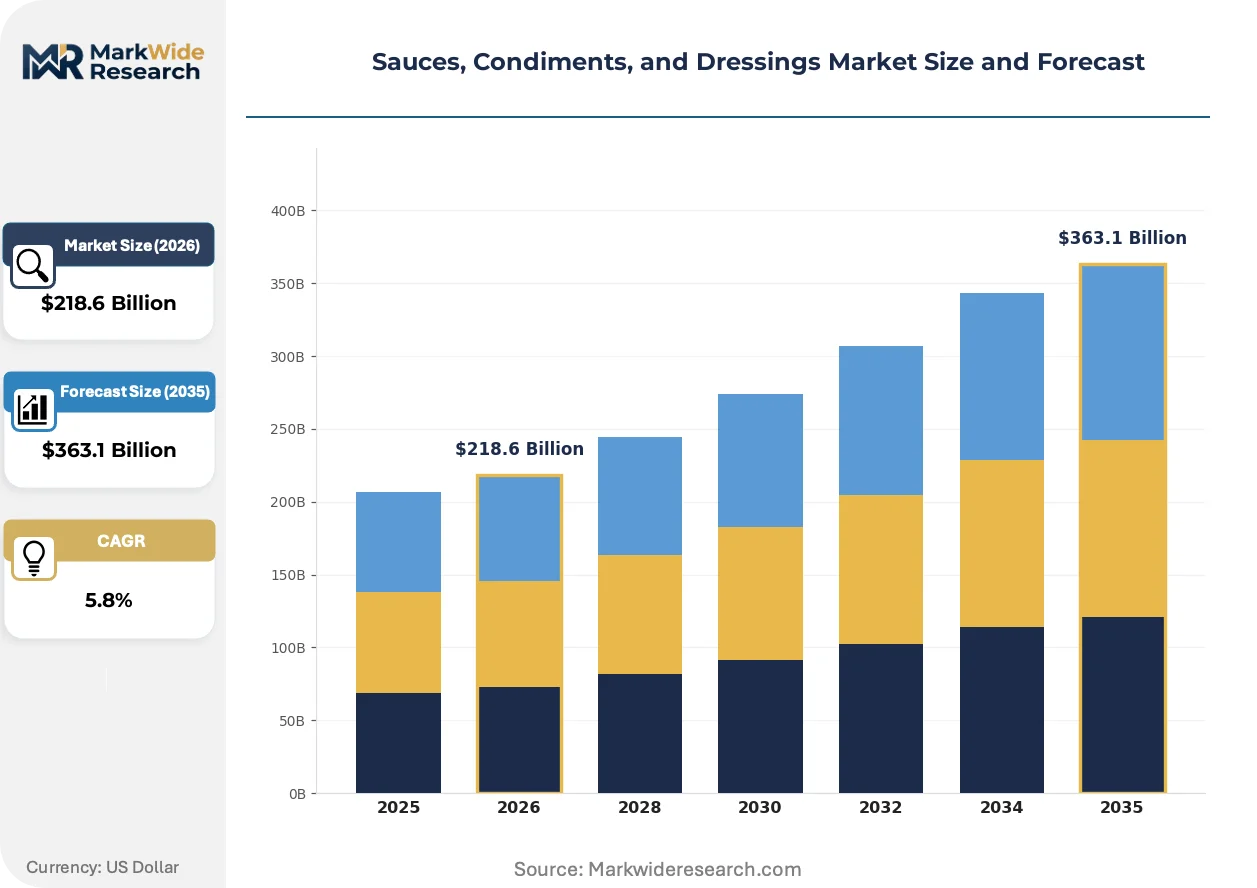
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $363.1 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ketchup, Mustard, Mayonnaise, Soy Sauce Ingredient Type: Organic, Gluten-Free, Low-Sodium, Artificial Packaging Type: Bottles, Jars, Pouches, Sachets Distribution Channel: Supermarkets, Online Retailers, Restaurants, Food Service |
| Companies Covered | Unilever, The Kraft Heinz Company, McCormick & Company, Conagra Brands, Nestlé, Kikkoman Corporation, General Mills, Del Monte Foods, Bolton Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sauces, Condiments, and Dressings Market Evolving Landscape
Formulation science and packaging engineering are converging to solve the clean-label paradox: delivering microbial stability without synthetic preservatives while maintaining the convenience formats that food service operators demand.
High-pressure processing technology is miniaturizing. Cold-pasteurization systems that once required industrial-scale capital deployment are now available in modular units suitable for regional co-manufacturers. Mid-tier sauce producers in Thailand and Malaysia are adopting these compact systems to enter clean-label segments without building dedicated facilities. This technology compression is lowering barriers to premium positioning for previously commodity-focused suppliers.
EFSA-approved natural preservatives are displacing benzoate and sorbate systems across EU-facing production lines. The industrial consequence is reformulation complexity: manufacturers must validate new hurdle-technology combinations to achieve equivalent shelf stability. Refrigerated dressing categories in Germany and France are most affected, with processors accelerating vinegar-acidification and cultured-dextrose trials to meet front-of-pack clean-label mandates.
Street-food commercialization is rotating demand toward portion-controlled formats. Urbanization in Southeast Asia is compressing household cooking frequency while amplifying hawker-stall and food-court throughput. Pouch and sachet procurement by Indonesian and Vietnamese distributors is displacing bulk bottle purchasing in these channels. This channel shift is most visible in soy sauce and chili sauce categories, where single-serve units now dominate food service procurement specifications.
Sauces, Condiments, and Dressings Market Segmentation
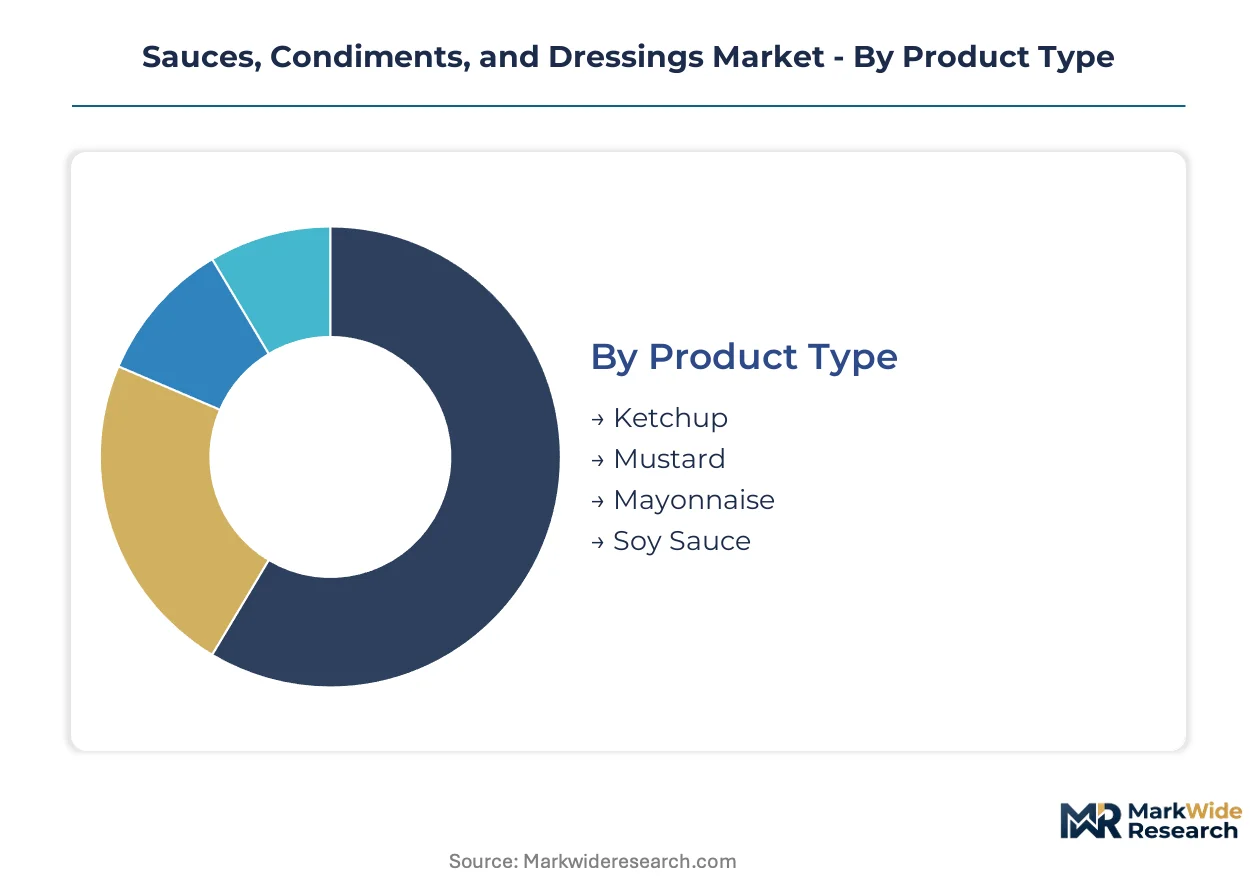
Segmentation in the Sauces, Condiments, and Dressings Market reveals how formulation priorities, packaging engineering, and channel economics split procurement decisions across distinct buyer ecosystems. Understanding these fault lines exposes where margin pools concentrate and where substitution threats are most acute.
Product Type:
Ketchup and mayonnaise face the most intense private-label substitution pressure as mature categories with commoditized taste profiles, while soy sauce maintains defensive positioning through fermentation complexity barriers.
- Ketchup:Tomato-based acidified condiment with standardized viscosity specifications and high thermal-process throughput. Demand concentrates in North American quick-service chains where portion-controlled sachet procurement is displacing bulk bottle contracts amid delivery-format expansion.
- Soy Sauce:Fermented soybean and wheat preparation graded by umami concentration and amino nitrogen content. Commercial kitchens in Southeast Asia are paying ingredient-grade premiums for traditionally brewed varieties that guarantee flavor consistency across standardized menus.
- Mustard:Acidulated seed-paste emulsion ranging from mild yellow to pungent Dijon-style heat profiles. European retail and deli channels sustain demand for specialty mustard formats with protected geographical indications.
- Mayonnaise:Oil-in-water emulsion stabilized by egg yolk lecithin and hydrocolloid systems. Private-label penetration has compressed branded margins in European and North American retail, pushing manufacturers toward food service bulk formats.
Ketchup anchors the volume base while soy sauce gains share at the steepest rate.
Ingredient Type:
Cost tier stratification separates premium-positioned certification grades from economy formulations, with mid-tier synthetic additive systems facing the steepest demand erosion.
- Organic:USDA-certified or equivalent production excluding synthetic pesticides and GMO inputs. North American retail shelf placement now requires organic certification as baseline credential, with EFSA-approved natural preservatives validating shelf stability claims.
- Low-Sodium:Reformulated products meeting FDA sodium-reduction targets through potassium chloride substitution and flavor-enhancer systems. European and North American manufacturers are absorbing R&D costs to rebuild taste profiles without salt dependence.
- Gluten-Free:Formulations eliminating wheat-derived ingredients through alternative starch and hydrocolloid stabilization. Celiac-safe certification expands addressable market in European retail where gluten intolerance diagnosis rates exceed global averages.
- Artificial:Synthetic preservative and flavoring systems including benzoates, sorbates, and petrochemical-derived colorants. Clean-label mandates in EU and North American markets are accelerating demand collapse for this tier.
Artificial ingredient systems anchor the volume base while organic certification gains share at the steepest rate.
Packaging Type:
Volume concentration in food service channels is rotating procurement specifications toward single-serve formats that minimize waste and standardize portion control.
- Sachets:Laminated film pouches containing single-serve condiment portions for airline, quick-service, and delivery applications. Indonesian and Vietnamese cloud kitchen operators are adopting sachet systems to reduce spoilage and simplify inventory management.
- Pouches:Flexible stand-up or flat formats with spout or tear-notch dispensing for food service and retail. Thailand and Malaysia manufacturers are deploying high-pressure processing-compatible pouch lines to enter clean-label segments without dedicated facility investment.
- Bottles:Rigid PET or glass containers with flip-top or screw-cap closure systems. Retail-centric demand persists in European and North American households with established pantry stocking patterns.
- Jars:Wide-mouth glass containers for spoonable dressings and thick condiments. Premium positioning in European deli and specialty retail channels sustains glass jar preference for visual quality signaling.
Bottles anchor the volume base while sachets gain share at the steepest rate.
Distribution Channel:
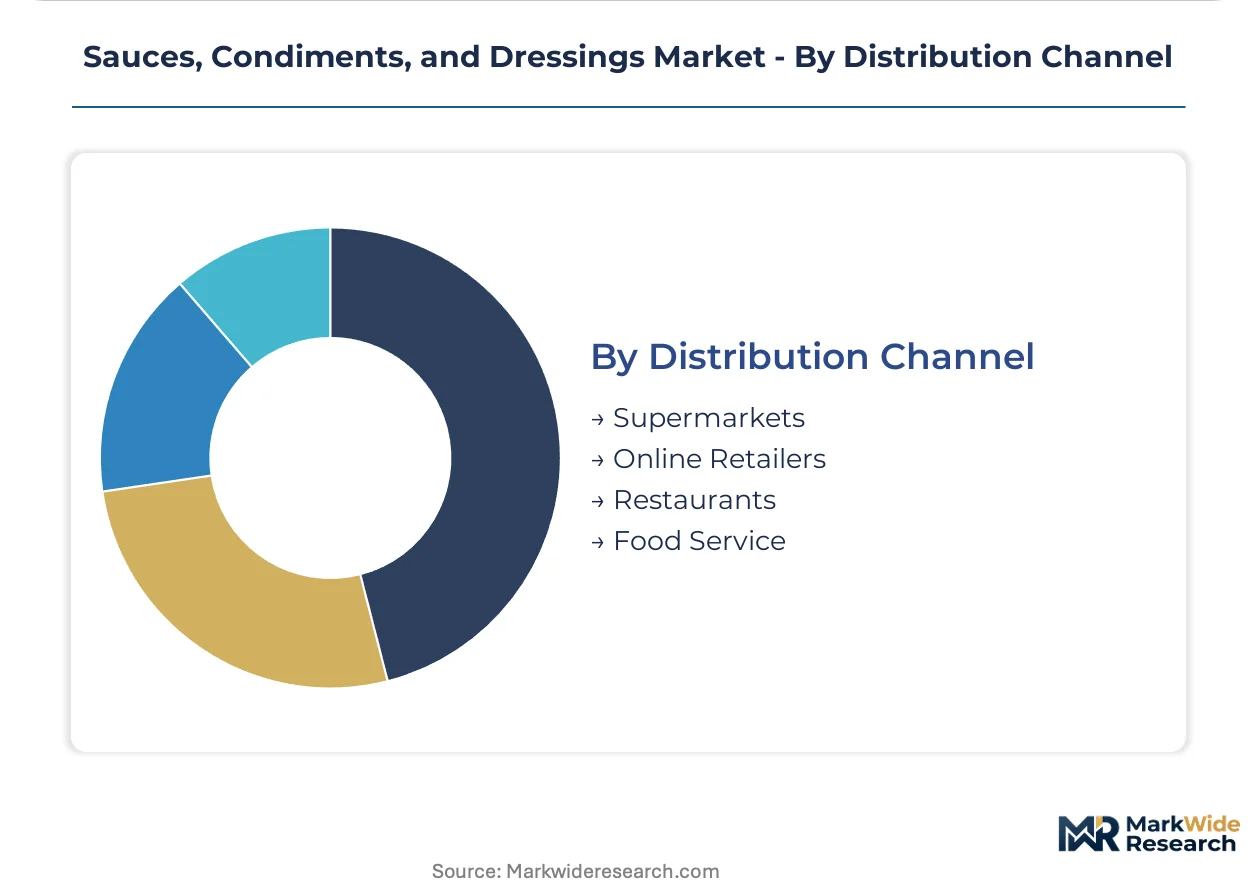
Customer type bifurcation splits the market between retail shoppers prioritizing shelf-stable convenience and food service operators demanding format flexibility and cost control.
- Food Service:Direct procurement by chain restaurants, cloud kitchens, and institutional caterers for bulk and portion-controlled formats. Southeast Asian quick-service expansion is pulling condiment volumes into food service specifications with customized viscosity and packaging requirements.
- Restaurants:Independent and small-chain operators sourcing through broadline distributors or direct manufacturer relationships. Fermented sauce categories command premium positioning through umami concentration guarantees that standardize finished dish quality.
- Supermarkets:Branded and private-label retail shelf placement through mass-market grocery channels. Clean-label certification has become table stakes for North American retail access, with organic and natural preservative claims determining shelf positioning.
- Online Retailers:E-commerce direct-to-consumer and third-party marketplace distribution. Subscription and bulk formats are gaining traction in European markets where pantry stocking convenience outweighs immediate gratification preferences.
Supermarkets anchor the volume base while food service gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Europe's role as a distribution hub for refrigerated dressing categories, while Singapore's Tuas Port expansion anchors Southeast Asian condiment transshipment.
United States
Quick-service restaurant chains and cloud kitchen operators are pulling condiment procurement toward food service specifications. FDA sodium-reduction targets are forcing reformulation investments across ketchup and mayonnaise production lines. Chicago's manufacturing corridor hosts bulk format production facilities supplying national restaurant distributors.
Germany
EFSA-approved natural preservative mandates are accelerating clean-label transitions in refrigerated dressing segments. EU F-Gas Regulation compliance is reshaping cold-chain distribution networks for fermented sauce categories. The Rhine-Ruhr industrial cluster concentrates high-pressure processing equipment manufacturing for regional co-manufacturers.
China
Urbanization and street-food commercialization are amplifying single-serve sachet demand in tier-one and tier-two cities. SAMR food additive codes are fragmenting formulation compliance for multinational suppliers. Yangtze River Delta manufacturing zones dominate hydrocolloid stabilizer production for texture-modified dressings.
Indonesia
Cloud kitchen penetration in Jakarta and Surabaya is rotating procurement toward pouch-format condiment systems. BIS-equivalent national standards are tightening import requirements for fermented sauce categories. Jababeka Industrial Estate hosts regional co-manufacturing facilities serving ASEAN food service distributors.
Vietnam
Hawker-stall and food-court throughput expansion is compressing household cooking frequency and concentrating condiment demand in commercial channels. National food safety regulations are mandating lot-traceability systems for fermented sauce imports. Ho Chi Minh City's packaging engineering cluster specializes in high-pressure processing-compatible pouch lines.
Sauces, Condiments, and Dressings Market Competitive Landscape
Listed leaders compete with private specialists across formulation complexity and channel access dimensions. The market exhibits tiered concentration with multinational conglomerates commanding retail shelf space while regional specialists capture food service procurement. Three archetypes dominate: fermentation-authenticity specialists, clean-label technology adopters, and commodity-scale volume players. M&A activity concentrates on acquiring regional flavor-system capabilities, while capacity expansion focuses on modular high-pressure processing deployment.
Within the multinational conglomerate tier, Unilever, The Kraft Heinz Company, and McCormick & Company exemplify distinct strategic positions. Unilever represents the global manufacturing footprint archetype supplying bulk formats across continents. The Kraft Heinz Company anchors North American retail-centric positioning through iconic branded portfolios. McCormick & Company occupies the specialized flavor-system niche targeting ethnic cuisine segments in dual-channel deployment.
| Leading Market Players |
|---|
| Unilever |
| The Kraft Heinz Company |
| McCormick & Company |
| Conagra Brands |
| Nestlé |
| Kikkoman Corporation |
| General Mills |
| Del Monte Foods |
| Bolton Group |
| Others |
Value Network & Pricing Analysis
Potassium chloride substitution for sodium chloride in low-sodium reformulations is simultaneously relocating hydrocolloid sourcing to Southeast Asian processing hubs and compressing margin structures across mid-tier ketchup and mayonnaise producers. This input swap forces manufacturers to absorb dual cost pressures from premium stabilizer grades and extended R&D validation cycles while private-label competitors exploit commodity sodium-based formulations.
Pricing Analysis
Volume-discount tiering structures separate national quick-service chain contracts from independent restaurant spot purchasing. Three-tier pricing stratifies across USDA Organic-certified premium lines, clean-label standard formulations, and economy synthetic-preservative systems. Pricing pressure stems from private-label expansion in North American retail ketchup and mayonnaise, where branded players face margin compression without differentiation claims. Food service buyers exhibit lowest price sensitivity due to menu-standardization requirements, while supermarket private-label shoppers drive aggressive cost negotiation.
Supply Chain Analysis
Inventory-strategy preferences bifurcate between just-in-time pouch replenishment for cloud kitchen operators and strategic tomato paste stockpiles by North American ketchup manufacturers. Raw material flows draw from Yangtze River Delta hydrocolloid processors, Yangling fermentation facilities for soy sauce cultures, and California Central Valley tomato processors. Single-source vulnerability concentrates in Chinese hydrocolloid stabilizer production for texture-modified dressings. Distribution feeds from regional co-manufacturing clusters through broadline food service distributors to quick-service chain specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from private-label compression in mature condiment categories, requiring defensive repositioning around clean-label certification and food service channel capture to preserve margin structures.
For Market Incumbents: Fortify fermentation-authenticity positioning in soy sauce through captive koji culture propagation facilities, locking ingredient-grade premium capture against synthetic amino acid substitutes. Accelerate USDA Organic certification coverage across retail portfolios to defend shelf placement against emerging clean-label specialists. Channel control through direct cloud kitchen supply agreements in Jakarta and Ho Chi Minh City limits distributor margin extraction. For New Entrants and Emerging Players: USDA Organic fast-track certification programs unlock immediate North American retail access where incumbent conversion lags create temporary shelf availability. Target Indonesian and Vietnamese cloud kitchen operators with high-pressure processing-compatible pouch formats, exploiting incumbent capital constraints in modular cold-pasteurization deployment. Go-to-market leverage rests on co-manufacturing partnerships with Thai and Malaysian processors already possessing clean-label equipment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed regional flavor-system specialists in Southeast Asia possessing fermented sauce expertise but lacking global distribution reach. Five-to-ten-year viability hinges on consolidation of fragmented ASEAN co-manufacturing capacity under platforms with cold-chain logistics integration. Monitor FDA sodium-reduction enforcement intensity as inflection signal for low-sodium reformulation capex demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Koji Culture Propagation | Captive fermentation inputs secure soy sauce authenticity premiums against synthetic substitutes. |
| Modular High-Pressure Processing Deployment | Thai and Malaysian co-manufacturers enter clean-label segments without dedicated facility construction. |
| USDA Organic Certification Fast-Track | North American retail shelf placement now requires organic credentials as baseline market access. |
| Cloud Kitchen Direct Supply Agreements | Jakarta and Ho Chi Minh City operators standardize pouch procurement for portion-controlled waste reduction. |
| Fermentation Microbiologist Talent Acquisition | Traditional soy sauce production requires specialized expertise that industrial food science programs undersupply. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA sodium-reduction guidance documents, EFSA natural preservative approval registers, and ASEAN customs trade flows. Input sources span R&D directors at multinational condiment manufacturers, procurement leads at Indonesian cloud kitchen operators, category buyers at North American supermarket chains, and fermentation microbiologists at Japanese soy sauce producers. Secondary validation draws from USDA Organic certification databases, SAMR food additive code filings, and BIS standard notifications. Bottom-up volume modeling triangulates against top-down expenditure allocation surveys.
Segmentation dimensions modeled include product type stratification, ingredient certification tier, packaging format specification, and distribution channel economics across the projection horizon. CAGRs derive from trend extrapolation of quick-service restaurant expansion rates, clean-label adoption curves, and cloud kitchen penetration patterns. Industry-specific forecast inputs incorporate EU F-Gas Regulation compliance cost trajectories and high-pressure processing equipment miniaturization adoption rates.
Underlying assumptions cover sustained FDA sodium-reduction enforcement, stable Yangtze River Delta hydrocolloid supply, and continued ASEAN urbanization-driven food service channel growth, with deviation risk concentrated in regulatory acceleration or trade restriction scenarios. Revision becomes warranted when private-label penetration in North American retail ketchup exceeds branded defense capacity or when fermentation microbiologist scarcity triggers production bottlenecks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Dips and Spreads Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Vegan Sauces Market
Condiments & Sauces
Low Salt Soy Sauce Market
Condiments & Sauces
Sauce Making Machine Market
Condiments & Sauces
Chocolate Syrup Market
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
Dipping Sauces Market
Condiments & Sauces
Ketchup Market
Condiments & Sauces
Sweet and Savory Spread Market
Condiments & Sauces
Europe Gluten-Free Soups and Sauces Market
Condiments & Sauces
Hot Sauce Market
Condiments & Sauces
Sandwich Spread Market
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
Gluten-Free Soups and Sauces Market
Condiments & Sauces
Pesto Sauces Market