
 Sun-Dried Tomato Umami Concentrate Systems Market | 2026-2036
Sun-Dried Tomato Umami Concentrate Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Sun-Dried Tomato Umami Concentrate Systems Market Insights
Ready-to-eat meal manufacturing is broadening its share of system deployments as brands seek concentrated tomato-derived glutamate alternatives to MSG. Givaudan leverages its flavor science infrastructure to anchor premium extraction partnerships across Mediterranean sourcing zones. Kerry Group sustains competitive positioning through integrated ingredient-application laboratories that shorten formulation cycles for foodservice clients. Sensient Technologies specializes in natural color and flavor convergence, occupying a technical niche where umami intensity meets visual appeal specifications.
Sun-dried tomato umami concentrate systems comprise integrated processing equipment that extracts, concentrates, and stabilizes glutamate-rich compounds from dehydrated Solanum lycopersicum fruit, typically achieving 20-40% solids content through controlled thermal or membrane-based methods for downstream flavor formulation. Vacuum concentration technology leads installed capacity due to its preservation of volatile aromatic sulfur compounds critical to authentic tomato flavor profiles, though membrane filtration represents the fastest-growing segment as cold-process claims gain retail label traction. Batch processing systems still dominate among craft and mid-scale specialty ingredient suppliers where formula flexibility outweighs throughput economics, while continuous processing systems capture margin pools in beverage enhancement applications demanding homogenized output at scale.
EU REACH and F-Gas Regulation frameworks govern solvent recovery and refrigerant use in extraction equipment sold across Europe, while FDA GRAS self-affirmation pathways shape formulation claims in the United States. EFSA clean-label guidance and evolving USDA organic processing standards are tightening allowable inputs and documentation requirements for natural flavor positioning. Stakeholders must monitor regulatory divergence between jurisdictions where umami concentrate labeling as natural flavor versus processing aid determines market access and premium capture potential.
Market Dynamics
Membrane filtration technology is displacing vacuum concentration as the dominant extraction method, driven by cold-process label claims that command retail premiums in European clean-label formulations.
Growth Catalysts
- EU Green Deal sustainability mandates:Equipment buyers in Italy and Spain prioritize energy-efficient thermal systems to meet carbon reduction targets in processing facilities.
- Clean-label MSG replacement demand:Ready-to-eat meal manufacturers across North America are reformulating with tomato-derived glutamate to satisfy natural flavor positioning requirements.
- Membrane filtration adoption:Cold-process extraction preserves volatile sulfur compounds while enabling organic certification compliance that vacuum systems cannot match.
Market Restraints
- Input cost volatility:Solanum lycopersicum paste prices fluctuate with California drought cycles and Spanish irrigation restrictions.
- Supply concentration risk:Specialty membrane suppliers cluster in Germany and Switzerland, creating procurement bottlenecks for mid-scale processors.
- REACH compliance friction:ECHA substance registration requirements extend equipment qualification timelines by 8-14 months for non-EU manufacturers.
Strategic Opportunities
- Beverage enhancement applications:Umami concentrate systems penetrate functional drink formulations in Japan where savory flavor profiles gain traction.
- USDA organic processing standards:Tightening allowable inputs creates first-mover advantage for processors achieving dual organic-kosher certification.
- Direct-to-foodservice distribution:Bypassing ingredient brokers lets concentrate producers capture formulation advisory fees from restaurant chains.
Industry Challenges
- Membrane fouling expertise gap:Maintenance technicians with ceramic and polymeric filtration experience command premium wages in California's Central Valley.
- Legacy batch system integration:Continuous processing retrofits require custom engineering to preserve existing clean-in-place infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sun-Dried Tomato Umami Concentrate Systems Market |
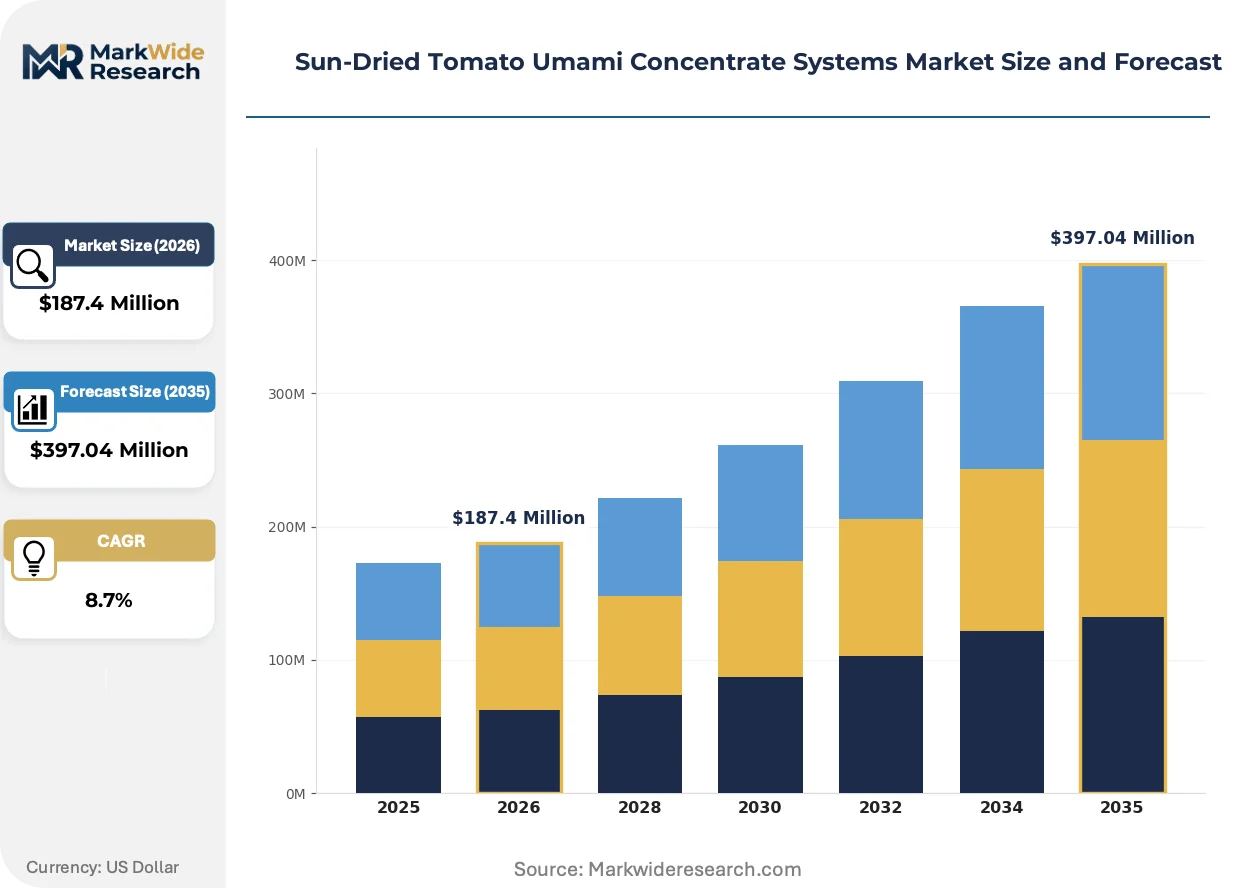
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Processing Systems, Continuous Processing Systems, Modular Units, Customized Solutions Technology: Vacuum Concentration, Membrane Filtration, Thermal Evaporation, Ultrafiltration, Spray Drying Application: Food Flavoring, Beverage Enhancement, Nutritional Supplements, Culinary Ingredients, Snack Seasonings End User: Food & Beverage Manufacturers, Specialty Ingredient Suppliers, Nutraceutical Companies, Foodservice Providers |
| Companies Covered | Lycored, Givaudan, Kerry Group, International Flavors & Fragrances, Symrise, Sensient Technologies, Kanegrade, Döhler, Olam Food Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sun-Dried Tomato Umami Concentrate Systems Market Trends and Innovations
Extraction technology convergence with sustainability verification systems is redefining equipment procurement criteria. Processors now prioritize traceability architecture alongside throughput metrics.
Membrane filtration is decentralizing umami concentrate production by enabling smaller-scale facilities to achieve commercial-grade glutamate concentration without vacuum infrastructure. Craft ingredient suppliers in Spain's Extremadura region are adopting skid-mounted systems at half the capital intensity of traditional plants. This distributed model compresses supply chains between tomato growing zones and flavor houses.
REACH F-Gas Regulation is phasing out hydrofluorocarbon refrigerants in extraction cooling systems, forcing equipment retrofits across European installed bases. Manufacturers are pivoting to ammonia-based or magnetic bearing compressor alternatives. Italian processors face the steepest compliance curves due to aging vacuum concentration fleets concentrated in Parma and Foggia.
Ingredient procurement is consolidating through long-term offtake agreements that bundle concentrate supply with formulation technical service. Foodservice clients in North America are displacing spot-market purchasing with integrated partnerships. This shift is most pronounced in California where restaurant chains seek guaranteed umami intensity specifications for menu consistency.
Sun-Dried Tomato Umami Concentrate Systems Market Segmentation
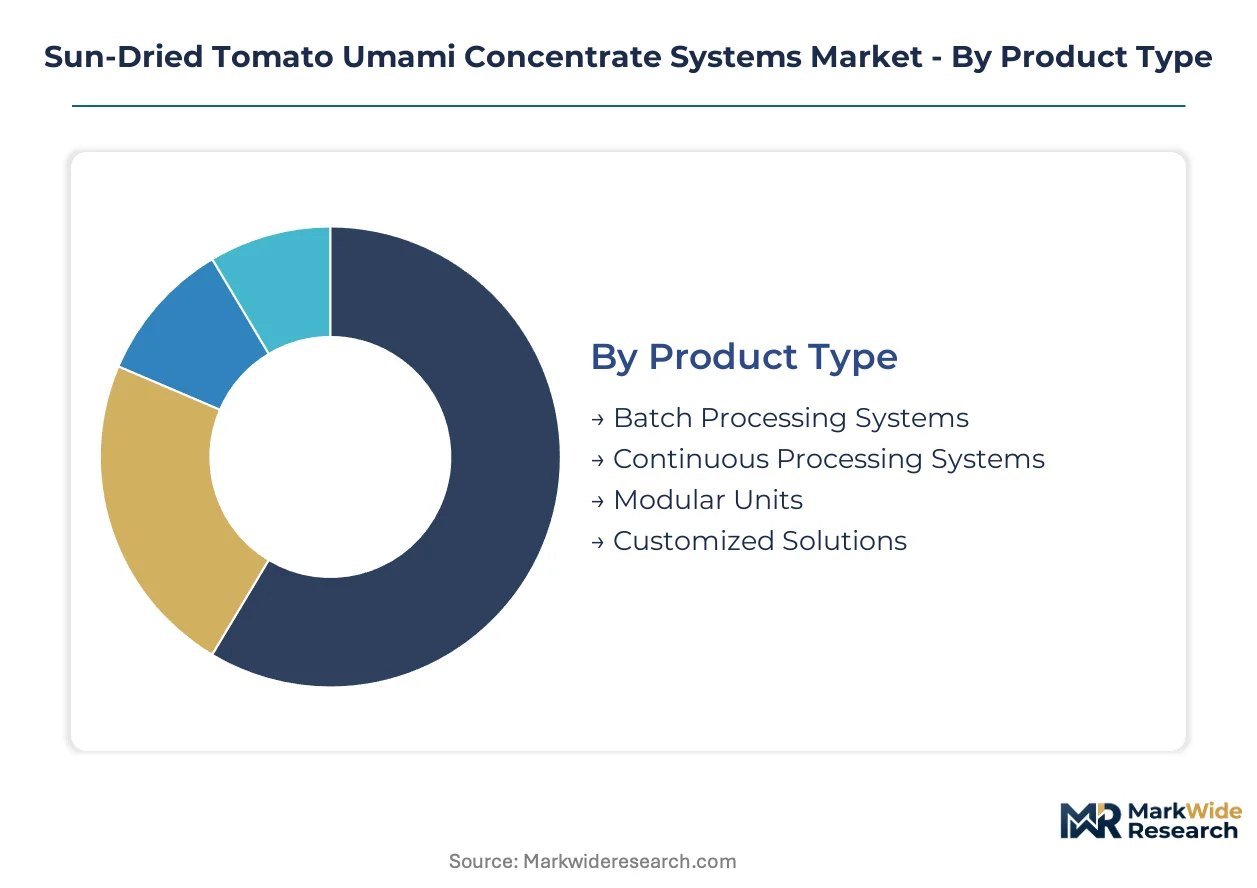
Equipment buyers in the sun-dried tomato umami concentrate systems market face divergent capital deployment logic depending on scale and application. Segmentation reveals where batch flexibility commands premium pricing versus where continuous throughput drives margin compression.
Product Type:
Volume throughput separates economy-tier purchasers from premium-positioned specialists seeking formula agility.
- Batch Processing Systems:Intermittent operation vessels with configurable temperature profiles enable craft producers to switch between tomato varietals without cross-contamination. Specialty ingredient suppliers in Italy's Emilia-Romagna cluster favor these systems for small-lot organic certification runs where recipe flexibility outweighs unit economics.
- Continuous Processing Systems:Steady-state operation with integrated CIP infrastructure achieves homogenized output for beverage enhancement applications at scale. California's Central Valley processors deploy these lines to supply restaurant chains demanding consistent glutamate intensity across quarterly volumes.
- Modular Units:Skid-mounted configurations reduce installation timelines for mid-scale entrants in Spain's Extremadura region.
- Customized Solutions:Engineered-to-order systems address legacy facility constraints in Parma's aging processing infrastructure.
Today's leader: Batch Processing Systems. Tomorrow's challenger: Continuous Processing Systems.
Technology:
Cold-process claims versus thermal efficiency defines procurement criteria across European and North American buyers.
- Vacuum Concentration:Reduced-pressure thermal processing preserves volatile aromatic sulfur compounds responsible for authentic tomato flavor signatures. Italian equipment buyers in Foggia maintain installed dominance here despite higher energy intensity versus membrane alternatives.
- Membrane Filtration:Pressure-driven separation without phase change enables organic certification compliance and cold-process label positioning. German and Swiss membrane suppliers face order backlogs as Spanish processors retrofit for EU Green Deal carbon targets.
- Thermal Evaporation:Open or forced-circulation systems serve budget-constrained entrants in developing markets.
- Ultrafiltration:Molecular weight cut-off selectivity targets specific glutamate fractions for nutritional supplement applications.
- Spray Drying:Atomization and hot-air dehydration produces shelf-stable powders for snack seasoning blends.
Membrane Filtration is climbing the fastest as clean-label mandates harden across European retail channels.
Application:
End-use concentration determines equipment specification stringency and formulation advisory revenue potential.
- Food Flavoring:Concentrated extracts replace synthetic MSG in ready-to-eat meal reformulations across North American manufacturing. Natural flavor positioning requirements from major retail chains drive specification intensity for glutamate purity and sulfur compound retention.
- Beverage Enhancement:Savory flavor profiles penetrate functional drink categories in Japan where umami-forward formulations differentiate saturated markets. Homogenized output specifications demand continuous processing infrastructure with real-time viscosity monitoring.
- Nutritional Supplements:Standardized glutamate content targets health-positioned powder blends.
- Culinary Ingredients:Foodservice distributors seek paste concentrates for restaurant chain menu consistency.
- Snack Seasonings:Dry powder applications favor spray-dried inputs with extended shelf stability.
Food Flavoring maintains volume dominance. Beverage Enhancement shows steepest expansion trajectory.
End User:
Customer scale and technical sophistication shape service bundling and pricing architecture.
- Food & Beverage Manufacturers:Integrated multinationals with captive R&D facilities demand equipment-software bundles with predictive maintenance modules. These buyers concentrate procurement authority at headquarters level with standardized specifications across California and European plant networks.
- Specialty Ingredient Suppliers:Mid-scale operators with formulation expertise capture premium positioning through technical service bundling. Spain's Extremadura cluster exemplifies this model where regional processors advise foodservice clients on umami intensity calibration.
- Nutraceutical Companies:Certificate-driven buyers prioritize organic and kosher compliance documentation.
- Foodservice Providers:Direct procurement from concentrate producers bypasses ingredient brokers in North American restaurant chain consolidation.
Food & Beverage Manufacturers command current capacity allocation. Specialty Ingredient Suppliers are gaining share fastest through advisory fee capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's Parma-Foggia processing corridor anchors installed capacity for vacuum concentration systems, while California's Central Valley and Spain's Extremadura region drive membrane filtration adoption as clean-label mandates reshape procurement patterns across three continents.
Italy
Artisan food manufacturers in Emilia-Romagna sustain demand for batch processing flexibility, while industrial processors in Foggia face steep REACH F-Gas Regulation compliance curves for aging vacuum concentration fleets. ECHA substance registration requirements extend equipment qualification timelines for non-EU suppliers entering this market. Parma's aging processing infrastructure is driving customized solution demand for legacy facility retrofits.
United States
Ready-to-eat meal manufacturers across California reformulate with tomato-derived glutamate to satisfy natural flavor positioning requirements from major retail chains. FDA GRAS self-affirmation pathways shape formulation claims, while USDA organic processing standards tighten allowable inputs for premium positioning. California's Central Valley processors deploy continuous processing lines to supply restaurant chains demanding consistent glutamate intensity across quarterly volumes.
Spain
Extremadura's craft ingredient suppliers adopt skid-mounted membrane systems at half the capital intensity of traditional plants, compressing supply chains between tomato growing zones and flavor houses. EU Green Deal sustainability mandates prioritize energy-efficient thermal systems to meet carbon reduction targets in processing facilities. German and Swiss membrane suppliers face order backlogs as Spanish processors retrofit for compliance.
Germany
Specialty membrane suppliers cluster around industrial zones, creating procurement bottlenecks for mid-scale processors across European markets. REACH compliance friction extends equipment qualification timelines by 8-14 months for non-EU manufacturers seeking market access. Bavaria's precision engineering base supplies ceramic and polymeric filtration components to tomato processing facilities in Italy and Spain.
Japan
Umami concentrate systems penetrate functional drink formulations where savory flavor profiles differentiate saturated beverage markets. METI standards influence equipment specifications for homogenized output with real-time viscosity monitoring. Kanto region food scientists collaborate with European extraction technology providers to adapt tomato-derived glutamate for traditional dashi-inspired applications.
Sun-Dried Tomato Umami Concentrate Systems Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment fabricators ally with flavor science laboratories to shorten formulation cycles. The vendor base organizes around three tiers: integrated multinationals with captive R&D facilities, mid-scale specialists bundling technical advisory services, and regional fabricators serving localized processing infrastructure. Two archetypes command attention—those anchoring premium extraction partnerships across Mediterranean sourcing zones, and those occupying technical niches where umami intensity meets visual appeal specifications. Competitive moves concentrate on portfolio diversification into adjacent natural flavor categories and geographic expansion through distributed production models.
Within the integrated multinational tier, Givaudan, Kerry Group, and Sensient Technologies exemplify divergent strategic positioning. Givaudan leverages flavor science infrastructure to anchor premium extraction partnerships. Kerry Group sustains positioning through integrated ingredient-application laboratories. Sensient Technologies occupies a technical niche where natural color and flavor convergence creates specification advantages for clients demanding simultaneous umami intensity and visual appeal compliance.
| Leading Market Players |
|---|
| Lycored |
| Givaudan |
| Kerry Group |
| International Flavors & Fragrances |
| Symrise |
| Sensient Technologies |
| Kanegrade |
| Döhler |
| Olam Food Ingredients |
| Others |
Pricing and Supply Chain Analysis
Solanum lycopersicum paste cost volatility traces from California drought cycles and Spanish irrigation restrictions through membrane filtration equipment premiums to final concentrate pricing tiers, with cold-process certification claims commanding substantial markups over vacuum-concentrated alternatives in European retail channels.
Pricing Analysis
Retailer markup layers separate premium-positioned membrane filtration concentrates from economy-tier vacuum-processed alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with USDA organic and EU organic labels commanding substantial premiums over conventional offerings. Price differentiation stems from cold-process claims and volatile sulfur compound retention specifications. Cost compression in economy-tier concentrates is intensifying because California drought cycles squeeze paste input margins. Mid-scale specialty ingredient suppliers exhibit highest price sensitivity, while integrated multinationals with captive R&D prioritize specification compliance over unit cost.
Supply Chain Analysis
Ceramic and polymeric membrane supply rests on German and Swiss specialty filtration producers, creating procurement bottlenecks for Spanish and Italian processors retrofitting for EU Green Deal compliance. Raw material dependencies span Solanum lycopersicum paste from California and Spain, membrane modules from Bavaria's precision engineering base, and ammonia-based refrigerants replacing phased-out hydrofluorocarbons. Single-source vulnerability concentrates in membrane supplier clusters around industrial zones. Distribution runs through long-term offtake agreements bundling concentrate supply with formulation technical service, displacing spot-market purchasing among North American restaurant chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration technology cost curves and clean-label premium tier expansion create margin expansion headroom for processors achieving dual organic-kosher certification ahead of tightening USDA standards.
For Market Incumbents: Cement positioning in Mediterranean sourcing zones through backward integration into tomato paste supply and captive membrane maintenance capabilities. Kerry Group's integrated ingredient-application laboratory model offers template for shortening formulation cycles. Threat from German and Swiss membrane supplier order backlogs demands inventory pre-positioning. Certification investment in REACH F-Gas Regulation compliance represents critical defensive lever for Italian vacuum concentration fleet operators. For New Entrants and Emerging Players: Membrane filtration technology-first wedges open entry paths through skid-mounted configurations at half traditional capital intensity. Spain's Extremadura craft processing cluster presents most penetrable geography, with decentralized production compressing supply chains between growing zones and flavor houses. Direct-to-foodservice distribution bypassing ingredient brokers captures formulation advisory fees from restaurant chains seeking menu consistency guarantees. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale specialty ingredient suppliers lack formulation advisory capabilities to match integrated multinational service bundling. Long-term viability favors processors with traceability architecture and sustainability verification systems alongside extraction throughput. Acquisition target archetype: Extremadura-region membrane filtration adopters with established foodservice client relationships. Signal to watch is membrane fouling technician wage inflation in California's Central Valley indicating capacity constraint inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | EU Green Deal carbon targets in Italy and Spain drive equipment replacement cycles. |
| Backward Integration into Paste Supply | California drought exposure mitigation secures input cost predictability. |
| Dual Organic-Kosher Certification | USDA tightening creates first-mover premium capture in North American retail. |
| Direct-to-Foodservice Distribution | Bypassing brokers captures advisory fees from restaurant chain consolidation. |
| Ammonia-Based Refrigerant Transition | REACH F-Gas Regulation compliance preserves European market access. |
Research Methodology
Multiple input streams — primary interviews with plant managers and procurement leads at downstream flavor houses, technical R&D directors at membrane suppliers, and aftermarket service heads at equipment fabricators — were reconciled against secondary validation from ECHA substance registration databases, EU customs trade records, and SEC filings of integrated multinationals. Bottom-up and top-down triangulation cross-checked equipment installation counts against concentrate production volume estimates.
Data-stream reconciliation applied analytical framework across product type, technology, application, and end-user segmentation dimensions over the projection horizon. CAGRs derived from equipment capacity expansion pipelines and reformulation cycle timelines in ready-to-eat meal manufacturing. Industry-specific forecast inputs incorporated California drought frequency models and REACH F-Gas Regulation phase-out schedules.
The model holds under stable regulatory enforcement timelines and membrane supplier capacity expansion; deviation in ECHA registration processing delays or German ceramic membrane export restrictions would shift equipment procurement patterns. Forecasts reflect documented assumptions on clean-label mandate adoption rates and carbon target stringency. California water policy, EU Green Deal implementation pace, and membrane fouling expertise availability warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Ketchup Concentrates Market
Condiments & Sauces
Dipping Sauces Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Hoisin Sauce Market
Condiments & Sauces
Hot Sauce Market
Condiments & Sauces
Culinary Sauces Market
Condiments & Sauces
Australia and New Zealand Tomato Sauce Market
Condiments & Sauces
Global Hot Pot Condiment Market
Condiments & Sauces
Chocolate Syrup Market
Condiments & Sauces
GCC Condiment Sauces (for Hospitality Sector) Market
Condiments & Sauces
Vegan Sauces Market
Condiments & Sauces
Mayonnaise Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
Sweet and Savory Spread Market
Condiments & Sauces
Sauce Market