
 Canada Food Preservatives Market | 2026-2036
Canada Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Food Preservatives Market Outlook
Clean-label food manufacturers are reorganizing procurement priorities across Ontario and Quebec processing corridors. Kerry Group plc leverages its North American ingredient technology base to sustain natural preservation portfolios for Canadian bakery and dairy clients. Corbion NV anchors its fermentation-derived solutions within the country's clean-label reformulation wave. Cargill Incorporated competes through its integrated supply chain control over plant-derived antimicrobial sources.
Food preservatives comprise chemical or natural substances added to food matrices at concentrations typically ranging from 0.01% to 0.3% by weight to inhibit microbial spoilage, enzymatic degradation, or oxidative rancidity, thereby extending shelf stability and ensuring consumer safety. Their primary commercial purpose centers on reducing food waste across extended distribution networks while maintaining sensory and nutritional integrity. Sorbates retain dominance in Canadian baked goods applications due to proven efficacy against mold and yeast at neutral pH conditions. Benzoates face structural pressure from clean-label substitution trends yet maintain positions in acidified beverages where regulatory thresholds remain permissive. Natural preservation alternatives within the nitrates category are capturing accelerated investment as processors reformulate cured meat portfolios to satisfy retail clean-label mandates.
Health Canada and the Canadian Food Inspection Agency jointly govern preservative usage through the Food and Drug Regulations and the Safe Food for Canadians Regulations, establishing maximum residue limits and labeling disclosure requirements that directly determine formulation feasibility and market access timelines. The CFIA's escalating enforcement of preventive control plans is compelling smaller Ontario and Alberta processors to consolidate supplier relationships toward compliance-vetted preservative distributors. Stakeholders must monitor pending revisions to Health Canada's permitted additive lists while positioning procurement contracts to accommodate rapid formulation pivots should natural preservative approvals accelerate.
Market Dynamics
Clean-label mandates from retail buyers are compressing formulation timelines across Ontario and Quebec processing corridors, forcing procurement departments to requalify preservative suppliers against stricter natural-source requirements.
Growth Catalysts
- Health Canada Approval Acceleration:Streamlined pathways for plant-derived antimicrobials are shortening market access timelines for fermentation-based preservation technologies.
- Toronto-Vancouver Distribution Density:Concentrated metropolitan demand from baked goods and dairy processors creates procurement scale advantages for compliant preservative distributors.
- CFIA Preventive Control Enforcement:Mandatory preventive control plans are consolidating supplier relationships toward vetted distributors with established compliance documentation.
Market Restraints
- Natural Extract Input Volatility:Supply fluctuations for rosemary and green tea extracts destabilize cost structures for clean-label reformulations.
- Technical Efficacy Gaps:Plant-derived antimicrobials demonstrate narrower pH efficacy windows versus synthetic alternatives, constraining application breadth.
- Quebec Supplier Concentration:Fermentation-derived preservation capacity clusters within limited biotech processing facilities, creating geographic supply risk.
Strategic Opportunities
- Alberta Meat Processing Corridor:Underpenetrated cured meat reformulation demand offers expansion potential for natural nitrate alternatives.
- Direct-to-Processor Digital Platforms:Emerging B2B procurement channels are disintermediating traditional distributor relationships for mid-size Ontario bakeries.
- Health Canada Pending Additive Revisions:Anticipated expansions to permitted natural preservative lists position early movers for rapid formulation pivots.
Industry Challenges
- Clean-Label Formulation Expertise Scarcity:Food science talent capable of balancing sensory integrity with natural preservation efficacy commands premium compensation in Toronto and Montreal.
- Dual Certification Burden:Simultaneous CFIA preventive control documentation and Health Canada additive compliance creates administrative overhead for Alberta and Saskatchewan processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Food Preservatives Market |
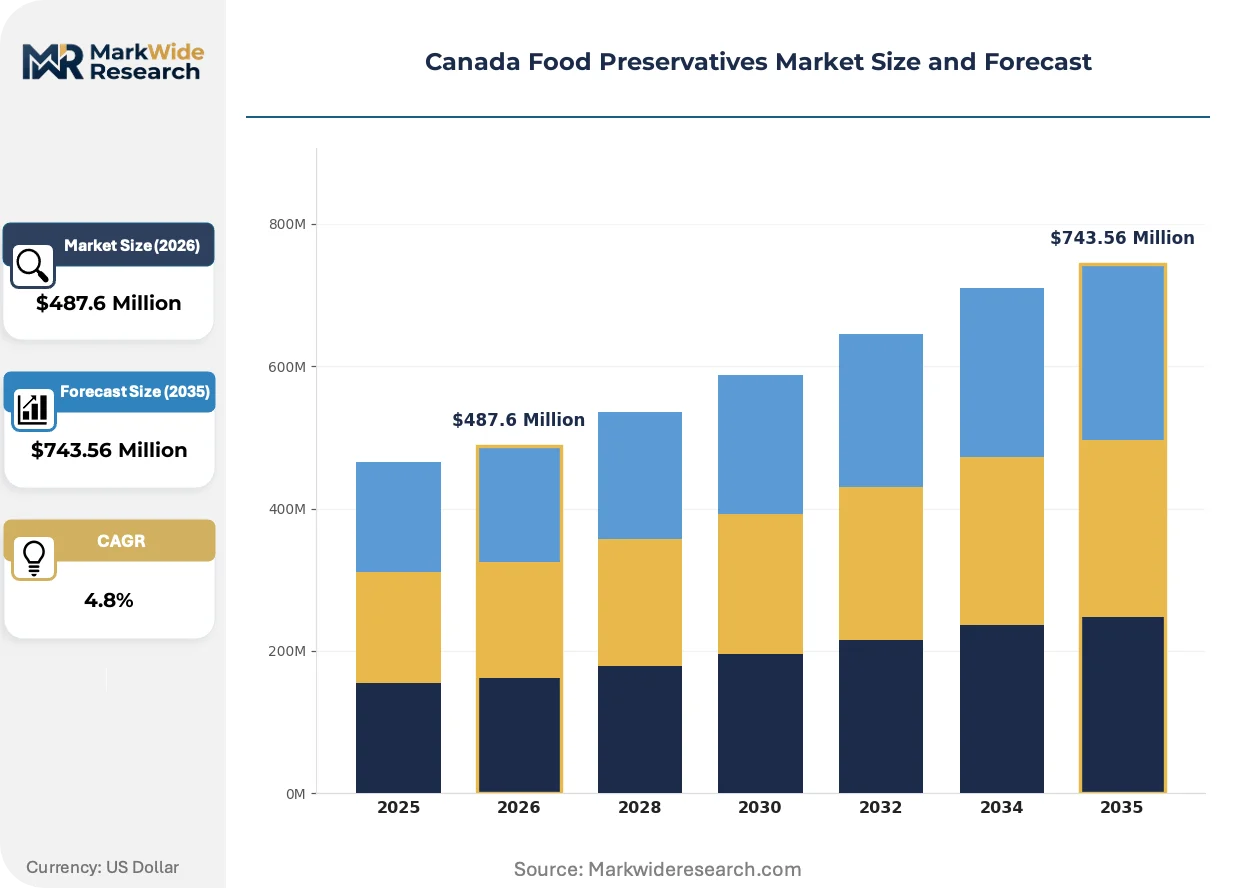
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbates, Benzoates, Nitrates, Sulfites Application: Baked Goods, Dairy Products, Beverages, Snacks End User: Food Manufacturers, Retailers, Restaurants, Household Distribution Channel: Online Sales, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Celanese Corporation, Corbion NV, Kerry Group plc, Brenntag AG, DuPont de Nemours Inc., Koninklijke DSM N.V., Cargill Incorporated, Kemin Industries Inc., ADM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Food Preservatives Market Strategic Shifts
Preservation technology is converging with biotechnology and digital supply chain verification, creating new competitive dimensions beyond traditional efficacy metrics.
Encapsulation technology for essential oil-based antimicrobials is miniaturizing active ingredient delivery systems, enabling targeted release in high-moisture bakery applications. Canadian dairy processors in the Greater Toronto Area are piloting these systems for extended shelf-life yogurt formats. The technology is miniaturizing preservation dosing precision while reducing flavor interference that previously limited natural alternative adoption.
Health Canada's evolving Food and Drug Regulations are tightening maximum residue limit frameworks for synthetic preservatives in acidified beverage categories. Reformulation investments are redirecting toward fermentation-derived benzoate alternatives as compliance deadlines approach. British Columbia beverage manufacturers are accelerating clean-label transitions ahead of anticipated enforcement phases.
Retail buyer consolidation around clean-label specifications is compressing supplier qualification cycles for Ontario and Quebec food manufacturers. Traditional specification-by-specification procurement is yielding to pre-approved vendor lists with embedded compliance documentation. Metropolitan Toronto distribution networks exhibit the most acute concentration of this buying-pattern shift, with major retail banners demanding uniform natural-preservation standards across supplier bases.
Canada Food Preservatives Market Segmentation
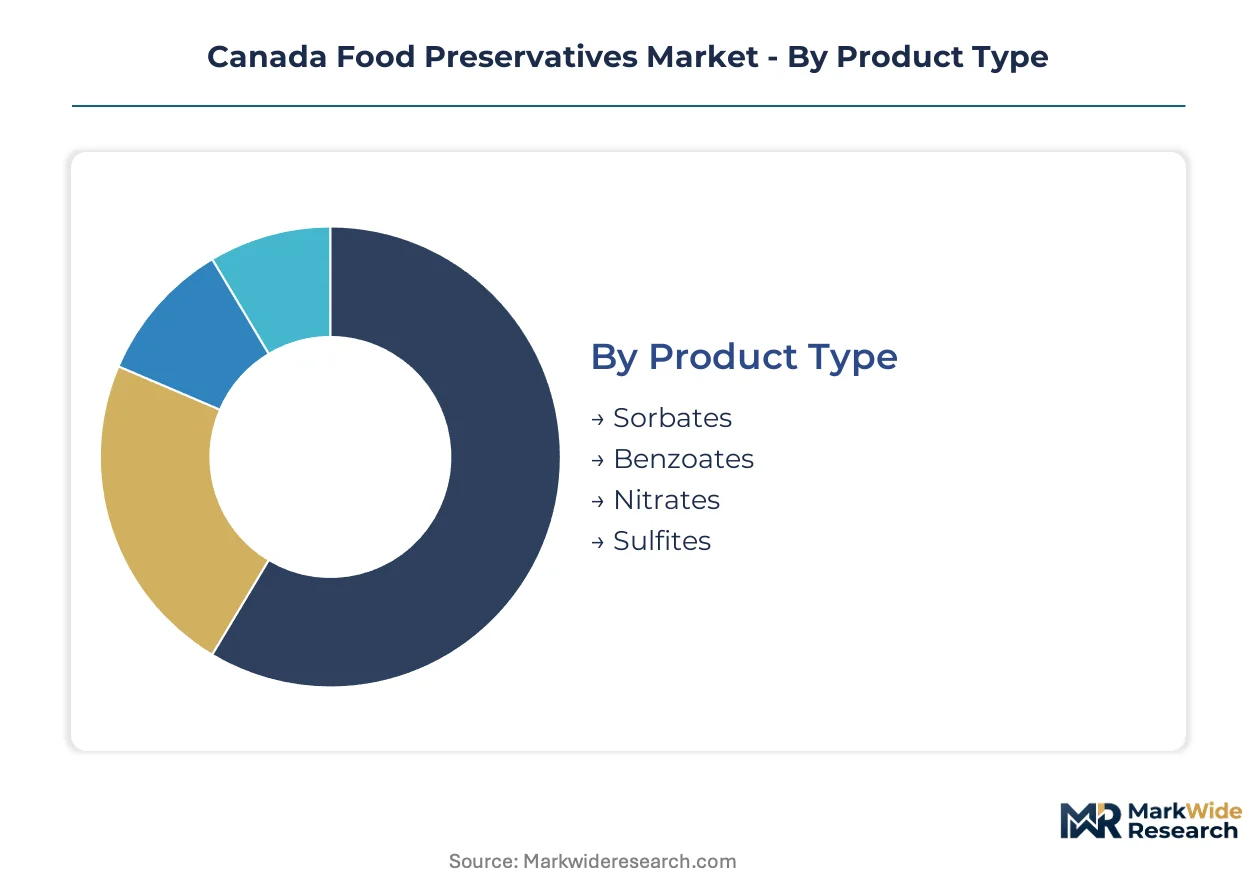
Segmentation reveals how clean-label substitution pressures concentrate unevenly across product categories and end-use channels. Procurement priorities in Ontario and Quebec processing corridors diverge sharply depending on which segment combination food manufacturers occupy.
Product Type:
Substitution pressure from plant-derived alternatives varies dramatically by molecular class, with some synthetic preservatives facing immediate displacement while others retain defensive positions.
- Sorbates:Potassium and sodium salt variants demonstrate proven mold and yeast inhibition across neutral pH bakery matrices. Demand concentrates within Greater Toronto Area industrial bakeries where shelf-life extension requirements remain non-negotiable for retail distribution.
- Nitrates:Natural nitrate alternatives from celery powder and fermented vegetable sources are capturing accelerated investment as Alberta and Ontario meat processors reformulate cured portfolios to satisfy retail clean-label mandates. Health Canada's evolving approval frameworks for natural preservation technologies are redirecting formulation investments toward these plant-derived antimicrobials.
- Benzoates:Synthetic variants face structural pressure from clean-label substitution trends yet maintain positions in acidified beverages where regulatory thresholds remain permissive.
- Sulfites:Antioxidant and antimicrobial applications in wine and dried fruit processing retain niche demand despite consumer sensitivity concerns.
Sorbates anchors the volume base while nitrates gains share at the steepest rate.
Application:
Cost tier stratification separates premium clean-label reformulations from commodity synthetic-dependent production lines across Canadian processing facilities.
- Baked Goods:Industrial bread and pastry manufacturing in Ontario and Quebec corridors drives the largest absolute preservative consumption. Sorbate-dependent formulations dominate mid-market retail products while artisan and premium lines accelerate natural antimicrobial adoption.
- Dairy Products:Extended shelf-life yogurt and cheese applications in the Greater Toronto Area are piloting encapsulation technologies for essential oil-based antimicrobials. The technology is miniaturizing preservation dosing precision while reducing flavor interference that previously limited natural alternative adoption.
- Beverages:Acidified categories retain benzoate tolerance under current Health Canada frameworks, though British Columbia manufacturers are accelerating clean-label transitions ahead of anticipated enforcement phases.
- Snacks:Savory and sweet snack processing exhibits fragmented preservation requirements depending on moisture content and fat stability needs.
Baked goods commands the largest procurement volumes while dairy products is expanding most quickly through clean-label reformulation investments.
End User:
Customer type determines specification stringency, with retail-facing manufacturers facing the most compressed qualification timelines.
- Food Manufacturers:Industrial processors across Ontario and Quebec are consolidating supplier relationships toward compliance-vetted preservative distributors as CFIA preventive control enforcement escalates.
- Retailers:Major Canadian retail banners are demanding uniform natural-preservation standards across supplier bases, compressing specification-by-specification procurement into pre-approved vendor lists with embedded compliance documentation.
- Restaurants:Food service distributors are introducing clean-label requirements for prepared ingredient sourcing, though enforcement remains less systematic than retail channels.
- Household:Consumer direct purchases of preservation ingredients for home food preparation represent minimal commercial significance.
Food manufacturers anchor the volume base while retailers is gaining share at the steepest rate through procurement standardization mandates.
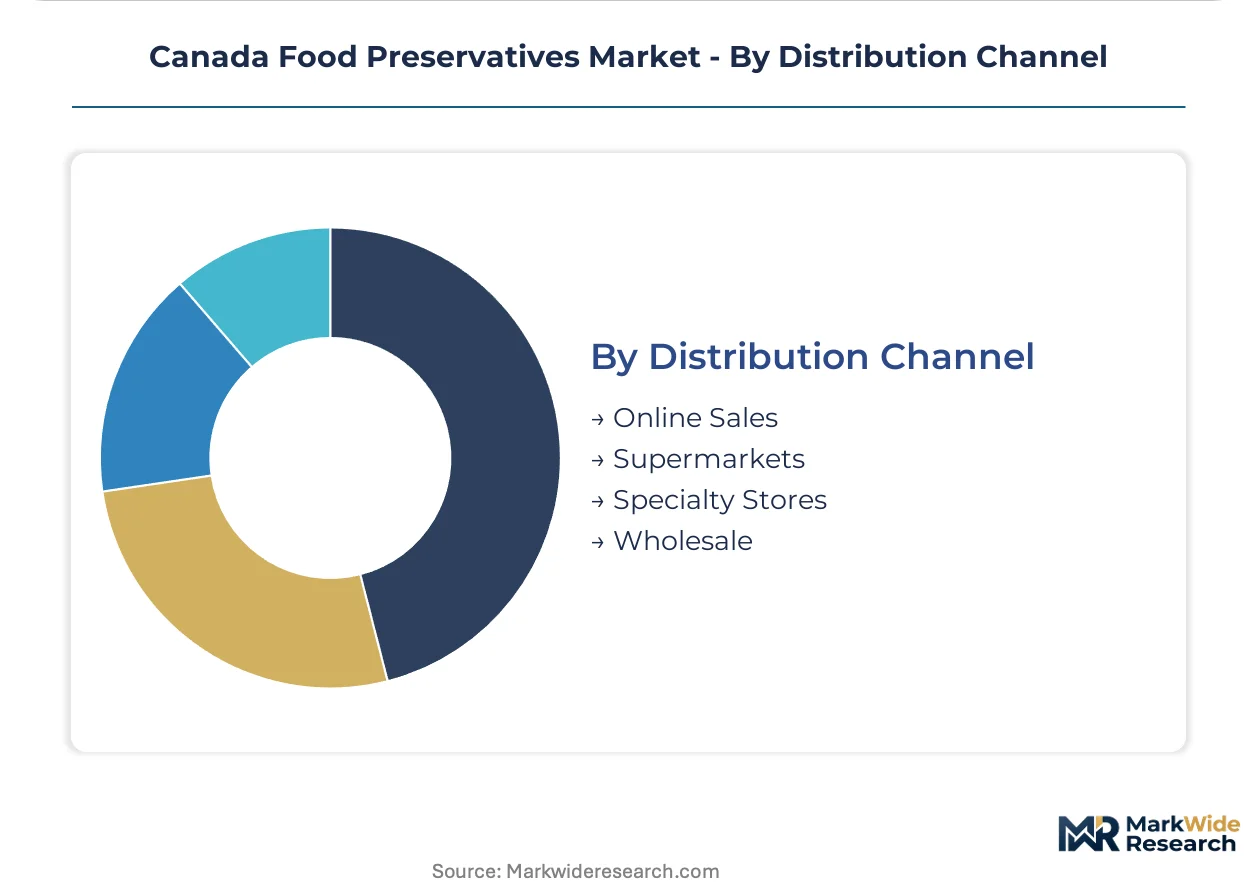
Distribution Channel:
Supply concentration among vetted distributors creates barriers for emerging natural preservative suppliers seeking direct processor relationships.
- Wholesale:Traditional industrial ingredient distributors with established CFIA compliance documentation dominate preservative volume flows to Ontario and Alberta processing facilities.
- Online Sales:Emerging B2B procurement platforms are disintermediating traditional distributor relationships for mid-size Ontario bakeries seeking direct supplier access.
- Supermarkets:Retail banner consolidation around clean-label specifications is compressing supplier qualification cycles for Ontario and Quebec food manufacturers.
- Specialty Stores:Niche natural ingredient suppliers serve artisan and small-batch processors with fermentation-derived preservation alternatives.
Wholesale anchors the volume base while online sales is expanding most quickly through digital procurement platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail buyer consolidation around clean-label specifications concentrates procurement influence within Ontario and Quebec processing corridors. Alberta meat processors and British Columbia beverage manufacturers follow distinct reformulation timelines driven by regional regulatory enforcement patterns. Metropolitan Toronto and Vancouver distribution networks anchor demand density for compliant preservative suppliers.
Ontario
Industrial bakery and dairy processing in the Greater Toronto Area drives the largest absolute preservative consumption volumes in Canada. Health Canada's Food and Drug Regulations govern maximum residue limits for synthetic preservatives across acidified beverage and baked goods categories. The province's processing corridor exhibits the most acute concentration of clean-label reformulation investment as retail banners demand uniform natural-preservation standards.
Quebec
Fermentation-derived preservation capacity clusters within limited biotech processing facilities serving cured meat and dairy applications. The Canadian Food Inspection Agency's preventive control plan enforcement compels processors to consolidate supplier relationships toward compliance-vetted distributors. Montreal's food manufacturing base is piloting encapsulation technologies for essential oil-based antimicrobials in extended shelf-life yogurt formats.
Alberta
Underpenetrated cured meat reformulation demand offers expansion potential for natural nitrate alternatives from celery powder and fermented vegetable sources. CFIA preventive control documentation requirements create administrative overhead for meat processors balancing dual certification burdens. Calgary and Edmonton processing facilities are redirecting formulation investments toward plant-derived antimicrobials as Health Canada approval pathways streamline.
British Columbia
Acidified beverage manufacturers are accelerating clean-label transitions ahead of anticipated enforcement phases for tightened synthetic preservative thresholds. Health Canada's evolving approval frameworks for natural preservation technologies are shortening market access timelines for fermentation-derived benzoate alternatives. Vancouver's beverage production cluster exhibits the most advanced clean-label adoption curve among Canadian provinces.
Canada Food Preservatives Market Competitive Environment
Player mix skews toward multinational ingredient technology specialists with integrated North American supply chain control. The vendor base concentrates around fermentation-derived solution providers and plant-derived antimicrobial suppliers with established Health Canada compliance documentation. Three strategic archetypes dominate: integrated supply chain controllers, fermentation technology specialists, and natural extract portfolio builders. Competitive moves center on strategic partnerships with Ontario and Quebec processors and portfolio diversification into clean-label alternatives.
Among North American integrated supply chain controllers, Cargill Incorporated anchors positions through captive sourcing of plant-derived antimicrobial inputs. Kerry Group plc and Corbion NV exemplify the fermentation technology specialist archetype, with the former leveraging its North American ingredient technology base and the latter anchoring fermentation-derived solutions within clean-label reformulation waves. These three companies occupy the tier most exposed to Health Canada approval acceleration for natural preservation technologies.
| Leading Market Players |
|---|
| Celanese Corporation |
| Corbion NV |
| Kerry Group plc |
| Brenntag AG |
| DuPont de Nemours Inc. |
| Koninklijke DSM N.V. |
| Cargill Incorporated |
| Kemin Industries Inc. |
| ADM |
| Others |
Value Chain & Pricing Dynamics
Health Canada's Food and Drug Regulations gate both supplier qualification and price differentiation simultaneously, as compliance documentation requirements separate vetted distributors commanding premium positioning from uncertified competitors facing qualification barriers.
Pricing Analysis
Synthetic-to-natural pricing gaps stratify procurement tiers across Ontario and Quebec processing corridors, with fermentation-derived alternatives commanding 15-40% premiums over conventional sorbates and benzoates. Price differentiation hinges on CFIA preventive control certification status and Health Canada additive approval tier, with certified suppliers extracting margin premiums from risk-averse manufacturers. Cost compression in mid-market synthetic preservatives is intensifying because clean-label mandates are accelerating volume shifts toward natural alternatives. Mid-size Ontario bakeries exhibit highest price sensitivity due to thin reformulation budgets, while national retail banners demonstrate lowest sensitivity given uniform specification mandates.
Supply Chain Analysis
China and India anchor global supply for rosemary extract, green tea polyphenols, and fermentation-derived antimicrobial inputs serving Canadian formulation houses. Domestic production draws from captive cultivation partnerships in Alberta and Saskatchewan for celery powder nitrate alternatives, while specialty fermentation capacity rests on Quebec biotech facilities. Single-source vulnerability concentrates in plant-derived extract streams subject to agricultural yield volatility and climate disruption. Distribution runs through CFIA-vetted wholesale distributors with embedded compliance documentation, though B2B digital platforms are fragmenting traditional channel control for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense as plant-derived antimicrobials displace synthetic preservatives across retail-facing product lines, requiring portfolio repositioning before qualification windows close.
For Market Incumbents: Shield market position through backward integration into fermentation-derived capacity in Quebec biotech corridors and accelerated Health Canada pre-submission for novel natural additives. Kerry Group plc and Corbion NV demonstrate how captive fermentation technology creates defensive moats against clean-label substitution. Certification investment in dual CFIA-Health Canada compliance documentation preserves distributor tier access. For New Entrants and Emerging Players: Lead with direct-to-processor digital platforms targeting mid-size Ontario bakeries underserved by traditional distributor relationships. Alberta cured meat processors represent the most penetrable segment given underdeveloped natural nitrate alternative supply. Fermentation-based ingredient partnerships with Montreal-area dairy pilot programs offer reference account pathways. For Investors and Strategic Acquirers: Health Canada's pending additive list revisions reshape the acquisition landscape toward early-stage natural preservation technology holders with established regulatory submission pathways. Five-to-ten-year viability favors fermentation-platform specialists over extract-dependent portfolios given input volatility exposure. The signal to watch is accelerated approval velocity for plant-derived antimicrobials in acidified beverage categories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Quebec biotech facilities reduce extract input volatility for clean-label portfolios. |
| CFIA Preventive Control Certification Investment | Compliance documentation unlocks wholesale distributor tier access for Ontario processors. |
| Health Canada Pre-Submission Partnership | Early regulatory engagement shortens market access timelines for novel antimicrobials. |
| Direct-to-Processor Digital Platform Launch | B2B procurement channels disintermediate traditional distributors for mid-size bakeries. |
| Alberta Meat Processing Corridor Expansion | Natural nitrate alternatives capture underpenetrated cured meat reformulation demand. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with food manufacturing procurement directors, CFIA compliance officers, fermentation technology R&D leads, and retail banner category managers. Secondary validation drew from Health Canada Food and Drug Regulations filings, CFIA preventive control plan enforcement records, Canadian Food Inspection Agency inspection data, and provincial agricultural statistics. Bottom-up volume triangulation across Ontario and Quebec processing facilities converged with top-down value estimates from ingredient distributor revenue proxies.
Across the analysis window, forecasts model product type substitution dynamics, application reformulation timelines, end-user procurement consolidation patterns, and distribution channel digitization velocity. CAGRs derive from segmented volume build-ups calibrated against historical approval velocity for natural preservation technologies. Industry-specific inputs include Health Canada additive approval pipeline status and CFIA enforcement phase implementation schedules.
The analysis sits within stated boundaries; outcomes outside Health Canada regulatory acceleration or sustained clean-label retail mandate enforcement would require recalibration. Forecasts reflect assumptions regarding fermentation capacity expansion timelines and plant extract agricultural yield stability. Recalibration cycles align with material shifts in Health Canada permitted additive list revisions and CFIA preventive control enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Europe Leavening Agents Market
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
Russia Food Preservatives Market
Food Additives and Ingredients
Ammonium Chloride Food Grade Market
Food Additives and Ingredients
Global Organic Feed Additives Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
Beverage Stabilizer Market
Food Additives and Ingredients
Carmine Alternatives Market
Food Additives and Ingredients
Global Food Release Agents Market
Food Additives and Ingredients
Glandular Ingredients Market
Food Additives and Ingredients
Europe Food Coating Ingredients Market
Food Additives and Ingredients
Asia- Pacific Food Micronized Salt Market
Food Additives and Ingredients
Octadecanedioic Acid (ODDA) Market
Food Additives and Ingredients
North America Food Acidulants Market
Food Additives and Ingredients
Argentina Food Acidulants Market
Food Additives and Ingredients
France Anti Caking Market