
 United States Nuts Market | 2026-2036
United States Nuts Market Size, Share, and Industry Trends Forecast 2026-2036
United States Nuts Market Analytics
USDA Organic certification is redrawing competitive boundaries in the United States nuts market, raising compliance costs that favor scaled operators. Blue Diamond Growers leverages its cooperative structure and integrated processing infrastructure across California's growing regions. The Wonderful Company dominates pistachio and almond verticals through captive orchards and brand-controlled distribution. John B. Sanfilippo & Son anchors the private-label and ingredient supply channels with midwestern processing capacity.
United States nuts comprise shelled and unshelled tree nuts and peanuts, typically characterized by protein content exceeding 15 percent, lipid fractions between 45 and 75 percent, and moisture levels below 7 percent for shelf-stable commercial distribution; processors employ dry-roasting, oil-roasting, or pasteurization to achieve pathogen reduction while preserving sensory attributes for snack, ingredient, and bakery applications. Almonds command the largest product type position due to planted acreage expansion and milk-alternative ingredient demand, while cashews represent the fastest-growing import-dependent category. Retail packs generate the highest margin pool within packaging type segments, though bulk formats sustain volume throughput into food manufacturing channels.
FDA enforcement of the Food Safety Modernization Act preventive controls rule, USDA National Organic Program standards, and California's Proposition 65 labeling requirements collectively shape processing investments and product claims across the domestic supply chain. Compliance with these overlapping frameworks determines facility qualification for national retail distribution and export eligibility. Stakeholders must monitor evolving FDA guidance on aflatoxin thresholds and state-level water allocation policies that directly constrain orchard productivity in major growing regions.
Market Dynamics
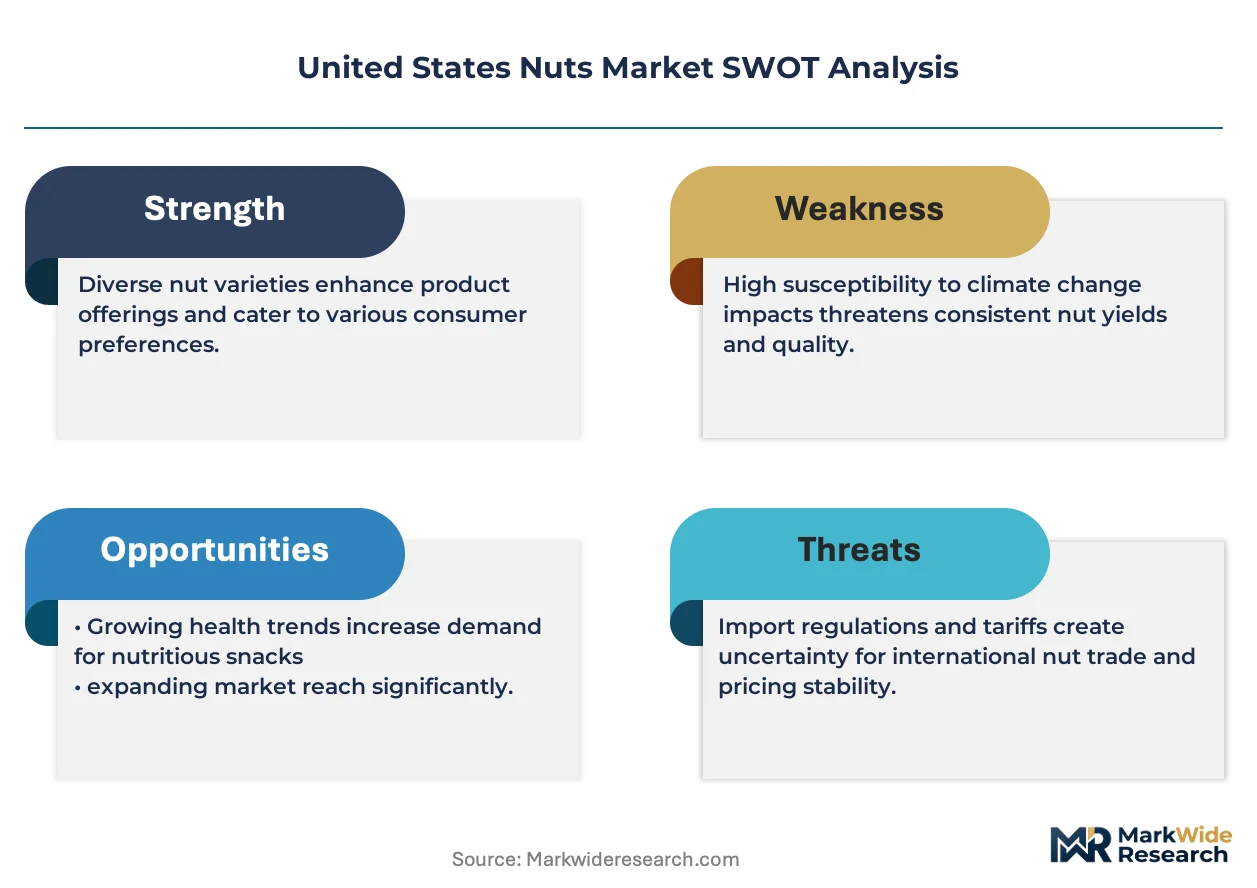
California's Proposition 65 labeling mandates and FDA Food Safety Modernization Act enforcement are compressing margins for small-scale processors while rewarding operators with captive laboratory and legal infrastructure. Water allocation disputes in the Central Valley compound regulatory pressure by constraining orchard yield predictability.
Growth Catalysts
- Plant-based ingredient demand:Almond milk formulations in beverage manufacturing pull volume through industrial channels. Food service operators expand nut-based dairy alternatives across menu categories.
- USDA Organic certification premium:Retail shelf placement advantages and price realization differentials incentivize conversion of conventional acreage. Scaled handlers amortize compliance costs across integrated processing networks.
- Snack pack format proliferation:Single-serve packaging aligns with convenience retail and food service grab-and-go channels. Portion-controlled offerings penetrate workplace and travel consumption occasions.
Market Restraints
- Input cost volatility:Water pricing in California's agricultural districts fluctuates with drought declaration cycles. Energy costs for cold storage and roasting operations track regional grid stress.
- Supply concentration risk:Almond and walnut production clusters in California's Central Valley expose the domestic supply base to climate shock correlation. Limited alternative sourcing geography within tariff-advantaged trade zones.
- Regulatory friction:FDA aflatoxin testing protocols create lot rejection risk and inventory holding costs. Preventive controls rule implementation demands dedicated food safety personnel.
Strategic Opportunities
- Underpenetrated organic conversion:Texas and Arizona pecan orchards present USDA Organic certification expansion potential. Irrigation infrastructure in these states supports yield stability under conversion timelines.
- Emerging bakery ingredient applications:Almond flour and nut butter inclusions displace conventional wheat and shortening formulations. Clean-label positioning drives reformulation mandates from retail bakery chains.
- Direct-to-consumer channel development:Subscription nut boxes and specialty roaster e-commerce bypass conventional retail slotting fee structures. Regional brand building through controlled customer acquisition.
Industry Challenges
- Specialized food safety talent scarcity:Preventive controls qualified individual certification requirements outpace training program throughput. Competition for experienced personnel intensifies among mid-sized handlers.
- Capex intensity for pathogen reduction:Pasteurization equipment and laboratory validation infrastructure demand seven-figure facility investments. Smaller cooperatives face financing constraints for FSMA compliance.
- Legacy system integration complexity:Lot traceability software implementation conflicts with decades-old inventory management platforms. Data migration risks disrupt harvest-season operational continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Nuts Market |
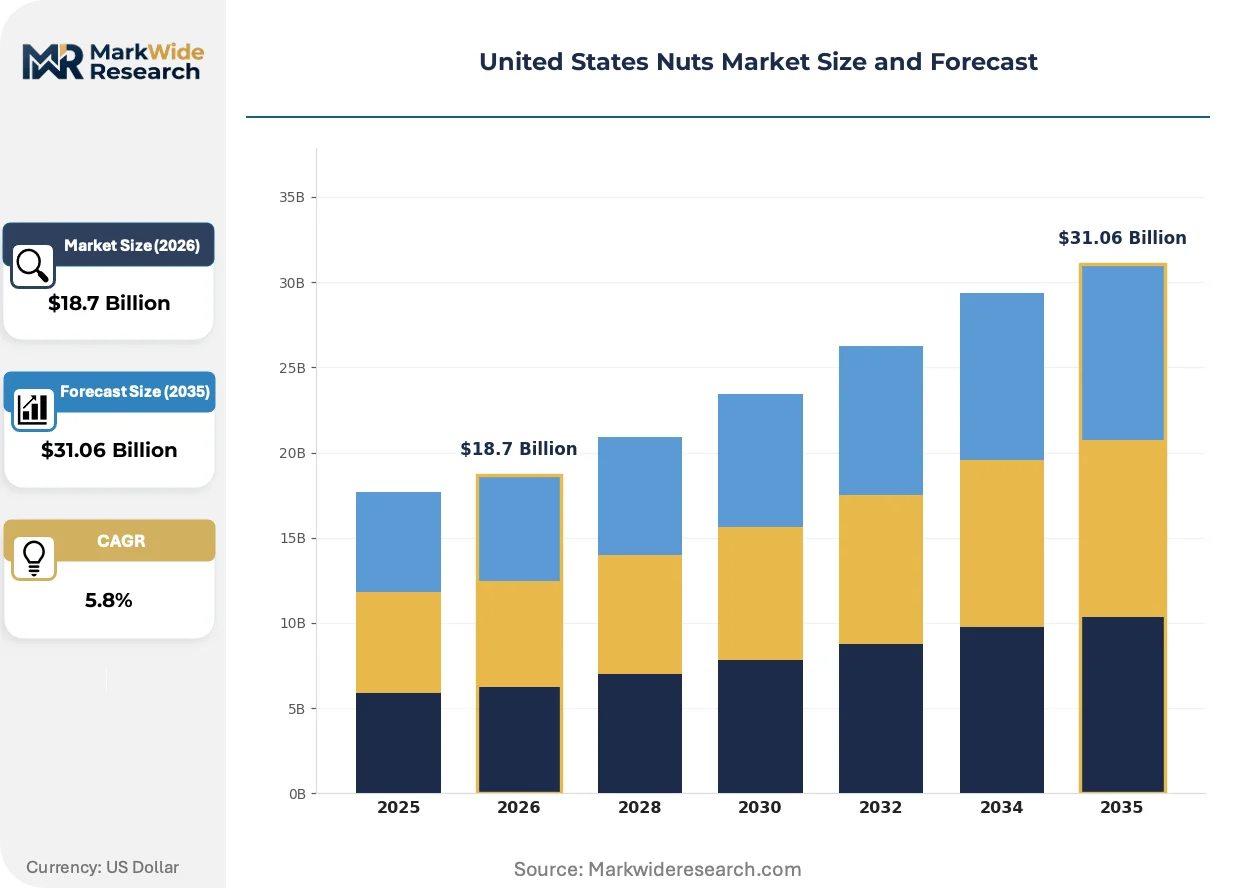
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almonds, Walnuts, Pecans, Cashews Packaging Type: Bulk, Retail Packs, Value Packs, Snack Packs End User: Retail Consumers, Food Manufacturers, Foodservice Operators, Exporters Form: Raw, Roasted, Flavored, Unsalted |
| Companies Covered | Blue Diamond Growers, Hormel Foods Corporation, The Wonderful Company LLC, John B. Sanfilippo & Son, Inc., Mariani Nut Company, Waterford Nut Company, Tierra Farm, Inc., Farm Breeze International LLC, Krema Nut Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Nuts Market Evolving Landscape
Processing technology and consumer-facing format innovation are redrawing value capture boundaries across the domestic nut supply chain. Sustainability verification and convenience-oriented packaging reshape competitive positioning.
High-pressure pasteurization technology is fragmenting the traditional thermal treatment equipment market by enabling pathogen reduction without the flavor degradation associated with conventional roasting. Premium snack brands and organic-certified handlers adopt HPP for raw product positioning. Equipment financing models and toll processing services lower capital barriers for mid-scale operators.
FDA enforcement discretion on aflatoxin thresholds is tightening lot release protocols and expanding laboratory testing expenditure across domestic receiving stations. Almond and pistachio handlers in California face elevated rejection risk for export-bound shipments. Third-party certification to enhanced testing standards is emerging as a commercial prerequisite for Asian market access.
Buyers in the ingredient channel are consolidating procurement relationships and demanding multi-year volume commitments with price collars. Food manufacturing accounts reduce supplier counts from regional fragmentation toward two-to-three preferred handler structures. This concentration is most visible in the Midwest bakery and confectionery corridor, where procurement teams prioritize supply security over spot-market price optimization.
United States Nuts Market Segmentation
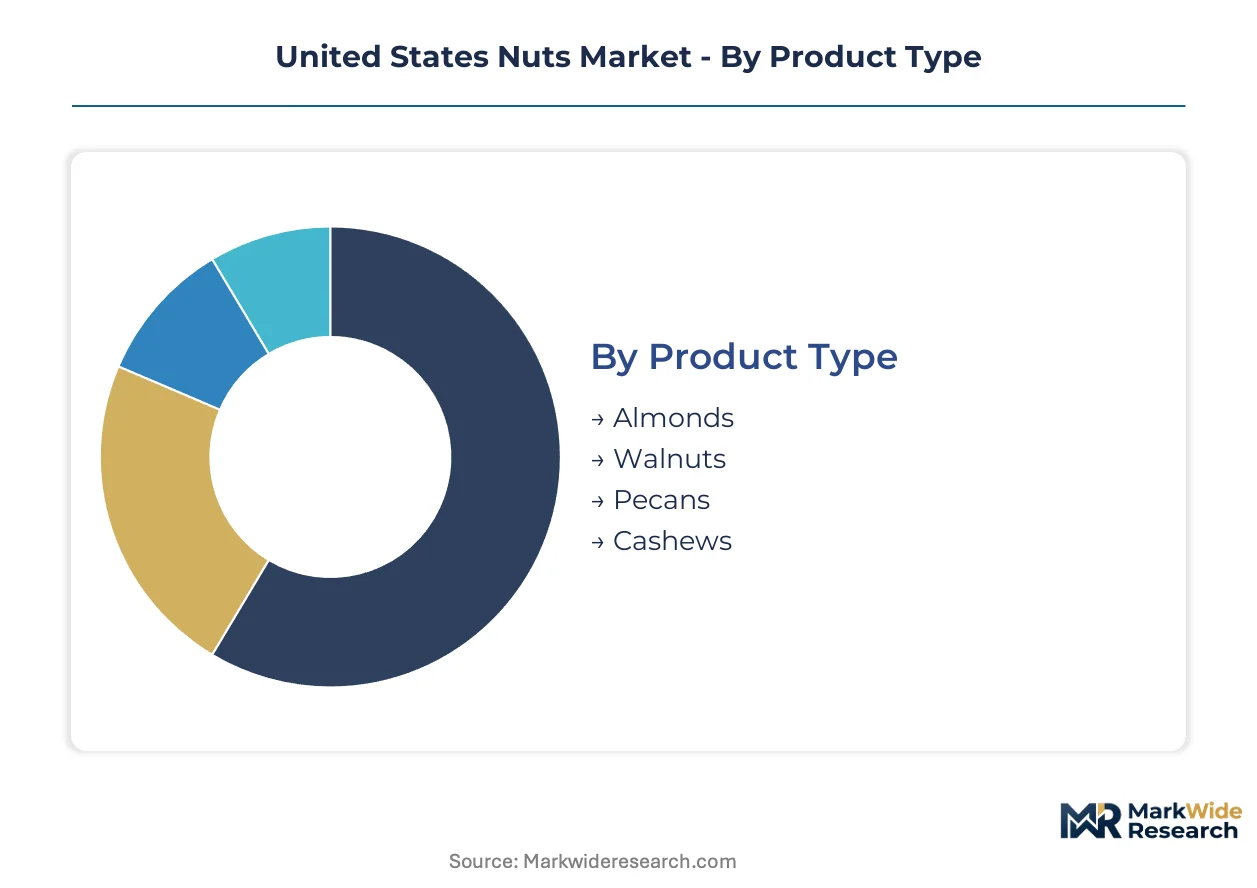
Nut processors configure operations around four intersecting dimensions that determine equipment investment, margin structure, and regulatory exposure. Each segmentation axis carries distinct geographic and channel implications for handlers competing across California's Central Valley and beyond.
Product Type:
Domestic production clusters heavily in California's Central Valley, while import dependency shapes competitive dynamics for segments without viable U.S. growing regions.
- Almonds:Planted acreage across Fresno, Kern, and Merced counties supplies both domestic milk-alternative ingredient demand and export shipments to Asian markets. Water allocation volatility and FDA aflatoxin testing protocols create lot rejection risk for handlers.
- Walnuts:Chandler and Hartley varieties dominate Central Valley orchards, with shelling operations concentrated in Stockton-Modesto corridor. Bakery ingredient and private-label snack channels absorb the majority of processed volume.
- Pecans:Texas and Georgia orchards provide domestic sourcing, though Mexico imports compete on price in confectionery applications.
- Cashews:Import-dependent category sourced primarily from Vietnam and India, with roasting and flavoring operations sited near coastal port infrastructure.
Almonds command the established base. The steepest expansion runs through cashews as foodservice operators broaden menu applications.
Packaging Type:
Margin structures diverge sharply between commodity bulk formats and branded retail configurations, with capital requirements scaling accordingly.
- Bulk:Industrial totes and foodservice bins sustain volume throughput into bakery and confectionery manufacturing channels across the Midwest corridor.
- Retail Packs:Stand-up pouches and canisters generate the highest margin pool, with slotting fees and trade promotion budgets determining shelf placement at national grocery chains.
- Value Packs:Multi-serve bags target warehouse club and suburban household pantry stocking occasions.
- Snack Packs:Single-serve portions align with convenience retail, workplace distribution, and travel consumption channels. Portion-controlled formats command per-ounce premiums that offset higher packaging costs.
Bulk formats anchor volume throughput. Snack packs deliver the fastest margin expansion trajectory.
End User:
Channel concentration creates divergent procurement patterns, with food manufacturers consolidating supplier relationships while retail fragments across format tiers.
- Retail Consumers:Supermarket, mass merchant, and e-commerce channels demand year-round supply security with promotional pricing flexibility.
- Food Manufacturers:Ingredient buyers in bakery and dairy-alternative segments consolidate toward two-to-three preferred handler structures with multi-year volume commitments.
- Foodservice Operators:Restaurant chains and institutional feeders prioritize portion-controlled formats and consistent roast specifications for menu standardization.
- Exporters:Asian market access demands third-party certification to enhanced aflatoxin testing standards beyond FDA baseline requirements.
Food manufacturers concentrate procurement leverage. Exporters are climbing the fastest as handlers invest in laboratory validation infrastructure.
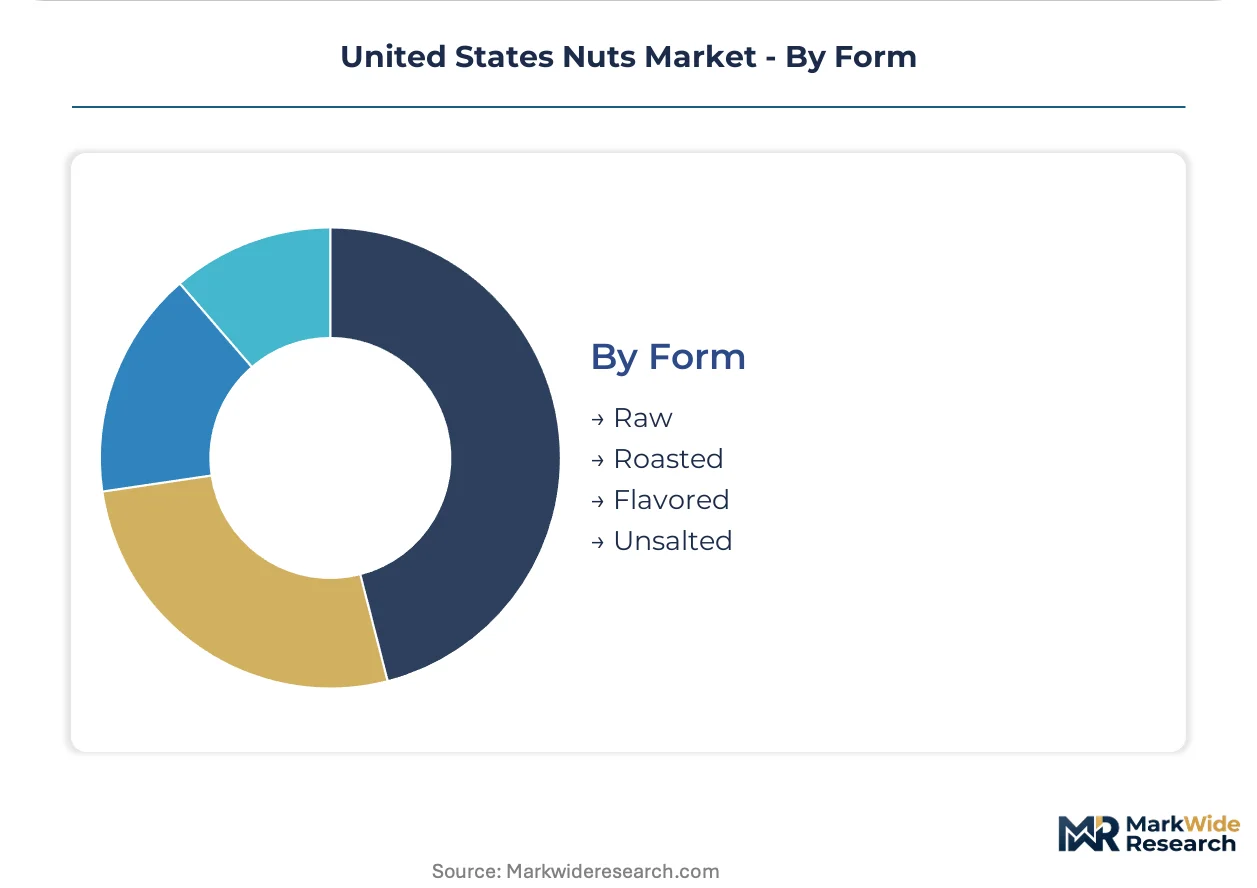
Form:
Processing intensity determines pathogen reduction protocols and capital equipment requirements across the form spectrum.
- Raw:High-pressure pasteurization technology enables pathogen reduction without thermal degradation, supporting premium positioning in organic and natural channels.
- Roasted:Dry-roasting and oil-roasting operations dominate conventional snack applications, with energy costs tracking regional grid stress in California processing facilities.
- Flavored:Seasoning and coating lines require dedicated allergen control protocols and clean-in-place infrastructure to prevent cross-contamination.
- Unsalted:Health-positioned SKUs target dietary-restricted consumers and clean-label reformulation mandates from retail bakery chains.
Roasted forms hold the volume base. Raw forms gain share fastest as HPP equipment financing lowers capital barriers for mid-scale operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal water policy and USDA conservation incentives are redirecting orchard investment toward states with reliable irrigation infrastructure. State-level organic certification programs create competitive advantages for handlers in emerging growing regions.
California
Almond and walnut production concentrates in Fresno, Kern, and Merced counties where planted acreage supplies domestic milk-alternative ingredient demand. FDA Food Safety Modernization Act enforcement and Proposition 65 labeling mandates compress margins for processors lacking captive laboratory infrastructure. The Stockton-Modesto corridor anchors shelling operations for Chandler and Hartley walnut varieties.
Texas
Pecan orchards in the Red River Valley and Central Texas regions present USDA Organic certification expansion potential with established irrigation infrastructure. State agricultural extension programs support grower conversion timelines with technical assistance grants. San Antonio and Dallas-Fort Worth processing clusters handle volume for confectionery and bakery ingredient channels.
Georgia
Pecan production in the Albany and Valdosta districts competes with Mexico imports on price in shelling and roasting applications. Georgia Department of Agriculture grading standards influence procurement specifications for national snack brands. Savannah port infrastructure supports import-export arbitrage for cashew roasting operations.
Arizona
Pecan orchards in the Cochise and Yuma counties leverage Colorado River water allocation stability under state agricultural priority structures. Arizona Department of Environmental Quality oversight of processing wastewater discharge shapes facility siting decisions. Phoenix-area roasting operations serve southwestern foodservice distribution networks.
Oregon
Hazelnut production in the Willamette Valley responds to confectionery demand from Pacific Northwest chocolate manufacturers. Oregon Department of Agriculture organic certification streamlines handler qualification for national retail distribution. Portland-area processing facilities specialize in raw and dry-roasted formats for natural channel placement.
United States Nuts Market Competitive Landscape
Player mix skews toward agricultural cooperatives and family-held processors with multi-generational orchard relationships. Market structure shows moderate consolidation at the handler level with fragmentation among regional roasting operations. Three archetypes dominate: cooperative-integrated processors with captive growing bases, private-label specialists with midwestern distribution reach, and organic-certified toll processors serving emerging brand channels. Competitive moves center on backward integration into orchard assets and multi-year supply contracts with food manufacturing accounts.
Within the cooperative-integrated tier, Blue Diamond Growers and The Wonderful Company exemplify handlers with captive Central Valley acreage and brand-controlled distribution infrastructure. John B. Sanfilippo & Son occupies a position bridging private-label supply and ingredient channel concentration in the Midwest bakery corridor. These three entities represent distinct scale advantages: cooperative membership networks, vertical orchard ownership, and midwestern processing logistics respectively.
| Leading Market Players |
|---|
| Blue Diamond Growers |
| Hormel Foods Corporation |
| The Wonderful Company LLC |
| John B. Sanfilippo & Son, Inc. |
| Mariani Nut Company |
| Waterford Nut Company |
| Tierra Farm, Inc. |
| Farm Breeze International LLC |
| Krema Nut Company |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day inventory cycles at California receiving stations compress margin buffers for handlers lacking captive cold storage, amplifying pricing power for integrated operators with backward control over Central Valley orchards and in-house pasteurization capacity.
Pricing Analysis
Certification level creates the primary spread across the United States nuts market, with USDA Organic and FDA FSMA-compliant handlers commanding shelf placement premiums over conventional commodity suppliers. Three-tier pricing structure separates organic-certified specialty packs from standard retail configurations and bulk ingredient totes. Cost compression in conventional almond segments is intensifying because water allocation volatility in Fresno and Kern counties elevates per-pound growing costs. Private-label food manufacturers exhibit the highest price sensitivity, while premium snack brands and direct-to-consumer channels absorb organic premiums with minimal volume elasticity.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and Oakland elevates inbound logistics costs for cashew shipments from Vietnam and India, forcing roasting operations to pre-position inventory ahead of peak processing seasons. Domestic almond and walnut production draws from California's Central Valley, with pecan sourcing splitting between Texas, Georgia, and Mexico. Single-source vulnerability concentrates in California water districts, where drought declarations trigger allocation cuts that cascade through shelling and processing schedules. Distribution runs through regional cold storage hubs in Stockton-Modesto and San Antonio, with final-mile delivery consolidated through foodservice redistribution centers and national grocery chain distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription nut box services and specialty roaster e-commerce platforms are expanding recurring revenue streams faster than conventional retail pack sales, positioning service-attach models as the priority growth vector for capital allocation.
For Market Incumbents: Consolidate procurement relationships with food manufacturing accounts through multi-year volume commitments that lock in base throughput, while expanding captive laboratory infrastructure to preempt FDA aflatoxin enforcement actions. Capacity addition in Texas pecan corridors hedges California water risk. Certification investment in USDA Organic and enhanced third-party testing protocols defends shelf position against emerging toll processors. For New Entrants and Emerging Players: Lead with direct-to-consumer subscription formats targeting workplace and travel consumption occasions, where established brands underinvest in portion-controlled innovation. Texas and Arizona organic pecan conversion presents the most penetrable white space, with state extension programs de-risking grower transition timelines. Specialty roasting equipment financing partnerships lower capital barriers for mid-scale market entry. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cooperative-integrated handlers with captive acreage and brand-controlled distribution command irreplaceable supply security premiums in an increasingly regulated environment. Target acquisition archetypes include midwestern private-label specialists with FDA-compliant facilities and regional organic-certified toll processors serving emerging brand channels. The signal to watch is FDA enforcement discretion tightening on aflatoxin thresholds, which would accelerate compliance-driven M&A among sub-scale operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Assets | Captive Central Valley acreage insulates handlers from water allocation volatility and FDA lot rejection risk. |
| USDA Organic Certification Expansion | Texas and Arizona pecan conversion unlocks premium shelf placement and price realization differentials at national retail chains. |
| High-Pressure Pasteurization Equipment Deployment | HPP technology enables raw product positioning in organic channels without thermal flavor degradation. |
| Direct-to-Consumer Channel Development | Subscription nut boxes bypass conventional retail slotting fees and build controlled customer acquisition economics. |
| Multi-Year Supply Contract Consolidation | Food manufacturers are reducing supplier counts toward preferred handler structures with volume commitment security. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with cooperative processing executives, FDA compliance officers at handler facilities, national grocery chain category buyers, and food manufacturing procurement directors; and secondary validation through USDA National Agricultural Statistics Service crop reports, FDA FSMA guidance documents, California Department of Water Resources allocation records, and customs import data for cashew shipments. Bottom-up volume modeling across product type, packaging format, and end-user segments was triangulated against top-down expenditure estimates from food manufacturing input cost disclosures.
Across the analysis window, the forecasting framework modeled price-volume interactions by nut type, organic certification status, and channel concentration patterns. CAGRs were derived from historical planted acreage trends, milk-alternative ingredient demand trajectories, and snack pack format penetration rates. Industry-specific inputs included California water district allocation forecasts, FDA enforcement discretion patterns on aflatoxin thresholds, and foodservice operator menu expansion data for nut-based dairy alternatives.
Forecasts assume regulatory continuity in FDA FSMA preventive controls enforcement and USDA National Organic Program standards; material policy shifts in aflatoxin thresholds or water allocation priorities would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Nut Based Spread Market
Nuts and Seeds
United States Cashew Market
Nuts and Seeds
North America Moringa Products Market
Nuts and Seeds
Almond Oil Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
Tiger Nuts Market
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Walnut-Based Spreads Market
Nuts and Seeds
Europe Nut-Based Spreads Market
Nuts and Seeds
Dry Roasted Almonds Snack Market
Nuts and Seeds
Almond Kernels Market
Nuts and Seeds
Asia-Pacific Grape Seed Extract Market
Nuts and Seeds
Passionfruit Seed Oil Market
Nuts and Seeds
Asia-Pacific Cashew Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Germany Cashew Market