
 United States Foodservice Market | 2026-2036
United States Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
United States Foodservice Market Analytics
Healthcare and institutional dining is broadening its share of the United States foodservice channel as hospitals, senior living operators, and corporate campuses outsource meal programs. Sysco Corporation dominates institutional contract logistics through its broadline distribution network and specialized healthcare division. US Foods Holding Corp. differentiates via its Scoop portfolio and chef-led innovation kitchen that develops menu solutions for restricted-diet environments. Performance Food Group Company leverages its Vistar convenience and theater division to sustain diversified revenue streams beyond traditional restaurant service.
Foodservice encompasses the commercial preparation, assembly, and delivery of meals outside the home, operating through facilities that range from full-service restaurants with on-premise culinary staff to centralized commissaries producing at volumes exceeding 10,000 meals daily for institutional clients. Quick service restaurants anchor the service type segment with standardized production protocols and drive-thru infrastructure that compresses order-to-delivery cycles below three minutes. Full-service dining occupies mature margin pools where wine and beverage attach rates determine profitability, while food trucks represent the fastest-growing service type due to lower capital barriers and municipal permit streamlining in Sun Belt metros.
The FDA Food Code governs state-level food safety standards, with the 2022 edition introducing enhanced allergen controls and time-temperature logging that distributors must support through traceability systems. USDA National School Lunch Program specifications and OSHA workplace safety mandates for commercial kitchens collectively shape equipment purchasing and labor scheduling decisions. Stakeholders must monitor how municipal composting ordinances and single-use packaging bans in California, New York, and Washington cascade into national supplier specifications.
Market Dynamics
Healthcare and senior living operators are consolidating meal program contracts under broadline distributors, compressing procurement cycles and forcing distributors to integrate clinical nutrition expertise into standard logistics operations. This institutional buyer concentration is reshaping vendor qualification criteria and margin structures across the channel.
Growth Catalysts
- State-level sodium reduction mandates:California and New York procurement specifications now require reduced-sodium menu options, creating pull-through demand for reformulated products and specialized distribution capabilities.
- Senior living facility expansion:Demographic migration to Sun Belt metros is driving construction of assisted living and memory care units with outsourced foodservice contracts.
- Commissary automation:Centralized production facilities serving hospitals and corporate campuses are adopting robotic portioning and cook-chill systems to achieve 10,000-plus meal daily volumes.
Market Restraints
- Protein input cost volatility:Beef and poultry commodity swings compress contract catering margins where price-lock agreements predominate.
- Broadline distributor concentration:Three national networks control institutional cold-chain logistics, creating single-source vulnerability for rural healthcare facilities.
- Commercial kitchen labor shortages:OSHA-mandated safety training requirements extend onboarding timelines for line cooks and prep staff.
Strategic Opportunities
- Texas and Florida sub-markets:Population migration and tourism infrastructure investment are outpacing contracted foodservice capacity in Dallas-Fort Worth and Orlando corridors.
- FDA Food Code traceability upgrades:The 2022 edition's enhanced allergen controls create demand for distributor-provided time-temperature logging systems.
- Food truck municipal permit streamlining:Sun Belt metros are reducing capital barriers for mobile foodservice operations in downtown and event venue clusters.
Industry Challenges
- Clinical nutrition certification timelines:Registered dietitian nutritionist staffing requirements delay healthcare contract launches.
- Composting ordinance compliance:California and Washington municipal organic waste mandates force kitchen-level operational reconfiguration.
- Legacy POS integration:Quick service drive-thru timing systems require costly retrofitting to connect with third-party delivery aggregators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Foodservice Market |
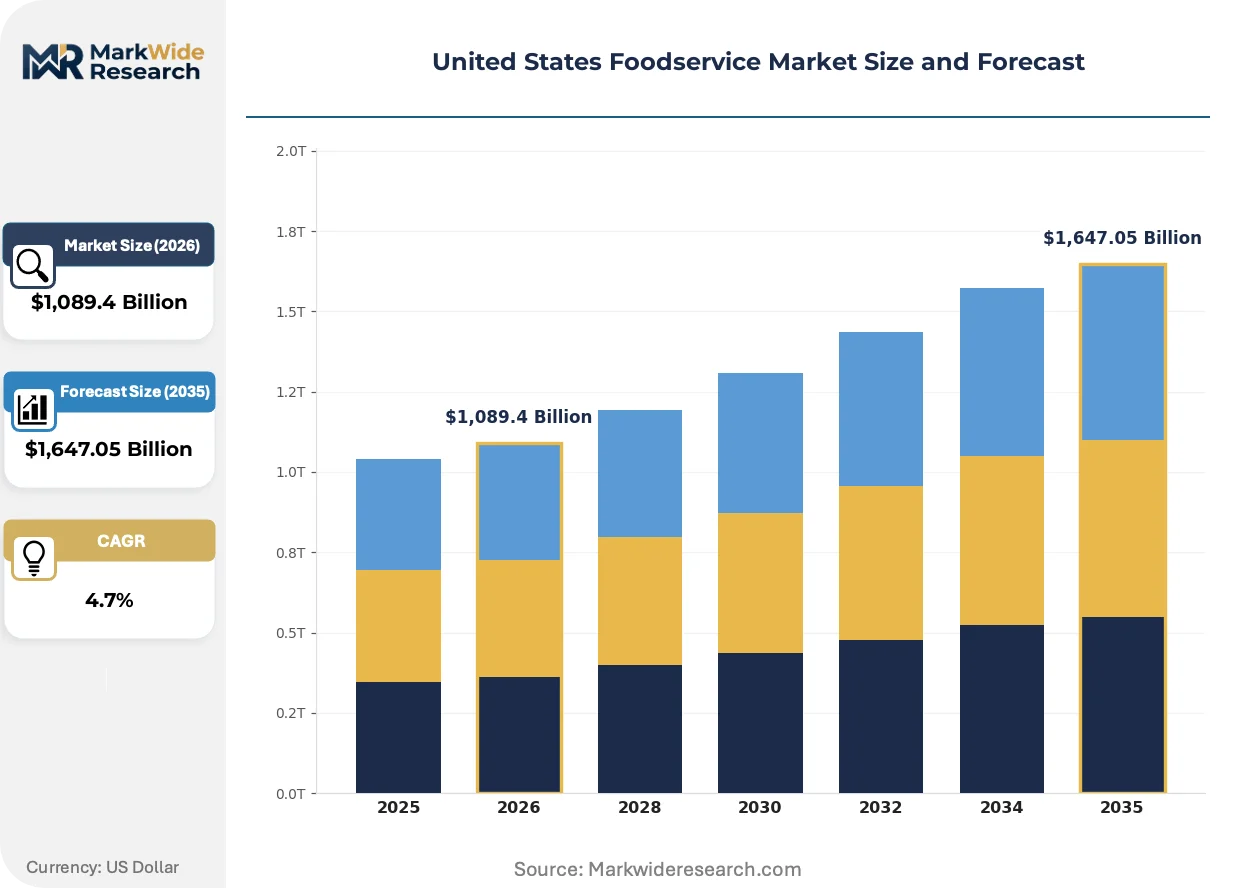
| Market Size in 2026 | $1,089.4 Billion |
| Market Size in 2035 | $1,647.05 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
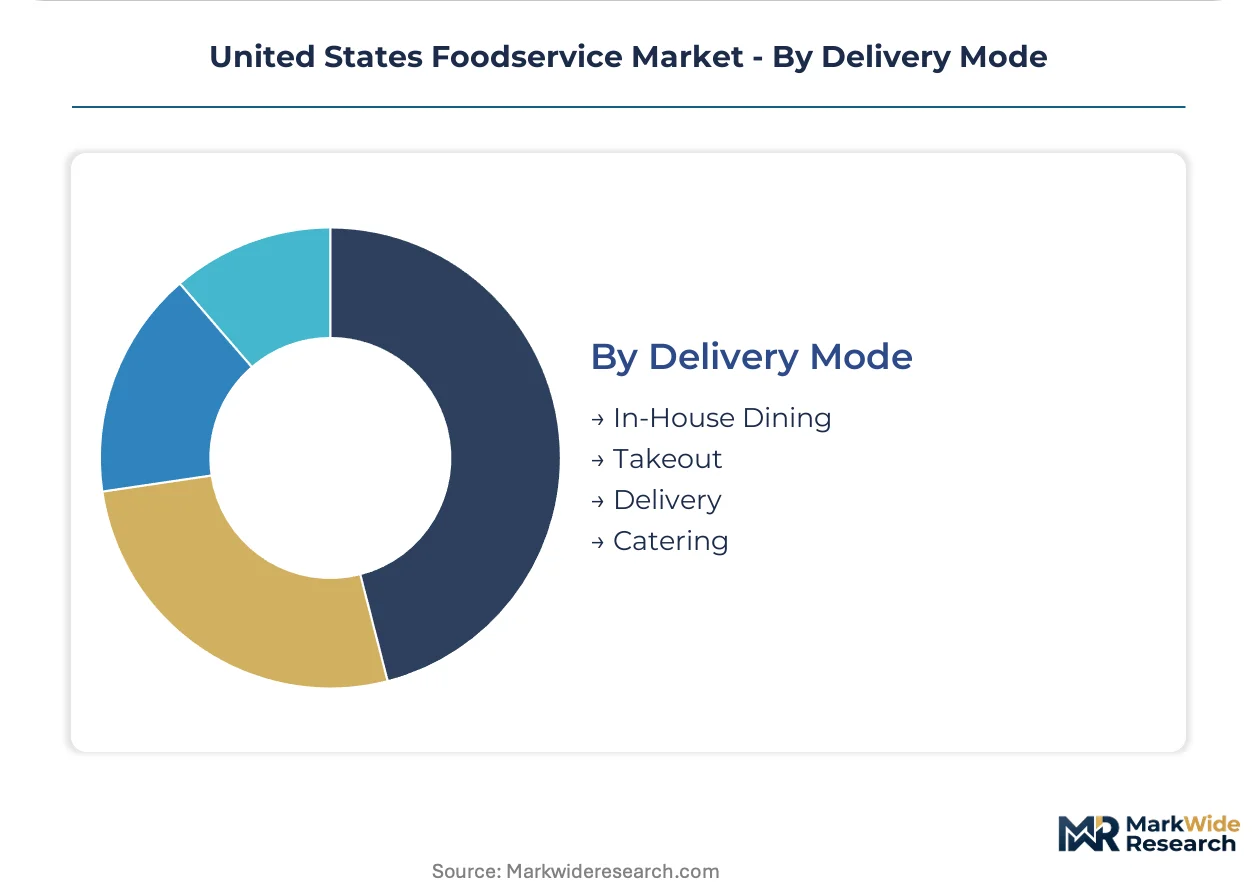
| Segmentation | Service Type: Full-Service, Quick Service, Cafeteria, Food Trucks Cuisine Type: Italian, Mexican, Asian, American Customer Type: Families, Students, Business Professionals, Tourists Delivery Mode: In-House Dining, Takeout, Delivery, Catering |
| Companies Covered | The Chefs' Warehouse, Inc., The Andersons, Inc., Sysco Corporation, HF Foods Group Inc., SpartanNash Company, US Foods Holding Corp., United Natural Foods, Inc., AMCON Distributing Company, Performance Food Group Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Foodservice Market Evolving Landscape
Automation and data-capture technologies are penetrating foodservice operations from back-of-house production to front-of-house ordering interfaces. These shifts are compressing labor dependency while raising capital requirements for equipment refresh cycles.
Cook-chill and blast-chilling systems are absorbing labor costs in high-volume institutional commissaries. Hospital and senior living operators with 5,000-plus daily meal obligations are deploying these technologies to extend production windows and reduce on-premise culinary headcount. The equipment is absorbing tasks previously requiring round-the-clock kitchen staffing.
FDA Food Code 2022 updates are mandating enhanced allergen controls and digital traceability documentation. State health departments are adopting these standards for restaurant and institutional inspections, forcing distributors to deploy temperature-logging hardware and cloud-based compliance dashboards. Quick service chains with multi-state footprints face the steepest adaptation costs.
Healthcare procurement officers are consolidating meal program contracts under single-source broadline agreements with embedded clinical nutrition consulting. This buyer-side concentration is displacing fragmented local vendor relationships in hospital and senior living channels. The pattern is most visible in California, Texas, and Florida where facility construction and merger activity are strongest.
United States Foodservice Market Segmentation
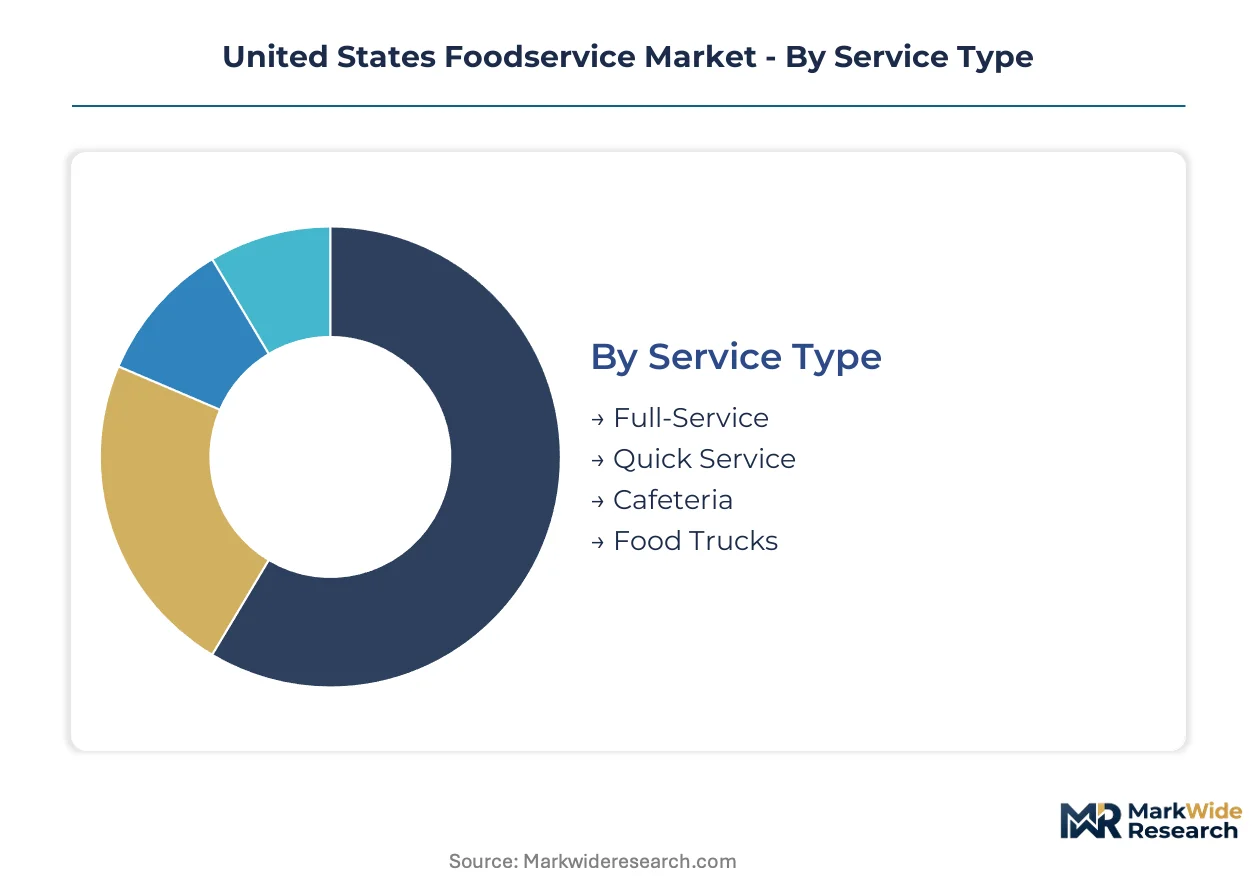
Foodservice segmentation reveals how procurement specifications, labor models, and real estate costs fragment the channel into distinct operational archetypes. Each dimension carries diverging margin structures and capital requirements that shape distributor portfolio priorities.
Service Type:
Standalone facilities operate with dedicated on-premise production infrastructure, while embedded formats integrate into host venues with shared utility and labor pools.
- Full-Service:Table-side preparation with wine and beverage attach rates driving profitability through extended dining durations. Demand concentrates in Florida and California where tourism infrastructure and affluent suburban corridors sustain premium check averages; labor intensity constrains expansion in markets with elevated minimum wage mandates.
- Quick Service:Standardized production protocols compress order-to-delivery cycles below three minutes through drive-thru infrastructure and limited menu breadth. Texas and Florida corridors absorb the fastest capacity additions as population migration outpaces existing restaurant density; real estate costs in coastal metros force format innovation with smaller footprints.
- Cafeteria:Self-service lines in institutional settings with tray-based portion control and pre-plated hot holding.
- Food Trucks:Mobile units capitalizing on municipal permit streamlining in Sun Belt metros and lower capital barriers.
Volume placements concentrate in Quick Service; the faster expansion belongs to Food Trucks.
Cuisine Type:
Menu positioning determines ingredient sourcing complexity, equipment specialization, and labor skill premiums across the operational base.
- Italian:Pasta and pizza formats dominate with centralized dough production and wood-fired or conveyor oven specialization. Family dining segments in suburban corridors sustain demand; cheese and tomato commodity exposure compresses margins during supply disruptions.
- Mexican:Assembly-line production models with protein grilling stations and salsa bars enabling high-throughput service. Texas and California anchor demand concentration; fresh produce logistics requirements favor distributor partnerships with regional cold-chain density.
- Asian:Wok-fired and sushi formats requiring specialized ventilation and rice-cooking infrastructure.
- American:Burger and sandwich formats with broad appeal and simplified supply chains.
American cuisine captures the widest geographic penetration; Asian formats are climbing the fastest in urban coastal markets.
Customer Type:
Daypart patterns and spending elasticity separate occasion-based demand from recurring institutional meal obligations.
- Families:Weekend and holiday occasion dining with high party sizes and shared-plate consumption. Suburban corridor locations in Texas and Florida sustain traffic; children's menu requirements add procurement complexity for specialized portion sizes.
- Business Professionals:Weekday lunch and after-work dining with compressed duration and beverage attach expectations. Downtown clusters in Dallas-Fort Worth and Orlando absorb concentration; corporate expense account erosion shifts volume toward fast-casual alternatives.
- Students:Campus-proximate and late-night formats with price-sensitive demand and high throughput requirements.
- Tourists:Destination and entertainment venue dining with elevated willingness-to-pay and experience-seeking behavior.
Business Professionals generate the highest per-visit revenue; Students represent the steepest expansion trajectory as campus foodservice outsourcing accelerates.
Delivery Mode:
Channel integration depth separates on-premise experience formats from logistics-dependent off-premise fulfillment systems.
- In-House Dining:Full experience control with ambiance, service timing, and beverage program integration. Full-service operators in California and Florida sustain differentiation through design investment; labor scheduling complexity rises with demand volatility.
- Takeout:Counter-based pickup with packaging optimization for food quality retention during transport. Quick service chains dominate with dedicated pickup infrastructure; parking accessibility determines competitive positioning in dense metros.
- Delivery:Third-party aggregator integration with commission structures compressing net revenue per order.
- Catering:Large-format production with advance ordering and off-premise service execution for events and institutions.
In-House Dining retains the highest margin per transaction; Delivery is gaining share fastest as aggregator infrastructure penetrates secondary metros.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States produces foodservice capacity through coastal import gateways and interior agricultural processing zones, while consumption concentrates in Sun Belt migration corridors where population growth outstrips existing restaurant density.
California
Los Angeles and San Francisco anchor the nation's largest institutional foodservice procurement market, where hospital systems and senior living operators consolidate contracts under broadline agreements. The state's municipal composting ordinances and single-use packaging bans force kitchen-level operational reconfiguration. San Diego's tourism infrastructure sustains premium full-service dining expansion along the coastal corridor.
Texas
Dallas-Fort Worth and Houston absorb the fastest quick-service capacity additions as population migration from coastal states accelerates. The Texas Department of State Health Services adopts FDA Food Code 2022 standards for enhanced allergen controls and digital traceability. Austin's corporate campus construction drives outsourced foodservice contract growth in the Central Texas corridor.
Florida
Orlando's tourism infrastructure and Miami's international visitor flows sustain destination dining demand at elevated price points. State health departments mandate time-temperature logging systems for multi-unit operators under adopted FDA guidelines. Tampa and Jacksonville senior living construction is outpacing contracted foodservice capacity in the northern Gulf Coast corridor.
New York
New York City's dense urban core supports the highest food truck permit density and third-party delivery aggregator penetration. State-level sodium reduction mandates reshape procurement specifications for healthcare and institutional accounts. The Hudson Valley and Long Island suburban corridors sustain family dining traffic with weekend occasion concentration.
Illinois
Chicago's downtown corporate expense account erosion shifts volume toward fast-casual alternatives, compressing full-service margins. The Illinois Department of Public Health enforces FDA Food Code standards for commercial kitchen safety and allergen documentation. Peoria and Rockford institutional commissaries deploy cook-chill automation for hospital and school district meal programs.
United States Foodservice Market Competitive Landscape
Top-tier vendors anchor national broadline distribution, while regional specialists and niche organic distributors occupy tier-two positions with focused geographic or product coverage. The vendor base stratifies across three functional tiers: integrated broadline networks with cold-chain density, specialty protein and produce distributors with sourcing relationships, and technology-enabled procurement platforms serving independent operators. Two dominant competitive moves are reshaping positioning: healthcare contract consolidation under single-source agreements, and vertical integration into captive production facilities for high-volume institutional accounts.
Among national-scale broadline distributors, Sysco Corporation, US Foods Holding Corp., and Performance Food Group Company exemplify the integrated logistics archetype with specialized healthcare divisions and traceability-compliant cold-chain infrastructure. These entities occupy positions where institutional buyer concentration and FDA Food Code compliance requirements create qualification barriers for smaller competitors.
| Leading Market Players |
|---|
| The Chefs' Warehouse, Inc. |
| The Andersons, Inc. |
| Sysco Corporation |
| HF Foods Group Inc. |
| SpartanNash Company |
| US Foods Holding Corp. |
| United Natural Foods, Inc. |
| AMCON Distributing Company |
| Performance Food Group Company |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up broadline distributors now control three-quarters of institutional cold-chain capacity in the United States, compressing procurement cycles while extracting volume-based rebates that reshape margin structures across hospital and senior living channels. This ownership concentration feeds upstream into captive production investments and downstream into exclusive distribution agreements that lock out regional competitors.
Pricing Analysis
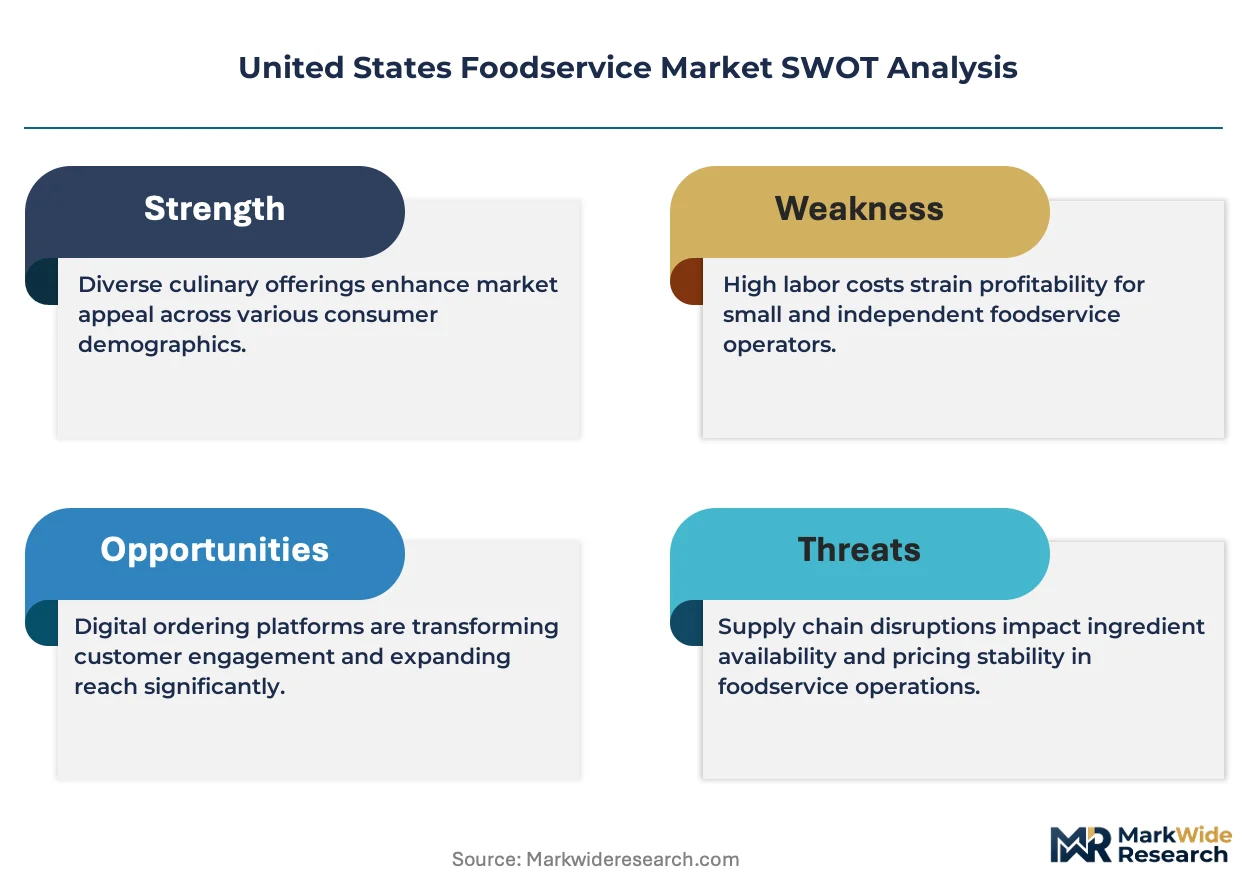
Margin tightening in contract catering reflects protein commodity swings and price-lock agreements that predominate in healthcare procurement. Three-tier pricing structure across premium, standard, and economy levels separates white-tablecloth independent operators from fast-casual chains and institutional commissaries. Cost-down pressure on broadline distributors accelerates because senior living operators consolidate single-source agreements. Quick service chains exhibit the highest price sensitivity; full-service coastal operators maintain the lowest.
Supply Chain Analysis
Freight cost absorption in cold-chain logistics centers on diesel volatility and driver wage inflation that distributors pass through as fuel surcharges. Protein supply concentrates in Midwest packing plants and Southern poultry processing zones; produce sourcing draws from California's Central Valley and Florida's winter vegetable belt. Single-source vulnerability pervades rural healthcare facilities dependent on one broadline network. Distribution runs through Sysco, US Foods, and Performance Food Group's consolidated warehouse networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States foodservice market functions as a vertical-integration race where distributors compete to capture captive production capacity and exclusive healthcare contracts. Players pursue backward integration into protein processing and commissary automation as the decisive upstream lever.
For Market Incumbents: Lock in exclusive healthcare contracts before senior living construction peaks in Texas and Florida corridors. Integrate clinical nutrition consulting capabilities to meet FDA Food Code 2022 traceability mandates. Defend against emerging technology-enabled procurement platforms by embedding proprietary compliance dashboards into hospital systems. For New Entrants and Emerging Players: The price-point gap between premium independent distributors and economy broadline tiers creates entry space for regional cold-chain specialists with organic certification. Target Sun Belt metro food truck clusters where municipal permit streamlining reduces capital barriers. Pursue white-label commissary production for corporate campus outsourcing as the fastest-penetrable institutional segment. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialty protein distributors with USDA certification in the Southeast and Mountain West corridors. Long-term viability hinges on five-to-ten-year demographic migration patterns toward healthcare-intensive geographies. Watch senior living occupancy rates as the inflection signal for contracted foodservice demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Commissary Automation Investment | Robotic portioning systems absorb labor costs in 10,000-meal daily hospital production facilities. |
| Clinical Nutrition Certification | Registered dietitian staffing satisfies state-level sodium reduction mandates for healthcare contracts. |
| Cold-Chain Traceability Upgrade | Temperature-logging hardware meets FDA Food Code 2022 allergen control inspection standards. |
| Sun Belt Geographic Expansion | Dallas-Fort Worth and Orlando corridors absorb fastest population migration and tourism investment. |
| Healthcare Contract Consolidation | Single-source broadline agreements displace fragmented local vendor relationships in California and Texas. |
Research Methodology
Document review covered FDA Food Code 2022 adoption patterns, USDA National School Lunch Program specifications, and state health department inspection protocols, complemented by interviews with broadline distribution executives, hospital procurement officers, senior living facility operators, and commercial kitchen equipment manufacturers. Secondary sources included SEC 10-K filings from listed distributors, OSHA workplace safety incident databases, and municipal composting ordinance records. Bottom-up volume estimates from institutional meal counts were triangulated against top-down market value assessments.
Historical volume trajectories were cross-referenced against panel input from foodservice operators across the projection horizon. The analytical framework modeled segmentation dimensions including service type, cuisine category, customer archetype, and delivery mode, with additional granularity on healthcare versus commercial end-use. CAGRs were derived from trend extrapolation adjusted for demographic migration patterns and regulatory compliance cost absorption. Forecast inputs incorporated protein commodity price cycles and senior living construction permit data.
Inputs from distributor sales executives and state health department officials were available through the study window; gaps in real-time commodity contract pricing introduce uncertainty bands around margin projections. Forecasts reflect assumptions about FDA Food Code adoption timing and Sun Belt migration velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Italy Foodservice Market
Food Service
Germany Foodservice Market
Food Service
Lunch Takeout Market
Food Service
Food Service Market
Food Service
International Food Subscription Box Service Market
Food Service
Online Grocery Market
Food Service
Gas Fryers Market
Food Service
Europe Inflight Catering Market
Food Service
South America Free from Food Market
Food Service
Pizza Foodservice Market
Food Service
United States Cafes & Bars Market
Food Service
Air Fryer Market
Food Service
Chinese Takeout Market
Food Service
Smokeless Grill Market
Food Service
Kuwait Food Service Market
Food Service
China Retail Bubble Tea Kits Market