
 Fat Free Salad Dressings Market | 2026-2036
Fat Free Salad Dressings Market Size, Share, and Industry Trends Forecast 2026-2036
Fat Free Salad Dressings Market Foresight
Buyer concentration in the food service channel is restructuring procurement patterns for fat-free salad dressings as chain restaurants consolidate supplier rosters. Unilever PLC leverages its global condiment infrastructure to sustain volume commitments across multiple quick-service accounts. The Kraft Heinz Company anchors retail shelf presence through dominant grocery channel control. McCormick & Company differentiates via flavor technology leadership in vinegar-based formulations.
Fat-free salad dressings are emulsified condiments containing less than 0.5 grams fat per serving, typically stabilized with modified food starch, xanthan gum, or gum arabic to replicate mouthfeel without oil content, manufactured through high-shear homogenization and cold-fill processes to preserve flavor integrity and extend refrigerated shelf life. Vinegar-based variants occupy the largest volume share due to lower ingredient cost and cleaner label positioning, while yogurt-based formulations represent the fastest-expanding margin pool as protein-forward positioning attracts wellness-oriented shoppers. Pouch packaging is gaining traction in food service for portion control and waste reduction.
The FDA's nutritional labeling requirements and the USDA's school meal nutrition standards shape product formulation decisions and channel access for manufacturers. State-level calorie disclosure laws in California and New York extend compliance burdens beyond federal baselines. Stakeholders must monitor evolving clean-label expectations against the technical constraints of fat replacement systems.
Market Dynamics
Clean-label emulsification technology is restructuring competitive positioning in fat-free salad dressings as manufacturers replace modified food starch and xanthan gum systems with protein-based or fiber-based stabilizers to meet consumer transparency demands without sacrificing shelf stability.
Growth Catalysts
- Calorie-Labeling Mandates:The FDA's menu labeling requirements and state-level disclosure laws in California and New York are compelling food service operators to expand fat-free dressing placements to maintain compliance and consumer trust.
- Clean-Label Technology:High-shear homogenization combined with cold-fill processing is enabling manufacturers to eliminate artificial stabilizers while preserving the mouthfeel consumers expect from traditional oil-based formulations.
- Food Service Channel Consolidation:Chain restaurant procurement centralization is creating volume commitments that favor suppliers with national distribution infrastructure and consistent reformulation capabilities.
Market Restraints
- Input Cost Volatility:Gum arabic prices fluctuate with harvest conditions in Sudan and Chad, creating margin pressure for manufacturers dependent on this traditional stabilizer for emulsion stability.
- Technical Limitation:Fat replacement systems struggle to replicate the flavor carry and texture of oil-based dressings in creamy variants, limiting consumer acceptance beyond vinegar-based categories.
- Regulatory Friction:The USDA's school meal nutrition standards create formulation constraints that conflict with clean-label positioning, forcing dual product lines for institutional versus retail channels.
Strategic Opportunities
- Yogurt-Based Formulations:Protein-forward positioning in wellness-oriented retail channels is opening margin expansion opportunities as consumers accept premium pricing for functional nutrition claims.
- Pouch Packaging Innovation:Single-serve flexible packaging is penetrating food service accounts seeking portion control and waste reduction, displacing traditional portion cups in quick-service environments.
- Dual Carbon Goals:China's national carbon neutrality targets are accelerating domestic demand for plant-based, low-carbon dressing alternatives, creating export opportunities for clean-label manufacturers.
Industry Challenges
- Flavor Chemistry Expertise Gap:The intersection of emulsion science and natural flavor masking requires specialized food technologists that mid-tier manufacturers struggle to recruit and retain.
- Refrigerated Supply Chain Reconfiguration:Cold-fill processes demand temperature-controlled distribution infrastructure that many regional distributors lack, constraining geographic expansion for perishable formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat Free Salad Dressings Market |
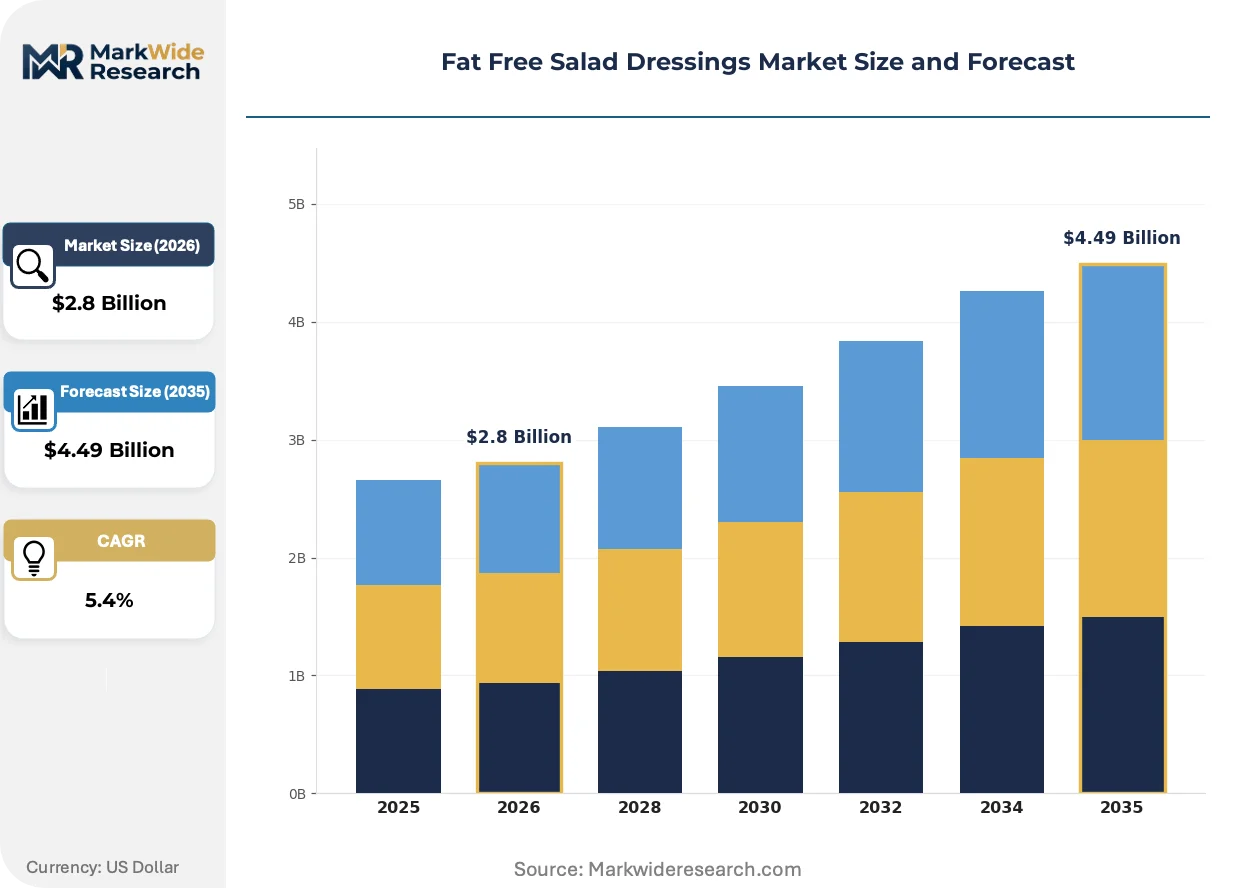
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinegar-Based, Yogurt-Based, Cream-Based, Oil-Based Flavor Profile: Italian, Balsamic, Ranch, Honey Mustard Packaging Type: Bottles, Pouches, Jars, Sachets Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service |
| Companies Covered | Unilever PLC, The Kraft Heinz Company, McCormick & Company, Dr. Oetker, Campbell Soup Company, Conagra Brands Inc., Hormel Foods Corporation, Southeastern Mills Inc., Remia C.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat Free Salad Dressings Market Shifts & Advancements
Reformulation science is accelerating as manufacturers balance clean-label imperatives against the technical constraints of fat replacement, with packaging and processing innovations converging to reshape product economics and channel access.
Micro-encapsulated flavor systems are modularizing how manufacturers deliver taste intensity in fat-free matrices. Quick-service chains are piloting these systems in limited-menu tests before system-wide rollout. The technology is modularizing supply chain relationships as flavor houses assume greater responsibility for finished-product performance specifications.
REACH authorization requirements for food-contact substances are tightening compliance burdens for European manufacturers sourcing modified starches and emulsifiers. The European Chemicals Agency's expanded substance evaluation program is extending reformulation timelines by 12-18 months for affected suppliers. Vinegar-based variants face fewer regulatory hurdles than creamy formulations, tilting new product development toward acidic categories in EU markets.
Retail buyers are consolidating supplier rosters around vendors offering turnkey clean-label solutions rather than commodity emulsifiers. This concentration is compressing margins for ingredient-only suppliers while rewarding integrated formulation partners. The shift is most visible in United States grocery channels where private-label penetration in fat-free dressings exceeds branded growth rates.
Fat Free Salad Dressings Market Segmentation
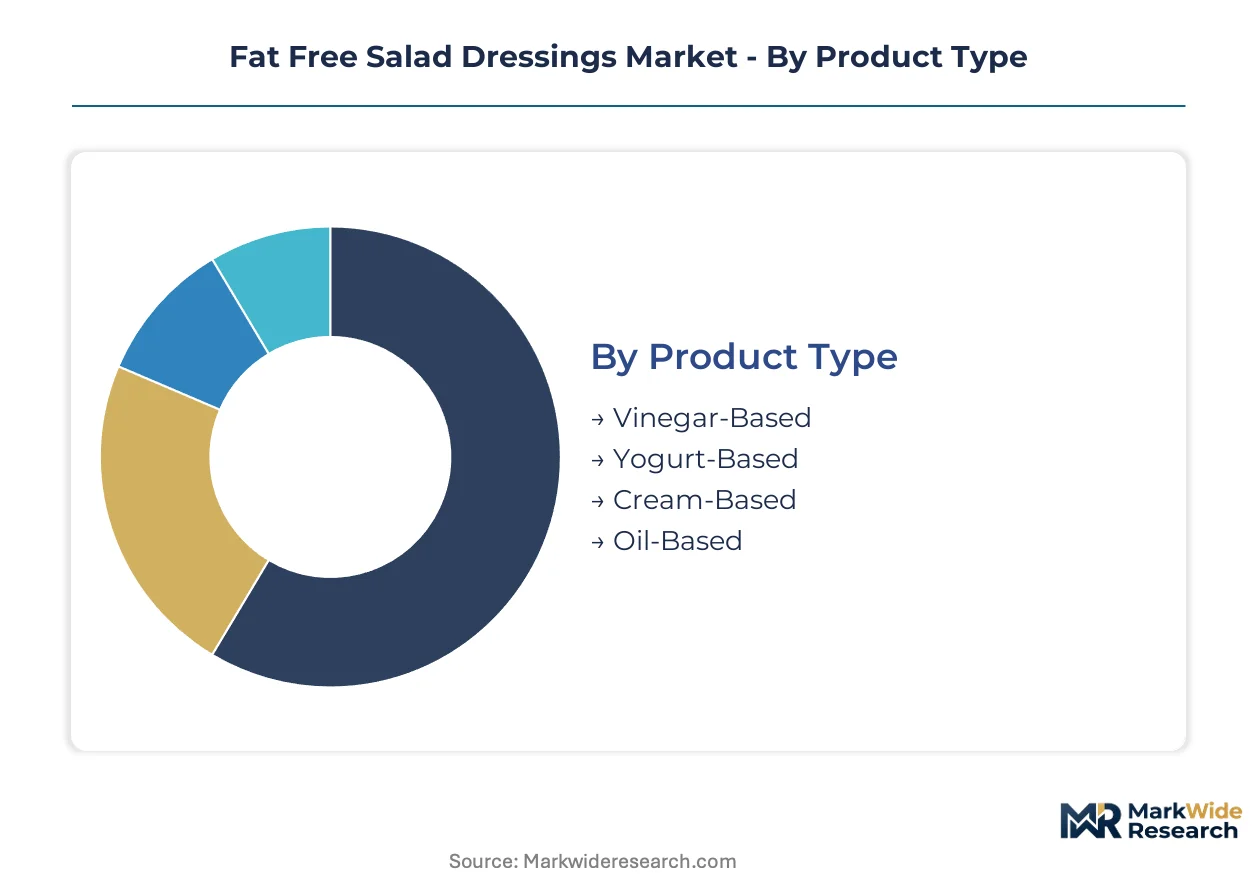
Segmentation in fat-free salad dressings reveals how formulation chemistry, packaging engineering, and channel economics intersect to determine margin capture. Manufacturers must align technical capabilities with the specific compliance and shelf-life requirements of each segment cluster.
Product Type:
The customization-vs-standardization spectrum spans from commodity vinegar formulations to protein-engineered yogurt bases requiring specialized fermentation partnerships.
- Vinegar-Based:Acidic emulsions stabilized with gum arabic or modified food starch deliver the cleanest label positioning and lowest ingredient cost. Demand concentrates in United States retail channels where calorie-labeling mandates at chain restaurants drive food service procurement toward these cost-efficient, compliance-friendly options.
- Yogurt-Based:Fermented dairy matrices incorporate live cultures and elevated protein content, commanding premium positioning in wellness-oriented retail. Expansion is steepest in United States metropolitan markets where functional nutrition claims justify price premiums over conventional fat-free alternatives.
- Cream-Based:Starch-thickened emulsions attempt to replicate mouthfeel of traditional creamy dressings through high-shear homogenization, facing persistent technical limitations in flavor carry.
- Oil-Based:These formulations fall outside strict fat-free classification but appear in hybrid portfolios targeting consumers seeking reduced-fat rather than zero-fat options.
Most installed capacity flows through vinegar-based production lines. Expansion is steepest in yogurt-based formulations.
Flavor Profile:
Flavor development intensity correlates with application complexity, from single-note Italian vinaigrettes to multi-layered ranch systems requiring advanced masking technology.
- Ranch:Buttermilk-derived flavor systems demand sophisticated emulsion science to maintain stability without oil content, representing the most technically challenging mainstream flavor. Adoption concentrates in United States quick-service accounts where ranch dominates salad dressing consumption patterns.
- Balsamic:Grape must reduction provides natural sweetness and viscosity, reducing dependence on artificial stabilizers and aligning with clean-label positioning in premium retail tiers.
- Italian:Herb and red wine vinegar combinations offer straightforward formulation pathways with established consumer acceptance across demographic segments.
- Honey Mustard:Sweet-acid balance requires careful sugar management to maintain fat-free status while delivering expected flavor intensity.
Volume concentrates in ranch and Italian variants. Balsamic is gaining share fastest in premium retail channels.
Packaging Type:
Packaging economics divide between capital-intensive bottling infrastructure and flexible-format pouch systems with divergent supply chain requirements.
- Pouches:Single-serve flexible formats reduce food service waste and enable precise portion control for calorie-labeling compliance. Demand is accelerating in United States quick-service chains seeking operational efficiency alongside regulatory adherence.
- Bottles:Standard retail formats dominate household purchasing through supermarket channels, requiring cold-fill processing capabilities and refrigerated distribution infrastructure.
- Jars:Wide-mouth glass containers serve deli-counter and food service bulk applications where scoop dispensing remains operational standard.
- Sachets:Individual portion packets persist in institutional settings including USDA-regulated school meal programs with strict nutrition standard compliance requirements.
Most cold-fill capacity serves bottle formats. Pouch adoption is climbing the fastest in food service channel restructuring.
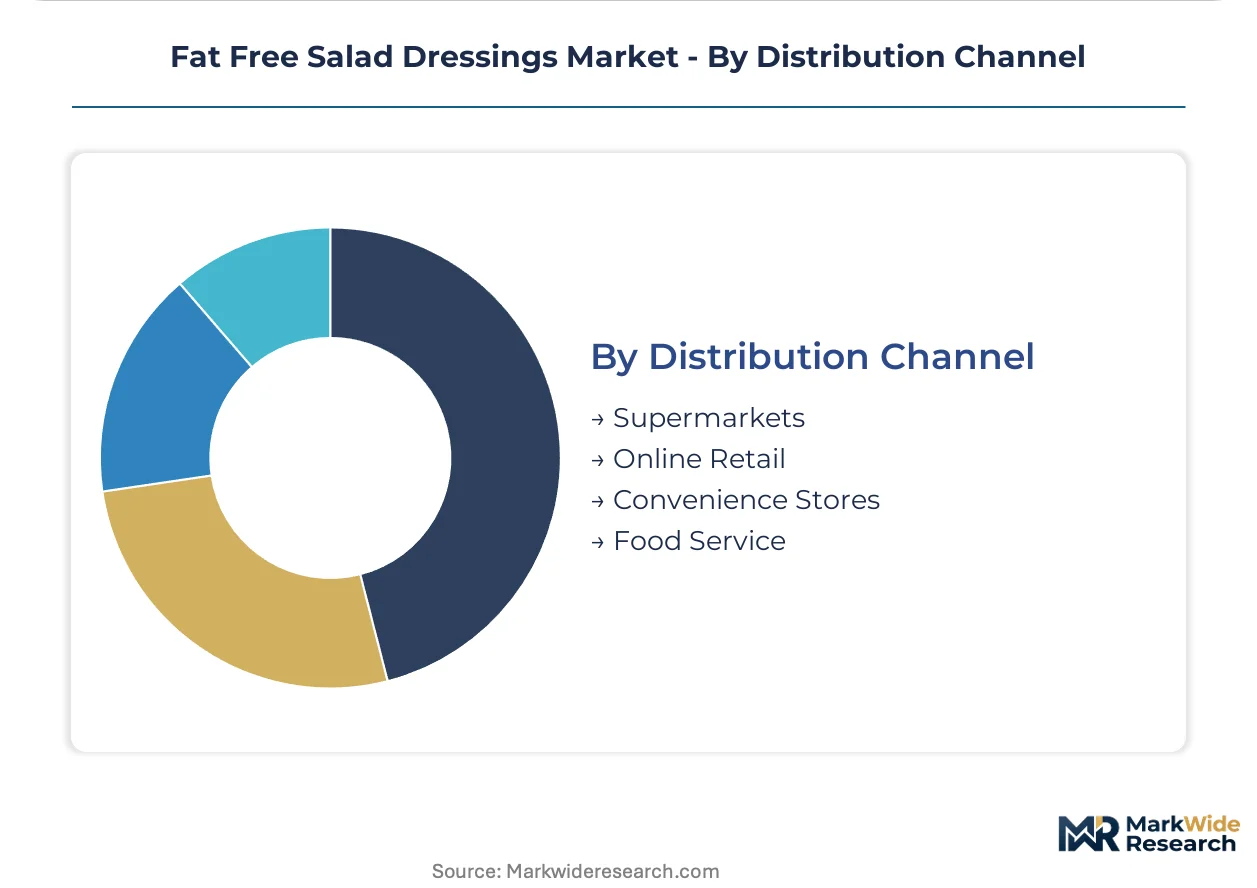
Distribution Channel:
Channel access determines formulation specifications, with food service demanding shelf-stable concentrates and retail requiring refrigerated finished goods with extended label claims.
- Food Service:Chain restaurant procurement centralization favors suppliers with national distribution infrastructure and consistent reformulation capabilities for calorie-labeling compliance. Volume commitments from consolidated buyers are restructuring supplier relationships toward integrated formulation partners.
- Supermarkets:Dominant United States grocery channel control anchors retail shelf presence, with private-label penetration exceeding branded growth rates as buyers consolidate around turnkey clean-label vendors.
- Online Retail:Direct-to-consumer channels enable subscription models for wellness-positioned yogurt-based variants, though cold-chain logistics constrain geographic reach.
- Convenience Stores:Limited refrigeration capacity restricts assortment to shelf-stable vinegar-based options with extended ambient shelf life.
Revenue concentrates in supermarket and food service channels. Online retail is expanding most quickly for premium yogurt-based offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates substantially higher per-capita consumption of fat-free salad dressings than Germany, where traditional oil-based formulations retain stronger cultural preference despite tightening nutritional labeling requirements.
United States
Calorie-labeling mandates at chain restaurants and school meal nutrition standards drive food service procurement toward vinegar-based options. The FDA enforces menu labeling requirements that expand fat-free placements. Chicago and Dallas-Fort Worth anchor quick-service chain procurement centralization.
Germany
REACH authorization requirements for food-contact substances extend reformulation timelines for creamy dressing variants. The ECHA substance evaluation program tightens compliance burdens on modified starch imports. Bavaria hosts major condiment manufacturing clusters adapting to clean-label emulsification shifts.
China
Dual carbon goals accelerate domestic demand for plant-based, low-carbon dressing alternatives in urban retail channels. The SAMR regulates nutritional claims on imported formulations. Shanghai and Beijing metropolitan markets concentrate wellness-oriented yogurt-based product trials.
United Kingdom
Private-label penetration in supermarket channels exceeds branded growth as buyers consolidate supplier rosters. The FSA enforces front-of-pack nutritional labeling schemes. Greater London anchors retail velocity for premium balsamic and Italian flavor variants.
Japan
Functional nutrition claims on protein-forward dressings attract aging demographics seeking wellness positioning. The PMDA oversees health claim substantiation for fermented yogurt-based products. The Kanto region around Tokyo drives innovation in portion-controlled pouch packaging formats.
Fat Free Salad Dressings Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions in clean-label formulation technology. The vendor base clusters around three strategic archetypes: diversified condiment conglomerates with global distribution infrastructure, flavor technology specialists leveraging emulsion science capabilities, and private-label manufacturers serving consolidated retail procurement. Competitive dynamics center on M&A activity to secure cold-fill processing capacity and strategic partnerships with protein-based stabilizer suppliers.
Within the diversified conglomerate tier, Unilever PLC and The Kraft Heinz Company exemplify scale-driven positioning through grocery channel control and food service volume commitments. McCormick & Company occupies a specialist position representing flavor technology leadership in vinegar-based formulations. These three entities collectively illustrate how competitive advantage in fat-free dressings converges on emulsification expertise and refrigerated supply chain reach.
| Leading Market Players |
|---|
| Unilever PLC |
| The Kraft Heinz Company |
| McCormick & Company |
| Dr. Oetker |
| Campbell Soup Company |
| Conagra Brands Inc. |
| Hormel Foods Corporation |
| Southeastern Mills Inc. |
| Remia C.V. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up food ingredient specialists now control substantial modified starch and gum arabic processing capacity, enabling coordinated supply allocation that tightens pricing discipline across vinegar-based and yogurt-based formulation tiers.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for cold-fill processed fat-free dressings as regional dairy processors expand yogurt-base fermentation infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates protein-forward wellness positioning from commodity vinegar formulations. Price differentiation hinges on clean-label certification tier and refrigerated distribution reach. Pricing pressure stems from Sudanese gum arabic harvest volatility, squeezing margins for manufacturers without captive stabilizer supply. Food service buyers exhibit highest price sensitivity due to calorie-labeling compliance mandates, while direct-to-consumer wellness channels accept premium positioning.
Supply Chain Analysis
Refrigerated freight costs from Upper Midwest dairy clusters to coastal metropolitan markets constrain geographic expansion for yogurt-based formulations with limited shelf stability. Supply concentrates in the United States for cold-fill processing infrastructure, Germany for clean-label emulsification technology, and Sudan for gum arabic harvests. Raw material dependencies include fermented dairy proteins, modified food starches, and natural flavor masking systems. Single-source vulnerability in Sudanese gum arabic creates disruption risk during harvest shortfalls. Distribution runs through temperature-controlled regional distributors serving supermarket chains, with food service procurement centralizing around national broadline operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as wellness-oriented consumers shift demand toward protein-forward yogurt-based formulations with functional nutrition claims, rewarding manufacturers with fermentation partnerships and clean-label credentials.
For Market Incumbents: Cement control over refrigerated distribution infrastructure through exclusive partnerships with regional cold-chain operators, defending against emerging plant-based entrants with inferior temperature compliance. Secure backward integration into protein-based stabilizer supply to insulate margins from gum arabic price volatility. Prioritize R&D investment in micro-encapsulated flavor systems to maintain technical differentiation in ranch and creamy variants where fat replacement challenges persist. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting wellness-oriented metropolitan markets in the United States, bypassing supermarket slotting fee barriers that favor established brands. Exploit white-space opportunity in pouch-packaged single-serve formats for quick-service chains seeking waste reduction alongside calorie-labeling compliance. Target online retail channels where cold-chain logistics partnerships enable premium yogurt-based positioning without national refrigerated distribution scale. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier private-label manufacturers lacking cold-fill processing capacity but holding established retailer relationships. Long-term viability over the projection horizon favors integrated formulation partners with turnkey clean-label capabilities over commodity emulsifier suppliers facing margin compression. Watch for inflection signals in FDA enforcement patterns around menu labeling requirements, which would accelerate food service channel restructuring toward compliant fat-free suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stabilizer Supply | Captive gum arabic or protein-based stabilizer production insulates margins from Sudanese harvest volatility. |
| Cold-Fill Processing Capacity Expansion | Additional refrigerated production lines capture food service volume from calorie-labeling mandate compliance. |
| Pouch Packaging Format Introduction | Single-serve flexible formats penetrate quick-service accounts seeking portion control and waste reduction. |
| Clean-Label Certification Investment | FDA-aligned natural positioning commands premium pricing in wellness-oriented retail channels. |
| Fermentation Partnership Development | Specialized dairy protein supply secures yogurt-based formulation expansion in functional nutrition segments. |
Research Methodology
Direct dialogue with food service procurement directors, refrigerated distribution operators, clean-label R&D scientists, and supermarket category buyers grounded qualitative findings, validated against FDA regulatory filings, USDA school meal nutrition databases, Nielsen retail audit data, and SEC disclosures from diversified condiment conglomerates. Bottom-up and top-down triangulation reconciled channel-level volume estimates with national production capacity assessments.
Bottom-up modeling aggregated segment-level demand across vinegar-based, yogurt-based, cream-based, and oil-based formulation chemistry, cross-referenced against packaging format adoption curves and distribution channel penetration rates. Top-down constraints incorporated macroeconomic consumption patterns and regulatory enforcement timelines. CAGRs derived from fitted growth curves across the analysis window, with yogurt-based protein-forward positioning and pouch packaging innovation treated as accelerant variables.
Forecast precision tightens around the base case; tail outcomes carry wider variance under gum arabic supply disruption scenarios or abrupt shifts in FDA calorie-labeling enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Dips and Spreads Market
Condiments & Sauces
Latin America Pasta Sauce Market
Condiments & Sauces
Barbecue Sauce Market
Condiments & Sauces
Ketchup Concentrates Market
Condiments & Sauces
Sandwich Spread Market
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
Hot Sauce Powder Market
Condiments & Sauces
Hot Sauce Market
Condiments & Sauces
Cheese Sauce Market
Condiments & Sauces
Culinary Sauces Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
West Africa Mayonnaise Market
Condiments & Sauces
Salad Dressings and Mayonnaise Market
Condiments & Sauces
Vegan Sauces Market
Condiments & Sauces
Sauce Making Machine Market
Condiments & Sauces
Cocktail Syrups Market