
 Diabetic Food Market | 2026-2036
Diabetic Food Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetic Food Market Analysis
Capital-intensity divergence between multinational CPG conglomerates and regional specialists is unwinding competitive dynamics in diabetic food manufacturing. PepsiCo leverages its global beverage infrastructure to distribute low-glycemic drinks at scale, while Nestle sustains category leadership through specialized metabolic health R&D pipelines. Mondelez International competes in the confectionery-adjacent segment with portion-controlled, reduced-sugar formulations that anchor its wellness portfolio.
Diabetic food comprises nutritionally modified products engineered with controlled carbohydrate loads, specific glycemic indices below 55, and alternative sweetener systems such as steviol glycosides or allulose to support blood glucose management. These formulations serve commercial purposes ranging from retail consumer self-management to clinical institutional procurement for controlled patient diets. Snacks and beverages command the largest revenue pools within product type segmentation, reflecting impulse-purchase frequency and hydration-driven consumption rituals. Fiber-enriched ingredient formulations capture expanding margin pools as consumers prioritize satiety and digestive health alongside glycemic control. Online retailers represent the fastest-growing distribution channel, displacing traditional supermarket dominance through subscription models and direct-to-consumer diagnostic integrations.
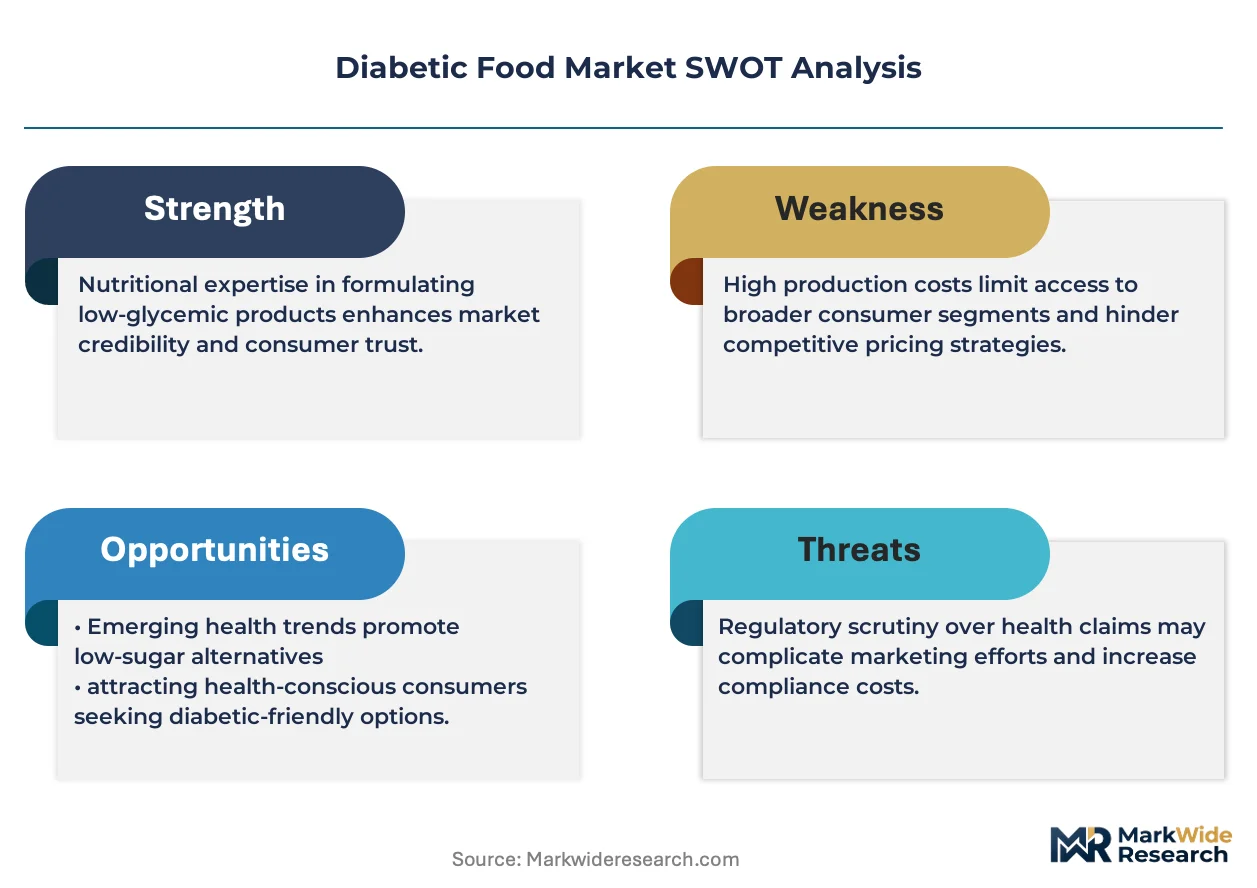
The FDA governs diabetic food labeling through its Nutrition Facts panel and health claim substantiation requirements, while the EPA regulates agricultural inputs for ingredient sourcing. EFSA and national European regulators enforce glycemic response validation for products bearing metabolic health claims, creating compliance cost barriers for non-EU exporters. Stakeholders must monitor evolving reimbursement eligibility criteria from Germany's statutory health insurers and the trajectory of glucose-responsive packaging technologies.
Market Dynamics
Continuous glucose monitoring adoption is compressing the feedback loop between consumption and metabolic response, forcing formulation cycles from annual to quarterly cadences as real-time biometric data reshapes product development priorities.
Growth Catalysts
- CGM-Beverage Integration:Smart bottle caps that sync with Dexcom and Abbott sensors are creating closed-loop hydration management systems for Type 1 diabetics in the United States.
- Germany's SHI Reimbursement:Statutory health insurance coverage for prescribed diabetic foods locks in predictable institutional procurement volumes and reduces patient price sensitivity.
- Allulose Scale-Up:Enzymatic conversion of fructose to this rare sugar is achieving cost parity with sucrose in North American manufacturing, enabling mass-market formulation shifts.
Market Restraints
- Stevia Supply Concentration:Raw steviol glycoside extraction concentrates among Chinese processors, exposing formulators to agricultural volatility and geopolitical friction.
- EFSA Glycemic Validation Costs:European metabolic health claims require clinical substantiation that consumes 18-24 months and seven-figure investment per SKU, freezing SME participation.
- Whole-Food Substitution:Unprocessed low-glycemic whole foods compete directly with engineered diabetic products on perceived naturalness and lower unit cost.
Strategic Opportunities
- India's Underserved Tier-2 Cities:Rising diabetes prevalence in Nagpur, Jaipur, and Lucknow outpaces organized retail coverage, creating first-mover whitespace for direct distribution.
- Glucose-Responsive Packaging:Color-shifting labels that indicate real-time glycemic load are converging with printed electronics to create interactive shelf differentiation.
- US Medicare CGM Expansion:Coverage extension to prediabetic populations is expanding the addressable user base for integrated food-sensor ecosystems.
Industry Challenges
- Formulation Talent Scarcity:Food scientists with dual competency in glycemic engineering and sensory optimization command 40% wage premiums, constraining R&D scaling.
- Legacy ERP Integration:Real-time batch tracking for FDA-compliant diabetic food manufacturing requires retrofitting antiquated MRP systems with serialized traceability modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetic Food Market |
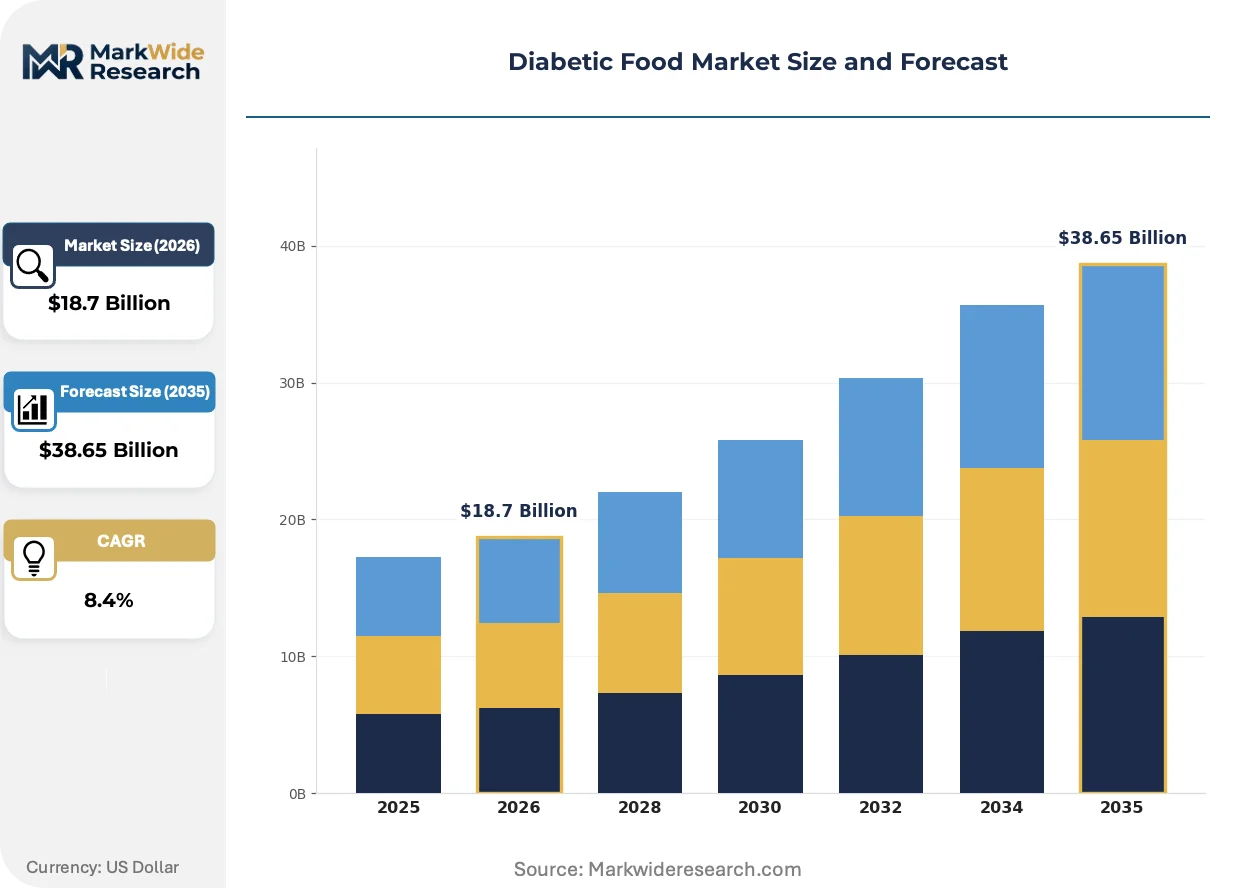
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Beverages, Desserts, Breakfast Foods Ingredient: Natural Sweeteners, Whole Grains, Low-Carb Alternatives, Fiber-Enriched Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Pharmacies End User: Individuals, Hospitals, Clinics, Nutritionists |
| Companies Covered | PepsiCo, Mars Incorporated, Nestle, Conagra Brands, Mondelez International, Unilever, The Kellogg Company, The Hershey Company, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetic Food Market Emerging Trajectories
Biometric feedback loops and precision fermentation are collapsing the distance between metabolic science and commercial food production, while regulatory jurisdictions race to standardize glycemic claim substantiation.
Micro-encapsulated fiber systems are miniaturizing. These sub-micron inulin and resistant starch particles mask texture degradation in reduced-sugar baked goods. Bakery manufacturers in the Netherlands and Denmark are adopting at pilot scale this quarter. The technology is miniaturizing delivery vehicles for functional ingredients, enabling clean-label positioning without sensory compromise.
REACH-compliant novel food ingredient pathways are tightening. EFSA's 2023 guidance on post-market surveillance for alternative sweeteners now requires 24-month safety monitoring. European formulators are consolidating SKU portfolios to limit compliance exposure. The confectionery segment is responding by retreating to grandfathered sweetener systems and delaying next-generation launches.
Subscription-based diagnostic bundles are displacing supermarket impulse purchasing. Direct-to-consumer platforms pair monthly CGM supplies with matched meal kits, capturing lifetime value through data lock-in. This model concentrates in Germany and the United Kingdom where insurance reimbursement structures accommodate bundled preventive care. Retail pharmacy chains are responding with counter-offers of loyalty-integrated glucose testing stations.
Diabetic Food Market Segmentation
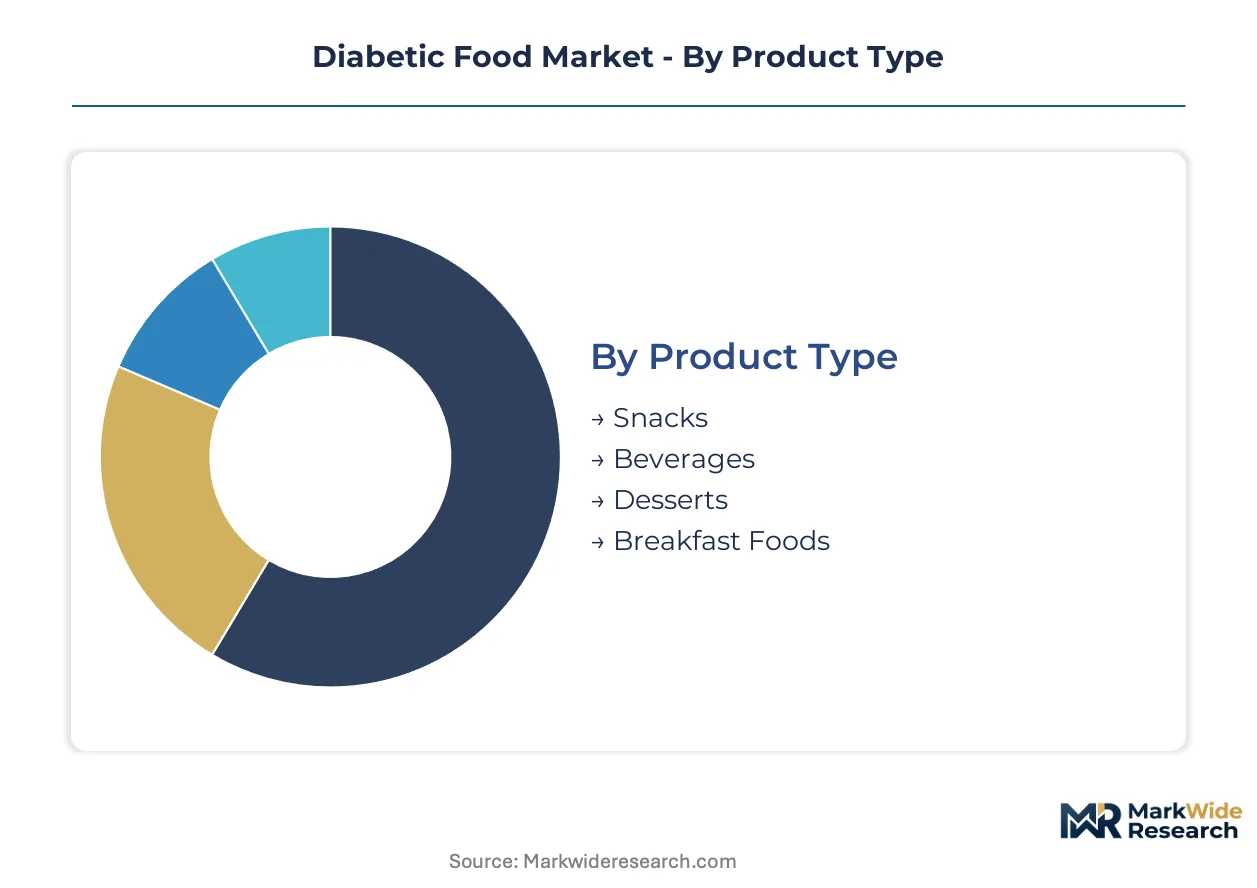
Segmentation in diabetic food markets reveals divergent margin structures across formulation intensity and channel control. Product type and ingredient sophistication determine pricing power, while distribution channel selection governs customer acquisition economics and reimbursement access.
Product Type:
Margin pools concentrate in beverage formulations where hydration rituals drive repeat purchase frequency and premium positioning tolerance.
- Snacks:Portion-controlled formulations with glycemic indices below 55 anchor retail shelf presence. Demand clusters in North American pharmacy chains where CGM-coupled purchasing drives basket size expansion.
- Beverages:Low-glycemic hydration products integrate with continuous glucose monitoring systems through smart packaging. Germany's statutory health insurance reimbursement locks in predictable institutional procurement volumes for clinical hydration protocols.
- Desserts:Reduced-sugar confectionery employing allulose and steviol glycoside systems targets indulgence occasions without glycemic spikes.
- Breakfast Foods:Fiber-enriched cereals and modified carbohydrate porridges serve morning glycemic management routines.
Snacks hold installed capacity. Beverages are rotating up the share rankings.
Ingredient:
Cost tier stratification separates commodity sweetener substitutions from proprietary fiber delivery systems commanding formulation premiums.
- Natural Sweeteners:Steviol glycosides and monk fruit extracts replace sucrose in clean-label positioning. Supply concentration among Chinese processors exposes formulators to agricultural volatility and geopolitical friction.
- Fiber-Enriched:Micro-encapsulated inulin and resistant starch particles mask texture degradation in reduced-sugar applications. Netherlands and Denmark bakery manufacturers are adopting sub-micron delivery systems at pilot scale.
- Whole Grains:Unmodified low-glycemic cereals compete on perceived naturalness against engineered alternatives.
- Low-Carb Alternatives:Almond flour, coconut flour, and modified starch systems enable ketogenic-compliant product extensions.
Natural sweeteners dominate current formulation volumes. Fiber-enriched systems are climbing the fastest as satiety claims gain regulatory traction.
Distribution Channel:
Channel selection determines reimbursement eligibility and customer lifetime value capture through data integration potential.
- Online Retailers:Subscription models pairing CGM supplies with matched meal kits concentrate lifetime value through diagnostic data lock-in. Germany and United Kingdom insurance structures accommodate bundled preventive care procurement.
- Pharmacies:Retail pharmacy chains are expanding shelf space for glycemic-index-certified products and deploying loyalty-integrated glucose testing stations to counter direct-to-consumer platforms.
- Supermarkets:Traditional mass retail faces displacement as impulse purchasing migrates to diagnostic-coupled channels.
- Health Food Stores:Specialty retailers serve premium-positioned clean-label segments outside reimbursement systems.
Supermarkets retain legacy volume foundations. Online retailers are gaining share fastest through subscription model economics.
End User:
Customer type segmentation separates self-directed consumer purchasing from institutional procurement governed by clinical protocol and reimbursement rules.
- Individuals:Self-managing consumers purchase through retail and direct-to-consumer channels, with CGM integration driving premium tolerance for sensor-coupled products.
- Hospitals:Controlled patient diets require batch-traceable formulations meeting FDA-compliant manufacturing standards.
- Clinics:Outpatient metabolic health programs prescribe reimbursable diabetic foods under Germany's statutory health insurance framework.
- Nutritionists:Professional dietary counseling creates prescription pathways for specialized glycemic management products.
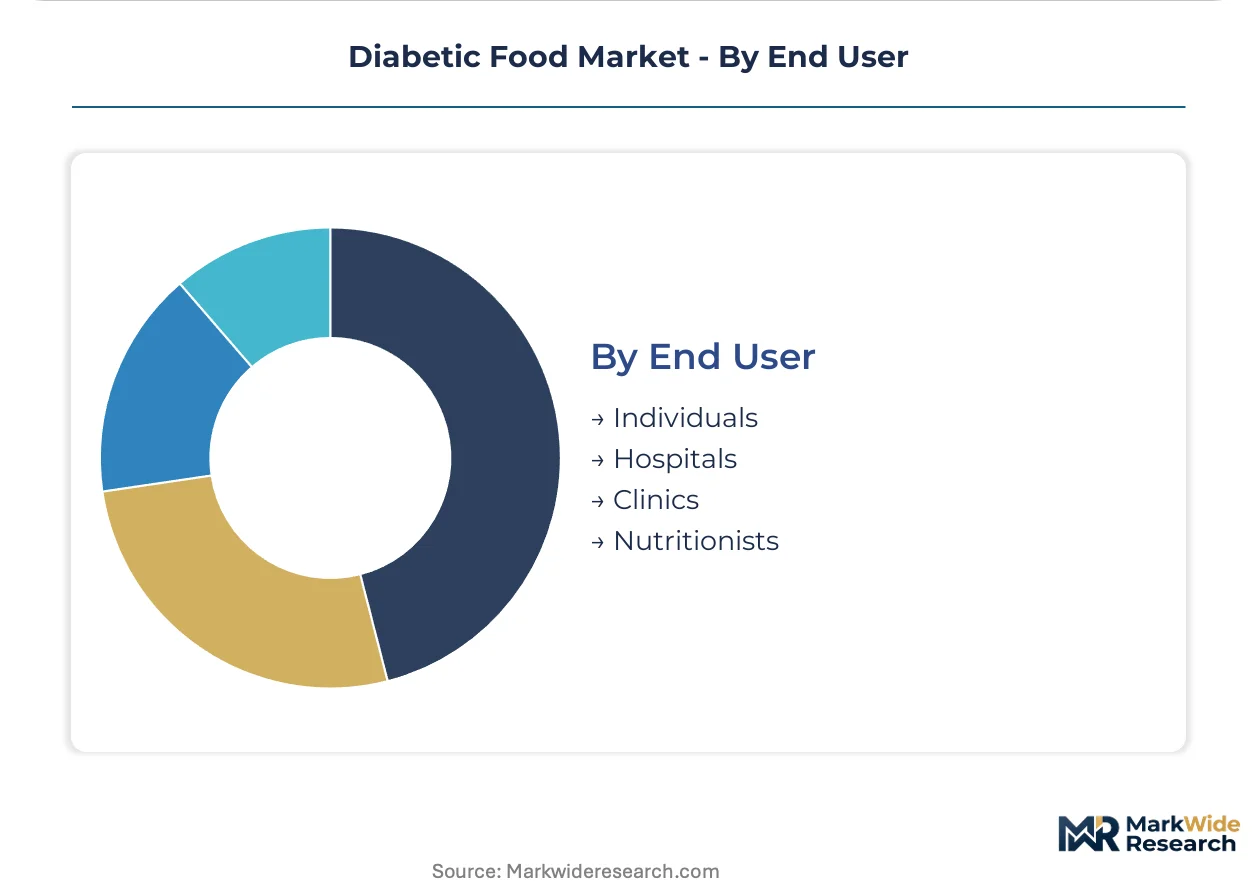
Individuals represent the largest addressable base. Clinics are rotating up the share rankings through reimbursement-driven institutional procurement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany exceeds that in India by a factor of three, reflecting statutory health insurance reimbursement structures against out-of-pocket consumer markets. This asymmetry drives divergent competitive strategies across geographies.
United States
Continuous glucose monitoring adoption and smart packaging integration dominate demand formation. The FDA's updated Nutrition Facts label requirements force quarterly formulation cycles. Retail pharmacy chains in Texas and Florida expand shelf space for glycemic-index-certified products.
Germany
Statutory health insurance reimbursement locks in predictable institutional procurement volumes for prescribed diabetic foods. EFSA glycemic response validation requirements create compliance barriers for imported formulations. The Cologne-Düsseldorf corridor hosts specialized metabolic health R&D facilities serving clinical nutrition protocols.
India
Rising diabetes prevalence in Nagpur, Jaipur, and Lucknow outpaces organized retail coverage. The FSSAI regulates alternative sweetener labeling while state-level food safety authorities enforce manufacturing standards. Direct distribution models target underserved Tier-2 cities with localized formulation adaptations.
China
Enzymatic conversion of fructose to allulose achieves manufacturing scale in Shandong Province processing facilities. SAMR oversees novel food ingredient approvals for alternative sweetener systems. The Yangtze River Delta concentrates steviol glycoside extraction capacity among agricultural processors.
Netherlands
Micro-encapsulated fiber adoption in bakery applications drives pilot-scale manufacturing investments. REACH-compliant novel food pathways require 24-month safety monitoring under EFSA guidance. Amsterdam-Rotterdam logistics hubs facilitate intra-European distribution of glycemic-certified formulations.
Diabetic Food Market Vendor Landscape
Concentration sits with multinational CPG conglomerates that leverage beverage infrastructure and metabolic health R&D pipelines. Regional specialists compete through portion-controlled formulations and clean-label positioning. Three archetypes dominate: scale-driven beverage distributors, specialized metabolic health researchers, and confectionery-adjacent wellness portfolio builders. Competitive moves center on strategic partnerships with continuous glucose monitoring device manufacturers and backward integration into alternative sweetener supply chains.
Among North American-based multinationals, PepsiCo, Nestle, and Mondelez International occupy distinct competitive positions. PepsiCo exemplifies the scale-driven beverage archetype through global distribution infrastructure. Nestle anchors the specialized metabolic health tier with dedicated R&D pipelines. Mondelez International represents the confectionery-adjacent wellness strategy, competing in reduced-sugar formulations that serve indulgence occasions.
| Leading Market Players |
|---|
| PepsiCo |
| Mars Incorporated |
| Nestle |
| Conagra Brands |
| Mondelez International |
| Unilever |
| The Kellogg Company |
| The Hershey Company |
| Danone |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for steviol glycoside concentrates in Chinese processing facilities directly shape formulation cost structures and margin distribution across the diabetic food value chain. This lead-time exposure concentrates pricing power among agricultural processors while forcing finished goods manufacturers into forward-contracting strategies that lock in input costs.
Pricing Analysis
The customization-premium spread between standard glycemic-index-certified formulations and sensor-integrated beverage systems exceeds threefold, reflecting embedded technology costs and reimbursement eligibility. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and CGM compatibility. Pricing pressure stems from allulose scale-up achieving cost parity with sucrose in North American manufacturing. Institutional procurement through Germany's statutory health insurance exhibits lowest price sensitivity, while out-of-pocket consumers in emerging markets face highest elasticity.
Supply Chain Analysis
Inventory concentration in Shandong Province allulose facilities and Yangtze River Delta steviol glycoside extraction creates geographic vulnerability for North American and European formulators. Raw material dependencies center on fructose feedstock for enzymatic conversion, stevia leaf supply from agricultural cooperatives, and micro-encapsulated fiber precursors. Single-source vulnerability in Chinese sweetener processing exposes formulators to tariff friction and agricultural volatility. Distribution runs through Amsterdam-Rotterdam logistics hubs for intra-European fulfillment and direct-to-consumer subscription platforms for sensor-coupled product ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diabetic food market represents early-cycle expansion as continuous glucose monitoring penetration extends beyond Type 1 diabetics into prediabetic populations, creating integrated food-sensor ecosystems that lock in recurring revenue.
For Market Incumbents: Fortify formulation talent pipelines through metabolic health R&D partnerships with German clinical nutrition institutes, countering 40% wage premiums for dual-competency food scientists. Deepen backward integration into alternative sweetener supply chains through offtake agreements with Shandong Province allulose processors, mitigating stevia supply concentration risk.
For New Entrants and Emerging Players: Differentiate on glucose-responsive packaging convergence with printed electronics, capturing shelf differentiation in pharmacy chains expanding glycemic-index-certified assortments. Target India's Tier-2 cities through direct distribution models that bypass organized retail gaps in Nagpur, Jaipur, and Lucknow.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational CPG conglomerates divesting non-core wellness portfolios, particularly confectionery-adjacent reduced-sugar lines lacking CGM integration. Signal to monitor: Medicare coverage expansion for prediabetic CGM access, which would expand addressable user bases for integrated food-sensor ecosystems.
| Strategic Initiative | Industry Significance |
|---|---|
| CGM-Beverage Integration Partnership | Smart bottle cap synchronization with Dexcom and Abbott sensors creates closed-loop hydration management for Type 1 diabetics. |
| Backward Integration into Allulose Supply | Enzymatic conversion capacity capture in North American manufacturing reduces dependence on Chinese steviol glycoside processors. |
| EFSA Glycemic Validation Investment | Clinical substantiation for metabolic health claims unlocks statutory health insurance reimbursement in Germany. |
| Direct-to-Consumer Diagnostic Bundle Launch | Subscription models pairing CGM supplies with matched meal kits concentrate lifetime value through data lock-in. |
| Micro-Encapsulated Fiber Scale-Up | Sub-micron inulin delivery systems enable clean-label positioning in reduced-sugar bakery applications without sensory compromise. |
Methodological Framework
Operator-level perspectives from food formulation scientists, retail pharmacy category managers, statutory health insurance reimbursement officers, and continuous glucose monitoring device manufacturers anchored the qualitative base. These primary inputs combined with FDA Nutrition Facts panel filings, EFSA glycemic response validation databases, German SHI procurement records, and customs trade data for alternative sweetener imports. Bottom-up volume triangulation across product type, ingredient sophistication, and distribution channel intersected with top-down market sizing.
Sensitivity analysis across the analysis window tested input cost volatility for steviol glycosides and allulose, reimbursement policy continuity in Germany, and CGM adoption curve assumptions. Segmentation dimensions modeled include product formulation intensity, glycemic certification tier, channel control level, and regional regulatory cluster. CAGRs derived from annualized growth rate calibration against historical volume trajectories in comparable functional food categories, with specific weighting for Germany's institutional procurement stability and India's retail infrastructure development.
Forecasts assume regulatory continuity in FDA Nutrition Facts requirements and EFSA glycemic claim substantiation; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Oral Clinical Nutrition Supplements Market
Dietary Supplements
Postnatal Health Supplements Market
Dietary Supplements
Pet Skin and Coat Health Supplement Market
Dietary Supplements
Soft Gel Capsule Market
Dietary Supplements
Womens Health and Beauty Supplements Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Australia Nicotine Replacement Therapy Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Global Lipid Regulators Market
Dietary Supplements
Herbal Medicine Market
Dietary Supplements
Cold Remedies Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Lifestyle-Related Disease Supplements Market
Dietary Supplements
Global Oral Electrolyte Solutions Market
Dietary Supplements
Eye Care Supplements Market
Dietary Supplements
Diabetes Supplements Market