
 Continence Care Market | 2026-2036
Continence Care Market Size, Share, and Industry Trends Forecast 2026-2036
Continence Care Market Analysis
Hospital-grade absorbency standards are redrawing procurement criteria across continence care, pushing manufacturers toward higher fluid-retention specifications and dermatological safety testing. Coloplast Group specializes in hydrophilic polymer engineering for extended-wear catheters and pad systems. Essity AB leverages its pulp-to-retail supply chain to sustain cost leadership in the European retail channel. Kimberly-Clark Corporation anchors North American institutional demand through direct contracts with integrated health networks.
Continence care encompasses absorbent and containment products engineered to manage urinary and fecal incontinence, typically constructed with superabsorbent polymer cores, acquisition distribution layers, and breathable backsheet films rated for specific fluid capacities and skin pH compatibility. These products serve aging populations, post-surgical patients, and individuals with neurological conditions requiring dignified, hygienic fluid management outside or within clinical settings. Adult diapers command the largest revenue pool due to institutional volume contracting, though protective underwear is expanding fastest among ambulatory users seeking discretion and self-application. Homecare providers represent a concentrated growth vector as reimbursement shifts favor community-based management over acute facility stays.
The FDA regulates continence products as Class I or II medical devices, mandating 510(k) clearance for novel polymer formulations and adhesive interfaces, while the EU MDR requires notified body certification for absorbent devices claiming therapeutic skin benefits. The EPA and state-level waste authorities in the US are scrutinizing superabsorbent polymer disposal pathways, pressuring manufacturers toward biodegradable composite materials. Stakeholders must monitor evolving extended producer responsibility frameworks and reimbursement tier adjustments that will determine which material platforms and channel configurations capture margin across the forecast window.
Market Dynamics
Hospital-grade absorbency standards are redrawing procurement criteria across continence care, pushing manufacturers toward higher fluid-retention specifications and dermatological safety testing. Coloplast Group specializes in hydrophilic polymer engineering for extended-wear catheters and pad systems. Essity AB leverages its pulp-to-retail supply chain to sustain cost leadership in the European retail channel. Kimberly-Clark Corporation anchors North American institutional demand through direct contracts with integrated health networks.
Growth Catalysts
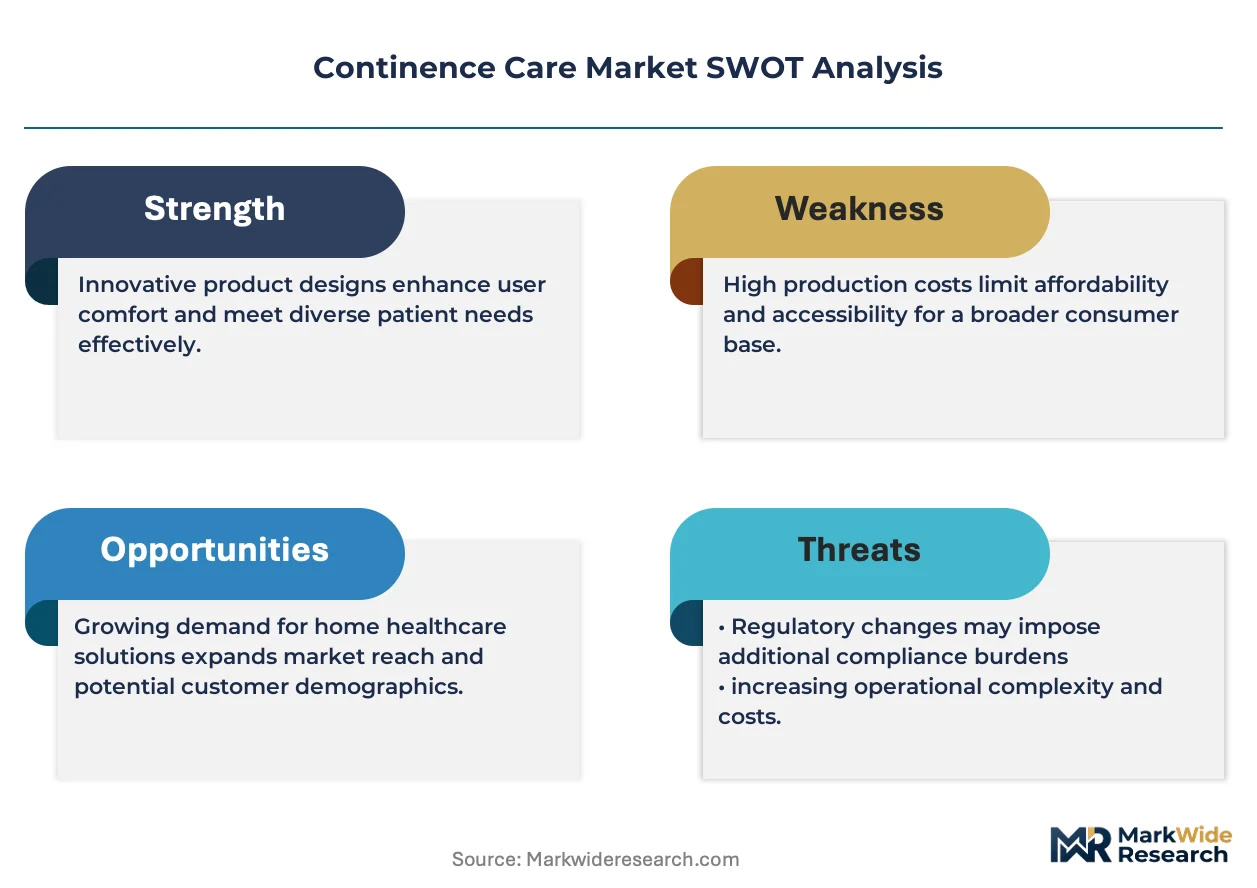
- EU MDR biocompatibility mandates:The Medical Device Regulation tightens polymer safety requirements for absorbent inserts, forcing manufacturers to upgrade testing protocols and creating demand for certified premium products.
- Germany's reimbursement clarity:Aging demographics combined with explicit coverage for advanced continence products drive premium uptake among homecare providers and institutional buyers.
- Superabsorbent polymer innovation:Hydrophilic core engineering enables extended-wear performance, reducing change frequency and lowering total cost of care for post-surgical and neurological patient segments.
Market Restraints
- Petrochemical input volatility:Superabsorbent polymers depend on acrylic acid derivatives, exposing margins to crude oil price swings and specialized chemical supply bottlenecks.
- East Asian supply concentration:Bulk polymer production clusters in China and South Korea, creating geographic risk for European and North American manufacturers without captive supply.
- Biodegradability technical ceiling:Current polymer science cannot match petroleum-based absorbency in compostable formats, limiting regulatory compliance pathways in jurisdictions with extended producer responsibility laws.
Strategic Opportunities
- Homecare channel expansion:Reimbursement shifts favor community-based management over acute facility stays, creating white space for direct-to-patient subscription models and specialized delivery logistics.
- Protective underwear ambulatory segment:Self-application demand among mobile users remains underpenetrated relative to adult diapers, offering margin expansion through discreet, fashion-conscious product design.
- EPA biodegradable material incentives:State-level waste authority scrutiny of polymer disposal creates competitive advantage for manufacturers investing in compostable composite research and take-back programs.
Industry Challenges
- 510(k) clearance timelines:FDA review of novel adhesive interfaces and polymer formulations extends product development cycles, compressing first-mover windows against established portfolios.
- Dermatological testing capacity:Biocompatibility certification requires specialized laboratory partnerships, creating bottlenecks for mid-tier manufacturers without in-house toxicology capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continence Care Market |
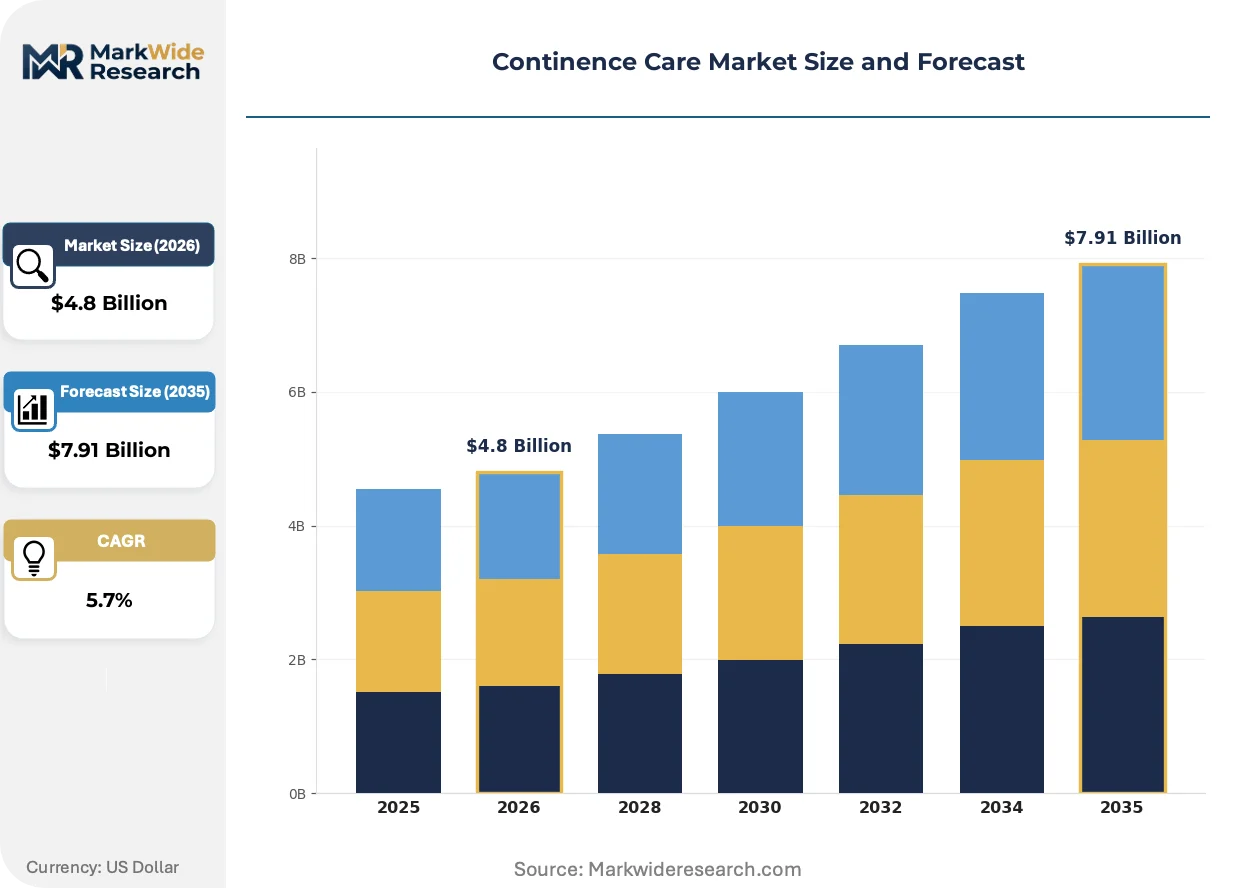
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbent Pads, Adult Diapers, Protective Underwear, Male Guards End User: Individuals, Healthcare Facilities, Homecare Providers, Rehabilitation Centers Distribution Channel: Pharmacies, Online Stores, Hospitals, Supermarkets Material: Polymer, Cotton, Non-woven Fabric, Composite Materials |
| Companies Covered | Kimberly-Clark Corporation, B. Braun Melsungen AG, Coloplast Group, Procter & Gamble Company, Wellspect HealthCare, ConvaTec Group Plc, Essity AB, Ontex Group NV, Hollister Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continence Care Market Emerging Trajectories
Sensor-embedded absorbent products and sustainable material science are actively reshaping competitive positioning in continence care. Manufacturers balance performance imperatives against regulatory pressure for environmental compliance. Digital health integration opens new service revenue streams while complicating traditional device economics.
Wearable moisture detection technology is miniaturizing. Thin-film sensors embedded within pad layers transmit real-time saturation data to caregiver applications, enabling predictive change scheduling. Nursing homes and dementia care facilities in Scandinavia pilot these systems to reduce skin breakdown incidents. The technology is miniaturizing hardware costs sufficiently to penetrate homecare segments previously priced out of connected health solutions.
REACH chemical restriction expansions are tightening polymer disclosure requirements for products marketed with therapeutic skin claims. Manufacturers must now document full supply chain substance inventories down to 0.1% concentration thresholds. Absorbent devices positioned for eczema-prone or post-radiation patients face the steepest compliance burden, driving reformulation investments among premium-tier suppliers.
Direct contracting between integrated health networks and manufacturers is compressing distributor intermediation. Large hospital systems negotiate volume guarantees for standardized absorbency specifications, bypassing traditional medical supply wholesalers. This pattern concentrates most visibly in Germany's statutory health insurance framework, where procurement centralization at insurer level rewards scale and certification depth over brand recognition.
Continence Care Market Segmentation
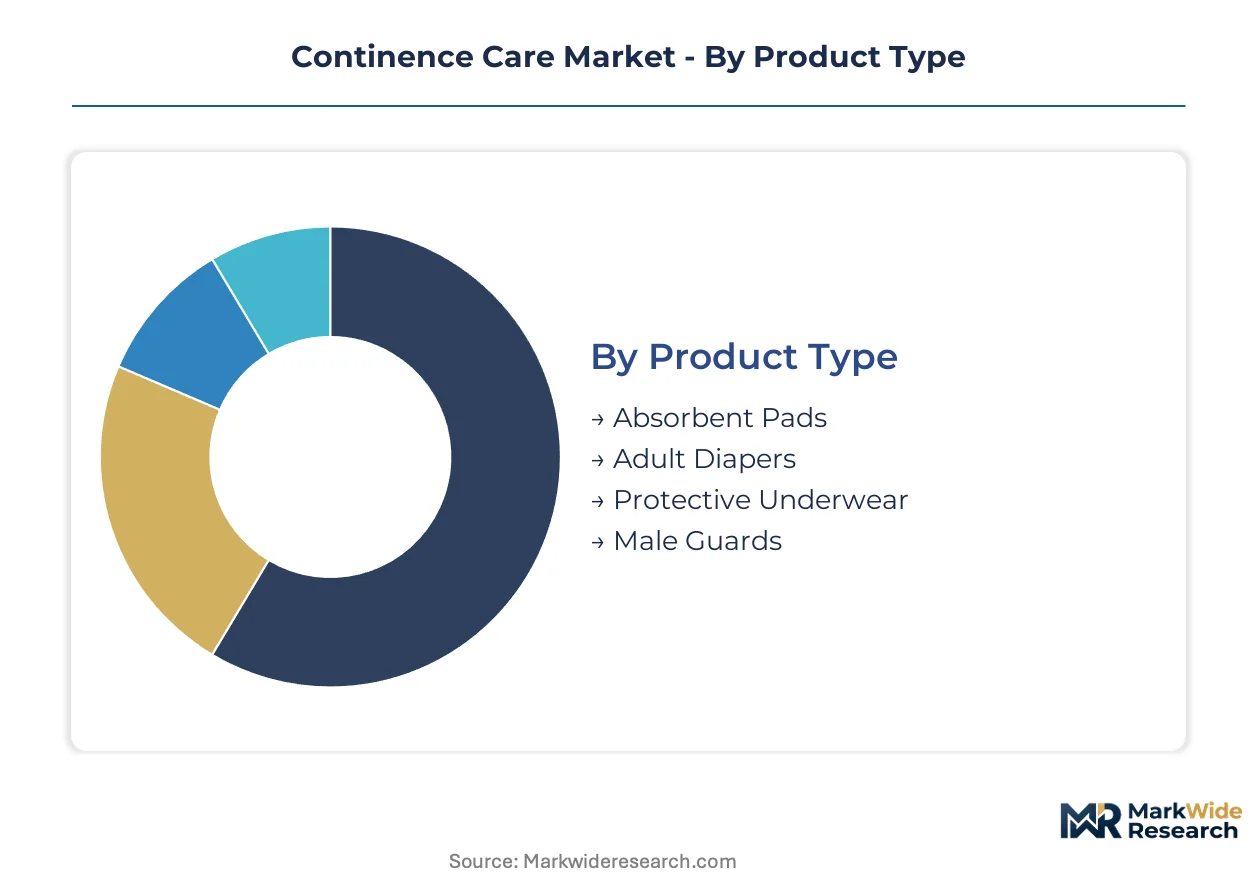
Continence care procurement patterns diverge sharply across patient mobility, care setting, and reimbursement channel. Manufacturers must align polymer specifications and packaging formats to distinct margin pools rather than treating incontinence as a uniform condition.
Product Type:
Premium fluid-retention tiers capture the highest per-unit margins, though volume concentrates in institutional formats with lower price points.
- Adult Diapers:These products integrate superabsorbent polymer cores with acquisition distribution layers rated for multiple voiding episodes. Demand concentrates in nursing homes and long-term care facilities across Germany, where statutory health insurance reimbursement favors bulk procurement of high-capacity formats over frequent change protocols.
- Protective Underwear:Designed for ambulatory users with elasticized waistbands and discreet profiles mimicking conventional undergarments. Post-surgical patients in Scandinavian homecare programs drive uptake, motivated by workplace reintegration and self-managed dignity rather than caregiver dependency.
- Absorbent Pads:Rectangular or contoured inserts for use with mesh pants or standard underwear, common in light-to-moderate incontinence management.
- Male Guards:Anatomically shaped pouches targeting post-prostate surgery patients with targeted absorption zones.
Adult diapers hold installed capacity. Protective underwear is rotating up the share rankings.
End User:
Reimbursement mechanism determines pricing power, with direct-to-patient channels commanding premium positioning over institutional contracting.
- Homecare Providers:These organizations manage community-based continence care through scheduled delivery and remote monitoring integration. Germany's Diakonie and Caritas networks specify dermatological safety certifications, filtering supplier pools to polymer engineers with REACH-compliant formulation documentation.
- Healthcare Facilities:Acute hospitals and skilled nursing facilities prioritize total cost of care through extended-wear specifications and reduced change frequency. FDA 510(k) clearance for novel adhesive interfaces creates procurement friction, extending vendor qualification timelines.
- Individuals:Direct retail purchasers seeking discretion through pharmacy or e-commerce channels.
- Rehabilitation Centers:Transitional care settings managing post-stroke and spinal cord injury patients with variable mobility trajectories.
Healthcare facilities hold installed capacity. Homecare providers are rotating up the share rankings.
Distribution Channel:
Channel concentration shapes working capital requirements, with direct hospital contracting compressing distributor margins while retail pharmacy sustains brand premiums.
- Hospitals:Integrated health networks negotiate volume guarantees for standardized absorbency specifications, bypassing traditional medical supply wholesalers. Germany's statutory health insurance procurement centralization rewards scale and certification depth over brand recognition.
- Online Stores:Direct-to-patient subscription models with predictive replenishment algorithms. Scandinavian dementia care pilots embed moisture sensors transmitting saturation data to caregiver applications, enabling predictive change scheduling.
- Pharmacies:Community dispensaries with pharmacist consultation for product fitting and skin health guidance.
- Supermarkets:Mass retail channels with economy-tier positioning and minimal clinical positioning.
Hospitals hold installed capacity. Online stores are rotating up the share rankings.
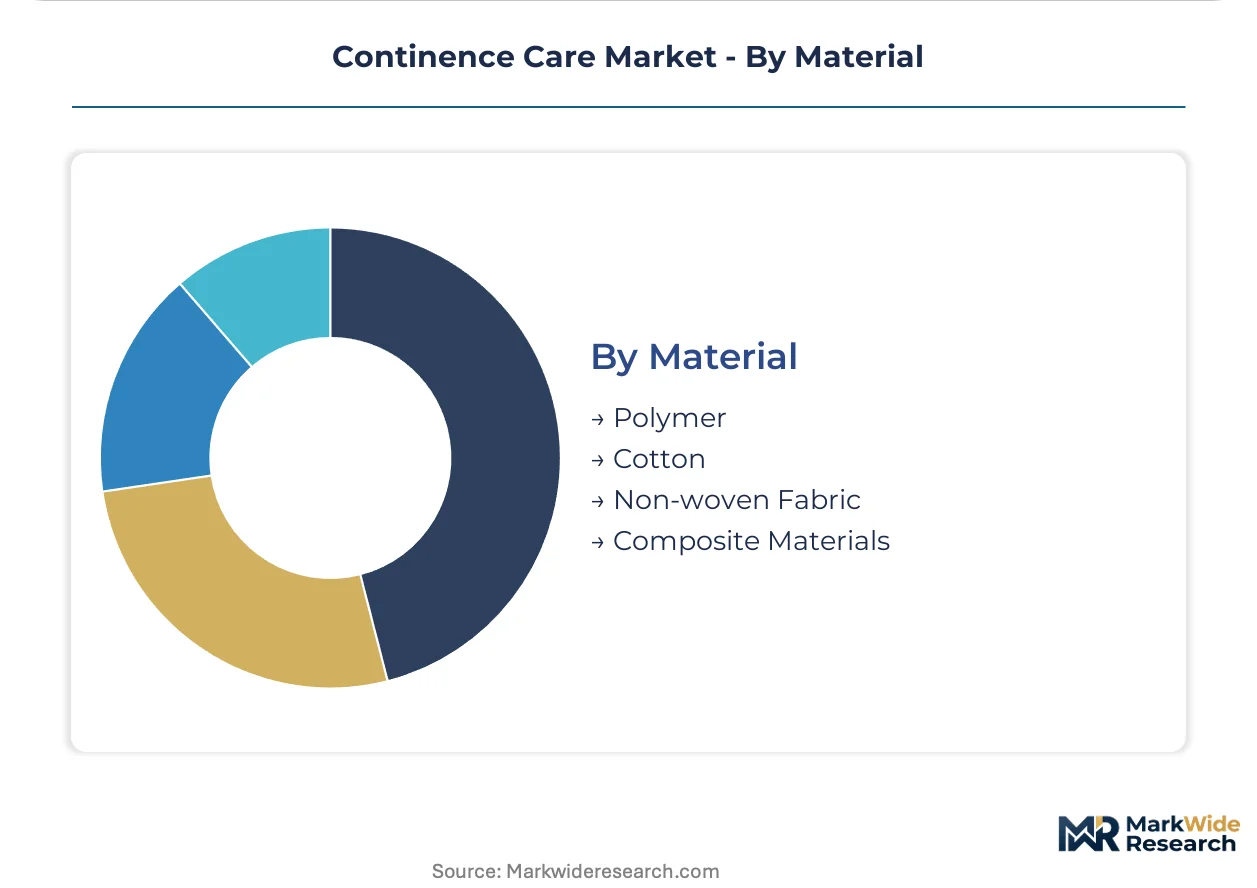
Material:
Polymer chemistry investments separate premium positioning from commodity competition, with biocompatibility certification creating tiered supplier access.
- Polymer:Superabsorbent acrylic acid derivatives forming hydrogel matrices with fluid retention capacities exceeding 50 times dry weight. EU MDR biocompatibility mandates for therapeutic skin claims force manufacturers to upgrade testing protocols, creating demand for certified premium products.
- Composite Materials:Layered constructions combining polymer cores with breathable backsheet films and pH-buffering top layers. EPA state-level waste authority scrutiny of disposal pathways pressures manufacturers toward biodegradable composite research.
- Cotton:Natural fiber alternatives for eczema-prone or post-radiation patients with heightened dermatological sensitivity.
- Non-woven Fabric:Spunbond or meltblown acquisition layers managing fluid distribution and surface dryness.
Polymer holds installed capacity. Composite materials are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Superabsorbent polymer supply chains concentrate in East Asian chemical clusters, yet demand-side procurement power sits with European reimbursement authorities and North American integrated health networks. Germany's statutory health insurance framework and the United States' Medicare Advantage programs shape volume allocation across premium and economy tiers. Regional regulatory divergence on biocompatibility certification and extended producer responsibility creates compliance moats for manufacturers with multi-jurisdictional testing infrastructure.
Germany
Aging demographics and explicit statutory health insurance coverage for advanced continence products drive premium uptake among homecare providers. The EU Medical Device Regulation mandates notified body certification for absorbent devices claiming therapeutic skin benefits, filtering supplier pools to polymer engineers with REACH-compliant documentation. Industrial concentration clusters in North Rhine-Westphalia, where procurement centralization at insurer level rewards scale and certification depth over brand recognition.
United States
Medicare Advantage expansion and direct contracting between integrated health networks and manufacturers compress distributor intermediation. The FDA regulates continence products as Class I or II medical devices, mandating 510(k) clearance for novel polymer formulations and adhesive interfaces. Manufacturing and distribution hubs concentrate in the Midwest corridor, where hospital system volume guarantees for standardized absorbency specifications bypass traditional medical supply wholesalers.
Japan
Super-aging society demographics and long-term care insurance reimbursement sustain demand for high-capacity adult diapers in institutional settings. The Ministry of Economy, Trade and Industry promotes domestic polymer innovation through R&D subsidies targeting extended-wear performance. Production and research clusters concentrate in the Kansai region around Osaka, where textile-to-medical device supply chains support rapid prototyping of dermatologically tested composite materials.
China
Domestic superabsorbent polymer production capacity expansion reduces import dependency for regional manufacturers serving Southeast Asian export markets. The National Medical Products Administration tightens biocompatibility documentation requirements for imported absorbent devices under revised medical device classification rules. Chemical engineering clusters in the Yangtze River Delta dominate acrylic acid derivative production, creating geographic risk concentration for European and North American manufacturers without captive supply agreements.
United Kingdom
Integrated care systems consolidate continence product procurement across former clinical commissioning group boundaries, favoring suppliers with national distribution infrastructure. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulation with EU MDR standards to maintain market access continuity. Demand concentration sits in London and the Southeast, where aging population density and private-pay retail channels sustain premium protective underwear uptake among ambulatory users.
Continence Care Market Vendor Landscape
Concentration sits with diversified hygiene conglomerates and specialized medical device manufacturers competing across distinct certification and channel tiers. Three to five multinational groups capture institutional volume through direct health network contracts, while mid-tier regional suppliers serve price-sensitive retail segments. Strategic archetypes include polymer engineering specialists with in-house toxicology capabilities, pulp-to-retail integrated conglomerates with European retail channel dominance, and North American institutional suppliers with Medicare contracting expertise. Competitive moves center on dermatological testing capacity expansion and biodegradable material research partnerships responding to EPA state-level waste authority scrutiny.
Among Scandinavian and European medical device specialists, Coloplast Group and Essity AB occupy positions representing polymer engineering and supply chain integration archetypes respectively. Coloplast exemplifies the hydrophilic polymer engineering specialist tier with extended-wear catheter and pad system capabilities. Essity anchors the pulp-to-retail integrated model sustaining cost leadership in European retail channels. Kimberly-Clark Corporation represents the North American institutional contracting archetype with direct integrated health network relationships.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| B. Braun Melsungen AG |
| Coloplast Group |
| Procter & Gamble Company |
| Wellspect HealthCare |
| ConvaTec Group Plc |
| Essity AB |
| Ontex Group NV |
| Hollister Incorporated |
| Others |
Supply Flow & Price Mechanics
EU MDR biocompatibility certification gates both supplier qualification and price differentiation simultaneously, creating a dual-filter where polymer engineers with notified body clearance capture premium positioning while uncertified competitors remain trapped in commodity tiers. This regulatory architecture concentrates pricing power among REACH-compliant formulators serving Germany's statutory health insurance procurement centralization.
Pricing Analysis
EU MDR dictates the pricing tier structure across premium, standard, and economy levels, with dermatological safety certification and fluid-retention capacity as the primary price differentiation drivers. Cost compression in economy tiers is intensifying because East Asian polymer imports undercut European manufacturing, though homecare providers show lowest price sensitivity due to reimbursement clarity and total-cost-of-care contracting.
Supply Chain Analysis
China and South Korea anchor bulk superabsorbent polymer production, with acrylic acid derivatives and hydrogel matrices as critical raw material dependencies. Single-source vulnerability concentrates in the Yangtze River Delta chemical clusters, exposing European and North American manufacturers to geographic risk without captive supply agreements. Distribution runs through integrated health network direct contracts in Germany and the United States, bypassing traditional medical supply wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The continence care market functions as a defensive-moat industry where regulatory entrenchment creates durable competitive positions. Certification depth and reimbursement relationships generate switching costs that protect incumbent returns across the analysis window.
For Market Incumbents: Secure dermatological testing capacity expansion to maintain EU MDR clearance advantages against emerging polymer specialists from East Asia. Deepen backward integration into acrylic acid supply through long-term offtake agreements with Yangtze River Delta producers, insulating margins from petrochemical input volatility. For New Entrants and Emerging Players: Lead with sensor-embedded absorbent technology targeting Scandinavian dementia care facilities and German homecare networks, where predictive moisture detection commands subscription pricing. The protective underwear ambulatory segment remains underpenetrated relative to adult diapers, offering white-space entry through discreet, fashion-conscious product design and direct-to-patient e-commerce channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biodegradable composite research programs as EPA state-level waste authority scrutiny intensifies. Target acquisition candidates with in-house toxicology capabilities and REACH-compliant formulation documentation, positioning for extended producer responsibility framework expansion. Monitor compostable polymer performance parity against petroleum-based absorbency as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Notified body clearance for therapeutic skin claims filters supplier pools to premium-tier competitors in Germany. |
| Backward Integration into Polymer Supply | Captive acrylic acid agreements with East Asian producers reduce margin exposure to petrochemical price volatility. |
| Sensor-Embedded Product Development | Wearable moisture detection technology opens subscription revenue streams in Scandinavian nursing home pilots. |
| Biodegradable Composite R&D Partnership | Compostable material science responds to EPA state-level waste authority scrutiny and extended producer responsibility laws. |
| Direct Hospital System Contracting | Volume guarantees with integrated health networks bypass distributor intermediation in the United States and Germany. |
Methodological Framework
Operator-level perspectives from hospital procurement managers, homecare network supply directors, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) filings, EU MDR notified body certification databases, hospital procurement records, and customs trade data. Bottom-up patient population modeling and top-down reimbursement flow analysis provided triangulation across the analysis window.
Sensitivity analysis tested volume and value outputs against variable assumptions across product type, end-user mobility status, distribution channel concentration, and material certification grade. CAGRs derived from segmented demand modeling incorporating aging demographic trajectories, reimbursement policy stability, and polymer innovation adoption curves. Forecast inputs included statutory health insurance coverage expansion rates and REACH chemical restriction compliance cost curves.
Forecasts assume regulatory continuity in EU MDR implementation and EPA state-level waste authority enforcement; material policy shifts would require re-modeling. Specific risks include biodegradability technical ceiling constraints, East Asian supply concentration disruptions, and dermatological testing capacity bottlenecks. Recalibration cycles align with material shifts in reimbursement tier adjustments and extended producer responsibility framework adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Global Bladder Cancer Market
Urology
Disposable Ureteroscope Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
North America Bladder Disorders Market
Urology
Catheter-Associated Urinary Tract Infections Treatment Market
Urology
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market
Urology
Male Urinary Incontinence Market
Urology
Global Castrate Resistant Prostate Cancer Market
Urology
Penile Cancer Market
Urology
Europe Urology Devices Market
Urology
Pyelonephritis Treatment Market
Urology
Ureter Cancer Treatment Market
Urology
Uropathy Treatment Market
Urology
Voiding Cystourethrogram Market
Urology
Global Nephrology and Urology Devices Market
Urology
Complicated Urinary Tract Infections Treatment Market