
 Negative Pressure Wound Therapy Market | 2026-2036
Negative Pressure Wound Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Negative Pressure Wound Therapy Market Analysis
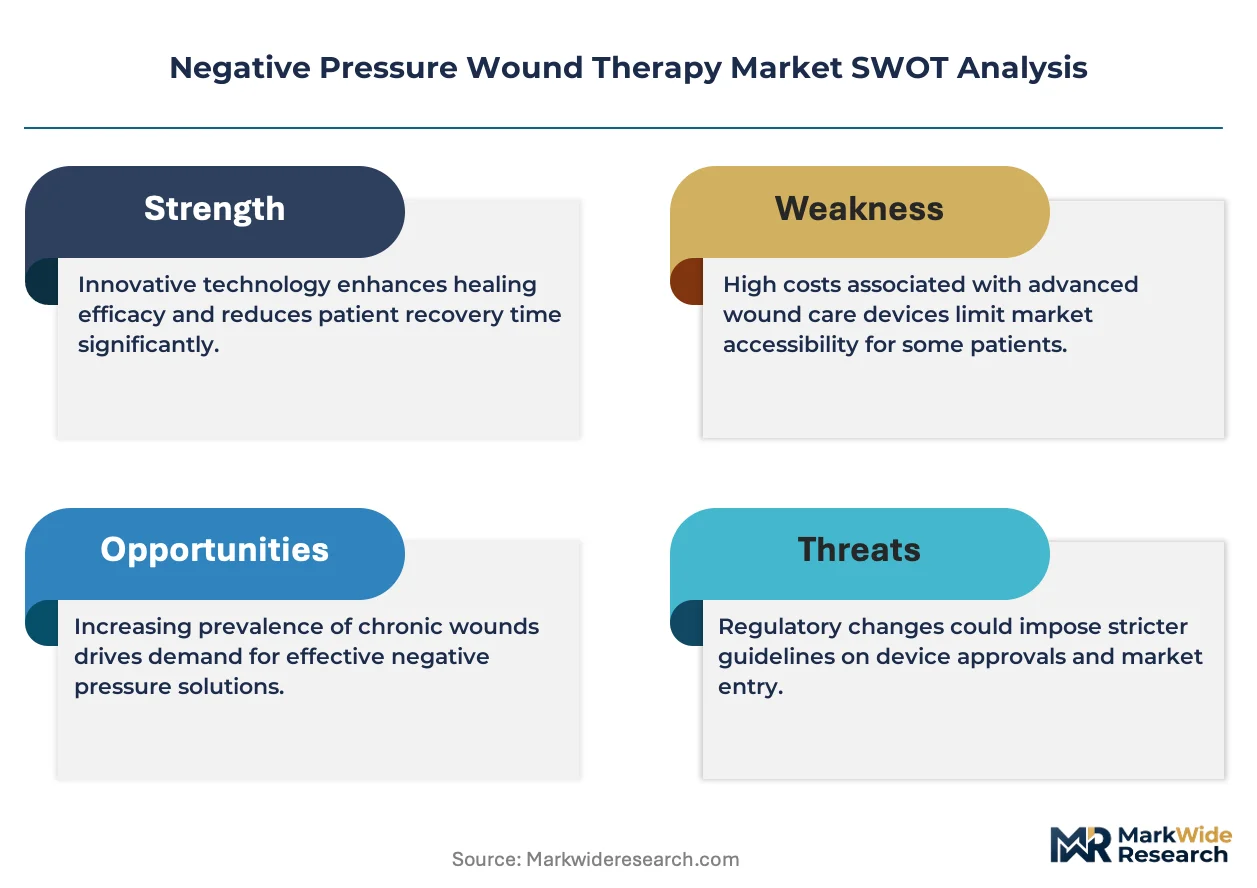
Modular NPWT kit bundling is consolidating buyer choice around all-in-one systems that combine pumps, canisters, and dressings. Smith & Nephew leverages its wound care heritage to anchor premium positioning in hospital accounts. 3M competes through adhesive technology leadership that extends dressing wear time and reduces change frequency. Cardinal Health controls distribution scale across outpatient channels, positioning its private-label alternatives against branded portfolios.
Negative Pressure Wound Therapy applies sub-atmospheric pressure to wound beds through sealed foam or gauze dressings connected to vacuum pumps, typically operating at negative pressures between 50 and 150 mmHg to promote granulation tissue formation and exudate removal. Portable units now lead product type growth as ambulatory and home settings displace fixed installations historically dominant in inpatient wards. Disposable systems within the technology dimension capture expanding margin pools by eliminating capital equipment cycles and reducing infection control overhead for facilities prioritizing single-patient use.
The FDA's Class II 510(k) clearance framework governs pump and dressing safety profiles, while the EU Medical Device Regulation imposes post-market surveillance obligations that extend clinical evidence requirements for CE-marked systems sold across European markets. The Centers for Medicare & Medicaid Services reimbursement coding for hospital outpatient and home health NPWT services directly shapes provider adoption economics in the United States. Stakeholders must monitor evolving pressure injury prevention protocols and value-based wound care contracts that will determine whether portable disposable formats displace reusable capital equipment across acute and post-acute settings.
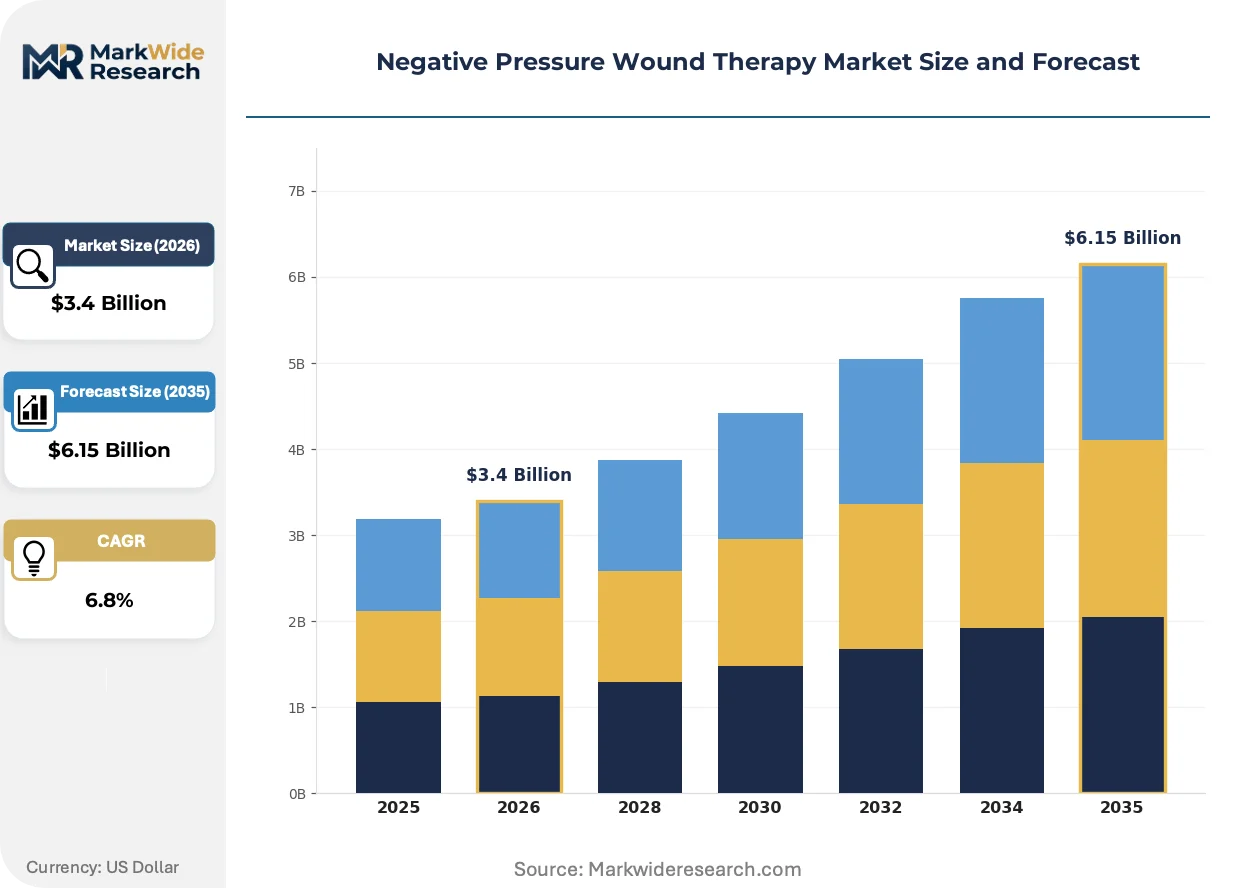
Market Dynamics
Portable NPWT systems are compressing the capital equipment replacement cycle as home healthcare providers and ambulatory surgical centers prioritize mobility over fixed-installation infrastructure. This shift redistributes margin pools from reusable pump manufacturers toward disposable kit suppliers and service-oriented rental platforms.
Growth Catalysts
- CMS Reimbursement Expansion:The Centers for Medicare & Medicaid Services maintains distinct billing codes for hospital outpatient and home health NPWT services, lowering provider adoption barriers across post-acute settings.
- Chronic Wound Prevalence:Rising diabetes-related ulcer incidence and venous insufficiency cases in the United States sustain clinical demand for advanced wound management protocols.
- Foam Dressing Innovation:Reticulated polyurethane foams with improved exudate wicking properties extend wear time between dressing changes, reducing nursing labor costs.
Market Restraints
- Silicone Adhesive Input Costs:Medical-grade silicone supply concentration in Germany and Japan creates pricing volatility for hydrocolloid and semi-permeable dressing layers.
- EU MDR Compliance Burden:The European Union Medical Device Regulation imposes extended clinical evidence requirements and notified body capacity constraints that delay CE-marked product launches.
- Low-Tech Substitutes:Advanced moist wound healing dressings without negative pressure functionality compete for cost-conscious payers in developing markets.
Strategic Opportunities
- Rural Home Health Penetration:Underserved counties in Texas, Mississippi, and rural Appalachia lack consistent wound care specialist access, creating white space for telemedicine-integrated NPWT rental services.
- Pediatric Burn Applications:Modified negative pressure systems for partial-thickness burns in children represent an emerging indication with limited specialized competition.
- IRA Hospital Infrastructure Funding:Inflation Reduction Act provisions for rural hospital capital improvements may subsidize NPWT device acquisition in critical access facilities.
Industry Challenges
- Wound Care Specialist Shortage:Certified wound ostomy continence nurses remain concentrated in urban academic medical centers, limiting protocol standardization in community hospitals.
- Legacy EHR Integration:Proprietary pump data formats from incumbent manufacturers resist interoperability with Epic and Cerner documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Negative Pressure Wound Therapy Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Fixed Units, Accessories, Dressings End User: Hospitals, Home Healthcare, Outpatient Clinics, Rehabilitation Centers Application: Chronic Wounds, Surgical Wounds, Traumatic Wounds, Burns Technology: Active Models, Disposable Systems, Automated Systems, Manual Systems |
| Companies Covered | Mölnlycke Health Care, 3M, Smith & Nephew, DeRoyal, Medela, Solventum, ConvaTec Group, Talley Group, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Negative Pressure Wound Therapy Market Emerging Trajectories
NPWT technology is fragmenting into modality-specific formats as manufacturers optimize for care setting rather than pursuing universal platform dominance. This specialization accelerates regulatory pathway diversification and complicates cross-portfolio procurement for integrated health systems.
Smart pump connectivity is converging with remote patient monitoring infrastructure. Bluetooth-enabled vacuum units transmit pressure adherence data to cloud dashboards, enabling home health agencies to intervene before dressing failures occur. Hospital systems in Florida and Arizona are deploying these connected systems for high-risk diabetic foot ulcer patients, compressing emergency department revisit rates and shifting accountability to device manufacturers for outcomes.
The FDA's 510(k) substantial equivalence pathway for NPWT pumps faces scrutiny as the agency demands more robust biocompatibility data for novel dressing materials. Manufacturers submitting polymer foam innovations now encounter extended review timelines compared to predicate devices. Small-to-mid-size entrants without established predicate relationships are pivoting toward the de novo classification route, accepting longer initial clearance timelines for subsequent competitive insulation.
Hospital purchasing committees are consolidating vendor relationships through single-source NPWT contracts that bundle pumps, disposables, and clinical training. This concentration disadvantages point-solution suppliers and elevates full-service providers with field nursing support capabilities. The trend is most pronounced in California and New York health systems pursuing value-based wound care bundled payments.
Negative Pressure Wound Therapy Market Segmentation
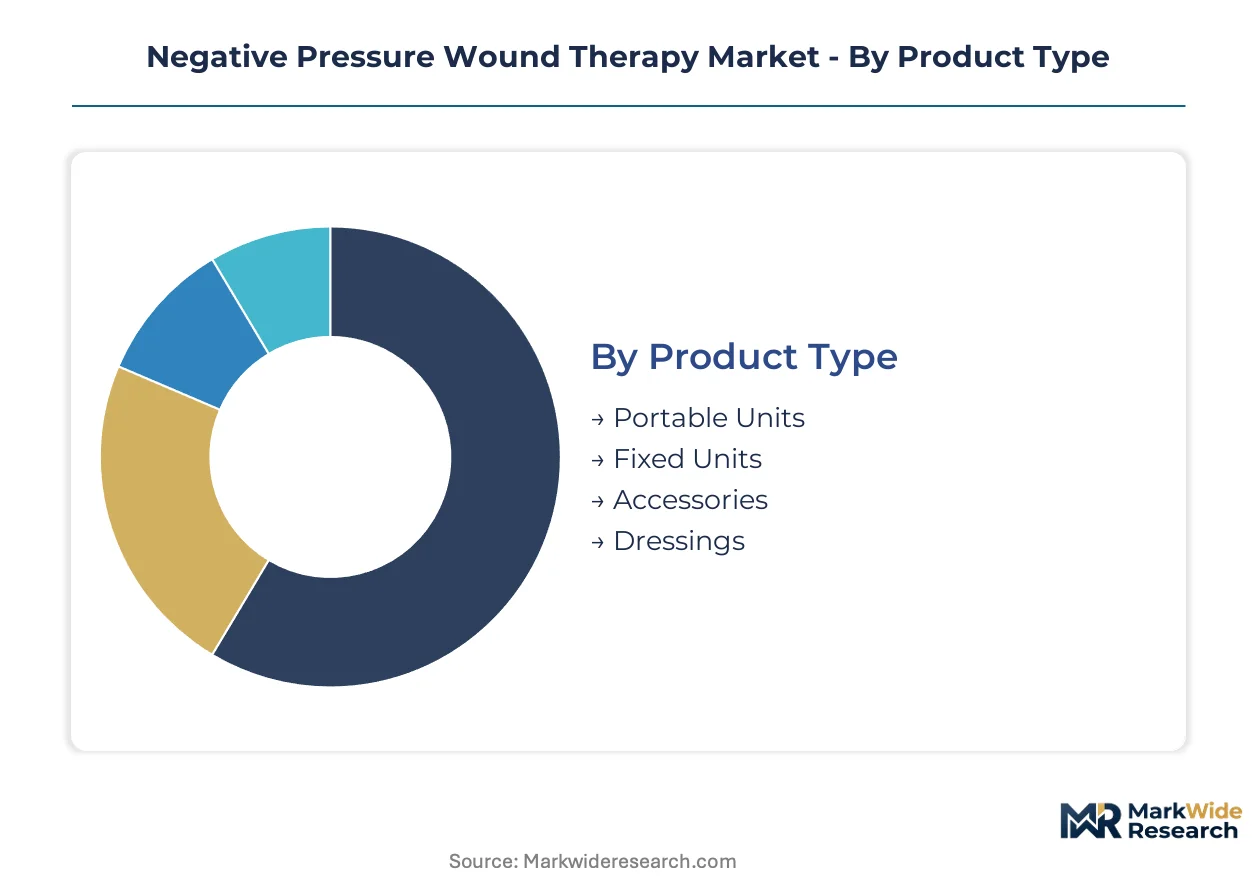
NPWT market segmentation reveals how capital equipment cycles, care setting migration, and reimbursement coding reshape procurement patterns across product configurations and clinical applications. Understanding these segment boundaries enables suppliers to align R&D investment with the highest-velocity upgrade pathways.
Product Type:
Replacement cycles accelerate as facilities abandon fixed-installation infrastructure for mobile platforms that support ambulatory revenue capture.
- Portable Units:Battery-powered vacuum pumps weighing under 3 pounds enable continuous therapy during patient transport and home discharge. Demand concentrates in United States home health agencies serving high-acuity wound patients in rural counties where specialist access is limited.
- Fixed Units:Wall-mounted or cart-based systems with higher suction capacity serve intensive care units and operating rooms for complex debridement procedures. Hospitals in California and Texas retain these installations for surgical suites despite ambulatory migration trends.
- Accessories:Tubing sets, connectors, and carrying cases extend system functionality and generate recurring revenue streams.
- Dressings:Reticulated polyurethane foam and gauze variants interface directly with wound beds and require scheduled replacement.
Portable units sit at the top of the volume ranking, with accessories climbing the fastest as disposable attach rates rise.
End User:
Procurement authority shifts from capital committees to clinical service line managers as payment models reward episode-based wound outcomes.
- Hospitals:Academic medical centers and community hospitals maintain centralized NPWT fleets for inpatient surgical and trauma services. United States facilities in Florida and Arizona deploy connected pumps for diabetic foot ulcer protocols to reduce readmission penalties.
- Home Healthcare:Skilled nursing agencies rent portable systems for post-acute wound management under CMS home health prospective payment. Rural counties in Mississippi and Appalachia represent underserved expansion territory.
- Outpatient Clinics:Ambulatory surgical centers and wound care clinics prioritize single-use disposable systems to eliminate sterilization overhead.
- Rehabilitation Centers:Long-term acute care hospitals and inpatient rehabilitation facilities utilize NPWT for pressure injury prevention in immobile patient populations.
Home healthcare sits at the top of the volume ranking, with outpatient clinics expanding most quickly as site-of-service payment differentials widen.
Application:
Clinical evidence requirements intensify for indications beyond diabetic foot ulcers as FDA demands biocompatibility data for novel dressing materials.
- Chronic Wounds:Venous leg ulcers, diabetic foot ulcers, and pressure injuries constitute the primary reimbursed indication category. United States Medicare coverage determinations favor NPWT for Wagner grade 3 and 4 diabetic foot lesions.
- Surgical Wounds:Closed incision management applications expand as orthopedic and cardiothoracic programs adopt prophylactic NPWT for high-risk closures.
- Traumatic Wounds:Combat casualty care and civilian trauma centers utilize NPWT for temporary wound closure and exudate control.
- Burns:Partial-thickness thermal injuries in pediatric and adult populations represent an emerging off-label application with limited specialized device competition.
Chronic wounds sit at the top of the volume ranking, with burns gaining share fastest as modified systems enter pediatric protocols.
Technology:
Margin pools redistribute toward single-patient-use formats that eliminate capital depreciation and infection control compliance costs.
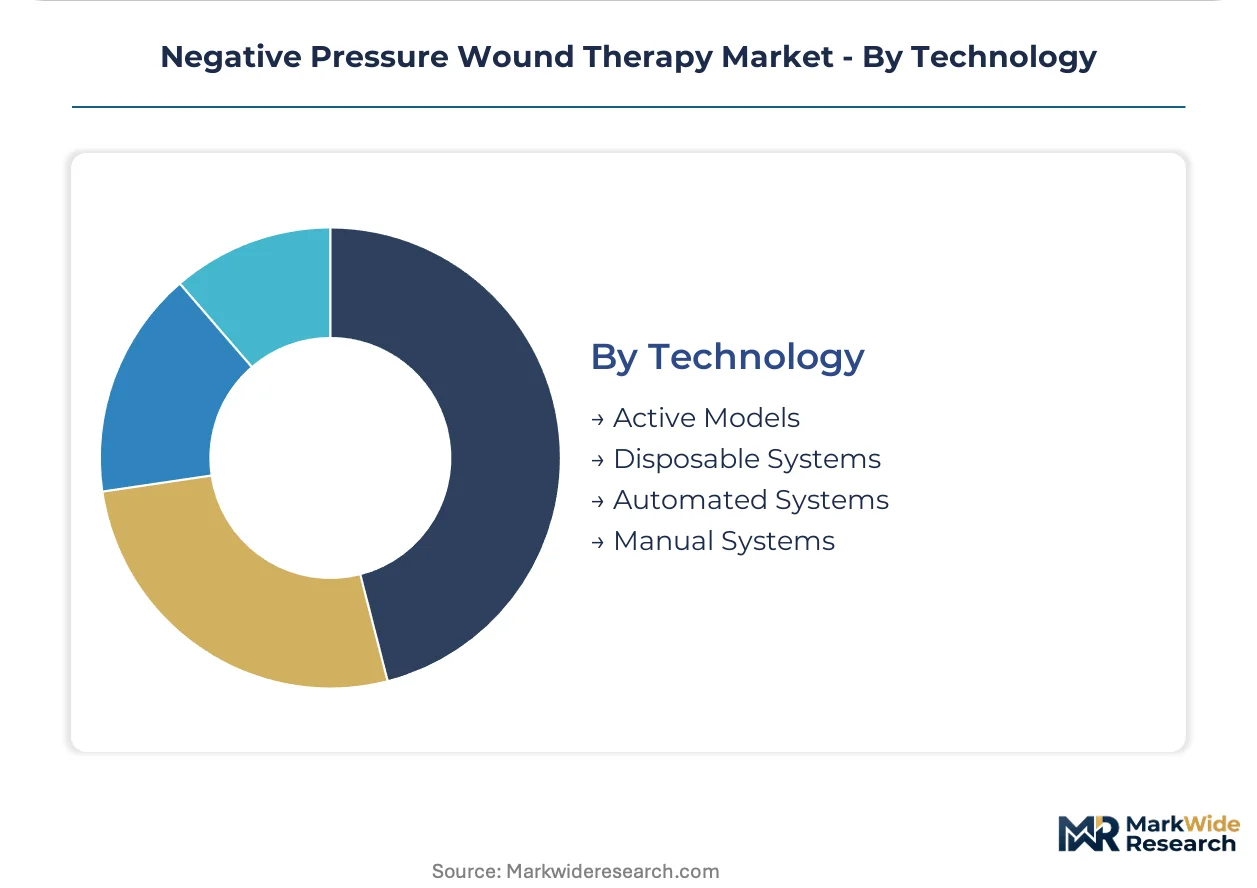
- Active Models:Electric pump systems with continuous or intermittent pressure modulation dominate hospital and home care settings. United States providers favor these for reliable negative pressure maintenance across extended wear periods.
- Disposable Systems:Mechanical spring or battery-integrated single-use devices eliminate return logistics and cross-contamination risk. Outpatient clinics in California and New York health systems adopt these for value-based wound care contracts.
- Automated Systems:Pressure-sensing pumps with feedback algorithms adjust suction in response to leak detection or canister fill levels.
- Manual Systems:Hand-operated or gravity-assisted negative pressure devices serve resource-limited settings with intermittent power availability.
Active models sit at the top of the volume ranking, with disposable systems climbing the fastest as health systems consolidate vendor relationships around full-service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Negative Pressure Wound Therapy industry traces its clinical roots to United States academic medical centers that pioneered vacuum-assisted closure protocols in the 1990s. This foundation established reimbursement infrastructure and regulatory templates subsequently adopted across developed markets. Geographic expansion now follows chronic wound epidemiology and home healthcare payment reform trajectories.
United States
Diabetic foot ulcer prevalence and Medicare reimbursement coding sustain the largest national NPWT consumption base. The FDA's 510(k) clearance pathway shapes product innovation timelines for pump and dressing manufacturers. Hospital systems in Florida and Arizona deploy connected portable systems for high-risk diabetic populations to reduce emergency department revisit rates.
Germany
Medical-grade silicone supply concentration supports hydrocolloid dressing production for European export markets. The EU Medical Device Regulation imposes post-market surveillance obligations that extend clinical evidence requirements for CE-marked systems. Industrial clusters in Baden-Württemberg host specialized polymer foam fabricators serving NPWT kit assemblers.
Japan
Aging demographics and pressure injury prevention protocols drive institutional adoption in long-term care facilities. The PMDA's pharmaceutical and medical device agency governs safety profiles for electric pump systems entering the market. Tokyo-based wound care specialists influence regional protocol standardization across East Asian academic medical centers.
United Kingdom
NHS value-based wound care contracts consolidate procurement around full-service providers with field nursing support. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining national approval pathways. London and Southeast England health systems lead adoption of disposable single-patient-use formats in outpatient settings.
China
Rising diabetes prevalence and hospital infrastructure investment expand addressable demand for advanced wound management. The NMPA's medical device registration requirements govern import and domestic manufacturing compliance for active pump systems. Yangtze River Delta medical device clusters incubate local dressing material suppliers targeting price-sensitive provincial hospital procurement.
Negative Pressure Wound Therapy Market Vendor Landscape
The competitive structure tilts toward diversified medical device conglomerates with wound care heritage and adhesive technology capabilities. Market concentration remains moderate with tiered participation across premium branded portfolios and private-label alternatives. Three strategic archetypes dominate: full-service providers bundling pumps, disposables, and clinical training; adhesive technology specialists leveraging materials science for extended dressing wear time; and distribution-scale operators controlling outpatient channel access. Competitive moves center on single-source contract consolidation and disposable system innovation to capture recurring revenue streams.
Among diversified wound care conglomerates, Smith & Nephew and 3M occupy positions anchored by decades of clinical presence and materials science investment. Mölnlycke Health Care represents the specialized European fabricator archetype with concentrated expertise in advanced dressing systems. Cardinal Health exemplifies distribution-scale competitive positioning through private-label alternatives and outpatient channel control. These three company types collectively illustrate how heritage, technology, and logistics capabilities segment strategic optionality in NPWT market participation.
| Leading Market Players |
|---|
| Mölnlycke Health Care |
| 3M |
| Smith & Nephew |
| DeRoyal |
| Medela |
| Solventum |
| ConvaTec Group |
| Talley Group |
| Cardinal Health |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up wound care specialists have consolidated dressing material suppliers across Germany and Japan, concentrating ownership of medical-grade silicone feedstocks and compressing procurement leverage for mid-tier pump assemblers while enforcing disciplined price bands across hospital system contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Smith & Nephew's connected pump systems from 3M's adhesive-optimized dressings and Cardinal Health's private-label alternatives. Price differentiation hinges on FDA 510(k) clearance tier and field nursing support bundling. Pricing pressure stems from CMS reimbursement compression on home health NPWT services. Outpatient clinics exhibit highest price sensitivity; academic medical centers prioritize clinical outcomes over unit economics.
Supply Chain Analysis
Freight cost volatility from Baden-Württemberg polymer foam fabricators to United States kit assemblers has compressed landed margins for European-sourced dressing materials. Supply concentrates in Germany for silicone adhesives, Japan for precision pump components, and China for battery cells. Raw material dependencies include reticulated polyurethane, medical-grade silicone, and lithium-ion power cells. Single-source vulnerability runs through German silicone concentration. Distribution runs through Cardinal Health's outpatient channel network and hospital GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through disposable system adoption that eliminates capital equipment depreciation and captures recurring revenue from dressing replenishment cycles.
For Market Incumbents: Extend field nursing support capabilities into rural home health territories to defend against telemedicine-integrated rental platforms. Deepen backward integration into foam fabrication by acquiring Baden-Württemberg polymer specialists. Lock in hospital system single-source contracts before value-based wound care bundled payments consolidate procurement authority. For New Entrants and Emerging Players: The premium-economy price gap in pediatric burn applications offers white-space entry with modified negative pressure systems. Rural counties in Mississippi and Appalachia lack wound specialist access. Target ambulatory surgical centers with disposable mechanical systems that eliminate sterilization overhead and capital committee approval cycles. For Investors and Strategic Acquirers: Diversified medical device conglomerates with wound care heritage are the most active acquirers in this space. Five-to-ten year viability favors targets with FDA 510(k) predicate relationships and connected pump data platforms. Acquisition target archetype: mid-cap disposable system innovators with CE marking but limited United States market presence. Watch FDA de novo classification volume as inflection indicator for competitive insulation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks European hospital procurement for disposable system entrants. |
| Hospital System Partnership | Florida and Arizona health systems deploy connected pumps to reduce diabetic foot ulcer readmissions. |
| Software Companion Development | Bluetooth-enabled pressure adherence dashboards compress emergency department revisit rates for home health agencies. |
| Reimbursement Strategy | CMS coding alignment determines provider adoption economics across post-acute settings. |
| FDA Submission | 510(k) substantial equivalence demands robust biocompatibility data for novel foam innovations. |
Methodological Framework
Multiple input streams — wound care clinician interviews, hospital purchasing committee discussions, biomedical engineer consultations, GPO contracts manager dialogues — were reconciled against FDA 510(k) filing databases, CMS Medicare reimbursement coding records, hospital procurement databases, and EU MDR notified body submission logs. Bottom-up demand modeling from county-level diabetic foot ulcer prevalence triangulated with top-down market sizing from pump manufacturer revenue disclosures.
Data-stream reconciliation across product type, end user, application, technology, and regional regulatory cluster dimensions generated volume and value outputs over the projection horizon. CAGRs derived from segment-level growth rate convergence analysis. Forecast inputs incorporated CMS reimbursement trajectory assumptions and EU MDR compliance timeline constraints for CE-marked system launches.
Caveats apply where FDA review timeline extensions for novel dressing materials or EU notified body capacity constraints could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Patch Based Wound Healing Products Market
Wound Care
Wound Healing Supplement Market
Wound Care
Venous Skin Ulcer Treatment Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Single-Use Negative Pressure Wound Therapy Devices Market
Wound Care
Wound Closure Devices Market
Wound Care
Wound Evacuators Market
Wound Care
US Wound Care Management Devices Market
Wound Care
South Korea Wound Care Management Market
Wound Care
Global Antimicrobial Dressings Market
Wound Care
Vascular Dressings Market
Wound Care
Global Wound Irrigation System Market
Wound Care
Animal Wound Care Market
Wound Care
Bioactive Wound Management Market
Wound Care
Global Compression Bandages Market