
 Brazil Wound Care Management Devices Market | 2026-2036
Brazil Wound Care Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Wound Care Management Devices Market Outlook
ANVISA's streamlined medical device registration pathways is recalibrating procurement priorities across Brazilian healthcare networks. B. Braun Melsungen AG leverages its established manufacturing footprint in the country to sustain competitive supply continuity. Mölnlycke Health Care anchors its position through advanced dressing portfolios tailored to chronic wound protocols. Smith & Nephew differentiates via negative pressure wound therapy systems optimized for hospital and home care transitions.
Wound care management devices encompass dressings, closure systems, and therapeutic apparatus engineered to protect tissue, manage exudate, and accelerate healing through controlled moisture balance and antimicrobial action; these products typically incorporate hydrocolloid, alginate, or foam substrates with pore sizes calibrated between 50 and 800 microns for optimal vapor transmission. Advanced dressings dominate value capture due to premium pricing of antimicrobial and bioactive variants, while negative pressure wound therapy represents the fastest-expanding device category as Brazilian clinics adopt portable systems for outpatient chronic wound management. Surgical sutures constitute a mature, volume-driven segment where margin pools favor synthetic absorbable materials over natural alternatives.
ANVISA governs product registration, clinical evidence requirements, and post-market surveillance for all wound care devices commercialized in Brazil, directly influencing time-to-market and compliance costs for manufacturers. The Brazilian Health Regulatory Agency's alignment with international harmonization initiatives, alongside mandatory reporting standards under the National Health Surveillance System, elevates quality benchmarks for both imported and domestically produced devices. Stakeholders must monitor evolving reimbursement classifications under the Unified Health System to anticipate volume shifts between hospital procurement and patient-funded channels.
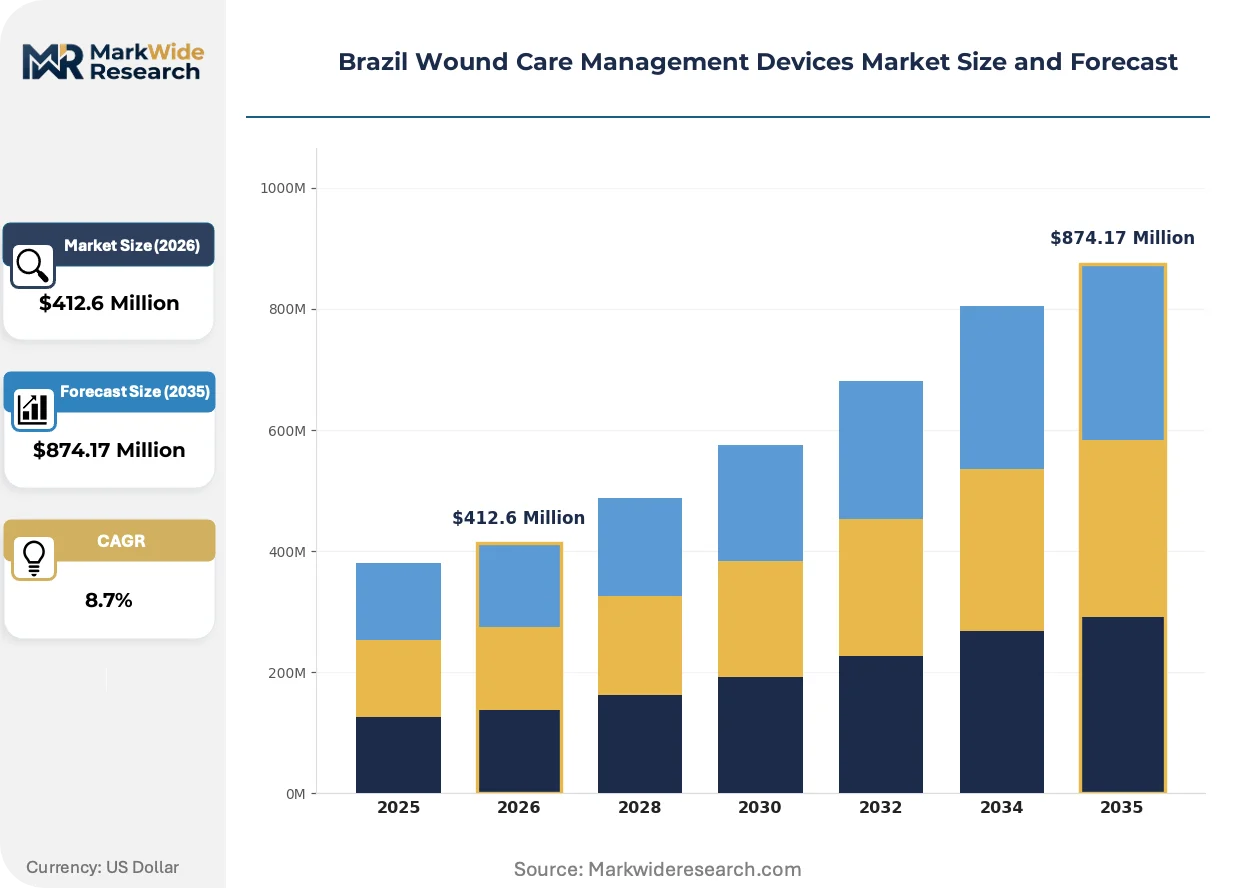
Market Dynamics
ANVISA's streamlined registration pathways are compressing time-to-market for advanced wound care devices while Brazilian public hospitals accelerate procurement of portable negative pressure systems for outpatient chronic wound protocols.
Growth Catalysts
- ANVISA Harmonization:The Brazilian Health Regulatory Agency's alignment with international standards reduces clinical evidence duplication for imported devices. Foreign manufacturers now navigate faster pre-market approval timelines.
- Chronic Disease Prevalence:Brazil's diabetic population drives sustained demand for advanced dressings and therapeutic apparatus. Hospital networks in São Paulo's metropolitan corridor prioritize moisture-balancing substrates for pressure ulcer management.
- Synthetic Absorbable Sutures:Operating rooms across Brazilian states are displacing natural catgut materials with polymer-based alternatives. This material shift elevates average selling prices in the mature surgical closure segment.
Market Restraints
- Import Dependency:Brazil's wound care device supply concentrates among European and North American manufacturers. Currency volatility elevates landed costs for hydrocolloid and alginate raw materials.
- Reimbursement Compression:The Unified Health System's fixed payment schedules for standard dressings limit margin expansion. Public procurement favors volume contracts over premium antimicrobial variants.
- Technical Limitations:Portable negative pressure systems face battery life constraints for rural home care deployment. Clinics in Amazonas and Pará states report equipment downtime during extended patient transport.
Strategic Opportunities
- Northeast Region Penetration:Pernambuco and Ceará healthcare networks remain underpenetrated for advanced wound care relative to Southeast Brazil. Regional distributors can capture first-mover positioning in tertiary hospital procurement.
- Home Care Transition:Post-acute wound management is migrating from hospital wards to patient residences. Disposable negative pressure canisters and simplified dressing protocols enable this channel expansion.
- Bioactive Convergence:Antimicrobial silver ion technology is merging with foam substrate engineering. This convergence creates premium pricing tiers for infected wound protocols in private hospital networks.
Industry Challenges
- Specialized Nursing Shortage:Negative pressure wound therapy requires certified wound care nurses for safe patient transition. Brazilian nursing schools lack dedicated curricula for device-operated chronic wound management.
- ANVISA Post-Market Surveillance:Mandatory adverse event reporting under the National Health Surveillance System demands dedicated regulatory affairs personnel. Mid-size distributors struggle with compliance infrastructure costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Wound Care Management Devices Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Advanced Dressings, Surgical Sutures, Wound Closure Strips, Negative Pressure Wound Therapy End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Distribution Channel: Online, Retail Pharmacies, Medical Supply Stores, Direct Sales Application: Chronic Wounds, Surgical Wounds, Burns, Ulcers |
| Companies Covered | B. Braun Melsungen AG, Medtronic, 3M Company, Mölnlycke Health Care, ConvaTec, Johnson & Johnson, Coloplast, Beiersdorf, Smith & Nephew, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Wound Care Management Devices Market Strategic Shifts
Technological convergence between antimicrobial materials and portable therapeutic systems is redefining competitive positioning across Brazilian wound care procurement channels.
Smart dressing substrates incorporating pH-responsive color indicators are expanding into post-surgical monitoring protocols. São Paulo's private hospital networks deploy these materials for early infection detection in orthopedic recovery wards. This expansion is compressing reliance on scheduled clinical assessments and enabling nurse-staffing optimization.
ANVISA's updated medical device regulations now mandate electronic submission of technical documentation through the unified portal. Manufacturers face compressed response timelines for deficiency corrections during review cycles. Imported negative pressure wound therapy systems encounter accelerated scrutiny for electrical safety certifications under this framework.
Hospital purchasing consortia in Minas Gerais and Rio de Janeiro are consolidating procurement authority for advanced wound care categories. Individual facility autonomy is yielding to centralized tender processes administered by state health secretariats. This concentration is most visible in surgical suture purchasing, where synthetic absorbable materials now flow through single-source agreements covering multiple municipal networks.
Brazil Wound Care Management Devices Market Segmentation
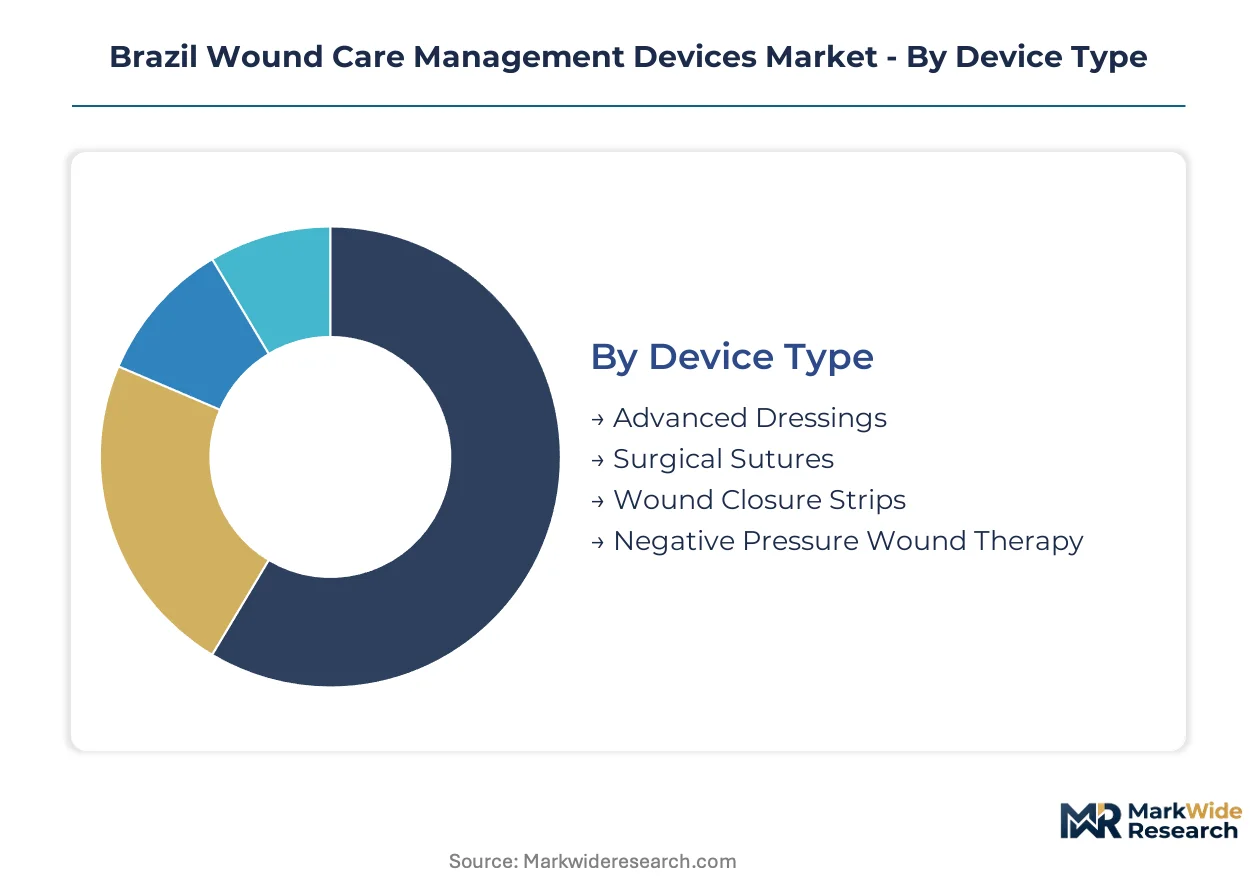
Segmentation reveals how procurement priorities diverge across Brazilian healthcare networks. Device specifications, care settings, and wound severity dictate distinct margin structures and competitive dynamics for manufacturers.
Device Type:
Material engineering and therapeutic mechanism define performance tiers and reimbursement eligibility under ANVISA classifications.
- Advanced Dressings:Hydrocolloid, alginate, and foam substrates with calibrated pore sizes between 50 and 800 microns manage exudate and moisture balance. São Paulo's metropolitan hospitals prioritize antimicrobial silver-ion variants for infected wound protocols, though premium pricing limits penetration in public procurement.
- Negative Pressure Wound Therapy:Portable systems with disposable canisters enable outpatient chronic wound management. Brazilian clinics in Minas Gerais and Rio de Janeiro are accelerating adoption for post-acute transitions, despite battery constraints in rural Amazonas deployments.
- Surgical Sutures:Polymer-based synthetic absorbable materials displace natural catgut in operating rooms, elevating average selling prices in this mature closure segment.
- Wound Closure Strips:Adhesive skin closures for low-tension lacerations and surgical incisions offer cost-efficient alternatives to sutures in emergency departments.
Mature deployment sits with Surgical Sutures. Newer deployment is concentrated in Negative Pressure Wound Therapy.
End User:
Care setting determines device complexity requirements and staffing certification needs across Brazilian states.
- Hospitals:Tertiary facilities in São Paulo's healthcare corridor drive demand for integrated negative pressure systems and bioactive dressings. ANVISA's streamlined registration enables faster technology refresh cycles in these capital-intensive procurement environments.
- Home Care:Simplified dressing protocols and portable therapeutic devices support patient discharge acceleration. Nursing shortages in Pará and Amazonas constrain safe deployment of device-operated wound management in remote municipalities.
- Clinics:Outpatient facilities concentrate volume for standard dressings and closure strips, with procurement flowing through state health secretariat consortia.
- Long-term Care Facilities:Pressure ulcer prevention protocols in geriatric institutions sustain demand for moisture-balancing substrates.
Volume concentration favors Hospitals. Channel expansion is accelerating fastest in Home Care.
Distribution Channel:
Supply chain configuration shapes price transparency and inventory carrying costs for Brazilian healthcare purchasers.
- Direct Sales:Manufacturer representatives negotiate multi-hospital agreements with state purchasing consortia, capturing synthetic suture volume in Minas Gerais and Rio de Janeiro networks.
- Medical Supply Stores:Regional distributors stock advanced dressings for clinic and long-term care procurement in underpenetrated Northeast states.
- Retail Pharmacies:Consumer-facing channels serve patient-funded dressing purchases outside Unified Health System reimbursement.
- Online:E-commerce penetration remains limited for regulated therapeutic devices requiring clinical training.
Consolidated procurement flows through Direct Sales. Fragmented demand channels through Medical Supply Stores.
Application:
Wound etiology determines antimicrobial requirements, dressing change frequency, and total cost of care.
- Chronic Wounds:Diabetic foot ulcers and venous leg ulcers require sustained moisture management and infection control. Brazil's diabetic population sustains recurring demand for advanced dressing portfolios in both public and private networks.
- Surgical Wounds:Post-operative incisions drive synthetic absorbable suture consumption and antimicrobial dressing protocols for infection prevention.
- Ulcers:Pressure ulcers in long-term care and decubitus prevention programs concentrate demand in São Paulo's geriatric facilities.
- Burns:Specialized foam dressings and silver-based materials address thermal injury management in trauma centers.
Established procedure volumes anchor Surgical Wounds. Steepest expansion trajectory appears in Chronic Wounds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's wound care device production concentrates among foreign-owned manufacturing facilities, while consumption spreads unevenly across state healthcare networks. São Paulo's industrial corridor hosts the dominant assembly operations, yet demand penetration lags in northern and northeastern states.
São Paulo
Metropolitan hospitals anchor demand for advanced dressings and negative pressure systems. ANVISA's streamlined registration pathways accelerate technology refresh cycles in this capital-intensive procurement environment. The São Paulo healthcare corridor drives premium product adoption through integrated purchasing consortia.
Minas Gerais
State health secretariat consolidation redirects surgical suture procurement through centralized tender processes. Public hospital networks prioritize synthetic absorbable materials over natural alternatives. Belo Horizonte's tertiary facilities coordinate multi-municipal agreements for wound closure categories.
Rio de Janeiro
Hospital purchasing consortia compress price points for standard dressing categories. The state procurement authority aggregates volume across municipal networks, favoring volume contracts over premium antimicrobial variants. Rio's private hospital segment sustains demand for bioactive dressing portfolios.
Northeast Region
Pernambuco and Ceará healthcare networks remain underpenetrated for advanced wound care relative to Southeast Brazil. Regional distributors capture first-mover positioning in tertiary hospital procurement. Recife's emerging medical device distribution hubs bridge supply gaps for alginate and foam substrates.
Amazonas and Pará
Portable negative pressure systems face battery life constraints for rural home care deployment. Clinics report equipment downtime during extended patient transport across remote municipalities. Manaus-based distributors struggle with inventory carrying costs for hydrocolloid raw materials subject to currency volatility.
Brazil Wound Care Management Devices Market Competitive Environment
The competitive structure tilts toward diversified medical technology conglomerates with established Brazilian manufacturing footprints. Market concentration favors players with integrated supply chains capable of navigating ANVISA's regulatory complexity. Three archetypes dominate: European surgical supply specialists, North American therapeutic device innovators, and diversified healthcare conglomerates with regional production assets. Competitive moves center on manufacturing localization and state-level procurement consortium penetration.
Among European-based specialists, B. Braun Melsungen AG and Mölnlycke Health Care exemplify archetypes with sustained Brazilian market presence. Smith & Nephew represents the therapeutic device innovation vector, occupying a position aligned with negative pressure wound therapy expansion. These three entities anchor the competitive landscape through differentiated regulatory affairs capabilities and state health secretariat relationship networks.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Medtronic |
| 3M Company |
| Mölnlycke Health Care |
| ConvaTec |
| Johnson & Johnson |
| Coloplast |
| Beiersdorf |
| Smith & Nephew |
| Others |
Value Chain & Pricing Dynamics
State health secretariat purchasing consortia in Minas Gerais and Rio de Janeiro command contract-based long-term offtake pricing for synthetic sutures, compressing margin pools for manufacturers lacking volume scale or ANVISA registration speed.
Pricing Analysis
Cost-down pressure on antimicrobial dressings accelerates as the Unified Health System's fixed payment schedules favor standard hydrocolloid variants over silver-ion premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates private hospital bioactive portfolios from public procurement volume contracts and patient-funded retail channels. Price differentiation traces to ANVISA certification tier and geographic delivery cost, with imported negative pressure systems carrying currency-adjusted premiums. Public sector buyers exhibit highest price sensitivity; private tertiary hospitals in São Paulo's corridor demonstrate lowest.
Supply Chain Analysis
ANVISA electrical safety certifications and ISO 13485 quality management standards gate entry for imported negative pressure wound therapy systems, extending approval timelines for manufacturers lacking Brazilian regulatory affairs infrastructure. Manufacturing concentrates in Germany, the United States, and Sweden for advanced dressings and therapeutic apparatus. Raw material dependencies span hydrocolloid polymers, alginate fibers, and medical-grade foam substrates sourced from European chemical specialists. Single-source vulnerability sits with battery cell supply for portable negative pressure devices. Distribution runs through state-level purchasing consortia for hospital networks and regional medical supply distributors for clinic and long-term care procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's streamlined registration pathways and mandatory post-market surveillance under the National Health Surveillance System erect compliance moats that favor established players with dedicated regulatory affairs infrastructure.
For Market Incumbents: To counter reimbursement compression in the Unified Health System's fixed payment schedules, B. Braun Melsungen AG and Mölnlycke Health Care should deepen backward integration into hydrocolloid and alginate raw material production to defend margin structures. Incumbents must also accelerate ANVISA electronic submission capabilities to compress deficiency response timelines and capture state health secretariat tender cycles ahead of slower competitors. For New Entrants and Emerging Players: Underpenetrated tertiary hospital networks in Pernambuco and Ceará present viable first-mover opportunities for regional distributors capable of bridging supply gaps for foam and alginate substrates. New entrants should target home care transition channels with simplified negative pressure canister protocols, leveraging nursing shortage constraints as a service differentiation angle against device-complexity incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap regional distributors with established ANVISA compliance infrastructure and state health secretariat relationships in Brazil's Northeast region. Long-term viability hinges on positioning for chronic wound prevalence expansion tied to Brazil's diabetic population trajectory. Watch for ANVISA adverse event reporting enforcement intensity as an inflection signal for compliance cost escalation and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Acceleration | Electronic submission capabilities capture state tender cycles ahead of slower competitors in Minas Gerais. |
| Backward Integration into Raw Materials | In-house hydrocolloid production defends margins against currency volatility in landed polymer costs. |
| Home Care Protocol Simplification | Disposable canister designs enable nursing shortage-constrained deployments in Amazonas and Pará. |
| Northeast Regional Distribution Buildout | Recife-based hubs bridge supply gaps for underpenetrated Pernambuco and Ceará hospital networks. |
| Post-Market Surveillance Infrastructure | Dedicated regulatory affairs personnel satisfy National Health Surveillance System adverse event mandates. |
Study Parameters
Document review covered ANVISA registration databases, Unified Health System procurement records, and National Health Surveillance System adverse event reports, complemented by interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at device manufacturers. Secondary validation drew from ANVISA technical documentation filings, state health secretariat tender announcements, and import customs records for hydrocolloid and alginate raw materials. Bottom-up demand modeling across device categories triangulated with top-down healthcare expenditure allocation analysis.
Segmentation outputs across device type, end user, distribution channel, and application dimensions were generated through the projection horizon, with CAGRs derived from historical ANVISA approval velocity and chronic wound prevalence trajectories. Forecast inputs incorporated diabetic population growth curves, state health secretariat consolidation patterns, and reimbursement classification shifts under the Unified Health System.
Revisions become necessary when ANVISA regulatory harmonization initiatives stall, currency volatility exceeds historical bands for euro and dollar-denominated imports, or nursing certification programs expand sufficiently to remove home care deployment constraints. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Closure Strips Market
Wound Care
Wound Care Market
Wound Care
Wound Evacuators Market
Wound Care
Asia Pacific Wound Care Biologics Market
Wound Care
Saudi Arabia Wound Care Management Devices Market
Wound Care
Advanced Wound Dressings Market
Wound Care
Pressure Bandages Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Foam Dressing Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
South Korea Wound Care Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
Japan Wound Care Management Devices Market
Wound Care
Single-Use Negative Pressure Wound Therapy Devices Market
Wound Care
Topical Wound Agents Market