
 Global Female Sterilization Devices Market | 2026-2036
Global Female Sterilization Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Female Sterilization Devices Market Analysis
Leasing arrangements for surgical equipment are rewriting capital deployment patterns across sterilization device procurement, enabling smaller facilities to access advanced platforms without full ownership burdens. Hologic leverages its integrated diagnostics-to-surgery portfolio to sustain recurring revenue streams in outpatient settings. Cooper Surgical anchors its position through deep specialization in women's health instrumentation. Cardinal Health competes on distribution density, controlling supply chain reach into mid-tier hospital systems.
Female sterilization devices encompass implantable, mechanical, and energy-based systems designed to achieve permanent tubal occlusion or tubal ligation, typically constructed from titanium, silicone, or polymer composites and deployed via hysteroscopic, laparoscopic, or laparotomy approaches. These devices serve the primary purpose of providing non-reversible contraception through minimally invasive or surgical intervention. Hysteroscopic implants command premium positioning due to their anesthesia-sparing profile and same-day discharge protocols, while electrosurgical devices retain volume leadership in emerging markets where capital equipment reuse optimizes per-procedure economics. Laparoscopic clips represent a maturing margin pool as commoditization pressures intensify among secondary suppliers.
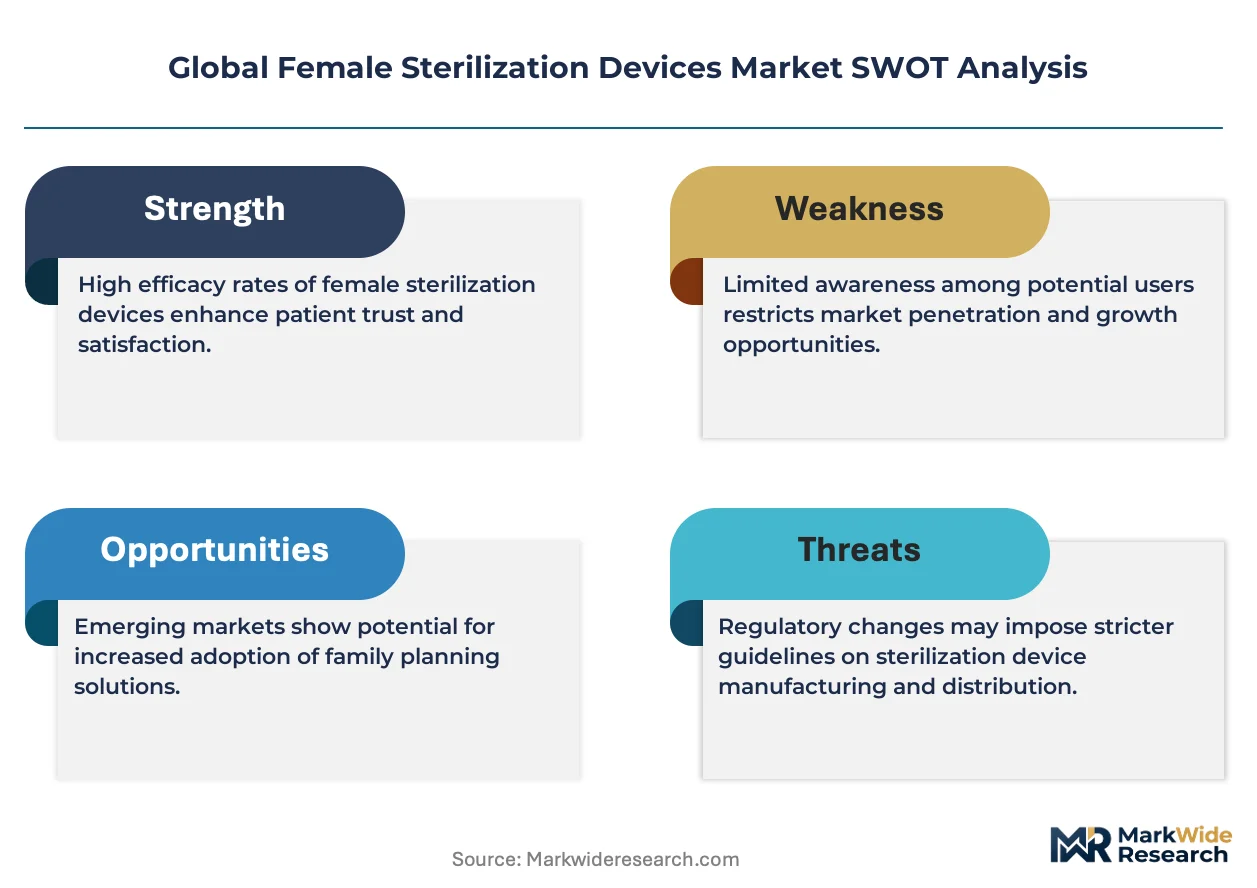
The FDA's premarket notification requirements and the EU MDR's reclassification of permanent implantable devices impose divergent compliance burdens that filter market entrants by certification capacity. WHO prequalification standards and ISO 10993 biocompatibility protocols further stratify product eligibility across public procurement channels. Stakeholders must weigh regulatory capital intensity against the pricing power conferred by hysteroscopic and robotic-assisted technology tiers.
Market Dynamics
The migration from laparoscopic clips toward hysteroscopic implants is redrawing competitive boundaries, as anesthesia-sparing protocols and same-day discharge requirements reshape hospital purchasing criteria.
Growth Catalysts
- EU MDR reclassification:Stricter conformity assessment for permanent implantables is filtering marginal suppliers and concentrating procurement among certified manufacturers.
- Ambulatory surgical centers:United States outpatient facilities are expanding hysteroscopic system deployment to capture reimbursement advantages tied to reduced facility fees.
- Titanium-nickel alloy advances:Improved shape-memory properties in hysteroscopic inserts are expanding eligible patient populations previously excluded by anatomical constraints.
Market Restraints
- Silicone supply concentration:Medical-grade silicone feedstock dependence on German and Japanese chemical suppliers exposes device makers to input cost volatility.
- FDA premarket notification pathway:Extended 510(k) review timelines for permanent implantables are delaying competitive entry and compressing effective patent life.
- Reversible contraception substitution:Long-acting reversible contraceptives are capturing family planning budgets in public health systems across Brazil and Mexico.
Strategic Opportunities
- India's Ayushman Bharat expansion:Government-funded health insurance is creating reimbursed access channels for sterilization procedures previously confined to out-of-pocket payment.
- Robotic-assisted tubal ligation:Convergence of laparoscopic clip systems with robotic surgical platforms is opening premium pricing tiers in integrated US health networks.
- WHO prequalification pathway:Certification alignment with international procurement standards is unlocking volume contracts in sub-Saharan African public health programs.
Industry Challenges
- Hysteroscopic insertion training:Physician credentialing requirements for blind insertion techniques are creating bottlenecks in adoption velocity.
- Biocompatibility testing backlog:ISO 10993-6 implantation study delays are extending time-to-market for polymer composite designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Female Sterilization Devices Market |
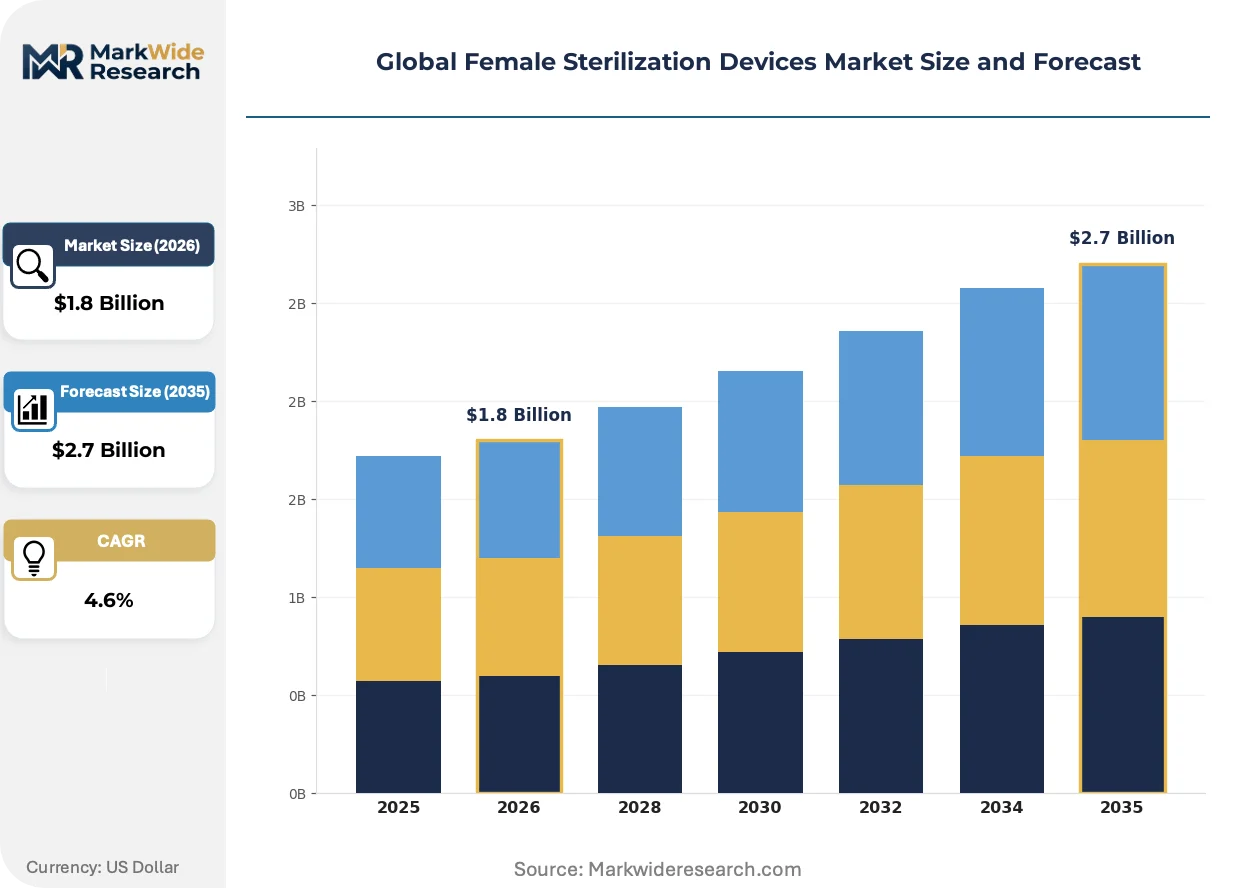
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laparoscopic Clips, Electrosurgical Devices, Hysteroscopic Devices, Implants End User: Hospitals, Clinics, Ambulatory Surgical Centers, Private Practices Technology: Endoscopic, Minimally Invasive, Conventional, Robotic Application: Family Planning, Therapeutic, Gynecological Surgery, Reproductive Health |
| Companies Covered | Bayer AG, Cooper Surgical, Hologic, Boston Scientific Corporation, Medtronic, Ethicon, CONMED Corporation, Cardinal Health, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Female Sterilization Devices Market Emerging Trajectories
Device miniaturization and procedural simplification are compressing the skill threshold required for permanent sterilization, expanding addressable provider pools beyond specialized gynecologic surgeons.
Radiofrequency-based tubal occlusion systems are collapsing the capital equipment footprint required for office-based procedures. Community health clinics in Texas and Florida are adopting these platforms to bypass hospital scheduling constraints. The technology is collapsing the economic viability of traditional operating-room-dependent laparoscopic approaches in cost-sensitive settings.
Japan's PMDA has tightened post-market surveillance requirements for permanent implantable contraceptives, mandating 10-year follow-up registries. Domestic manufacturers must now integrate real-world evidence collection into distribution contracts. Hysteroscopic device categories face disproportionate compliance burden given their irreversible mechanism of action.
Integrated health networks in the United States are consolidating sterilization device procurement under single-source agreements tied to broader women's health portfolios. Independent ambulatory centers are losing direct supplier relationships as purchasing shifts to system-level contracting offices. This concentration is most visible in California and Texas, where multi-hospital alliances control regional volume allocation.
Global Female Sterilization Devices Market Segmentation
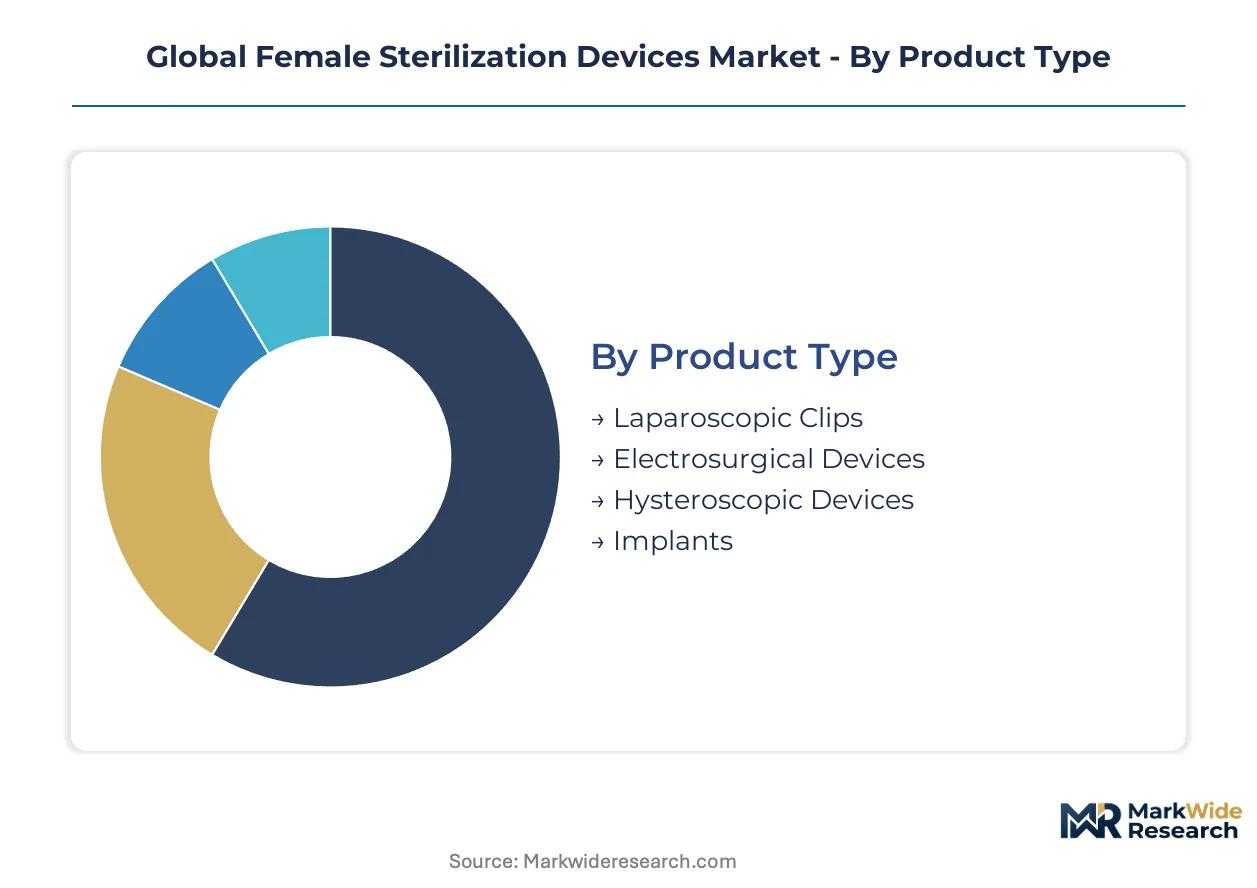
Segmentation in female sterilization devices reveals distinct procurement rhythms and margin profiles across product categories. Understanding these structural differences enables targeted positioning for manufacturers navigating reimbursement complexity and regulatory tiering.
Product Type:
Cycle times vary dramatically across device categories, with hysteroscopic systems turning over fastest due to single-use economics while laparoscopic clips persist longest in hospital inventories through bulk sterilization protocols.
- Hysteroscopic Devices:Silicone or polymer composite inserts deployed via transcervical access without abdominal incision. Demand concentrates in United States ambulatory surgical centers where same-day discharge protocols maximize reimbursement capture under facility fee structures. These systems command premium positioning through anesthesia-sparing profiles.
- Laparoscopic Clips:Titanium or polymer mechanical occlusion devices applied during laparoscopic tubal ligation. Volume leadership persists in Brazil and Mexico where capital equipment reuse optimizes per-procedure economics in public hospital systems constrained by budget cycles.
- Electrosurgical Devices:Bipolar or monopolar energy systems for tubal coagulation. These platforms retain installed base in secondary markets where electrosurgical generators serve multipurpose surgical suites.
- Implants:Permanent implantable constructs achieving tubal occlusion through tissue ingrowth mechanisms. Regulatory reclassification under EU MDR and FDA 510(k) pathways has concentrated supply among certified manufacturers with biocompatibility testing capacity.
Laparoscopic clips dominate installed base. Hysteroscopic devices are where expansion concentrates.
End User:
Procurement authority concentrates differently across care settings, with integrated health networks controlling hospital purchasing while independent clinics retain direct supplier relationships for specialized platforms.
- Hospitals:Comprehensive surgical departments performing laparoscopic and hysteroscopic sterilization within broader gynecological service lines. These facilities negotiate system-level contracts tied to women's health portfolio purchasing.
- Ambulatory Surgical Centers:Outpatient-focused facilities capturing reimbursement advantages through reduced facility fees and accelerated patient throughput. United States volume is climbing fastest in Texas and Florida where certificate-of-need restrictions are minimal.
- Clinics:Community health centers and family planning providers emphasizing access over surgical complexity. These settings adopt radiofrequency-based office systems to bypass hospital scheduling constraints.
- Private Practices:Individual or small-group gynecology practices with direct patient relationships. Capital constraints limit device selection to platforms with favorable leasing arrangements or manufacturer financing.
Hospitals dominate installed base. Ambulatory surgical centers are gaining share fastest.
Technology:
Capital intensity and training requirements stratify adoption velocity across technological tiers, with robotic platforms demanding substantial infrastructure investment while conventional approaches require minimal equipment.
- Minimally Invasive:Hysteroscopic and laparoscopic approaches reducing tissue trauma and recovery time. These modalities anchor volume in United States commercial reimbursement environments where outcomes-based contracting favors reduced complication rates.
- Endoscopic:Visualized access systems including hysteroscopes and laparoscopes with integrated imaging. Demand clusters in tertiary hospitals with dedicated gynecologic surgery divisions and fellowship-trained specialists.
- Robotic:Da Vinci and competing surgical robot platforms enabling precision tubal ligation. United States integrated health networks in California and Texas deploy these for premium positioning within competitive regional markets.
- Conventional:Laparotomy-based tubal ligation via mini-lap or postpartum approaches. These techniques persist in low-resource settings where equipment scarcity and surgeon training patterns favor open surgical access.
Minimally invasive systems dominate installed base. Robotic technology is where expansion concentrates.
Application:
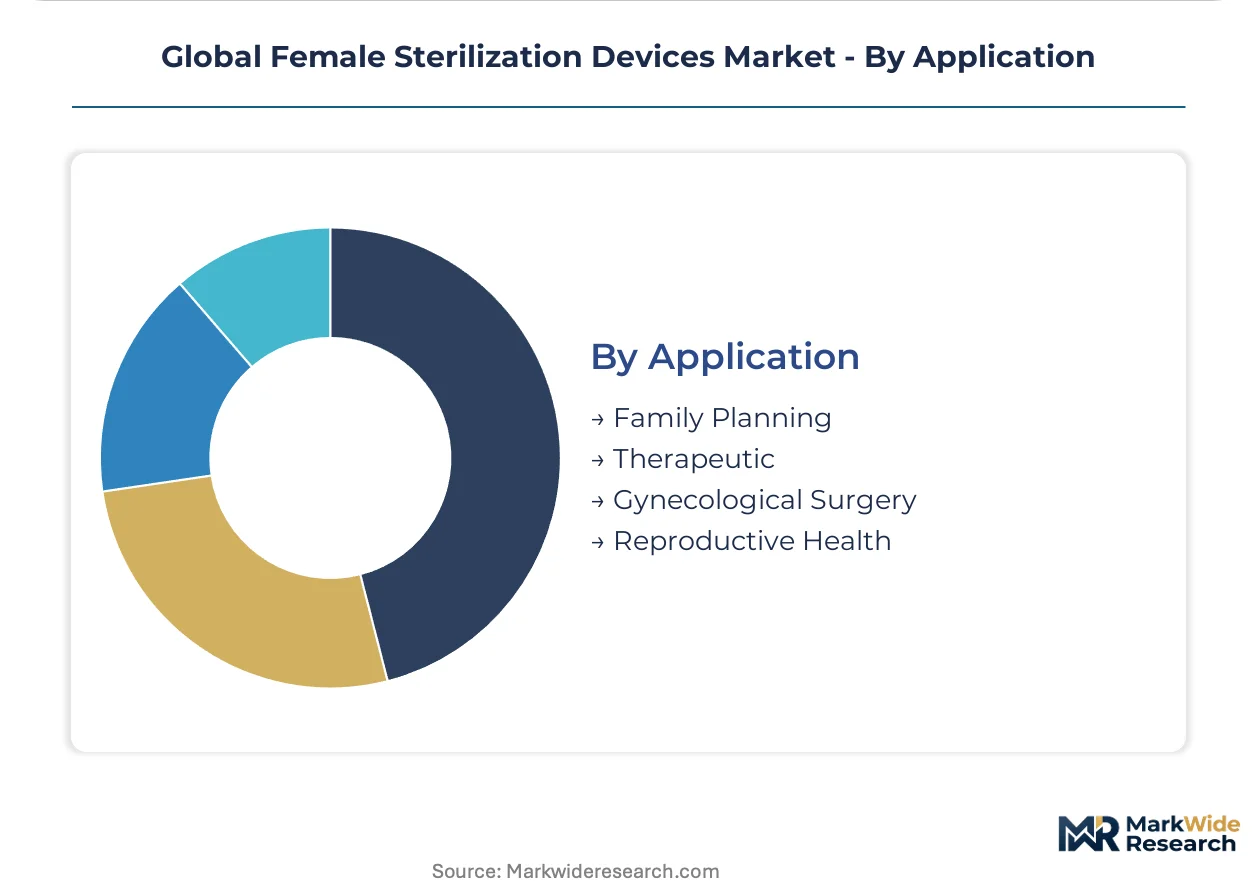
Reimbursement coding and patient population characteristics differentiate demand patterns across clinical indications, with family planning procedures commanding distinct procurement workflows versus therapeutic interventions.
- Family Planning:Elective sterilization for contraceptive purposes. Volume concentrates in United States commercial payor environments and India's Ayushman Bharat reimbursed channels where insurance coverage eliminates out-of-pocket barriers.
- Gynecological Surgery:Sterilization performed concurrent with other pelvic procedures such as myomectomy or endometriosis treatment. These cases leverage existing surgical access and anesthesia exposure.
- Therapeutic:Sterilization for medical indications including high-risk pregnancy contraindications or hereditary condition management. These procedures often proceed through hospital-based pathways with multidisciplinary consultation requirements.
- Reproductive Health:Comprehensive service delivery integrating sterilization counseling within broader contraceptive access programs. Public health systems in sub-Saharan Africa and Southeast Asia emphasize this category within WHO-aligned procurement frameworks.
Family planning dominates installed base. Gynecological surgery is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for medical-grade silicone and titanium-nickel alloys tilts trade flows toward German and Japanese chemical suppliers, while finished device exports concentrate from US and European manufacturing bases serving ambulatory networks worldwide.
United States
Ambulatory surgical centers in Texas and Florida drive hysteroscopic system procurement through certificate-of-need minimal environments. FDA 510(k) premarket notification pathways filter competitive entry timelines for permanent implantables. Integrated health networks in California consolidate sterilization device purchasing under single-source women's health portfolio agreements.
Germany
Medical-grade silicone feedstock production anchors European supply chains for polymer composite inserts. EU MDR reclassification of permanent implantables imposes stricter conformity assessment burdens that concentrate procurement among certified manufacturers. The Rhine-Ruhr industrial corridor hosts specialized chemical suppliers serving device makers across the continent.
India
Ayushman Bharat government-funded health insurance creates reimbursed access channels for sterilization procedures previously confined to out-of-pocket payment. CDSCO medical device regulations align with ISO 10993 biocompatibility protocols for public procurement eligibility. Maharashtra and Gujarat manufacturing clusters produce cost-optimized laparoscopic clips for domestic and export markets.
Brazil
Public hospital systems constrained by budget cycles favor laparoscopic clip reuse economics over capital-intensive hysteroscopic platforms. ANVISA medical device registration requirements stratify market access by certification capacity. São Paulo state health networks maintain volume leadership in family planning sterilization procedures.
Japan
PMDA post-market surveillance mandates 10-year follow-up registries for permanent implantable contraceptives, integrating real-world evidence into distribution contracts. METI industrial policy supports domestic manufacturers in shape-memory alloy development for hysteroscopic inserts. The Kanto region around Tokyo concentrates specialized gynecologic surgery training centers.
Global Female Sterilization Devices Market Vendor Landscape
On the supply side, the industry is consolidating around integrated diagnostics-to-surgery portfolios and distribution density networks. Three archetypes dominate: diversified medical technology conglomerates with women's health divisions, specialized gynecologic surgery instrument manufacturers, and supply chain intermediaries controlling hospital system reach. Competitive moves center on leasing arrangement expansion for capital-constrained facilities and robotic surgical platform convergence for premium pricing tiers.
Within the diversified technology tier, Bayer AG and Boston Scientific Corporation exemplify portfolio breadth spanning pharmaceutical and device segments. Cooper Surgical occupies a specialist position in women's health instrumentation, while Hologic anchors the integrated diagnostics-to-surgery recurring revenue model. Cardinal Health represents the distribution density archetype, with Olympus Corporation sitting within the endoscopic visualization systems tier that underlies procedural access.
| Leading Market Players |
|---|
| Bayer AG |
| Cooper Surgical |
| Hologic |
| Boston Scientific Corporation |
| Medtronic |
| Ethicon |
| CONMED Corporation |
| Cardinal Health |
| Olympus Corporation |
| Others |
Supply Flow & Price Mechanics
The Rhine-Ruhr industrial corridor's medical-grade silicone production capacity anchors polymer composite insert supply, with feedstock bottlenecks there transmitting directly into hysteroscopic device pricing power for certified manufacturers. German and Japanese chemical suppliers command premium positioning through ISO 10993 biocompatibility protocol alignment, while downstream buyers face constrained negotiation leverage during supply allocation cycles.
Pricing Analysis
Integrated health networks anchor contract-based long-term purchasing agreements that compress per-unit variability. Three-tier pricing structure across premium hysteroscopic systems, standard laparoscopic clips, and economy electrosurgical platforms reflects FDA 510(k) certification grade and anesthesia-sparing performance. Cost compression in the standard tier is intensifying because Brazilian and Mexican public hospitals prioritize capital equipment reuse. Independent ambulatory surgical centers exhibit highest price sensitivity due to certificate-of-need minimal environments in Texas and Florida.
Supply Chain Analysis
Contract manufacturing for titanium-nickel alloy components concentrates in German precision metalworking clusters and Japanese shape-memory foundries. Raw material sourcing draws from Australian titanium ore, German silicone polymerization, and Japanese nitinol wire drawing. Single-source vulnerability in medical-grade silicone feedstock exposes device makers to input cost volatility from Rhine-Ruhr chemical suppliers. Distribution runs through Cardinal Health's hospital system reach and Cooper Surgical's women's health specialty channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biocompatibility testing capacity and hysteroscopic insertion training infrastructure represent binding constraints that filter competitive entry. Manufacturers lacking ISO 10993-6 implantation study capabilities or physician credentialing program scale face extended time-to-market penalties regardless of product innovation.
For Market Incumbents: Entrench position through backward integration into titanium-nickel alloy supply and captive biocompatibility testing facilities. Long-acting reversible contraceptive substitution in Latin American public health systems threatens volume retention in traditional sterilization. Certification investment for EU MDR and FDA 510(k) pathway alignment preserves pricing power against marginal suppliers. For New Entrants and Emerging Players: Pursue WHO prequalification pathway alignment to unlock sub-Saharan African public health procurement contracts previously inaccessible to uncertified manufacturers. India's Ayushman Bharat expansion offers the most penetrable reimbursement channel for cost-optimized laparoscopic clips. Direct distribution partnerships with Maharashtra and Gujarat manufacturing clusters enable price-competitive export positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized women's health instrument manufacturers with hysteroscopic platform pipelines over diversified conglomerates with sterilization as peripheral exposure. Long-term viability hinges on robotic-assisted tubal ligation convergence and same-day discharge protocol adoption. The signal to watch is ambulatory surgical center certificate-of-need deregulation momentum across US states.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Notification | Accelerated review timelines for permanent implantables compress effective patent life for device makers. |
| EU MDR Conformity Assessment | Stricter reclassification filters marginal suppliers and concentrates procurement among certified manufacturers. |
| Hospital System Partnership | Integrated health networks in California consolidate sterilization purchasing under single-source women's health agreements. |
| Software Companion Development | Real-world evidence collection platforms satisfy Japan PMDA 10-year post-market surveillance mandates for implants. |
| Reimbursement Strategy | Ayushman Bharat alignment in India converts out-of-pocket sterilization demand into reimbursed volume channels. |
Methodological Framework
Cross-validation between primary interviews with gynecologic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU MDR conformity assessment databases, CMS Medicare procedure data, and hospital procurement contract repositories. Bottom-up demand modeling across ambulatory surgical centers and top-down market sizing through manufacturer revenue triangulation ensure robust coverage.
Calibration against historical hysteroscopic system adoption curves and laparoscopic clip volume trajectories informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user facility category, technology tier, and application indication. CAGRs derive from procedure volume elasticity to reimbursement rate changes and regulatory pathway clearance timelines. Titanium-nickel alloy raw material cost indices and silicone feedstock pricing volatility feed into margin compression assumptions.
Macroeconomic conditions sit as an overlay; deviation in medical device reimbursement rates, trade tariff exposure on German and Japanese chemical imports, or WHO prequalification budget allocations would shift the trajectory. Forecasts reflect documented assumptions regarding ambulatory surgical center expansion velocity and EU MDR implementation enforcement intensity. Quarterly review of FDA 510(k) clearance backlogs and CDSCO medical device registration processing times is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Global Medical Sensor Market
Medical Devices
Carotid Artery Stents Market
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
Urodynamic Devices Market
Medical Devices
Bone Conduction Hearing Aids Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Airway Clearance Systems Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
Mexico Ophthalmic Devices Market
Medical Devices
Pacemaker/Defibrillator Lead Extraction Kits Market
Medical Devices
Fracture Fixation Products Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market