
 North America Wound Care Management Market | 2026-2036
North America Wound Care Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wound Care Management Market Analytics
The EPA's Safer Choice program and hospital sustainability procurement mandates are pivoting purchasing criteria toward biodegradable dressings and reduced-packaging wound products. Smith & Nephew leverages its biologics portfolio to capture premium positioning in regenerative wound segments. Medline Industries anchors North American distribution through its direct-to-facility logistics network spanning thousands of hospital contracts. Baxter International specializes in advanced tissue repair matrices for complex surgical wounds, differentiating its offerings from commoditized gauze and basic dressing lines.
Wound care management encompasses the clinical protocols, medical devices, and therapeutic interventions employed to promote healing of acute and chronic skin disruptions, typically involving moisture-retentive dressings with absorption capacities ranging from grams to tens of grams of exudate per unit area. These systems serve to prevent infection, maintain optimal hydration balance, and accelerate re-epithelialization across inpatient and outpatient settings. Advanced Therapies commands the highest margin pool due to biologic growth factors and skin substitute technologies, while Dressings retains the largest volume footprint across hospital and home care channels. Hospitals dominate end-user procurement through centralized supply chain contracts, though Home Care represents the fastest-growing delivery site as payors push shorter length-of-stay protocols.
The FDA regulates wound care devices through 510(k) premarket notification and PMA pathways, with heightened scrutiny on biologic-synthetic combination products that blend living cellular materials with structural matrices. Health Canada and the Canadian Standards Association enforce parallel safety and efficacy requirements, creating a dual-compliance burden for manufacturers operating across the US-Canada border. The Centers for Medicare & Medicaid Services shapes demand through its Physician Fee Schedule and Outpatient Prospective Payment System reimbursement rates for wound debridement and advanced dressing applications. Stakeholders must monitor evolving FDA guidance on regenerative medicine advanced therapy designations, as these classifications will determine which wound biologics receive expedited review and preferential coding for reimbursement.
Market Dynamics
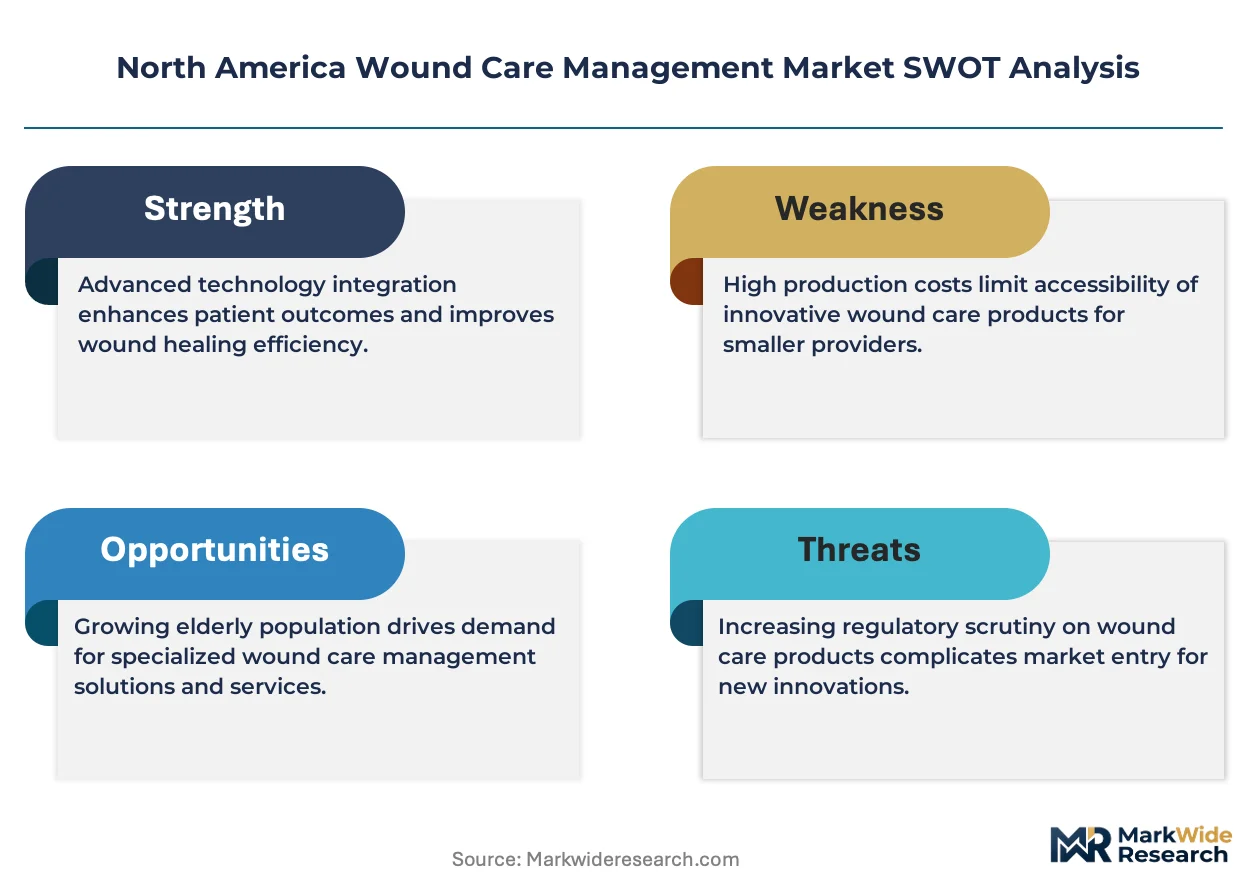
Medicare reimbursement compression for inpatient wound debridement is accelerating site-of-care migration toward outpatient and home-based delivery models across US hospital networks.
Growth Catalysts
- Advanced Dressing Reimbursement:CMS Physician Fee Schedule revisions expand coverage for moisture-retentive and antimicrobial dressings, incentivizing hospital procurement of higher-margin products over commodity gauze.
- Canada:Health Canada's expedited review pathway for regenerative medicine products reduces biologic wound therapy approval timelines, attracting portfolio investment from multinational manufacturers.
- Biologics Integration:Skin substitute technologies incorporating growth factors and cellular matrices command premium positioning in diabetic foot ulcer and venous leg ulcer protocols.
Market Restraints
- Raw Material Concentration:Collagen and hyaluronic acid supply chains concentrate among specialized European and Asian extractive processors, exposing North American manufacturers to input cost volatility.
- 510(k) Pathway Friction:FDA heightened scrutiny on biologic-synthetic combination products extends premarket notification review cycles for novel wound matrices.
- Basic Dressing Commoditization:Non-adherent gauze and hydrocolloid generics face price erosion from private-label contract manufacturing, compressing margin pools for undifferentiated producers.
Strategic Opportunities
- Mexico Manufacturing:Maquiladora zones near the US border offer tariff-advantaged production capacity for sterile dressing assembly serving Southwestern hospital networks.
- Remote Patient Monitoring:Integration of wound imaging and exudate sensors with telehealth platforms enables reimbursement capture under CMS remote therapeutic monitoring codes.
- EPA Safer Choice Alignment:Biodegradable dressing materials and reduced packaging formats satisfy hospital sustainability procurement mandates and differentiate tender submissions.
Industry Challenges
- Specialized Wound Care Nursing Shortage:Certification requirements for negative pressure wound therapy and biologic application limit deployment velocity in long-term care chains.
- Legacy EHR Integration:Wound measurement and documentation tools require custom API development to synchronize with entrenched electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wound Care Management Market |
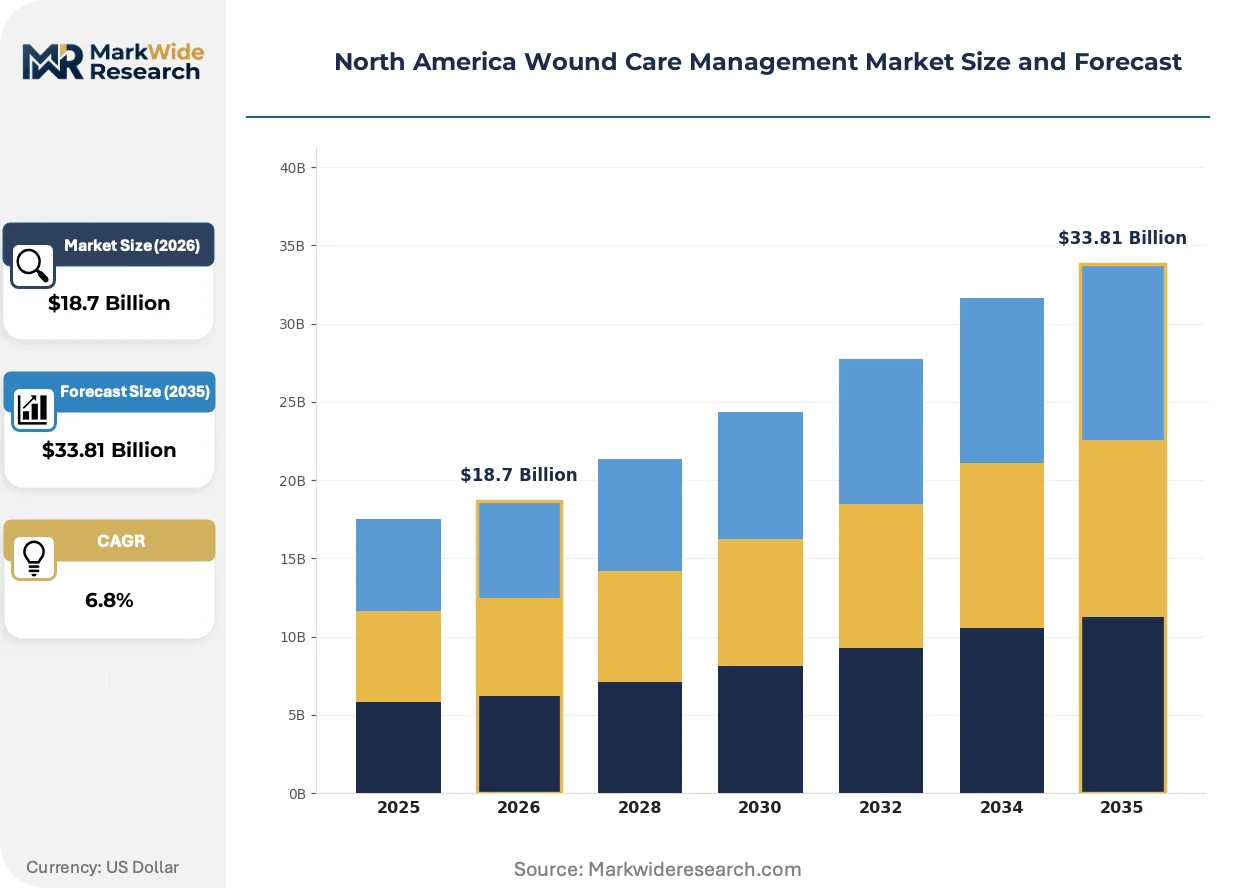
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Antiseptics, Other Devices, Advanced Therapies End User: Hospitals, Home Care, Clinics, Nursing Facilities Application: Diabetic Ulcers, Surgical Wounds, Burns, Pressure Sores Technology: Hydrocolloid, Foam, Alginate, Biologics |
| Companies Covered | Integra LifeSciences, Medline Industries, Smith & Nephew, Cardinal Health, Johnson & Johnson, 3M Company, Molnlycke Health Care, Baxter International, ConvaTec Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wound Care Management Market Evolving Landscape
Digital wound assessment and closed-loop dressing systems are compressing clinical decision cycles while regulatory frameworks for regenerative products reshape competitive entry barriers.
Negative pressure wound therapy systems equipped with automated pressure modulation and exudate sensing are automating clinician workflow in US acute care settings. Hospital wound care teams adopt these devices for complex surgical wounds and pressure injuries, reducing dressing change frequency. The technology is automating labor allocation across understaffed nursing units while capturing reimbursement under procedural codes.
Health Canada's alignment with FDA regenerative medicine advanced therapy designations creates parallel expedited pathways for skin substitute and growth factor products. Manufacturers filing concurrent submissions reduce total approval timeline exposure across the US-Canada border. Biologics portfolios targeting diabetic foot ulcers and burns prioritize this dual-market registration strategy.
Home infusion and durable medical equipment suppliers are capturing wound care device distribution from hospital-owned specialty pharmacies. Medicare Advantage plans in Florida and Texas direct post-acute wound therapy to contracted home care networks, bypassing traditional acute care discharge channels. This channel rotation concentrates volume among regional DME platforms with logistics density in retirement corridor geographies.
North America Wound Care Management Market Segmentation
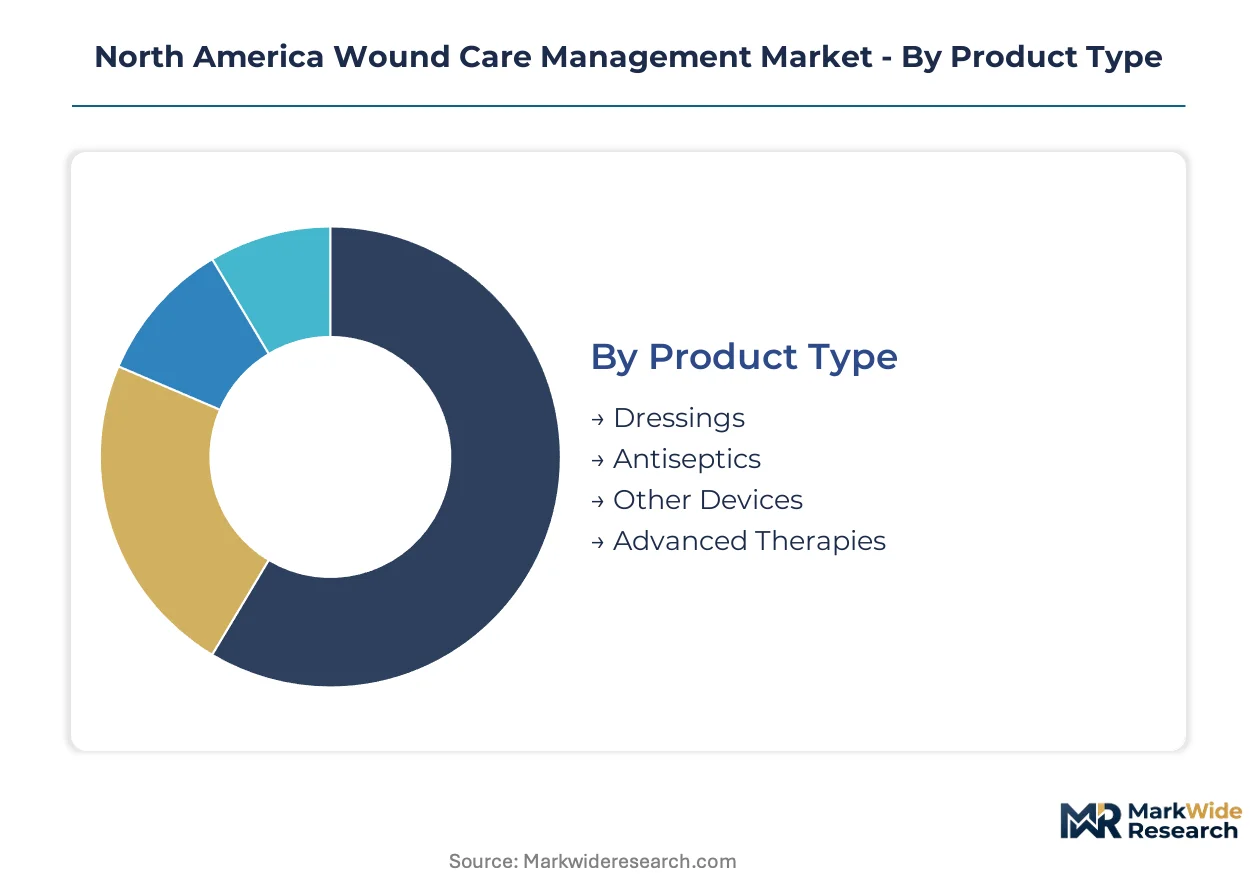
Segmentation in North American wound care reveals divergent capital requirements and reimbursement economics across product tiers and delivery sites. Hospital procurement centralization and Medicare coding distinctions create discrete margin pools that reshape manufacturer portfolio priorities.
Product Type:
Advanced Therapies demand the steepest upfront investment in clinical trial infrastructure and FDA biologics licensing, while commodity dressings require manufacturing scale rather than R&D intensity.
- Advanced Therapies:Skin substitutes and growth factor matrices incorporate living cellular materials requiring cryogenic logistics and specialized application training. Demand concentrates in academic medical centers and wound care clinics managing diabetic foot ulcers, where CMS reimbursement codes support premium pricing against amputation cost offsets.
- Dressings:Moisture-retentive films, hydrocolloids, and antimicrobial variants absorb exudate across gram-scale capacities. Hospital networks in Texas and Florida drive volume through centralized supply contracts, though home care channels are capturing share as Medicare Advantage plans shorten inpatient stays.
- Antiseptics:Iodine and silver-based formulations prevent biofilm formation in contaminated wounds. Long-term care chains in the Midwest specify these products for pressure injury protocols.
- Other Devices:Negative pressure wound therapy pumps and accessories automate exudate removal. US acute care settings deploy these for complex surgical wounds and dehisced incisions.
Most installed capacity flows through Dressings. Expansion is steepest in Advanced Therapies.
End User:
Site-of-care economics differentiate procurement authority, with hospital supply chains wielding volume leverage against fragmented home care purchasing.
- Hospitals:Centralized value analysis committees negotiate multi-year contracts covering thousands of SKUs. These facilities anchor demand for advanced biologics and NPWT systems through procedural reimbursement capture.
- Home Care:Durable medical equipment suppliers and home health agencies manage post-acute wound therapy. Medicare remote therapeutic monitoring codes now reimburse digital wound assessment, accelerating channel shift in retirement corridor states.
- Clinics:Outpatient wound care centers specialize in debridement and biologic application. Physician Fee Schedule revisions expand coverage for moisture-retentive dressings in these settings.
- Nursing Facilities:Skilled nursing operators face staffing constraints for specialized dressing changes. Certification requirements limit negative pressure therapy deployment velocity.
Hospitals retain the largest procurement volume. Home Care is expanding most quickly as payors mandate shorter length-of-stay protocols.
Application:
Clinical severity and complication risk stratify product selection, with limb-threatening conditions justifying premium biologic intervention.
- Diabetic Ulcers:Lower extremity wounds in diabetic populations drive demand for cellular matrices and growth factors. US podiatry and vascular surgery practices anchor prescribing volume for advanced skin substitutes.
- Surgical Wounds:Post-operative incisions and dehisced sites require antimicrobial dressings and NPWT. Hospital surgical departments specify these products through preference cards integrated with EHR systems.
- Burns:Thermal and chemical injuries utilize biosynthetic and cadaveric skin substitutes. Regional burn centers in the US concentrate procurement authority for these specialized products.
- Pressure Sores:Facility-acquired injuries in immobile patients trigger quality metrics and penalty exposure. Nursing facilities prioritize cost-effective foam and alginate dressings for prevention and treatment.
Most clinical protocols address Surgical Wounds. Steepest expansion trajectory appears in Diabetic Ulcers as population prevalence rises and biologic efficacy data accumulates.
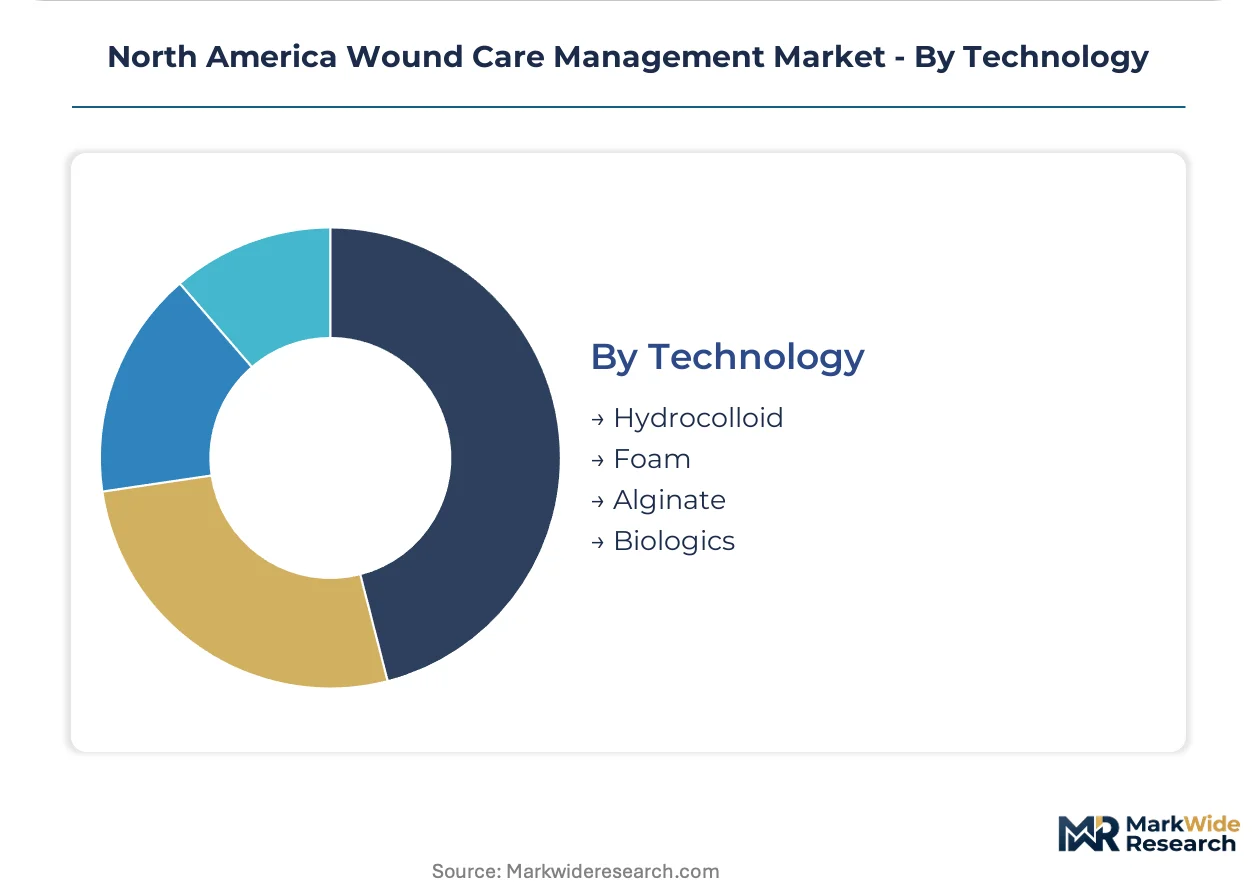
Technology:
Material science sophistication and manufacturing complexity separate premium positioning from commodity supply.
- Biologics:Living cellular matrices and recombinant growth factors require cryopreservation and specialized logistics. Health Canada and FDA regenerative medicine designations create expedited approval pathways attracting multinational investment.
- Foam:Polyurethane structures manage moderate-to-heavy exudate across inpatient and outpatient settings. Hospital networks standardize these products for surgical wound protocols.
- Hydrocolloid:Gel-forming polymers maintain moist healing environments for low-exudate wounds. Home care channels favor these for patient self-management.
- Alginate:Seaweed-derived fibers absorb heavy drainage and conform to cavity wounds. Long-term care operators specify these for pressure injury management.
Most dressing units deploy Foam technology. Biologics is gaining share fastest through reimbursement expansion and clinical outcome differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The wound care management industry traces its modern scale to post-World War II surgical advances in the United States, where military trauma research established protocols later commercialized through academic medical centers and Veterans Health Administration networks.
United States
Medicare Advantage plans in Florida and Texas drive post-acute wound therapy volume toward home care networks, bypassing traditional hospital discharge channels. CMS remote therapeutic monitoring codes now reimburse digital wound assessment, accelerating technology adoption in retirement corridor states. The Boston-Cambridge cluster anchors regenerative medicine R&D, with academic medical centers piloting cellular matrix therapies for diabetic foot ulcers.
Canada
Health Canada's expedited review pathway for regenerative medicine products reduces biologic wound therapy approval timelines, attracting multinational manufacturing investment. Provincial health authorities in Ontario and Quebec negotiate centralized procurement contracts for advanced dressings across hospital networks. The Toronto-Waterloo corridor concentrates medical device development activity, with startups commercializing negative pressure wound therapy accessories.
Mexico
Maquiladora zones near the Tijuana and Ciudad Juárez border crossings offer tariff-advantaged sterile dressing assembly capacity serving Southwestern US hospital networks. Mexican manufacturing labor costs support competitive positioning for commoditized hydrocolloid and foam products. The Baja California medical device cluster has expanded cleanroom capacity to meet FDA quality system regulation requirements for export-bound production.
North America Wound Care Management Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and reimbursement capture capability. The market structures around three tiers: multinational conglomerates with diversified medtech portfolios, specialized wound care pure-plays with concentrated biologics expertise, and private-label contract manufacturers serving price-sensitive procurement channels. Consolidation pressure operates through strategic acquisitions of cellular matrix technologies and geographic expansion into Medicare Advantage-dominated retirement corridors.
Among the established multinational tier, Smith & Nephew and Baxter International exemplify divergent strategic positioning within advanced therapies. Medline Industries anchors North American distribution scale through direct-to-facility logistics infrastructure. These three entities represent distinct competitive archetypes: biologics-led premium positioning, surgical-specialty matrix development, and supply chain density capture respectively.
| Leading Market Players |
|---|
| Integra LifeSciences |
| Medline Industries |
| Smith & Nephew |
| Cardinal Health |
| Johnson & Johnson |
| 3M Company |
| Molnlycke Health Care |
| Baxter International |
| ConvaTec Group |
| Others |
Value Network & Pricing Analysis
Cryogenic logistics infrastructure for cellular matrices concentrates production economics among specialized biologics manufacturers while simultaneously elevating distribution costs that reshape contract pricing across hospital networks. This dual compression on manufacturing and cold-chain outlays forces tiered pricing stratification that separates regenerative therapies from commodity dressing lines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement negotiations, with FDA biologics licensing status and CMS reimbursement codes serving as the primary price differentiation drivers. Price erosion runs through hydrocolloid and foam generics as private-label contract manufacturers capture hospital volume tenders. Long-term care chains exhibit highest price sensitivity due to fixed per-diem reimbursement, while academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with European collagen extractors and Asian hyaluronic acid processors, exposing North American dressing manufacturers to input cost volatility. Raw material dependencies center on marine-derived alginate, pharmaceutical-grade silver compounds, and recombinant growth factor substrates. Tariff exposure on Chinese-sourced antimicrobial agents compounds supply risk. Distribution runs through Medline Industries' direct-to-facility logistics network and regional durable medical equipment suppliers serving home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America wound care management market functions as a stable compounder, with Medicare Advantage penetration in retirement corridor states driving predictable post-acute volume expansion.
For Market Incumbents: Anticipate reimbursement compression in basic dressings by accelerating biologics portfolio development and securing CMS remote therapeutic monitoring code capture for digital wound platforms. Prioritize backward integration into collagen processing to defend margin position against European supply volatility. Hospital GPO contract consolidation represents the central threat to volume retention. For New Entrants and Emerging Players: Launch via home care DME partnerships in Florida and Texas retirement corridors, where Medicare Advantage site-of-care mandates concentrate addressable demand. Target underpenetrated negative pressure wound therapy accessories for diabetic foot ulcer protocols. White-space exists in biodegradable dressing formats aligned with EPA Safer Choice procurement mandates. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap foam and hydrocolloid manufacturers facing commoditization pressure, offering platform consolidation opportunities. Long-term viability favors cellular matrix developers with dual FDA-Health Canada approval pathways. Monitor Health Canada regenerative medicine designation granting velocity as inflection indicator for biologics portfolio premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| CMS Reimbursement Strategy | Remote therapeutic monitoring code capture enables digital wound assessment monetization in Medicare Advantage plans. |
| Biologics Portfolio Expansion | Skin substitute technologies command premium positioning against amputation cost offsets in diabetic foot ulcer protocols. |
| Hospital System Partnership | Centralized value analysis committee contracts lock in multi-year volume commitments across thousands of SKUs. |
| Manufacturing Scale-Up | Maquiladora zone capacity expansion serves Southwestern US networks with tariff-advantaged sterile dressing assembly. |
| Sustainability Repositioning | EPA Safer Choice alignment satisfies hospital procurement mandates for biodegradable materials and reduced packaging. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down biologics manufacturing capacity tracking forms the analytical core of this study. Primary interviews with wound care clinicians, hospital purchasing committee directors, GPO contracts managers, and home health agency operators combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital supply chain procurement records, and Health Canada medical device licensing data. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map dressing unit volumes and advanced therapy value pools across product type, end user, application, and technology dimensions throughout the forecast period. CAGRs derive from regression analysis against Medicare Advantage enrollment trajectories, diabetic population prevalence curves, and biologics reimbursement expansion schedules. Modeling incorporates Health Canada expedited review pathway utilization rates and EPA Safer Choice certification adoption curves as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA regulatory delay scenarios or acute collagen supply disruption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Italy Wound Care Market
Wound Care
South Korea Wound Care Management Market
Wound Care
Infectious Wound Care Management Market
Wound Care
Wound Management Market
Wound Care
Europe Advanced Wound Care Market
Wound Care
Wound Evacuators Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Global Diabetic Foot Ulcers Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Dental Wound Dressings Market
Wound Care
Global Surgical Drains/Wound Drainage Market
Wound Care
Burn Care Centers Market
Wound Care
Advanced Wound Dressings Market
Wound Care
Asia Pacific Advanced Wound Care Market
Wound Care
Autologous Wound Patches Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market