
 Wound Contact Layer Dressing Market | 2026-2036
Wound Contact Layer Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Contact Layer Dressing Market Analytics
Antimicrobial-grade contact layers is reorganizing competitive priorities across the wound contact layer dressing supply base. Smith & Nephew plc leverages its vertically integrated silicone manufacturing to sustain premium positioning in surgical wound applications. Mölnlycke Health Care AB anchors European hospital supply chains through direct distribution contracts with national health systems. 3M Company differentiates via proprietary adhesive technologies that reduce trauma during dressing changes.
A wound contact layer dressing constitutes a semi-permeable or non-adherent substrate, typically 0.5 to 2.0 mm in thickness, engineered from silicone, hydrogel, or petroleum-impregnated gauze to permit exudate passage while preventing mechanical adherence to granulating tissue. Its primary commercial purpose is to serve as an interface between the wound bed and secondary absorbent dressings, minimizing epithelial stripping during removal across burns, surgical incisions, and chronic ulcer management. Hydrogel-based variants command margin premiums in burn centers where cooling and hydration properties reduce patient discomfort, while silicone-coated segments dominate surgical wound applications due to their atraumatic removal characteristics. Foam contact layers occupy the fastest-expanding niche in home care settings where extended wear time reduces nursing visit frequency.
FDA 510(k) clearance pathways and the EU Medical Device Regulation (MDR) classification framework govern market access, with MDR's heightened clinical evidence requirements extending certification timelines for novel materials. The EPA regulates antimicrobial claims under FIFRA, constraining silver-ion and PHMB marketing assertions to validated efficacy data. Stakeholders must monitor evolving biocompatibility testing standards from ISO 10993 and reconcile divergent FDA-EMA expectations for combination product classifications as drug-device boundaries blur in advanced wound care.
Market Dynamics
Hospital procurement of wound contact layer dressings is pivoting toward outpatient surgical recovery protocols, compressing traditional inpatient supply contracts and forcing manufacturers to restructure distribution networks for ambulatory surgical centers and home care channels.
Growth Catalysts
- EU Medical Device Regulation (MDR):Heightened clinical evidence requirements favor established manufacturers with robust biocompatibility data, accelerating consolidation around compliant suppliers.
- Silver-ion antimicrobial coatings:EPA-validated efficacy claims under FIFRA enable premium positioning in burn centers and diabetic foot clinics where infection control drives purchasing decisions.
- Home care nursing:Extended wear-time foam contact layers reduce visit frequency for chronic ulcer management, expanding addressable volume beyond acute care settings.
Market Restraints
- Medical-grade silicone feedstock volatility:Petrochemical input costs fluctuate with energy markets, compressing margins on silicone-coated variants that dominate surgical applications.
- ISO 10993 biocompatibility testing:Evolving cytotoxicity and sensitization standards extend development timelines for novel hydrogel formulations.
- Petroleum-impregnated gauze substitution:Low-cost traditional dressings retain share in price-sensitive long-term care facilities, limiting premium product penetration.
Strategic Opportunities
- Combination product classification:Drug-device boundary blurring creates white space for antimicrobial-eluting contact layers with sustained-release pharmacological claims.
- Direct-to-hospital distribution:Bypassing group purchasing organizations enables margin capture and clinical education investment in integrated delivery networks.
- India's PLI scheme for medical devices:Domestic manufacturing incentives attract contract manufacturers seeking to serve Asia-Pacific demand with reduced import duty exposure.
Industry Challenges
- Regulatory affairs specialization:Divergent FDA-EMA expectations for combination product submissions require dedicated expertise that mid-cap manufacturers struggle to retain.
- Legacy ERP integration:Track-and-trace requirements under MDR and FDA UDI rules demand supply chain software upgrades that fragment operational focus.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Contact Layer Dressing Market |
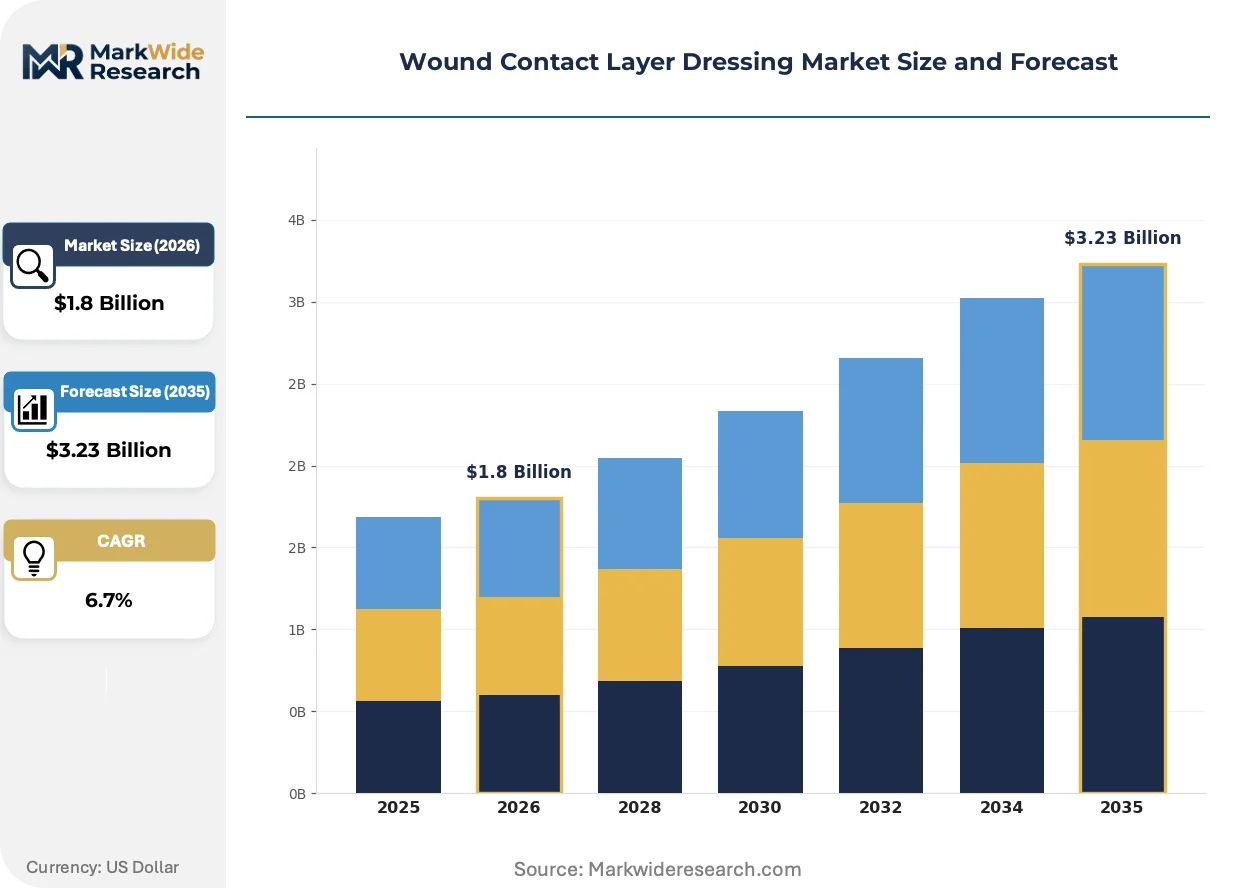
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogel, Foam, Film, Non-woven End User: Hospitals, Home Care, Clinics, Long-term Care Application: Burns, Surgical Wounds, Diabetic Ulcers, Pressure Ulcers Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Smith & Nephew plc, 3M Company, Mölnlycke Health Care AB, ConvaTec Group Plc, Paul Hartmann AG, Coloplast A/S, Cardinal Health, B. Braun Melsungen AG, Lohmann & Rauscher GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Contact Layer Dressing Market Evolving Landscape
Material science advances and regulatory recalibration are simultaneously expanding clinical indications and compressing commercialization timelines for next-generation wound interface technologies.
Silicone-coated contact layer technology is fragmenting competitive positioning across surgical wound care. Burn centers and plastic surgery units now specify atraumatic removal characteristics as standard, forcing petroleum-impregnated gauze suppliers into commodity pricing. This shift is fragmenting procurement decisions by clinical specialty rather than centralized materials management.
EU MDR's heightened clinical evidence requirements are extending certification timelines for novel materials. Manufacturers must now generate post-market surveillance data that exceeds predecessor directive obligations, particularly for antimicrobial claims. Hydrogel-based variants face the steepest compliance burden, delaying European launches relative to FDA 510(k) pathways.
Integrated delivery networks are consolidating supplier contracts around outcomes-based metrics rather than unit pricing. Hospital systems now evaluate total cost of care including dressing change labor and complication rates. This behavioral shift is most visible in United States Medicare Advantage populations where readmission penalties amplify procurement scrutiny.
Wound Contact Layer Dressing Market Segmentation
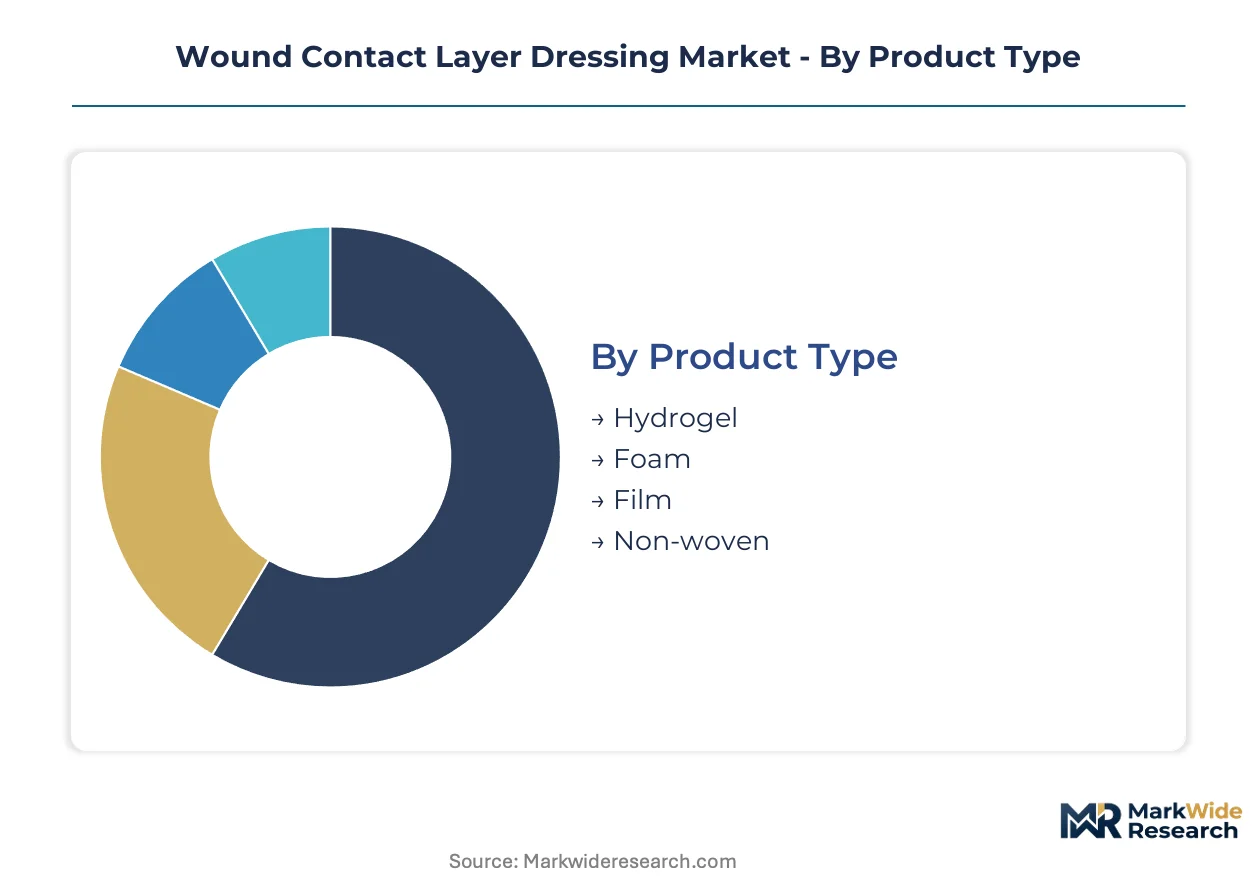
Segmentation in wound contact layer dressings reveals how regulatory pathways, reimbursement structures, and clinical workflows fragment demand across materially different commercial channels. Understanding these divides enables targeted positioning against distinct purchasing criteria.
Product Type:
Silicone-coated variants face FDA 510(k) and EU MDR pathways with divergent biocompatibility evidence requirements, while hydrogel formulations encounter steeper clinical validation burdens under ISO 10993 cytotoxicity standards.
- Silicone:Atraumatic removal properties dominate surgical wound applications. United States hospital systems prioritize this segment for outpatient recovery protocols where minimizing epithelial stripping reduces readmission risk.
- Hydrogel:Cooling and hydration characteristics command margin premiums in burn centers. European certification timelines extend relative to FDA pathways due to MDR's heightened post-market surveillance obligations for novel polymer matrices.
- Foam:Extended wear-time properties reduce nursing visit frequency in home care channels.
- Film:Semi-permeable barriers serve superficial wound protection with minimal exudate management.
- Non-woven:Petroleum-impregnated gauze retains price-sensitive long-term care penetration despite silicone displacement in acute settings.
Silicone handles the majority of throughput; foam is expanding most quickly on share as home care volumes accelerate.
End User:
Procurement authority concentrates differently across settings, with integrated delivery networks consolidating hospital contracts around outcomes-based metrics while home care purchasing fragments across regional nursing agencies.
- Hospitals:Centralized materials management dominates, though surgical specialty units increasingly specify atraumatic removal characteristics independent of procurement. United States Medicare Advantage readmission penalties amplify total-cost-of-care evaluation.
- Home Care:Extended wear-time requirements drive foam contact layer preference. Nursing visit reimbursement constraints in Germany and Japan create demand for reduced dressing change frequency.
- Clinics:Ambulatory surgical centers compress traditional inpatient supply relationships.
- Long-term Care:Budget constraints sustain petroleum-impregnated gauze substitution despite clinical inferiority.
Hospitals capture the dominant value pool; home care registers the steepest expansion trajectory as aging demographics shift care settings.
Application:
Clinical indication determines material selection criteria, with infection control priorities in diabetic foot clinics and cosmetic outcomes driving plastic surgery procurement.
- Surgical Wounds:Atraumatic removal characteristics are now standard specification in plastic surgery and general surgery units. Silicone-coated variants dominate as epithelial stripping minimization becomes non-negotiable.
- Burns:Cooling and hydration properties reduce patient discomfort in specialized burn centers. Hydrogel variants face extended European certification timelines under MDR antimicrobial claim requirements.
- Diabetic Ulcers:Infection control drives silver-ion antimicrobial coating preference in podiatry clinics.
- Pressure Ulcers:Extended wear-time foam contact layers reduce nursing labor in long-term care.
Surgical wounds absorb the largest volume; diabetic ulcers are climbing the fastest as population prevalence expands.
Distribution Channel:
Channel structure reflects customer scale and regulatory complexity, with direct sales requiring dedicated clinical education capabilities and online channels demanding simplified product configurations.
- Direct Sales:Integrated delivery network contracts bypass group purchasing organizations, enabling margin capture and clinical education investment. United States hospital systems consolidate supplier relationships around outcomes metrics.
- Wholesalers:National health system contracts in France and Sweden anchor European hospital supply chains through tender-based procurement.
- Online:Simplified configurations serve home care patients and small clinic purchasers.
- Retail:Pharmacy and medical supply stores address consumer-directed chronic wound management.
Direct sales commands the highest value concentration; online channels are gaining share fastest as purchasing decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of advanced wound contact layers concentrates in the United States, Germany, and Japan, where medical-grade silicone and hydrogel formulation capabilities align with stringent regulatory infrastructure. These three countries house the primary production clusters serving hospital systems across North America, Europe, and Asia-Pacific respectively.
United States
Outpatient surgical recovery protocols and Medicare Advantage readmission penalties drive demand for atraumatic silicone-coated dressings. FDA 510(k) clearance pathways enable faster commercialization than European alternatives, attracting manufacturers to establish formulation facilities in the Research Triangle and Greater Boston medical device clusters.
Germany
National health system tender contracts and aging demographics sustain high-volume procurement of advanced wound interfaces. The EU MDR classification framework governs market access, with Lohmann & Rauscher and other domestic manufacturers leveraging post-market surveillance infrastructure developed under predecessor directives.
Japan
Reimbursement constraints on nursing visit frequency accelerate home care adoption of extended wear-time foam contact layers. PMDA regulatory timelines and METI industrial policy support domestic production of silicone-based medical materials in the Kansai and Chubu manufacturing belts.
United Kingdom
NHS supply chain consolidation around integrated care systems reshapes procurement authority for surgical wound dressings. MHRA operates under retained EU MDR equivalence arrangements, with Smith & Nephew maintaining formulation capabilities in Hull to serve European and domestic hospital contracts.
India
Domestic manufacturing incentives under the PLI scheme for medical devices attract contract manufacturers seeking reduced import duty exposure for Asia-Pacific distribution. CDSCO regulatory harmonization efforts and diabetic population growth position the country as an emerging demand center for antimicrobial contact layers.
Wound Contact Layer Dressing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the wound contact layer dressing supply base. The market structure consolidates around diversified medical device conglomerates with captive silicone supply chains, while mid-cap specialists occupy niche positions in hydrogel and antimicrobial segments. Three strategic archetypes dominate: vertically integrated multinationals with direct hospital contracting capabilities, regional champions anchored in national health system supply chains, and technology-focused innovators pursuing combination product classifications. Competitive dynamics center on M&A activity to secure biocompatibility data assets and capacity expansion into India's PLI-subsidized manufacturing zones.
Among diversified medical device conglomerates, Smith & Nephew plc and 3M Company occupy positions exemplifying technology-led differentiation, while Mölnlycke Health Care AB represents the regional champion archetype with deep European hospital supply chain integration. These three entities anchor the premium tier through distinct competitive vectors: proprietary adhesive technologies, vertically integrated silicone manufacturing, and direct national health system contracting respectively.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| 3M Company |
| Mölnlycke Health Care AB |
| ConvaTec Group Plc |
| Paul Hartmann AG |
| Coloplast A/S |
| Cardinal Health |
| B. Braun Melsungen AG |
| Lohmann & Rauscher GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Petroleum-impregnated gauze displacement by silicone-coated variants simultaneously redraws manufacturing geography toward medical-grade silicone clusters and compresses margins on legacy formulations. This substitution dynamic concentrates pricing power with suppliers commanding captive silicone supply chains while forcing traditional gauze manufacturers into commodity positioning.
Pricing Analysis
FDA 510(k) and EU MDR dictate the pricing tier structure across the wound contact layer dressing market, with antimicrobial silver-ion coatings commanding premium positioning validated by EPA FIFRA efficacy claims. Three-tier pricing structure across premium, standard, and economy levels separates silicone-coated surgical variants from hydrogel burn center formulations and petroleum-impregnated gauze for long-term care. Cost compression in the economy tier intensifies because low-cost substitutes retain share in price-sensitive nursing facilities. Long-term care facilities exhibit highest price sensitivity; burn centers and plastic surgery units demonstrate lowest sensitivity due to outcomes-based procurement criteria.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes periodically constrain medical-grade silicone feedstock deliveries to formulation facilities. Manufacturing concentrates in the United States, Germany, and Japan, where medical-grade silicone and hydrogel formulation capabilities align with stringent regulatory infrastructure. Raw material dependencies center on petrochemical-derived silicone polymers, silver-ion antimicrobial precursors, and specialized hydrogel polymer matrices. Single-source vulnerability characterizes medical-grade silicone supply given concentration among specialized chemical producers. Distribution runs through direct hospital contracting for integrated delivery networks, national health system tenders in Europe, and regional wholesalers serving ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement decentralization across surgical specialty units creates fragmentation opportunity as clinical stakeholders bypass centralized materials management. This demand-side shift generates niche positioning potential for differentiated contact layer technologies.
For Market Incumbents: Compound defensive positioning through backward integration into medical-grade silicone manufacturing and accelerated MDR post-market surveillance infrastructure investment. Emerging contract manufacturers in India threaten established supply relationships through PLI-subsidized cost structures. Vertical integration into captive silicone supply represents the critical lever for margin defense against low-cost import competition. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways offer expedited market entry for silicone-coated variants targeting ambulatory surgical center channels. Home care nursing agencies in Germany and Japan represent the most penetrable segment given reimbursement constraints on visit frequency. Direct-to-hospital distribution bypassing group purchasing organizations provides the essential go-to-market angle for margin capture and clinical education investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap specialists possessing ISO 10993 biocompatibility data libraries but lacking direct hospital contracting scale. Long-term viability over the five-to-ten year window hinges on combination product classification capabilities as drug-device boundaries blur. Acquisition targets should demonstrate robust post-market surveillance infrastructure and antimicrobial claim validation. The signal to monitor is EU MDR enforcement intensity accelerating consolidation around compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Investment | Post-market surveillance infrastructure secures European hospital access against certification delays. |
| Antimicrobial Coating Development | Silver-ion and PHMB formulations command EPA-validated premium positioning in infection-sensitive applications. |
| Direct Hospital Contracting | Bypassing GPOs enables margin capture and clinical education investment in integrated delivery networks. |
| India PLI Manufacturing Entry | Domestic production incentives reduce import duty exposure for Asia-Pacific distribution expansion. |
| Combination Product Classification | Drug-device boundary blurring creates white space for antimicrobial-eluting sustained-release formulations. |
Research Methodology
Operator-level perspectives from hospital procurement managers, biomedical engineers, GPO contracts managers, and wound care clinicians anchored the qualitative base for this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR certification databases, hospital procurement contracts, and CMS Medicare reimbursement data. Bottom-up volume estimates triangulated against top-down market sizing across product type, end user, application, and distribution channel dimensions.
Sensitivity analysis tested forecast robustness across alternative scenarios for regulatory timeline acceleration and raw material cost volatility. Segmentation modeling incorporated product material technology, clinical indication, care setting, and geographic regulatory cluster throughout the projection horizon. CAGRs derived from historical growth pattern analysis adjusted for structural shifts in outpatient surgical recovery protocols and home care channel expansion. Antimicrobial claim validation requirements and biocompatibility testing evolution served as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable FDA-EMA regulatory convergence and continued petrochemical feedstock availability; material deviation would warrant model refresh. Specific risk factors include EU MDR enforcement intensity exceeding baseline assumptions, medical-grade silicone supply disruption, and reimbursement compression in Medicare Advantage populations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
Wound Care Centers Market
Wound Care
Wound Cleanser Products Market
Wound Care
Dental Wound Dressings Market
Wound Care
Wound Healing Market
Wound Care
Enzymatic Wound Debridement Market
Wound Care
Global Burn Care Market
Wound Care
Japan Wound Care Management Devices Market
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Infectious Wound Care Management Market
Wound Care
Decubitus Ulcer Treatment Products Market
Wound Care
Gauze Bandage Rolls Market
Wound Care
Wound Evacuators Market
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
Middle East and Africa Advanced Wound Care Market