
 Chronic Wound Care Market | 2026-2036
Chronic Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Wound Care Market Intelligence
The FDA's 510(k) modernization initiative is pivoting submission requirements for antimicrobial and bioengineered wound products, raising clinical evidence thresholds for market clearance. Smith & Nephew leverages its negative pressure wound therapy portfolio to sustain leadership in hospital procurement channels. Mölnlycke Health Care anchors European supply networks through specialized foam and silicone adhesive technologies. Baxter competes in the advanced tissue matrix segment with collagen-based platforms for diabetic ulcer reconstruction.
Chronic wound care encompasses the clinical management of non-healing cutaneous defects persisting beyond twelve weeks, employing moisture-retentive dressings, topical bioactives, negative pressure devices, and cellular or acellular skin substitutes engineered from porcine or bovine extracellular matrix. These interventions restore physiologic moisture balance, debride necrotic tissue, and modulate inflammatory cytokine profiles to advance wounds through proliferative and remodeling phases. Antimicrobial dressings incorporating silver or iodine compounds command premium positioning as infection control mandates intensify across acute care settings, while negative pressure wound therapy systems capture disproportionate revenue per procedure due to capital equipment and disposable recurring sales. Foam and hydrocolloid dressings represent mature volume categories with compressed margins, whereas bioengineered skin substitutes concentrate margin pools in specialized burn and diabetic foot centers.
The FDA, the European Medicines Agency through its Medical Device Regulation framework, and the International Organization for Standardization govern biocompatibility testing, sterilization validation, and clinical performance benchmarks for chronic wound products. These bodies shape demand by conditioning reimbursement eligibility on demonstrated cost-effectiveness and safety documentation, particularly for advanced therapies seeking Category III device classification. Stakeholders must monitor evolving antimicrobial resistance surveillance data and corresponding regulatory restrictions on silver-eluting formulations to anticipate portfolio reconfiguration requirements.
Market Dynamics
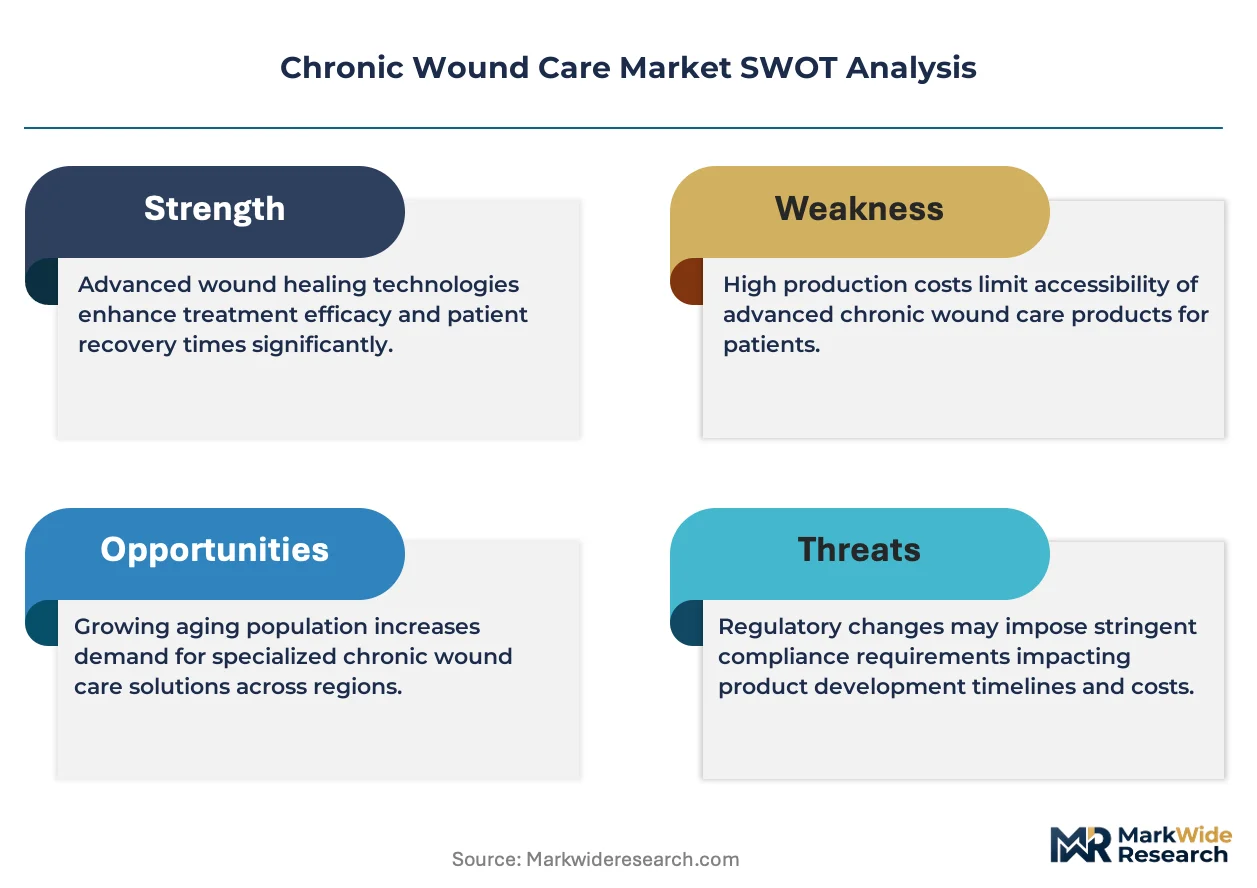
The FDA's 510(k) modernization initiative is compressing clearance timelines for antimicrobial dressings while elevating clinical evidence requirements, forcing manufacturers to restructure R&D budgets toward larger pivotal trials and real-world evidence collection.
Growth Catalysts
- Hospital-acquired infection mandates:CMS non-payment policies for preventable surgical site infections are driving procurement of silver-impregnated and iodine-releasing dressings in US acute care networks.
- REACH antimicrobial framework:The European Chemicals Agency's tightened biocidal product regulations are accelerating substitution toward bioengineered alternatives that bypass metal-based active ingredient restrictions.
- Diabetic foot ulcer protocols:Medicare's expanded coverage for cellular skin substitutes in outpatient settings is pulling advanced matrix products into community wound centers.
Market Restraints
- Collagen raw material concentration:Over 60% of medical-grade bovine and porcine collagen derives from Brazilian and Argentinian slaughterhouse networks, exposing supply chains to foot-and-mouth disease quarantines and export license volatility.
- Silver resistance surveillance:The WHO's Global Antimicrobial Resistance and Use Surveillance System is documenting reduced susceptibility in Pseudomonas aeruginosa and Staphylococcus aureus isolates, threatening the clinical positioning of silver-eluting dressings.
- Negative pressure capital intensity:Hospital procurement committees face 18-24 month depreciation schedules for NPWT pumps, delaying replacement cycles and capping disposable revenue expansion.
Strategic Opportunities
- Home care channel penetration:Medicare's Hospital at Home waiver extensions are creating reimbursement pathways for portable negative pressure systems in post-acute settings previously restricted to inpatient facilities.
- 3D bioprinted matrix convergence:The intersection of extrusion-based cell deposition and decellularized scaffold sourcing is enabling patient-specific graft geometry for deep diabetic ulcer cavities.
- Indian manufacturing zones:The PLI scheme for medical devices is attracting contract manufacturers to Gujarat and Karnataka clusters, offering 15-20% cost advantages for hydrocolloid and foam dressing exports.
Industry Challenges
- Wound care specialist workforce gaps:The American Board of Wound Medicine certifies fewer than 500 new physicians annually, creating bottlenecks for advanced therapy adoption in community settings.
- ISO 10993 biocompatibility testing backlogs:Contract research organizations face 6-9 month queues for cytotoxicity and sensitization studies, delaying 510(k) submissions for novel adhesive formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Wound Care Market |
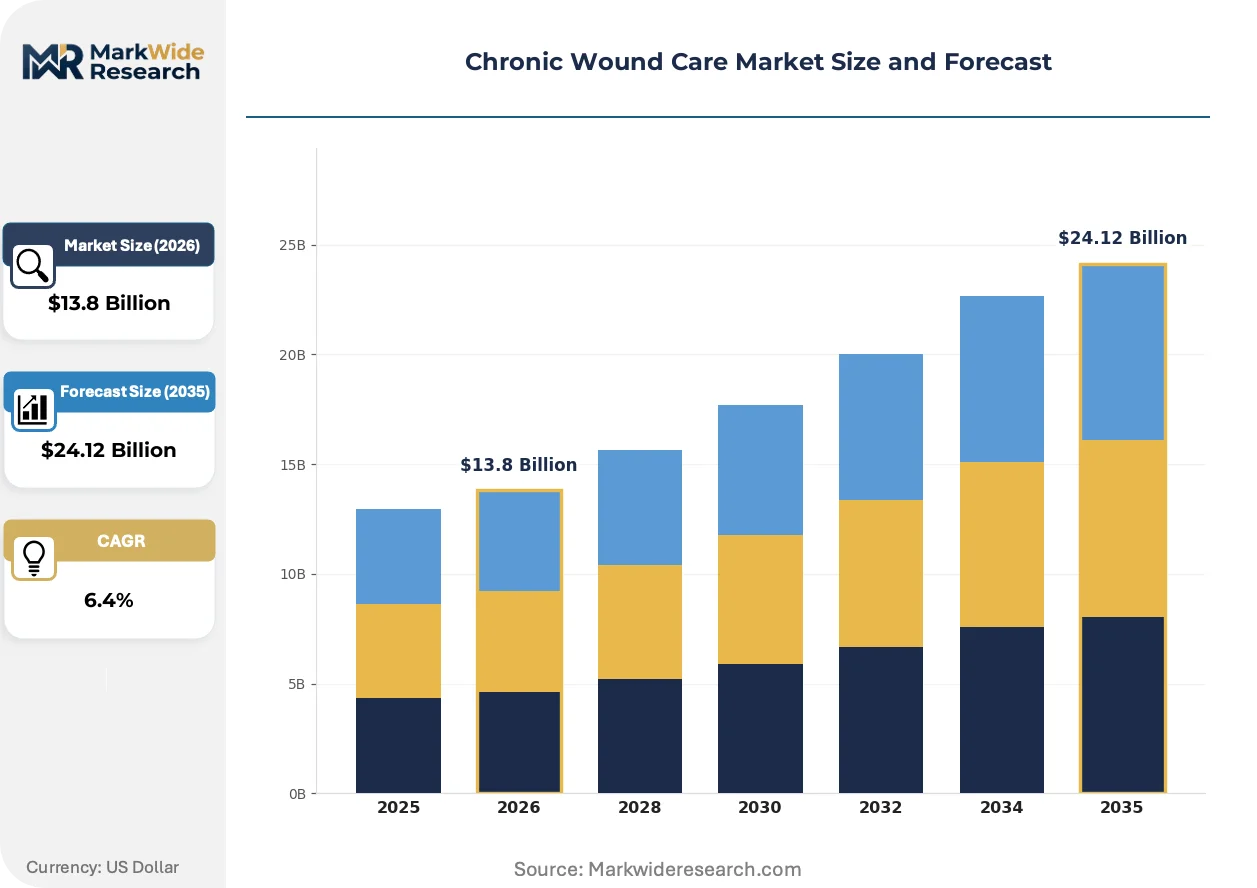
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid Dressings, Foam Dressings, Alginate Dressings, Film Dressings, Antimicrobial Dressings, Collagen Dressings Application: Diabetic Ulcers, Venous Leg Ulcers, Pressure Ulcers, Surgical Wounds, Traumatic Wounds End User: Hospitals, Wound Care Centers, Home Healthcare, Ambulatory Surgical Centers Delivery Mode: Topical Therapies, Negative Pressure Wound Therapy, Bioengineered Skin Substitutes, Electrical Stimulation, Ultrasound Therapy |
| Companies Covered | 3M, Medtronic, Smith & Nephew, Integra LifeSciences, Baxter, ConvaTec Group, Coloplast, Cardinal Health, Mölnlycke Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Wound Care Market Strategic Shifts & Innovations
Bioactive wound management is pivoting from passive moisture retention toward engineered microenvironments that actively modulate healing cascades, with convergence across materials science, cellular biology, and digital monitoring platforms.
Electroconductive wound dressings incorporating printed graphene circuits and zinc-oxide nanostructures are electrifying the chronic wound segment by enabling real-time impedance spectroscopy for moisture and bacterial load assessment. Hospital wound centers in Germany and the Netherlands are piloting these systems for diabetic foot surveillance. The technology is electrifying competitive positioning by collapsing the diagnostic-treatment interval from days to hours, compressing margins for conventional dressing categories that lack sensing capabilities.
The EU Medical Device Regulation's 2021 recast is forcing reclassification of absorbable hemostats and tissue adhesives from Class IIa to Class III, requiring clinical investigations that add 18-24 months to market entry. Small and mid-size manufacturers without European authorized representative infrastructure are withdrawing SKUs rather than absorbing compliance costs. The collagen-based skin substitute segment is most affected, with several US-origin products now restricted to compassionate use pathways pending MDR certification.
Integrated service contracts bundling advanced dressings with remote patient monitoring and specialist teleconsultation are displacing transactional product sales in US Medicare Advantage networks. Wound care management organizations are consolidating purchasing across 50-100 clinic footprints, extracting 12-15% price concessions in exchange for volume commitments and outcomes data sharing. This consolidation is most visible in Florida and Texas, where diabetic ulcer prevalence and capitated reimbursement models concentrate buyer leverage.
Chronic Wound Care Market Segmentation
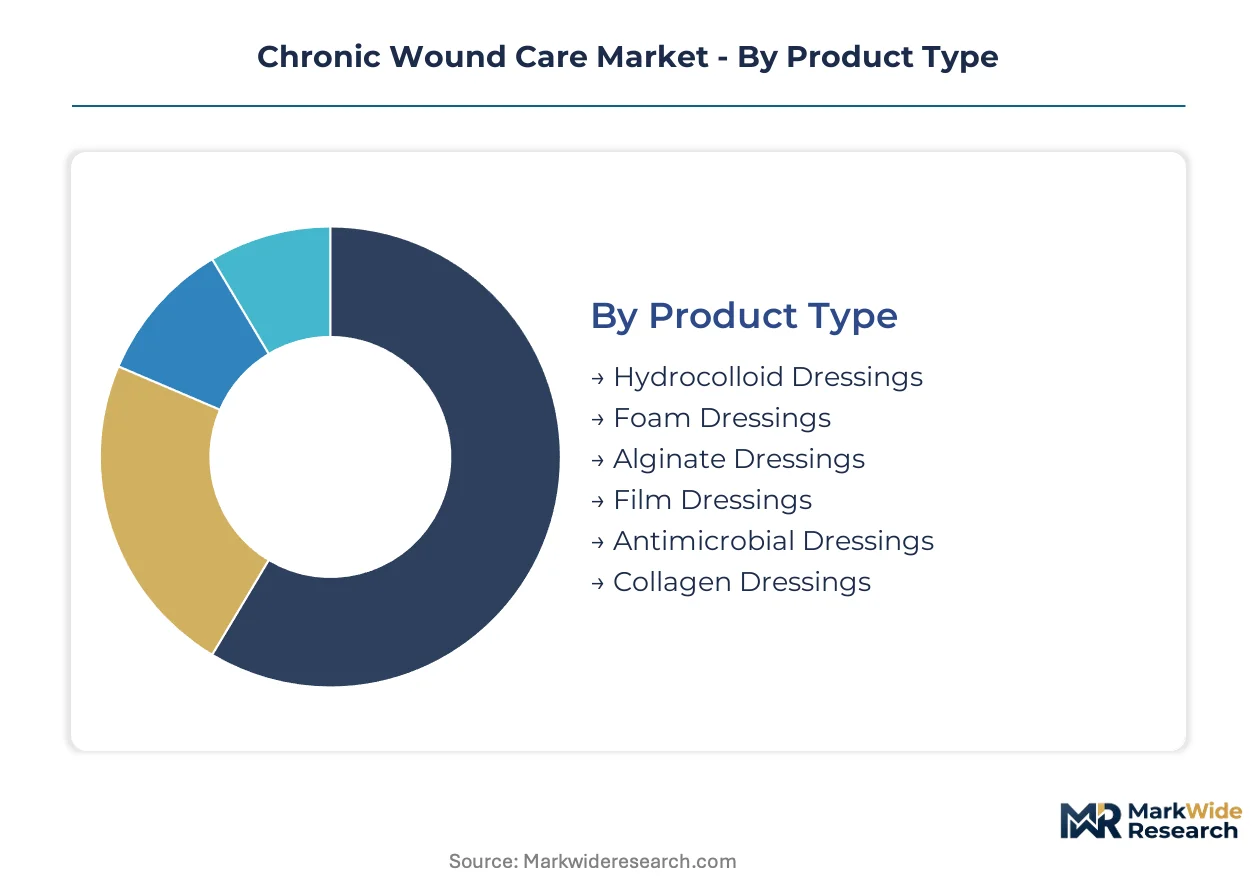
Chronic wound care segmentation reflects divergent clinical workflows across acute, outpatient, and home settings. Product specifications, reimbursement pathways, and care delivery infrastructure determine which configurations capture volume versus margin.
Product Type:
Material composition and moisture management mechanics define therapeutic positioning across dressing categories.
- Hydrocolloid Dressings:Gel-forming carboxymethylcellulose matrices absorb exudate while maintaining autolytic debridement environments. Demand concentrates in post-operative outpatient settings across Germany and the Netherlands where cost-containment protocols favor reusable-capable platforms.
- Antimicrobial Dressings:Silver sulfadiazine, iodine complexes, or polyhexamethylene biguanide-impregnated substrates deliver sustained bacterial load reduction. US acute care networks drive procurement intensity as CMS non-payment policies for hospital-acquired infections harden compliance mandates.
- Foam Dressings:Hydrophilic polyurethane structures manage moderate-to-heavy exudate in pressure ulcer protocols.
- Alginate Dressings:Calcium-sodium fiber derivatives derived from brown seaweed form gel matrices upon contact with wound fluid.
- Film Dressings:Semi-permeable polyurethane membranes enable moisture vapor transmission while blocking liquid and bacterial ingress.
- Collagen Dressings:Bovine or porcine-derived extracellular matrix scaffolds accelerate granulation tissue formation in diabetic foot applications.
Foam dressings lead on scale; antimicrobial variants lead on momentum.
Application:
Wound etiology determines reimbursement tiering and specialist referral intensity.
- Diabetic Ulcers:Neuropathic lesions in weight-bearing plantar surfaces require offloading integration with advanced matrix therapies. Medicare's expanded cellular skin substitute coverage in US outpatient settings is pulling bioengineered platforms into community wound centers.
- Venous Leg Ulcers:Chronic venous insufficiency-derived wounds demand compression therapy coordination with exudate management. Demand clusters in UK and Australian public health systems where standardized care pathways reduce amputation incidence.
- Pressure Ulcers:Facility-acquired lesions trigger penalty frameworks across US skilled nursing networks.
- Surgical Wounds:Incision site management spans closed primary healing to dehisced complex reconstruction.
- Traumatic Wounds:Acute injury-derived defects require hemorrhage control integration with subsequent chronic phase transition.
Diabetic ulcers lead on scale; venous leg ulcers lead on momentum.
End User:
Site-of-care migration is redistributing product form factors and service bundling requirements.
- Hospitals:Inpatient wound services command capital-intensive negative pressure systems and operating room-based cellular graft applications. Procurement committees in US academic medical centers negotiate integrated device-disposable contracts spanning 3-5 year horizons.
- Home Healthcare:Portable negative pressure pumps and simplified dressing kits enable post-acute transition. Medicare's Hospital at Home waiver extensions in the US are creating reimbursement pathways previously restricted to inpatient facilities.
- Wound Care Centers:Specialized outpatient facilities concentrate advanced therapy expertise and outcomes data collection.
- Ambulatory Surgical Centers:Same-day procedural settings manage limited debridement and graft placement volumes.
Hospitals lead on scale; home healthcare leads on momentum.
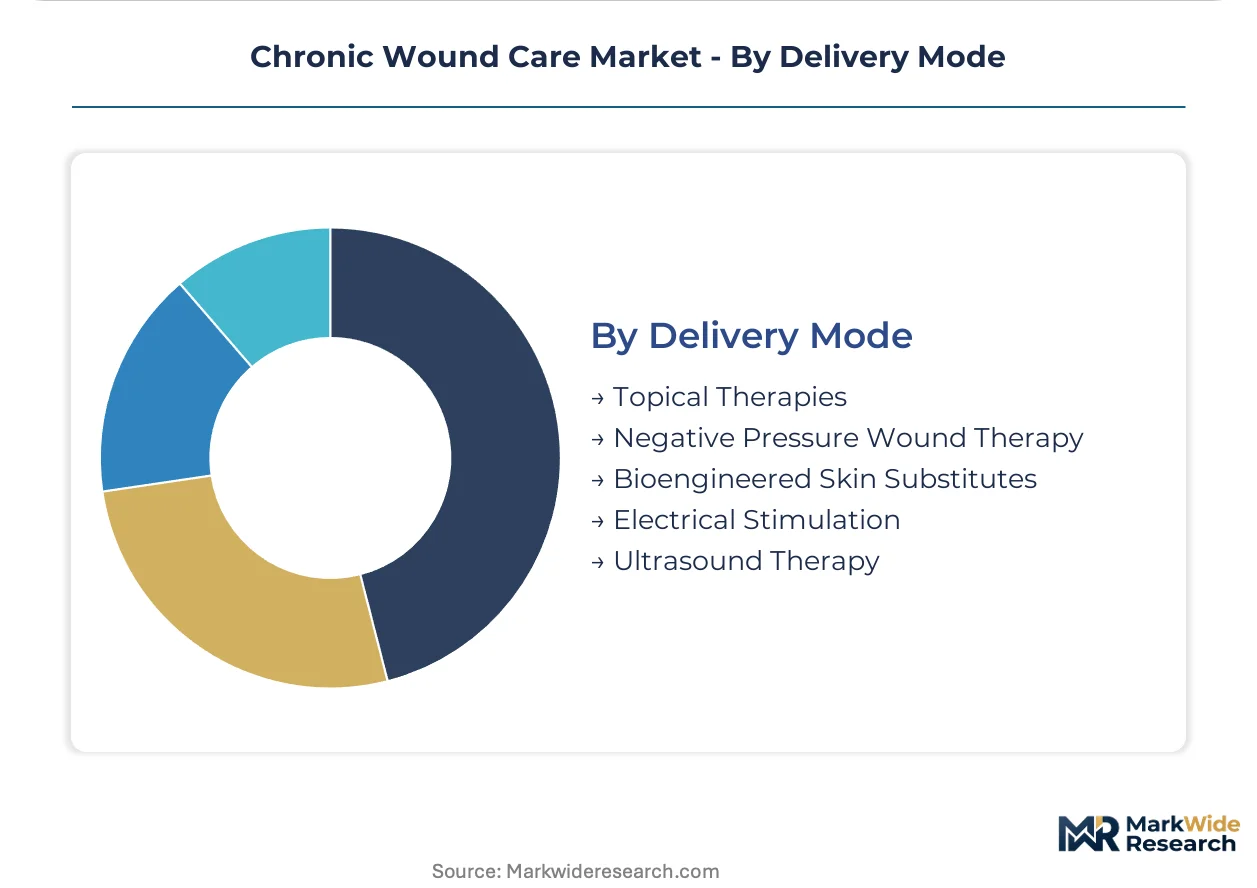
Delivery Mode:
Intervention intensity spans passive substrate placement to active biophysical modulation.
- Negative Pressure Wound Therapy:Subatmospheric pressure application through sealed foam or gauze interfaces accelerates granulation tissue formation. Hospital procurement committees face 18-24 month depreciation schedules for pump capital, delaying replacement cycles.
- Bioengineered Skin Substitutes:Acellular or cellular matrices derived from human, porcine, or bovine sources provide scaffold structures for dermal regeneration. The EU MDR's 2021 recast is forcing reclassification and extended clinical investigation timelines for collagen-based platforms.
- Topical Therapies:Enzymatic, antimicrobial, or growth factor-containing formulations address surface bioburden and protease activity.
- Electrical Stimulation:Microcurrent and pulsed electromagnetic field devices modulate cellular migration and angiogenesis.
- Ultrasound Therapy:Low-frequency acoustic energy applications promote debridement and perfusion enhancement.
Topical therapies lead on scale; bioengineered skin substitutes lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The chronic wound care industry traces its modern commercial roots to post-war surgical dressing manufacturers in the United States and textile-based medical supply producers in Germany, with subsequent scaling driven by diabetes epidemic responses across industrialized healthcare systems.
United States
Medicare's expanded reimbursement for cellular skin substitutes in outpatient settings and CMS non-payment policies for hospital-acquired infections drive procurement intensity. The FDA's 510(k) modernization initiative elevates clinical evidence thresholds for antimicrobial product clearances. Texas and Florida concentrate wound care management organization consolidation, with capitated reimbursement models extracting volume-based price concessions across 50-100 clinic footprints.
Germany
Standardized venous leg ulcer care pathways in public health systems reduce amputation incidence while sustaining demand for compression-coordinated exudate management. The EU Medical Device Regulation's 2021 recast forces reclassification of absorbable hemostats and tissue adhesives from Class IIa to Class III. Hospital wound centers in Germany and the Netherlands pilot electroconductive dressings with printed graphene circuits for real-time bacterial load assessment.
India
The PLI scheme for medical devices attracts contract manufacturers to Gujarat and Karnataka clusters, offering cost advantages for hydrocolloid and foam dressing exports. The Central Drugs Standard Control Organization governs biocompatibility testing and sterilization validation requirements for imported wound products. Tamil Nadu and Maharashtra medical device parks host expanding sterilization and packaging operations serving Middle Eastern and African export markets.
Brazil
Over 60% of medical-grade bovine and porcine collagen derives from Brazilian and Argentinian slaughterhouse networks, exposing supply chains to foot-and-mouth disease quarantines. The national pharmaceutical regulator, ANVISA, conditions market authorization on ISO 10993 biocompatibility documentation. São Paulo state concentrates collagen processing and extracellular matrix scaffold manufacturing for North American and European contract customers.
Japan
Aging demographics sustain pressure ulcer incidence in long-term care facilities, driving demand for moisture-retentive dressing categories. The Ministry of Economy, Trade and Industry and the Pharmaceuticals and Medical Devices Agency coordinate standards for antimicrobial resistance surveillance in wound products. The Kansai region around Osaka anchors domestic manufacturing of alginate and hydrofiber dressings derived from regional seaweed processing supply chains.
Chronic Wound Care Market Key Industry Players
The competitive structure tilts toward diversified medical technology conglomerates with hospital procurement channel dominance. Three to five multinational players capture disproportionate revenue pools in negative pressure wound therapy capital equipment and recurring disposable sales. Strategic archetypes include integrated device-disposable contract negotiators, specialized matrix technology licensors, and regional cost-optimized dressing fabricators. Dominant competitive moves encompass multi-year integrated service contract bundling with remote patient monitoring capabilities, and backward integration into collagen raw material sourcing to secure supply against veterinary quarantine volatility.
Among diversified medical technology conglomerates, Smith & Nephew and Baxter exemplify archetypes anchored in hospital capital equipment and advanced tissue matrix segments respectively. Mölnlycke Health Care occupies a position within the specialized European supply network tier, with silicone adhesive and foam technology concentrations. These three entities represent distinct strategic postures: negative pressure therapy system integration, bioengineered scaffold platform development, and regional manufacturing scale with premium adhesive specialization.
| Leading Market Players |
|---|
| 3M |
| Medtronic |
| Smith & Nephew |
| Integra LifeSciences |
| Baxter |
| ConvaTec Group |
| Coloplast |
| Cardinal Health |
| Mölnlycke Health Care |
| Others |
Cost & Logistics Intelligence
3D bioprinted matrix convergence is collapsing unit economics for patient-specific grafts while redistributing value capture toward decellularized scaffold suppliers in Brazil and the United States. This production-method transition simultaneously elevates raw material premiums and compresses finished-product margins across hydrocolloid and foam dressing tiers.
Pricing Analysis
The bundled-vs-unbundled service split separates integrated device-disposable contracts from transactional dressing sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service intensity. Cost compression in standard foam and hydrocolloid tiers is intensifying because Indian contract manufacturers are capturing 15-20% export cost advantages. Home healthcare channels exhibit highest price sensitivity due to Medicare reimbursement caps, while hospital procurement committees demonstrate lowest sensitivity under capitated risk arrangements.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian and Argentinian slaughterhouse networks supplying over 60% of medical-grade bovine and porcine collagen. Raw material dependencies encompass calcium-sodium alginate fibers from Japanese seaweed processing, hydrophilic polyurethane foams from German chemical clusters, and silver sulfadiazine active ingredients from Indian pharmaceutical intermediates. Foot-and-mouth disease quarantine exposure threatens supply continuity. Distribution runs through wound care management organizations consolidating 50-100 clinic footprints in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: the PLI scheme for medical devices in Gujarat and Karnataka offers 15-20% cost advantages against European manufacturing, while FDA 510(k) modernization compresses clearance timelines relative to EU MDR recast delays.
For Market Incumbents: Extend negative pressure therapy system integration into remote patient monitoring bundles to defend against portable pump entrants capturing Medicare Hospital at Home waivers. Deepen backward integration into Brazilian collagen sourcing to mitigate foot-and-mouth quarantine volatility. Prioritize ISO 10993 biocompatibility testing queue positions to accelerate 510(k) submissions for novel adhesive formulations. For New Entrants and Emerging Players: Launch via direct-to-wound-center distribution targeting community-based diabetic foot ulcer protocols where specialist workforce gaps create adoption bottlenecks for incumbents. Penetrate the bioengineered skin substitute segment in US outpatient settings where Medicare expanded cellular matrix coverage. Exploit EU MDR recast withdrawal of US-origin collagen products to establish compassionate use pathways. For Investors and Strategic Acquirers: Roll-up economics work for specialized matrix technology licensors because the EU MDR's Class III reclassification has stranded mid-size manufacturers lacking European authorized representative infrastructure. Five-to-ten-year viability hinges on reimbursement strategy execution in capitated Medicare Advantage networks. Watch FDA antimicrobial resistance surveillance data as inflection indicator for silver-eluting dressing portfolio reconfiguration requirements.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR recast forces 18-24 month clinical investigation timelines for collagen-based platforms. |
| Hospital System Partnership | Integrated service contracts extract 12-15% price concessions across 50-100 clinic footprints. |
| Software Companion Development | Electroconductive dressings with printed graphene circuits collapse diagnostic-treatment intervals. |
| Reimbursement Strategy | Medicare expanded cellular skin substitute coverage pulls advanced matrices into community settings. |
| Backward Integration | Captive supply of Brazilian collagen mitigates foot-and-mouth disease quarantine exposure. |
Research Approach
Multiple input streams — primary interviews with hospital procurement managers, wound care clinicians, and GPO contracts directors; secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, and EU MDR certification records — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, wound etiology, site-of-care delivery mode, and geographic regulatory cluster generated volume and value outputs over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling incorporating diabetic ulcer incidence curves, antimicrobial dressing procurement intensity, and negative pressure system replacement cycle dynamics.
Several conditions sit outside the modeled scope, including unanticipated WHO antimicrobial resistance surveillance restrictions, veterinary quarantine extensions beyond historical patterns, and Medicare reimbursement tier revisions. Forecasts reflect documented assumptions about FDA 510(k) modernization implementation pacing and EU MDR enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Venous Ulcer Treatment Market
Wound Care
North America Negative Pressure Wound Therapy Market
Wound Care
Wound Skin Care Market
Wound Care
Wound Biologics Market
Wound Care
Interactive Wound Dressing Market
Wound Care
Asia Pacific Wound Care Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Venous Skin Ulcer Treatment Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Liquid Bandages Market
Wound Care
Pressure Ulcer Treatment Market
Wound Care
Asia Pacific Wound Care Biologics Market
Wound Care
Mexico Wound Care Management Devices Market
Wound Care
Global Active Wound Care Market
Wound Care
South Korea Wound Care Market
Wound Care
Gauze Bandage Rolls Market