
 Asia Pacific Advanced Wound Care Market | 2026-2036
Asia Pacific Advanced Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Advanced Wound Care Market Analysis
Hospital-grade antimicrobial certification is redrawing procurement standards across Asia Pacific wound care. Smith & Nephew leverages its negative pressure wound therapy portfolio to anchor premium positioning in Australian and Japanese hospitals. Mölnlycke Health Care AB sustains manufacturing scale advantages through integrated foam dressing production across Southeast Asian facilities. Axio Biosolutions Pvt. Ltd. specializes in hemostatic biologics that differentiate its offering in Indian trauma centers.
Advanced wound care encompasses dressings, devices, and biologics engineered to maintain moist wound environments, manage exudate, and accelerate tissue regeneration through controlled moisture vapor transmission rates typically between 2,000 and 8,000 g/m²/24h. These products serve primarily to reduce healing time for diabetic foot ulcers, pressure injuries, and post-surgical incisions in institutional and home settings. Foam dressings and antimicrobial dressings command the deepest margin pools due to higher ASPs and recurring replacement schedules in hospital settings. Negative pressure wound therapy systems represent the fastest-growing technology segment as clinicians expand use beyond operating rooms into outpatient clinics and home care programs.
Japan's PMDA and Australia's TGA enforce stringent biocompatibility and sterility standards that elevate barriers for non-compliant imports while creating preference for CE-marked and domestically registered products. India's CDSCO medical device rules, aligned with MDR principles, now classify advanced wound dressings as Class B or C devices, requiring clinical evidence submissions that favor established multinationals with regulatory infrastructure. China's NMPA accelerated review pathways for innovative wound biologics are compressing approval timelines. Stakeholders must monitor reimbursement harmonization across ASEAN markets, where fragmented national health insurance schemes currently create patchy access for negative pressure therapy and biologic skin substitutes.
Market Dynamics
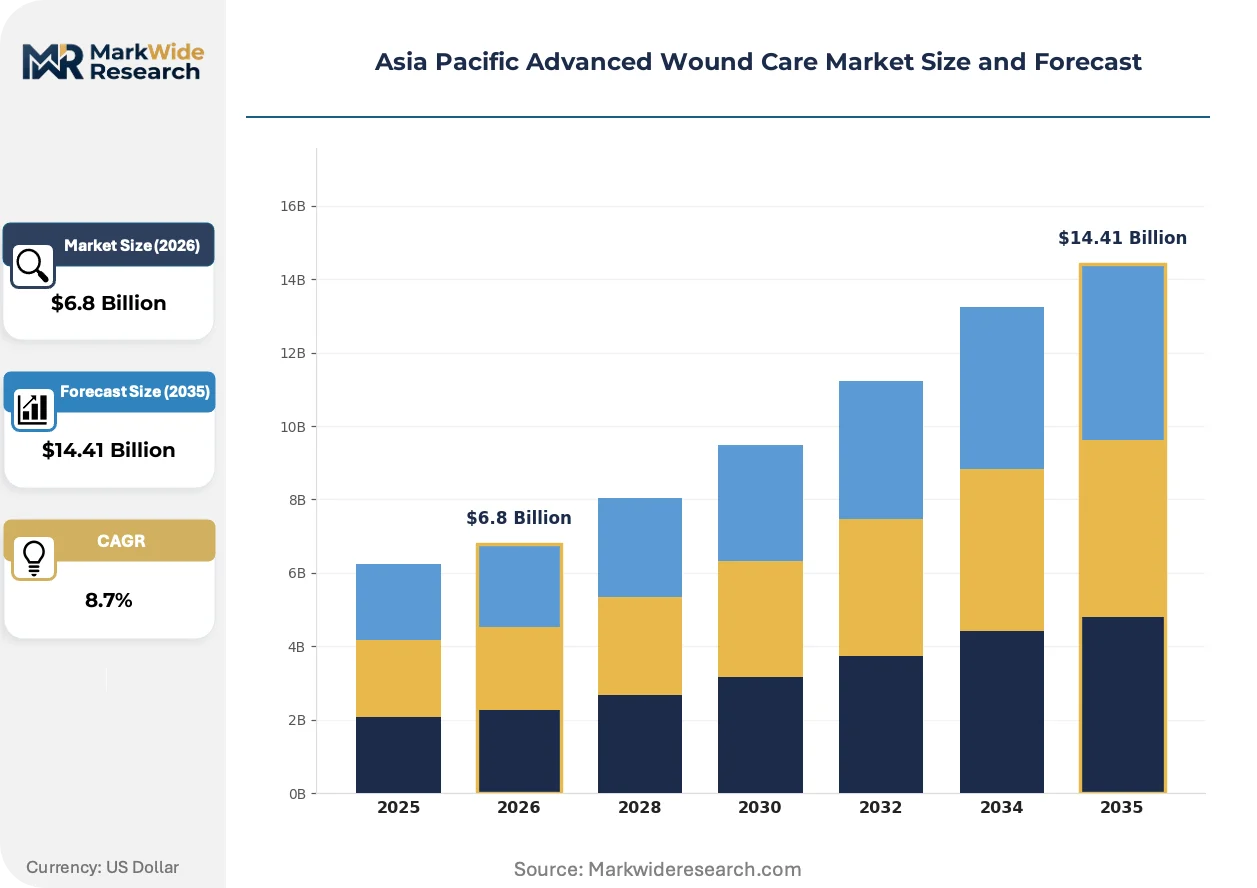
Hospital procurement consolidation across Asia Pacific is compressing vendor margins while elevating antimicrobial certification requirements that only scaled manufacturers can satisfy. Japan's PMDA and Australia's TGA biocompatibility standards now function as de facto trade barriers, filtering out regional challengers lacking clinical evidence infrastructure.
Growth Catalysts
- India's PLI scheme for medical devices:Production-linked incentives are attracting foam dressing manufacturing investments into Gujarat and Tamil Nadu medical device parks, building regional supply capacity.
- Chronic wound prevalence among diabetic patients:China's aging population and metabolic disease burden are sustaining institutional volume for advanced moist wound healing products in tertiary hospitals.
- Negative pressure wound therapy:Portable NPWT systems are expanding from operating theaters into outpatient wound clinics and home care programs across Australian and Japanese healthcare networks.
Market Restraints
- Silver and antimicrobial agent cost volatility:Raw material price swings for ionic silver compounds compress gross margins on hospital-grade dressings during procurement contract periods.
- Supply concentration in Southeast Asian foam production:Malaysia and Thailand host dominant integrated dressing manufacturers, creating single-source vulnerability for regional distributors.
- Biocompatibility testing timelines:Japan's PMDA cytotoxicity and sensitization protocols extend product registration cycles beyond eighteen months for novel wound biologics.
Strategic Opportunities
- Vietnam and Indonesia hospital infrastructure:Greenfield medical cities in Ho Chi Minh City and Jakarta are specifying advanced wound care in equipment tenders with limited incumbent supplier relationships.
- Reimbursement expansion for biologics:Japan's Ministry of Health, Labour and Welfare is adding cellular and tissue-based products to national health insurance fee schedules.
- Telemedicine-integrated wound monitoring:Smartphone-connected moisture sensors and remote image assessment are converging with dressing replacement logistics for rural patient cohorts.
Industry Challenges
- Wound care specialist nurse shortages:Australian and Japanese tertiary centers face recruitment gaps for certified wound ostomy continence nurses capable of biologics application protocols.
- CE-MDR transition documentation burdens:European regulatory alignment requirements are forcing Asian manufacturers to rebuild technical files for legacy dressing portfolios.
- Legacy ERP integration with hospital procurement platforms:Vendor electronic data interchange compatibility with China's centralized hospital purchasing systems requires substantial middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Advanced Wound Care Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid Dressings, Foam Dressings, Alginate Dressings, Antimicrobial Dressings End User: Hospitals, Long-term Care Facilities, Home Care, Outpatient Clinics Application: Surgical Wounds, Chronic Wounds, Burn Care, Traumatic Injuries Technology: Negative Pressure Wound Therapy, Biologics, Hydrogel, Composite Dressings |
| Companies Covered | Healthium Medtech Limited, Mölnlycke Health Care AB, Smith & Nephew, B. Braun Melsungen AG, Medtronic, ConvaTec Group PLC, Coloplast A/S, Axio Biosolutions Pvt. Ltd., 3M, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Advanced Wound Care Market Emerging Trajectories
Digital wound assessment tools and portable therapeutic devices are compressing the boundary between institutional and home-based care delivery across Asia Pacific healthcare systems.
Single-use negative pressure wound therapy pumps are miniaturizing from briefcase-sized units to palm-held disposable devices. Japanese outpatient clinics are adopting these systems for post-surgical incision management, reducing hospital readmission exposure. This form factor shift is miniaturizing capital requirements for clinic-based wound programs and enabling direct-to-patient rental models that bypass traditional durable medical equipment distributors.
China's NMPA accelerated review pathways for innovative wound biologics are compressing approval timelines from thirty-six to eighteen months for products demonstrating superior epithelialization rates. Domestic manufacturers with established Good Manufacturing Practice facilities are leveraging this regulatory tailwind to file first-in-class submissions ahead of multinational competitors. Cellular and tissue-based products targeting diabetic foot ulcers are capturing priority review status under this framework.
Hospital purchasing consortia in Australia are consolidating antimicrobial dressing contracts around outcome-based performance metrics rather than unit pricing. Queensland and New South Wales health departments are piloting total-cost-of-care agreements where dressing suppliers assume partial risk for healing timelines. This contracting evolution is most visible in pressure injury prevention programs where nursing home chains negotiate bundled supply and clinical training packages.
Asia Pacific Advanced Wound Care Market Segmentation
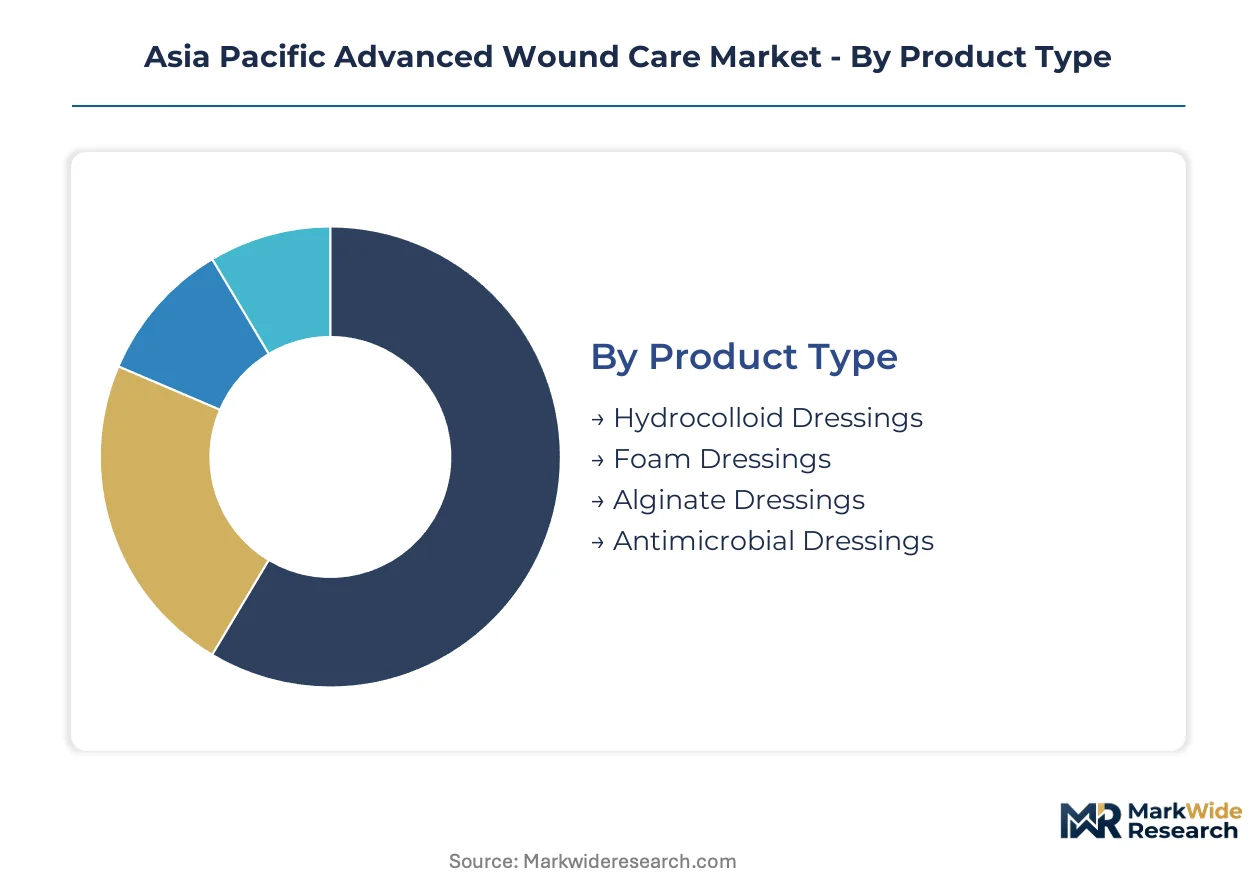
Segmentation in Asia Pacific advanced wound care reveals how reimbursement pathways and clinical protocols concentrate purchasing power across distinct product categories and care settings. Understanding these divisions exposes where substitution pressures and margin compression threaten incumbent positions.
Product Type:
Antimicrobial and foam dressings face intensifying substitution pressure from lower-cost hydrocolloid alternatives in price-sensitive procurement environments.
- Foam Dressings:Polyurethane foam structures absorb moderate-to-heavy exudate while maintaining moist wound interfaces. Australian hospital purchasing consortia specify these for pressure injury protocols in aged care facilities, though silver-impregnated variants command premium positioning.
- Antimicrobial Dressings:Ionic silver, PHMB, or iodine-embedded matrices inhibit bacterial colonization in infected or high-risk wounds. Japan's PMDA biocompatibility standards filter out non-compliant imports, preserving market access for CE-marked and domestically registered suppliers.
- Hydrocolloid Dressings:Gel-forming polymers like carboxymethylcellulose create occlusive environments for low-exudate wounds. India's CDSCO Class B classification requires clinical evidence submissions that favor established multinationals.
- Alginate Dressings:Calcium-sodium alginate fibers derived from brown seaweed form gel matrices upon contact with wound fluid. These serve primarily in Chinese tertiary hospitals for diabetic foot ulcer management.
Foam dressings retain volume leadership; antimicrobial variants hold the steepest expansion curve.
End User:
Cost tier stratification separates institutional purchasers with centralized procurement from fragmented home care payers bearing out-of-pocket burdens.
- Hospitals:Tertiary medical centers in China and Japan drive volume through bundled payment models for surgical site infections. These facilities specify negative pressure systems and biologics in standardized formularies.
- Home Care:Aging-in-place policies across Japan and Australia are shifting dressing replacement logistics toward community nurses and family caregivers. Portable NPWT pumps enable this transition.
- Long-term Care Facilities:Nursing homes in Queensland and New South Wales pilot outcome-based contracts where suppliers assume partial risk for pressure injury healing timelines.
- Outpatient Clinics:Japanese wound centers are adopting single-use NPWT for post-surgical incision management, reducing hospital readmission exposure.
Hospitals dominate absolute spending; home care segments are gaining share fastest as reimbursement shifts toward community-based models.
Application:
Volume concentration in chronic wounds creates supply security requirements that favor manufacturers with regional production footprints.
- Chronic Wounds:Diabetic foot ulcers and venous leg ulcers in China's aging population sustain recurring demand for advanced moist wound healing products. These cases require extended treatment cycles with frequent dressing changes.
- Surgical Wounds:Post-operative incision management in Australian and Japanese hospitals drives adoption of antimicrobial dressings and NPWT systems for high-risk patients.
- Burn Care:Biologic skin substitutes and hydrogel sheets serve thermal and chemical injury cases in specialized burn centers across India and Thailand.
- Traumatic Injuries:Emergency departments in Indian trauma centers utilize hemostatic biologics for acute wound stabilization.
Chronic wounds anchor procurement volume; surgical applications show the most rapid technology uptake.
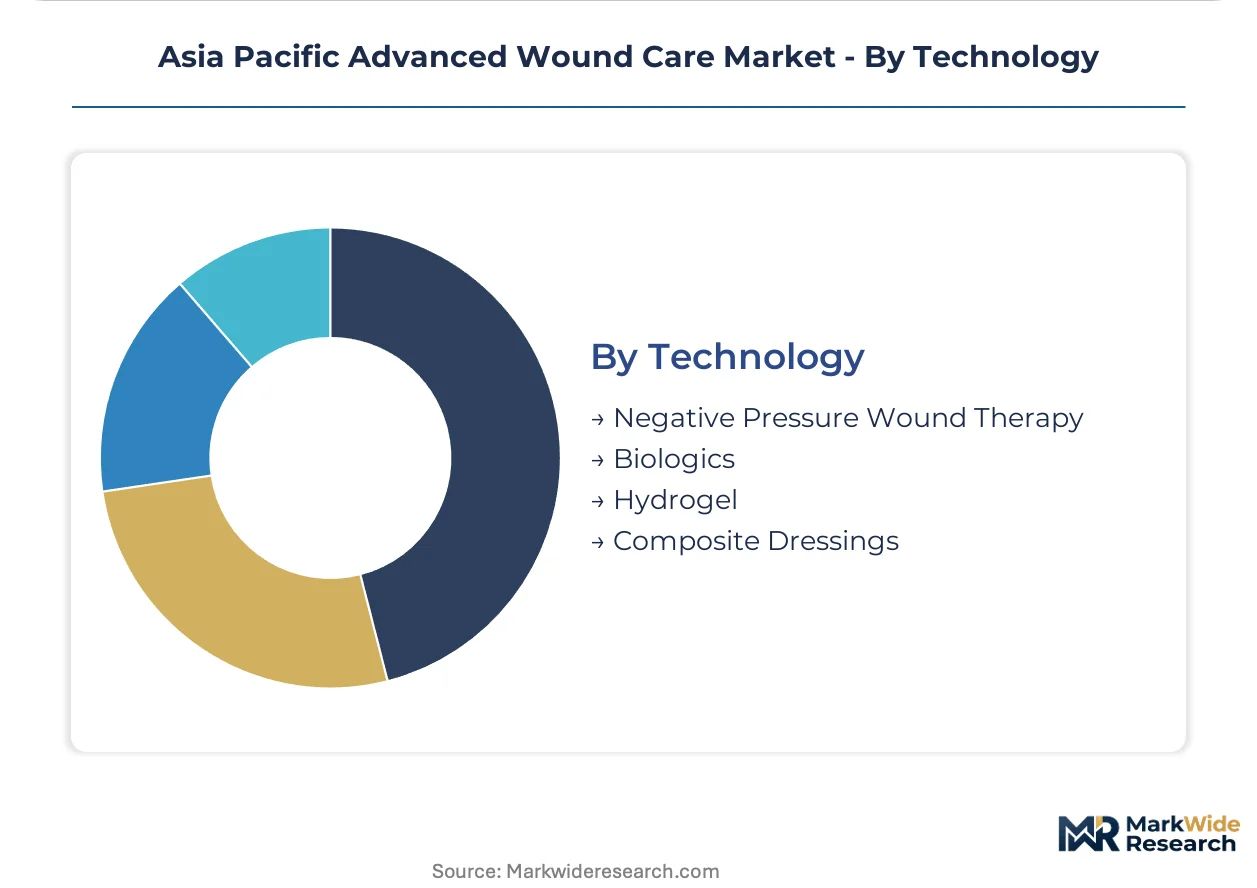
Technology:
Supply concentration in Southeast Asian manufacturing clusters shapes competitive access for device versus biologic technologies.
- Negative Pressure Wound Therapy:Portable and single-use pumps are miniaturizing from briefcase-sized units to palm-held disposables. Japanese outpatient clinics and Australian home care programs are expanding adoption beyond operating theaters.
- Biologics:Cellular and tissue-based products targeting diabetic foot ulcers capture priority review status under China's NMPA accelerated pathways. Japan's Ministry of Health, Labour and Welfare is adding these to national health insurance fee schedules.
- Hydrogel:Cross-linked polymer networks deliver moisture to dry or necrotic wounds. These serve primarily in burn care and chronic wound debridement protocols.
- Composite Dressings:Multi-layer constructions combining absorbent cores with adhesive borders address varied exudate levels in institutional settings.
NPWT systems command the highest revenue per patient; biologics are climbing the fastest as regulatory pathways compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Asia Pacific wound care procurement. Japanese tertiary hospitals absorb premium biologics without volume sacrifice, while Indian state tenders drive aggressive unit-cost compression on standard dressings.
China
Diabetic foot ulcer prevalence among aging urban populations sustains institutional demand for advanced moist wound healing products. NMPA accelerated review pathways compress approval timelines for innovative wound biologics from thirty-six to eighteen months. Yangtze River Delta medical device clusters in Shanghai and Suzhou host domestic manufacturers filing first-in-class cellular therapy submissions ahead of multinational competitors.
Japan
Reimbursement expansion for cellular and tissue-based products under Ministry of Health, Labour and Welfare fee schedules is elevating biologics utilization in tertiary wound centers. PMDA cytotoxicity and sensitization protocols extend registration cycles beyond eighteen months for novel wound biologics, filtering non-compliant imports. Kanto region hospitals in Tokyo and Yokohama specify single-use negative pressure wound therapy systems for post-surgical incision management in outpatient settings.
India
State-level hospital procurement tenders concentrate volume for antimicrobial and foam dressings while squeezing vendor margins through centralized rate contracts. CDSCO medical device rules aligned with MDR principles classify advanced wound dressings as Class B or C devices, requiring clinical evidence submissions. Gujarat and Tamil Nadu medical device parks under PLI scheme incentives are attracting foam dressing manufacturing investments from domestic and multinational producers.
Australia
Hospital purchasing consortia in Queensland and New South Wales are piloting outcome-based contracts where dressing suppliers assume partial risk for pressure injury healing timelines. TGA biocompatibility standards preserve market access for CE-marked and domestically registered suppliers while filtering regional challengers. Aged care facility chains in Sydney and Melbourne metropolitan areas negotiate bundled supply and clinical training packages for pressure injury prevention programs.
South Korea
MFDS regulatory harmonization with international standards is streamlining market entry for advanced wound care devices while maintaining sterility verification requirements. Seoul Capital Area tertiary hospitals drive adoption of portable negative pressure wound therapy systems for surgical site infection protocols. Busan-Ulsan manufacturing corridors host contract producers supplying foam dressing components to regional distributors.
Asia Pacific Advanced Wound Care Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across Asia Pacific wound care. Multinational manufacturers with integrated foam dressing production anchor premium positioning through antimicrobial certification and regulatory infrastructure, while regional specialists compete on trauma biologics and hemostatic applications. Three archetypes dominate: scaled integrated producers with Southeast Asian manufacturing footprints, biologics specialists targeting diabetic foot and burn indications, and portable device innovators miniaturizing negative pressure systems. Competitive moves concentrate on M&A for regulatory infrastructure and capacity expansion into Indian medical device parks.
Among European-integrated multinationals, Mölnlycke Health Care AB and Smith & Nephew occupy positions defined by manufacturing scale and negative pressure therapy portfolios respectively. Axio Biosolutions Pvt. Ltd. represents the regional biologics specialist archetype. These three exemplify how competitive positioning splits between cost-engineered supply scale and clinical evidence-intensive premium segments.
| Leading Market Players |
|---|
| Healthium Medtech Limited |
| Mölnlycke Health Care AB |
| Smith & Nephew |
| B. Braun Melsungen AG |
| Medtronic |
| ConvaTec Group PLC |
| Coloplast A/S |
| Axio Biosolutions Pvt. Ltd. |
| 3M |
| Others |
Supply Flow & Price Mechanics
Integrated foam dressing production across Malaysian and Thai facilities generates scale economies that simultaneously concentrate supply-side power and establish price floors for hospital-grade antimicrobial variants. Japan's PMDA biocompatibility protocols and India's PLI scheme incentives interact with this manufacturing base to stratify procurement tiers across the region.
Pricing Analysis
CDSCO medical device rules aligned with MDR principles dictate the pricing tier structure across Indian institutional procurement. Three-tier pricing structure across premium CE-marked, standard domestically registered, and economy unbranded levels separates multinational suppliers from regional challengers. Price differentiation rests on antimicrobial certification grade and clinical evidence submission depth. Cost compression in economy hydrocolloid segments is intensifying because state tender consolidation squeezes vendor margins. Indian state hospital purchasing committees exhibit highest price sensitivity; Japanese tertiary wound centers absorb premium biologics without volume sacrifice.
Supply Chain Analysis
Port congestion along the Singapore-Klang container corridor elevates inbound logistics costs for ionic silver compounds and polyurethane foam precursors entering Southeast Asian dressing manufacturing hubs. Supply concentrates in Malaysia, Thailand, and Vietnam, with foam component production drawing from Saudi petrochemical feedstocks and German specialty chemical additives. Single-source vulnerability pervades the alginate fiber supply anchored in Chinese seaweed processing facilities. Distribution runs through hospital purchasing consortia in Australia and centralized state tenders in India, bypassing traditional distributor networks for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific advanced wound care market rewards manufacturers possessing integrated regulatory infrastructure and clinical evidence generation capabilities. Scarce PMDA registration expertise and NMPA accelerated pathway navigation skills separate viable competitors from margin-challenged commodity suppliers.
For Market Incumbents: Compound antimicrobial certification advantages by backward integration into foam substrate production at Indian PLI scheme medical device parks. Lock in Queensland and New South Wales outcome-based contracts before regional biologics specialists achieve TGA registration. Defend against portable NPWT device miniaturization threats through exclusive clinic partnership networks in Japanese outpatient wound centers. For New Entrants and Emerging Players: Lead with telemedicine-integrated wound monitoring solutions targeting Australian rural patient cohorts underserved by specialist nurse networks. Vietnam's greenfield medical cities in Ho Chi Minh City present the most penetrable hospital infrastructure segment with limited incumbent supplier relationships. Pursue direct-to-patient rental models for single-use NPWT systems that bypass traditional durable medical equipment distributors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biologics specialists with NMPA priority review status and established GMP facilities over commodity dressing manufacturers facing silver price volatility. Long-term viability hinges on reimbursement expansion trajectory for cellular and tissue-based products across Japanese national health insurance fee schedules. Watch for CDSCO Class C device classification enforcement as inflection indicator accelerating consolidation toward scaled multinationals.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Japan's PMDA recognizes CE-marked biocompatibility data, compressing registration cycles for compliant entrants. |
| Hospital System Partnership | Queensland Health's outcome-based contracting pilots reward suppliers assuming healing timeline risk. |
| Software Companion Development | Smartphone-connected moisture sensors enable remote wound assessment for Japanese aging-in-place policies. |
| Reimbursement Strategy | NMPA accelerated review pathways prioritize diabetic foot ulcer biologics with superior epithelialization rates. |
| Backward Integration | Gujarat medical device parks under PLI scheme attract foam dressing substrate manufacturing investments. |
Methodological Framework
Desk research of hospital procurement databases, GPO contracts, and regulatory filing records preceded structured interviews with wound care clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary fieldwork across Shanghai, Tokyo, Mumbai, Sydney, and Seoul validated secondary findings from NMPA submissions, PMDA approval summaries, CDSCO medical device registrations, and TGA inclusion records. Bottom-up patient volume modeling and top-down healthcare expenditure allocation were triangulated against manufacturer production disclosures.
Variance decomposition across product type, end user, application, and technology segments shaped the analytical framework over the projection horizon. Modeled dimensions encompassed dressing category, institutional versus home care setting, chronic versus acute wound indication, and device versus biologic technology class. CAGRs were derived from segment-level volume projections calibrated to reimbursement policy trajectories and hospital infrastructure investment pipelines across the analysis window. Forecast inputs incorporated diabetic foot ulcer prevalence modeling and antimicrobial dressing replacement frequency assumptions.
Forecasts assume regulatory continuity in Japanese PMDA biocompatibility protocols, Chinese NMPA accelerated review frameworks, and Indian CDSCO MDR-aligned classification schemes; material policy shifts would require re-modeling. Silver compound price volatility, wound care specialist nurse shortages, and ASEAN reimbursement harmonization failures represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Healing Nutrition Market
Wound Care
Europe Wound Care Market
Wound Care
Wound Skin Care Market
Wound Care
US Burn Care Centers Market
Wound Care
Non-Invasive Surgical Wound Closure Market
Wound Care
Alginate Dressing Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Saudi Arabia Wound Care Management Devices Market
Wound Care
Wound Care Market
Wound Care
Smart Bandages and Smart Wound Dressings Market
Wound Care
Maggot Debridement Market
Wound Care
Collagen Dressings Market
Wound Care
United States Negative Pressure Wound Therapy Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
Biopatches Market
Wound Care
Chronic Wound Care Market