
 Global Surgical Drains/Wound Drainage Market | 2026-2036
Global Surgical Drains/Wound Drainage Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Drains/Wound Drainage Market Foresight
Hospital procurement is tilting toward integrated supply contracts that bundle drains with broader wound care portfolios. Cardinal Health leverages its distribution scale to anchor these bundled arrangements across North American health systems. B. Braun Melsungen AG sustains manufacturing depth in Europe through in-house silicone and polymer processing capabilities. Medtronic competes on technology leadership in suction-based active drain systems for post-operative fluid management.
Surgical drains and wound drainage devices are tubular or flat conduits manufactured from medical-grade silicone, PVC, or latex with radiopaque striping and graduated collection bulbs or canisters, designed to evacuate blood, serous fluid, or pus from surgical sites to prevent hematoma formation and promote tissue approximation. Closed drainage systems dominate procedure volume in orthopedic and thoracic applications due to their lower infection risk profile, while negative pressure drains represent the fastest-growing technology segment as vacuum-assisted closure protocols expand beyond chronic wounds into acute post-surgical care. Gravity drainage retains mature status in resource-limited settings where powered suction infrastructure remains scarce.
The FDA's 510(k) clearance framework and the EU Medical Device Regulation (MDR) impose distinct biocompatibility and clinical evidence requirements that fragment product registration strategies across jurisdictions. Japan's PMDA maintains stringent foreign manufacturer inspection protocols that delay market entry for non-domestic producers. Stakeholders must monitor how evolving antimicrobial coating standards and single-use device sustainability mandates reshape material selection and manufacturing location decisions.
Market Dynamics
Closed drainage systems are displacing open drainage in orthopedic and thoracic procedures as infection control protocols tighten, while negative pressure wound therapy extends from chronic care into acute post-surgical settings, compressing traditional gravity drain volumes.
Growth Catalysts
- Ambulatory surgical center expansion:United States, Germany, and Japan are accelerating same-day joint replacement programs that require portable closed drainage systems for outpatient discharge protocols.
- EU MDR antimicrobial coating standards:The regulation's biocompatibility requirements are pulling silver-ion and chlorhexidine-impregnated drain materials into standard-of-care positioning across European hospital procurement.
- Vacuum-assisted closure protocols:Negative pressure technology is migrating from wound care clinics into operating rooms for immediate post-operative fluid management in cardiac and spinal fusion procedures.
Market Restraints
- Medical-grade silicone price volatility:Petrochemical feedstock fluctuations and semiconductor-sector competition for silicone supply are squeezing margins on elastomer-based drain manufacturing.
- Japan PMDA foreign manufacturer inspections:The regulator's stringent on-site audit requirements create 18-24 month entry delays for non-domestic producers seeking market access.
- Gravity drainage substitution ceiling:Resource-limited settings in sub-Saharan Africa and South Asia retain mature gravity systems where powered suction infrastructure remains economically unfeasible.
Strategic Opportunities
- India's PLI scheme for medical devices:The production-linked incentive program offers 5-10% cashback on incremental sales for domestic manufacturing of Class C and D wound drainage products.
- Single-use sustainability mandates:EU Green Deal circular economy requirements are creating first-mover advantage for biodegradable polymer drain materials and closed-loop recycling programs.
- Home-based negative pressure systems:Miniaturized battery-powered suction devices are opening post-discharge revenue streams for surgical drain manufacturers in United States Medicare Advantage networks.
Industry Challenges
- Polymer processing skill scarcity:Medical-grade silicone extrusion and radiopaque striping integration require specialized technicians that command premium wages in Germany and Switzerland manufacturing clusters.
- FDA 510(k) clinical evidence thresholds:The agency's tightened substantial equivalence standards for active suction drains are extending premarket submission preparation timelines and ballooning predicate device search costs.
- Legacy hospital inventory integration:New closed drainage systems must interface with existing wall suction infrastructure and canister disposal workflows, complicating product redesign cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Drains/Wound Drainage Market |
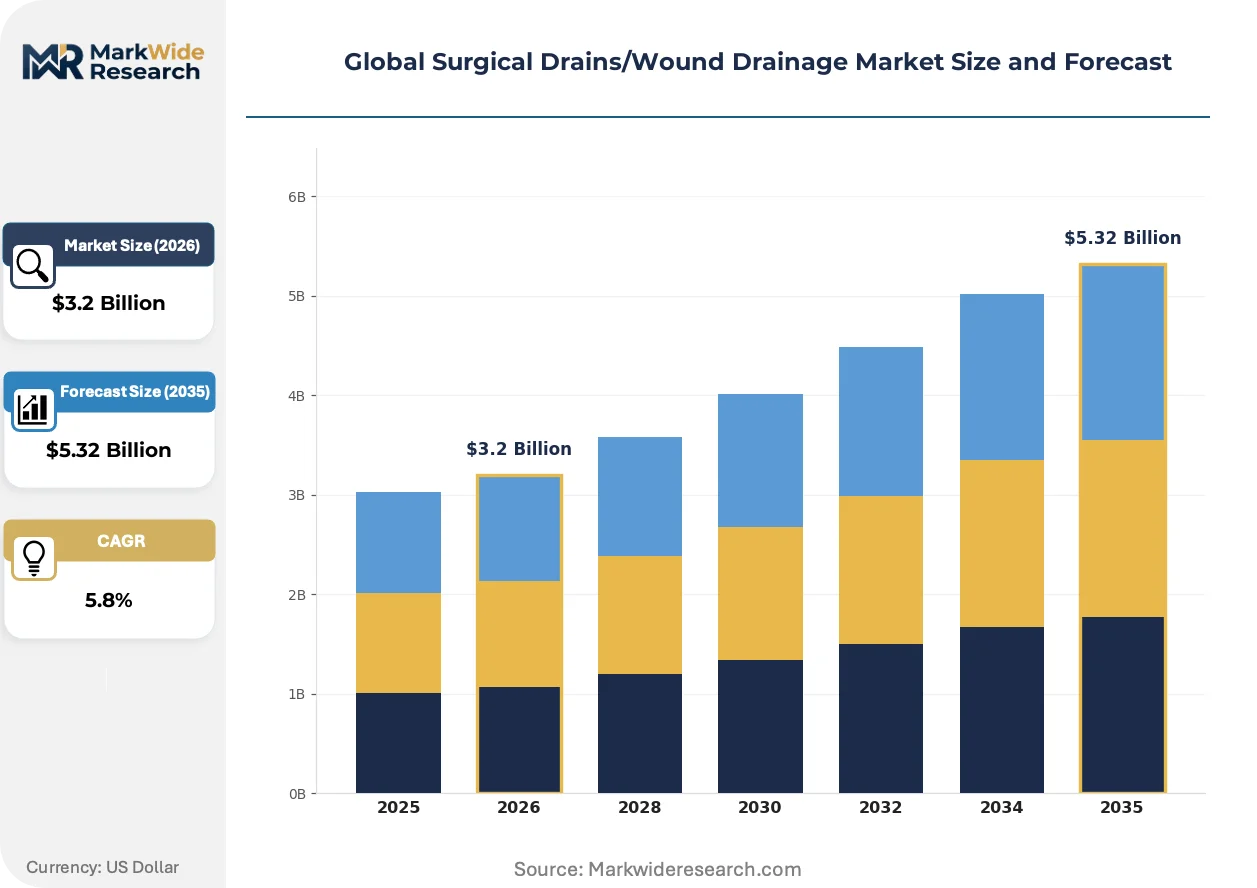
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.32 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Drainage Systems, Open Drainage Systems, Active Drains, Passive Drains, Negative Pressure Drains Application: Orthopedic Surgery, Neurosurgery, Thoracic Surgery, General Surgery, Plastic Surgery, Gynecological Procedures End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Outpatient Facilities, Long-term Care Centers Technology: Suction Drainage, Gravity Drainage, Electroactive Drainage, Capillary Action, Vacuum-assisted Drainage |
| Companies Covered | Cardinal Health, B. Braun Melsungen AG, Cook Medical, Zimmer Biomet, ConvaTec, Medtronic, Johnson & Johnson, Romsons, Teleflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Drains/Wound Drainage Market Shifts & Advancements
Digital fluid monitoring and antimicrobial material science are converging to transform passive drainage into data-generating therapeutic platforms, while regulatory sustainability mandates accelerate material substitution timelines.
Smart drains with integrated flow sensors and wireless transmission capabilities are rendering obsolete manual bulb compression logging and subjective clinical assessment of drainage volume. Orthopedic surgery departments in United States academic medical centers are piloting these systems for remote post-discharge monitoring. The technology is compressing readmission rates and enabling earlier safe removal decisions based on objective trend data rather than calendar-based protocols.
EU MDR's enhanced clinical evidence requirements for Class IIb wound drainage devices are forcing manufacturers to conduct prospective post-market follow-up studies that legacy 510(k) clearances never demanded. The regulation's economic operators and unique device identification mandates are restructuring distributor relationships across European markets. Small-to-mid sized manufacturers are responding by consolidating notified body engagements and centralizing regulatory affairs functions in Ireland and the Netherlands.
Hospital supply chain rationalization is consolidating vendor lists and bundling wound drainage into broader infection prevention portfolios rather than standalone commodity purchasing. Cardinal Health and regional distributors are displacing traditional manufacturer-direct sales relationships with integrated service contracts that span drapes, dressings, and drains. This concentration is most visible in United States IDN consolidation, where ten health systems now control roughly one-third of surgical procedure volume and demand price transparency across entire product categories.
Global Surgical Drains/Wound Drainage Market Segmentation
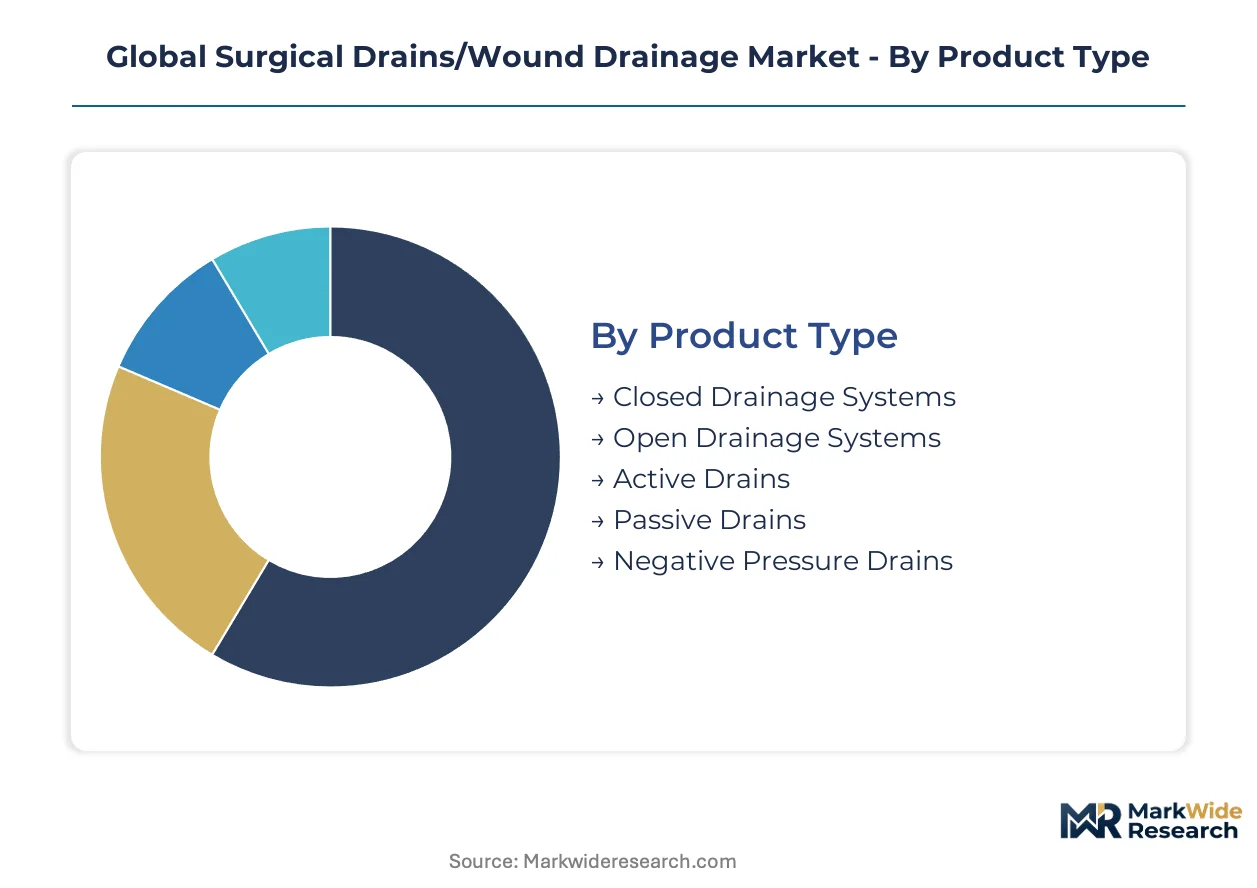
Surgical drain segmentation reflects divergent clinical workflows across acute care, ambulatory settings, and chronic wound management. Product architecture, application site, and suction modality each dictate distinct procurement criteria and reimbursement pathways.
Product Type:
Closed drainage systems dominate infection-sensitive procedures, while negative pressure technology is capturing share in complex wound protocols.
- Closed Drainage Systems:Sealed circuits with collection bulbs or canisters prevent retrograde contamination during orthopedic and thoracic procedures. United States academic medical centers are standardizing these systems for same-day discharge protocols in joint replacement programs.
- Negative Pressure Drains:Vacuum-assisted platforms integrate suction control with fluid measurement for cardiac and spinal fusion cases. Germany's university hospitals are migrating this technology from wound clinics into immediate post-operative settings.
- Open Drainage Systems:Penrose drains and corrugated sheets remain in resource-constrained environments lacking suction infrastructure.
- Active Drains:Suction-powered systems with wall-mounted or portable vacuum sources enable precise pressure modulation.
- Passive Drains:Gravity-dependent conduits without external power serve basic drainage needs in general surgery.
The dominant share belongs to Closed Drainage Systems, while Negative Pressure Drains is closing the gap fastest.
Application:
Procedure-specific fluid characteristics determine drain selection, from high-volume hematoma evacuation to low-output seroma management.
- Orthopedic Surgery:Total joint replacements generate substantial post-operative bleeding requiring high-capacity closed suction systems. Japan's expanding ambulatory surgical center networks are driving portable drain demand for hip and knee procedures.
- Thoracic Surgery:Chest tube placement for pneumothorax and pleural effusion demands large-bore systems with underwater seal chambers. United States cardiothoracic units are adopting digital air leak monitors to accelerate safe removal decisions.
- Neurosurgery:Cranial and spinal procedures utilize small-caliber drains to prevent epidural hematoma without neural compression.
- General Surgery:Abdominal procedures employ varied drain types based on anastomotic risk and expected output volume.
- Plastic Surgery:Aesthetic and reconstructive cases favor thin, flexible drains to minimize scar formation.
- Gynecological Procedures:Hysterectomy and pelvic surgery utilize dependent drainage to reduce lymphocele formation.
Orthopedic Surgery commands the largest procedure volume, though Thoracic Surgery is expanding most quickly as minimally invasive lung resection volumes rise.
End User:
Site-of-care migration is fragmenting procurement authority between centralized hospital supply chains and decentralized outpatient operators.
- Hospitals:Inpatient surgical departments maintain bulk purchasing leverage through integrated delivery networks. United States health systems with ten or more facilities now control roughly one-third of surgical drain procurement volume.
- Ambulatory Surgical Centers:Same-day discharge mandates are creating demand for compact, patient-portable drainage systems. Germany's Kliniklandkarte expansion is accelerating this segment's equipment requirements.
- Specialty Clinics:Orthopedic and wound care focused practices require specialized negative pressure systems for post-operative monitoring.
- Outpatient Facilities:Hospital-affiliated day surgery units balance cost constraints with clinical protocol compliance.
- Long-term Care Centers:Skilled nursing facilities manage chronic wound drainage with simplified gravity-based systems.
Hospitals retain the dominant procurement position, yet Ambulatory Surgical Centers are climbing the fastest as procedure migration accelerates.
Technology:
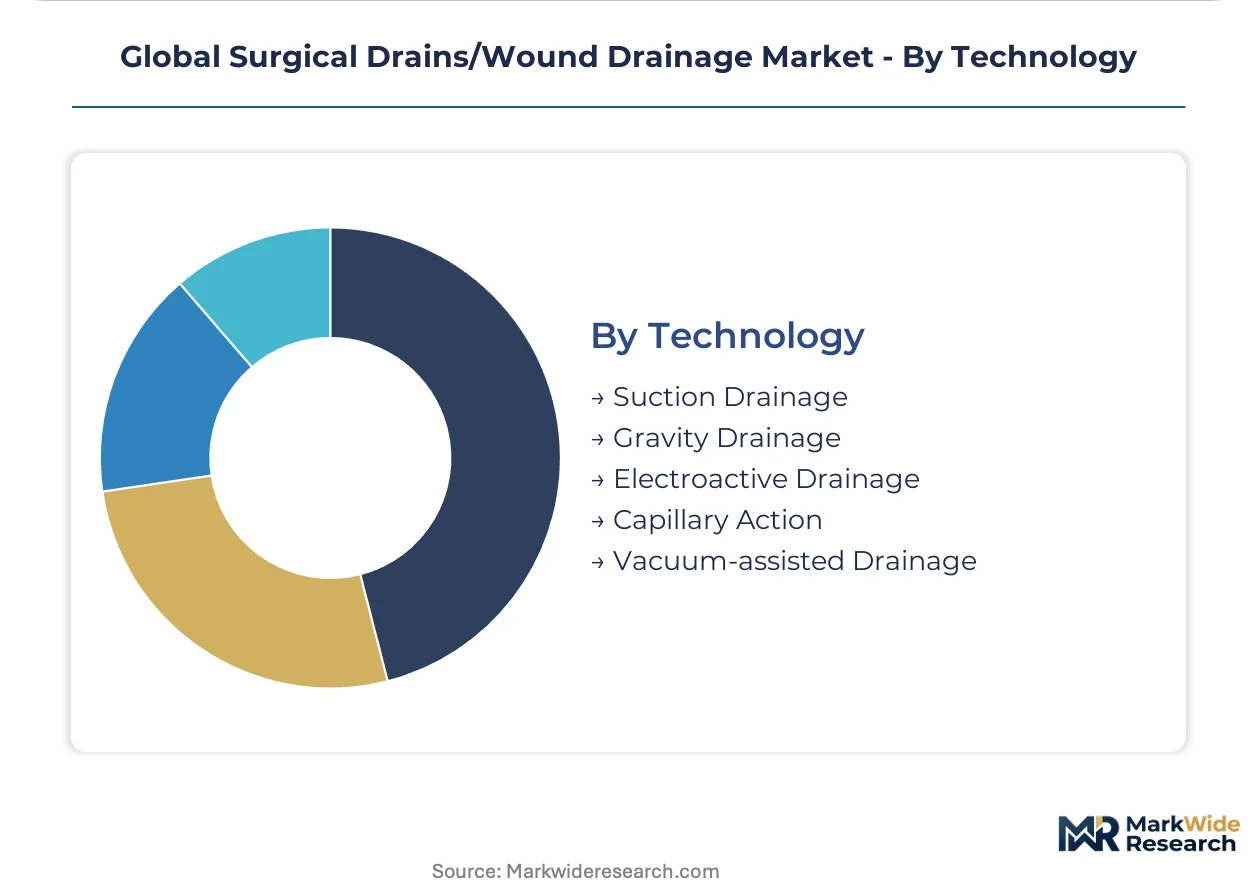
Suction modality selection hinges on infrastructure availability, clinical monitoring capacity, and wound healing objectives.
- Vacuum-assisted Drainage:Controlled negative pressure systems accelerate granulation tissue formation and reduce edema. United States Medicare Advantage networks are reimbursing home-based portable units for post-discharge management.
- Suction Drainage:Active wall-mounted or portable vacuum systems remain standard for high-output surgical sites. Japan's PMDA inspection requirements for foreign manufacturers are constraining supply expansion in this category.
- Gravity Drainage:Passive dependent drainage retains mature status where powered infrastructure is economically unfeasible.
- Electroactive Drainage:Experimental systems utilizing electrical potential gradients remain in preclinical evaluation.
- Capillary Action:Wick-based systems serve specialized applications requiring gentle, continuous fluid transport.
Suction Drainage maintains the installed base leadership, though Vacuum-assisted Drainage is gaining share fastest as wound care protocols migrate into acute surgical settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for medical devices is redirecting manufacturing investment toward domestic Class C and D wound drainage production. Germany's university hospital networks are accelerating negative pressure system adoption for post-operative protocols. Japan's PMDA inspection requirements continue to constrain foreign manufacturer market entry timelines.
United States
Ambulatory surgical center expansion is driving portable closed drainage demand for same-day joint replacement discharge protocols. The FDA's tightened 510(k) substantial equivalence standards are extending premarket preparation timelines for active suction drains. Academic medical centers in Boston and the Research Triangle are piloting smart drain systems with integrated flow sensors for remote monitoring.
Germany
University hospitals are migrating negative pressure technology from wound clinics into immediate post-operative cardiac and spinal fusion settings. The EU MDR's biocompatibility requirements are pulling silver-ion and chlorhexidine-impregnated drain materials into standard procurement positioning. Manufacturing clusters in Baden-Württemberg and North Rhine-Westphalia maintain specialized silicone extrusion capabilities for radiopaque striping integration.
Japan
Expanding ambulatory surgical center networks are creating demand for patient-portable drainage systems in hip and knee procedures. The PMDA's stringent foreign manufacturer inspection protocols impose 18-24 month entry delays for non-domestic producers. Tokyo and Osaka metropolitan hospital systems control the majority of procurement volume through centralized supply chain rationalization.
India
Domestic production of Class C and D wound drainage products qualifies for 5-10% cashback under the PLI scheme's incremental sales structure. CDSCO regulatory harmonization with international standards is streamlining import substitution pathways. Manufacturing investment is concentrating in Gujarat and Karnataka medical device parks with dedicated polymer processing infrastructure.
United Kingdom
NHS supply chain consolidation is bundling wound drainage into broader infection prevention portfolios rather than standalone purchasing. MHRA post-Brexit regulatory autonomy is creating divergence from EU MDR implementation timelines for market entry. London and Southeast England health systems are standardizing closed drainage protocols for orthopedic same-day surgery programs.
Global Surgical Drains/Wound Drainage Market Competitive Landscape
On the supply side, the industry is consolidating around integrated distribution networks and specialized polymer processing capabilities. Tiered competitive positioning separates scale-driven health system contractors from technology-focused active suction specialists and regional manufacturing depth players. Strategic moves center on portfolio bundling into infection prevention contracts and backward integration into medical-grade silicone supply chains.
Within the integrated distribution tier, Cardinal Health anchors bundled supply arrangements across North American health systems. B. Braun Melsungen AG exemplifies European manufacturing depth through captive silicone and polymer processing. Medtronic occupies the technology leadership position in suction-based active drain systems for post-operative fluid management.
| Leading Market Players |
|---|
| Cardinal Health |
| B. Braun Melsungen AG |
| Cook Medical |
| Zimmer Biomet |
| ConvaTec |
| Medtronic |
| Johnson & Johnson |
| Romsons |
| Teleflex |
| Others |
Supply & Pricing Matrix
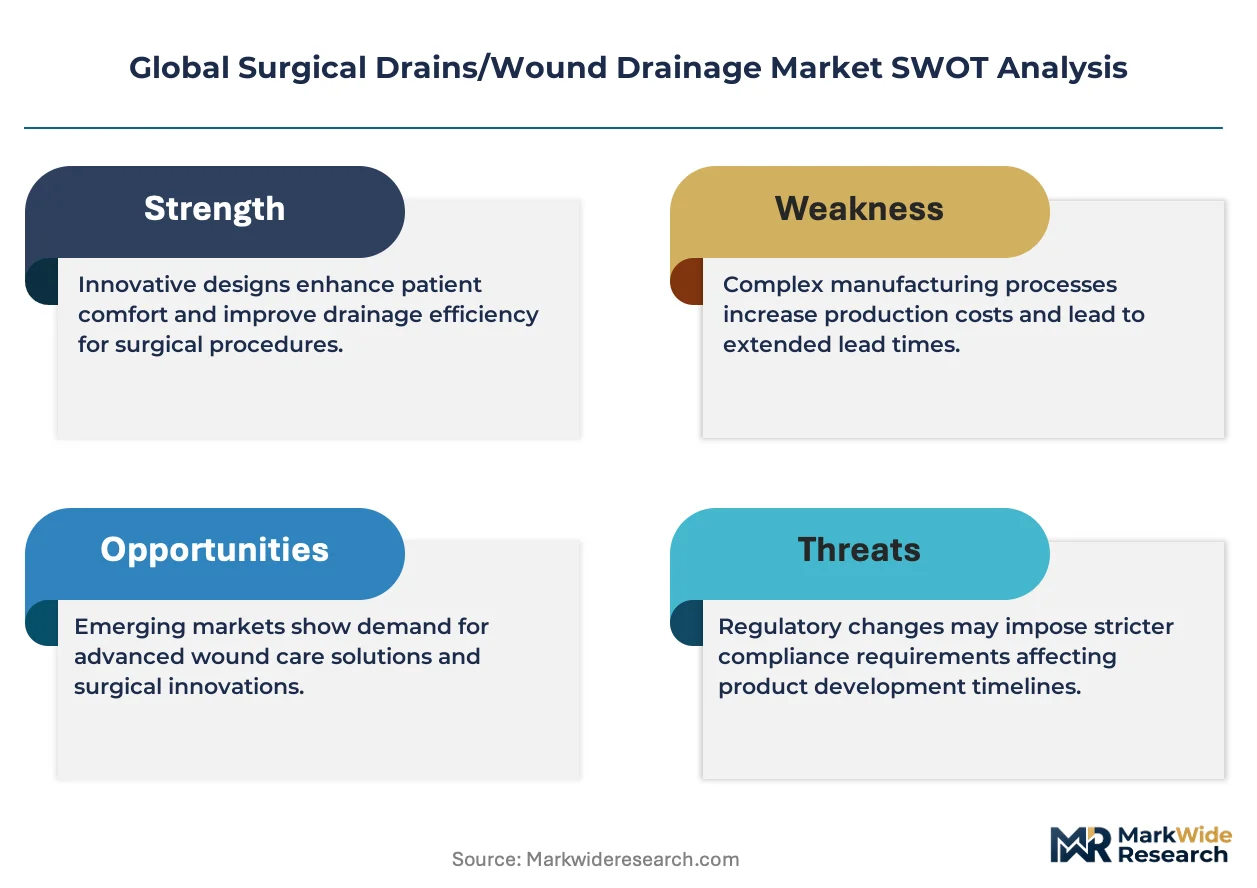
Baden-Württemberg's medical-grade silicone extrusion clusters anchor European supply capacity for radiopaque drain manufacturing, translating polymer processing depth into pricing power for Class IIb device producers serving German university hospital networks. This geographic concentration enables captive margin capture that resists commoditization pressure from Asian contract manufacturers.
Pricing Analysis
Certification level creates the primary spread between ISO 13485/FDA-grade premium drains and basic CE-marked alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects biocompatibility testing depth and antimicrobial coating inclusion. Cost compression in the standard tier is intensifying because Indian PLI-subsidized domestic producers are expanding Class C output. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare Advantage reimbursement constraints, while United States academic medical centers prioritize digital monitoring capabilities over unit cost.
Supply Chain Analysis
Medical-grade silicone feedstock draws from German, Japanese, and United States petrochemical complexes before downstream extrusion. Polymer processing hinges on specialized chlorinated platinum catalyst supply chains concentrated in Switzerland and Belgium. Single-source vulnerability runs through semiconductor-sector competition for high-purity silicone. Distribution runs through Cardinal Health's North American network and B. Braun's European direct-hospital channels, with emerging Indian manufacturers bypassing traditional distributor markups via CDSCO-registered direct tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment protects incumbent positions. The EU MDR's unique device identification mandates and economic operator requirements create structural switching costs that new entrants cannot easily replicate.
For Market Incumbents: Entrench position through backward integration into medical-grade silicone supply chains in Baden-Württemberg or Gujarat medical device parks. Capture ambulatory surgical center procurement via portable closed drainage system bundles that interface with existing wall suction infrastructure. The FDA's tightened 510(k) substantial equivalence standards represent the primary regulatory moat against emerging Asian competitors. For New Entrants and Emerging Players: Pursue India's PLI scheme cashback structure for Class C and D wound drainage manufacturing in Karnataka or Gujarat dedicated polymer processing zones. Target gravity drainage substitution opportunities in sub-Saharan African markets where powered suction infrastructure remains economically unfeasible. Home-based negative pressure systems for United States Medicare Advantage networks offer the most penetrable reimbursement pathway. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with captive silicone extrusion capabilities and established EU MDR notified body relationships. The five-to-ten-year viability window rewards acquisition targets combining antimicrobial material science IP with hospital system GPO contract access. Watch FDA 510(k) clearance velocity for active suction drains as the inflection signal for technology leadership shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Expedited clearance for predicate-established active suction drains accelerates United States market entry timelines. |
| CE Marking Pathway | EU MDR Class IIb clinical evidence requirements force prospective post-market follow-up studies that consolidate notified body relationships. |
| Hospital System Partnership | Integrated delivery network bundling contracts displace standalone commodity purchasing across United States orthopedic departments. |
| Software Companion Development | Smart drain flow sensor integration enables remote post-discharge monitoring and earlier safe removal decisions. |
| Reimbursement Strategy | Medicare Advantage network coding for home-based negative pressure systems unlocks post-discharge revenue streams. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads; and secondary validation through FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up triangulation across product type and application segments reconciled with top-down macroeconomic framing.
Forecast inputs incorporated procedure volume migration from inpatient to ambulatory settings, antimicrobial coating regulatory mandates, and silicone feedstock cost trajectories across the projection horizon. Segmentation modeling spanned product architecture, suction modality, application site, and end-user procurement authority. CAGRs derived from log-linear trend fitting adjusted for regulatory phase-in effects and technology substitution elasticities.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing or semiconductor-sector silicone demand would shift the trajectory. Material shifts in FDA 510(k) substantial equivalence standards or EU MDR antimicrobial coating requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Global Wound Dressings Market
Wound Care
Wound Closure Devices Market
Wound Care
Enzymatic Wound Debridement Market
Wound Care
Wound Care Sealants Market
Wound Care
Gauze Bandage Rolls Market
Wound Care
Asia Pacific Wound Care Biologics Market
Wound Care
Advanced Wound Care Management Market
Wound Care
Moist Wound Dressings Market
Wound Care
Europe Negative Pressure Wound Therapy Market
Wound Care
North America Advanced Wound Care Market
Wound Care
South Korea Wound Care Management Market
Wound Care
Smart Bandages and Smart Wound Dressings Market
Wound Care
North America Wound Care Management Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
Wound Skin Care Market
Wound Care
Brazil Wound Care Management Devices Market