
 Antimicrobial Furniture Market | 2026-2036
Antimicrobial Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Furniture Market Analysis
North American contract furniture manufacturing is restructuring around infection-control specifications as healthcare and corporate buyers rewrite procurement criteria. Steelcase leverages its clinical seating expertise to anchor premium positions in hospital waiting areas and patient rooms. Herman Miller, Inc competes through R&D intensity in copper-embedded textiles and non-porous surface engineering. Godrej & Boyce Mfg dominates South Asian institutional tenders with cost-optimized antimicrobial laminates and metal frames.
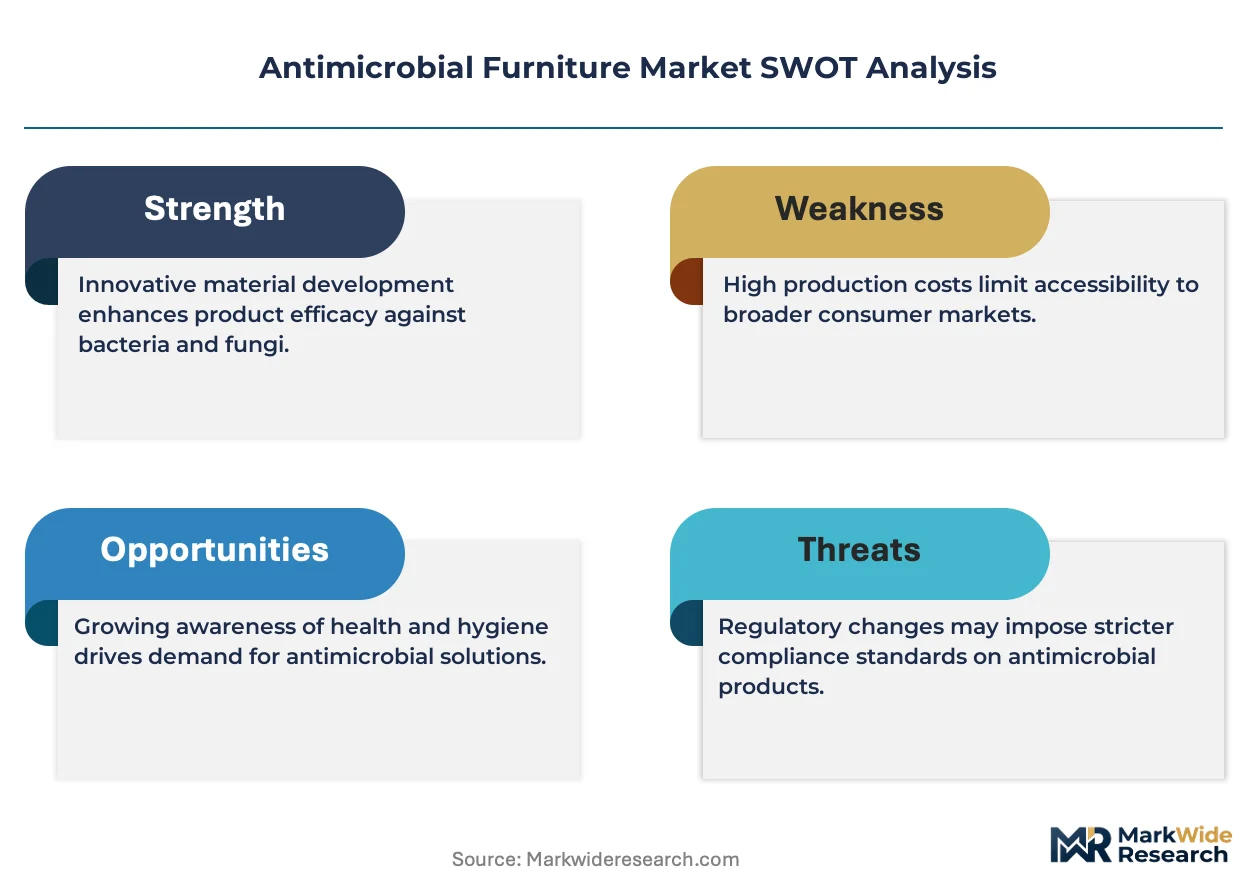
Antimicrobial furniture encompasses seating, surfaces, and storage systems engineered with biocidal additives or inherently resistant materials to suppress microbial colonization on contact points, typically integrating silver ions, copper alloys, or quaternary ammonium compounds into substrates during extrusion or finishing stages. The primary purpose centers on reducing pathogen transmission in high-occupancy environments where frequent disinfection degrades conventional finishes. Plastic and composite materials lead volume shipments due to compatibility with injection-molded antimicrobial masterbatches and lower moisture absorption versus wood alternatives. Healthcare and hospitality end users generate the fastest-growing demand pools, as infection-control audits and guest-safety protocols harden into mandatory specification language across both sectors.
FDA guidelines on medical device surfaces and EPA registrations for antimicrobial claims shape product development pathways and limit unsubstantiated marketing in the United States. REACH restrictions in Europe govern biocidal active substances, forcing reformulation of European-bound product lines to comply with evolving substance authorization lists. Stakeholders must monitor regulatory divergence between EPA-registered claims and EU biocidal product regulation to avoid market-access friction and compliance-driven margin erosion.
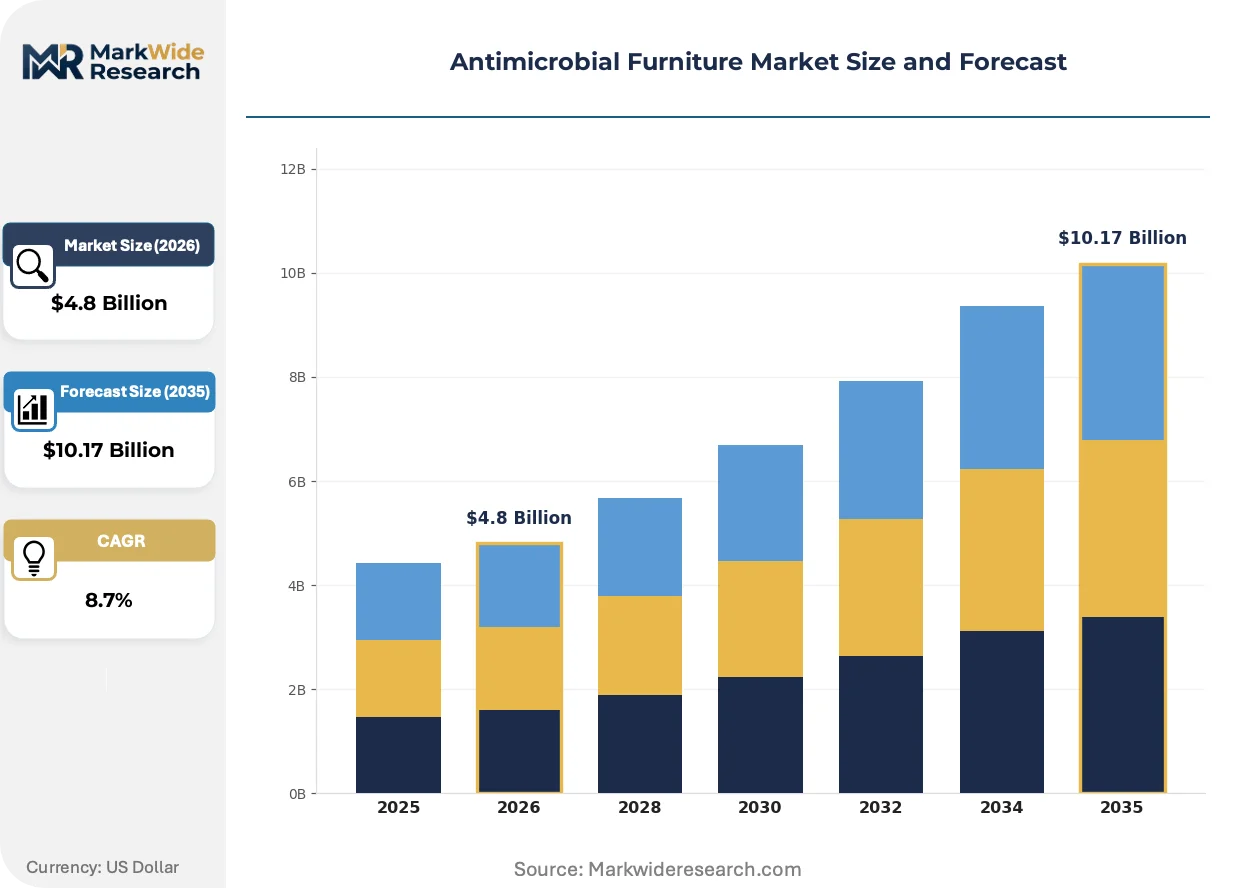
Market Dynamics
Silver-ion and copper-infused coating technologies are restructuring procurement criteria across healthcare and corporate interiors, forcing contract furniture manufacturers to retool finishing lines and reformulate substrate specifications to maintain specification-grade eligibility.
Growth Catalysts
- Joint Commission infection-control standards:US healthcare facilities are mandating antimicrobial surfaces in patient-facing areas, expanding specification-grade furniture volumes.
- Copper alloy integration:Metal furniture producers embed biocidal copper into high-touch components, reducing pathogen viability without chemical disinfectant degradation.
- Germany hospital renovation programs:Federal infrastructure spending on clinical facility modernization drives premium antimicrobial furniture adoption in acute care settings.
Market Restraints
- Silver price volatility:Antimicrobial masterbatch producers face margin compression when precious metal markets spike, forcing pass-through pricing to furniture manufacturers.
- REACH substance authorization delays:European manufacturers must reformulate product lines when biocidal actives face sunset clauses, creating inventory obsolescence risk.
- Quaternary ammonium compound durability limits:Surface treatments leach or degrade under aggressive cleaning protocols, shortening effective product lifecycles in intensive care environments.
Strategic Opportunities
- India institutional procurement:Government hospital expansion and medical college construction create tender opportunities for cost-optimized antimicrobial seating and storage systems.
- Hospitality guest-safety protocols:Hotel chains are rewriting FF&E specifications to include antimicrobial finishes, extending addressable market beyond traditional healthcare.
- EPA-registered claim differentiation:Manufacturers securing validated antimicrobial registrations can command specification premiums in US federal and state procurement channels.
Industry Challenges
- Biocidal efficacy testing bottlenecks:Third-party laboratory capacity constraints delay product launch timelines for manufacturers seeking EPA or BPR compliance.
- Substrate-antimaterial compatibility engineering:Furniture producers must redesign extrusion and finishing processes to prevent additive migration or substrate degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Furniture Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Desks, Sofas Material: Plastic, Wood, Metal, Composite End User: Healthcare, Hospitality, Residential, Educational Application: Public Spaces, Offices, Homes, Laboratories |
| Companies Covered | HNI Corporation, Inter IKEA Group, Ashley Furniture Industries, Kohler Co., The Home Depot, Inc, Godrej & Boyce Mfg, Steelcase, Okamura Corporation, Herman Miller, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Furniture Market Emerging Trajectories
Active coating technologies and substrate engineering are converging to extend antimicrobial durability beyond surface treatments into structural materials, reshaping how furniture is specified, manufactured, and maintained across infection-sensitive environments.
Photocatalytic titanium dioxide coatings are consolidating around healthcare and transportation applications by enabling continuous microbial reduction under ambient light exposure without chemical replenishment. Hospital systems in Germany and the Netherlands specify these finishes for waiting area seating where frequent disinfection damages conventional surfaces. The technology is consolidating mid-market antimicrobial furniture into fewer, more durable product lines that reduce lifecycle replacement frequency.
REACH authorization timelines for biocidal active substances are compressing formulation lead times for European-bound product portfolios. Manufacturers must pre-register substitute actives years ahead of sunset dates to avoid supply discontinuity. Hospital furniture suppliers serving the EU market are accelerating dual-formulation strategies to maintain cross-border shipment flexibility.
Integrated service contracts are replacing transactional FF&E purchasing in US health system procurement, bundling furniture delivery with surface monitoring and recoating services. Group purchasing organizations negotiate multi-year agreements that shift vendor selection criteria from unit price to total cost of ownership. This restructuring concentrates purchasing power among national health networks and marginalizes regional furniture distributors.
Antimicrobial Furniture Market Segmentation
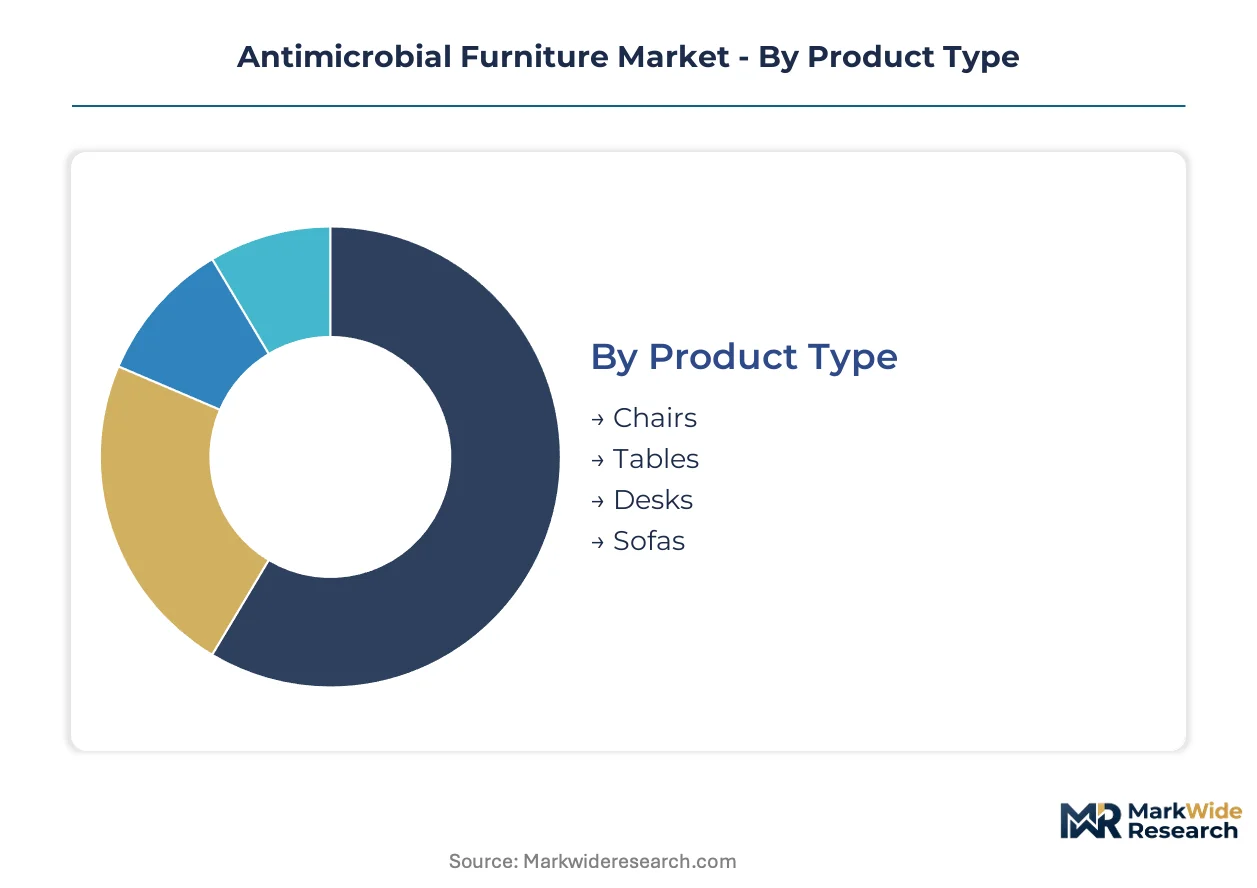
Antimicrobial furniture procurement patterns diverge sharply across product categories, materials, and end-use environments. Specification-grade buyers prioritize infection-control performance over cost, while mass-market segments balance efficacy claims with price sensitivity.
Product Type:
Supply concentration clusters around seating systems where high-touch frequency justifies premium antimicrobial engineering.
- Chairs:Patient seating and waiting area chairs incorporate silver-ion masterbatches into injection-molded shells. US hospital systems specify these for emergency departments where Joint Commission audits scrutinize surface hygiene protocols.
- Tables:Workstation and dining surfaces employ copper-infused laminates or photocatalytic titanium dioxide coatings. German hospital renovation programs specify these for clinical workstations where chemical disinfectant degradation threatens conventional finishes.
- Desks:Administrative and clinical workstations with antimicrobial edge banding and non-porous surfaces.
- Sofas:Lounge seating with copper-embedded textiles for hospitality and residential applications.
Chairs absorb the bulk of installed capacity; tables are expanding most quickly.
Material:
Cost tier stratification separates specification-grade substrates from commodity alternatives in procurement decisions.
- Plastic:Polypropylene and ABS resins compatible with antimicrobial masterbatch integration dominate volume production. Injection molding enables precise additive distribution for healthcare seating in India where government hospital tenders prioritize cost-optimized infection control.
- Metal:Copper alloys and stainless steel with inherent biocidal properties command premium positions. EPA-registered copper alloy surfaces qualify for federal procurement channels without supplemental coating claims.
- Wood:Engineered substrates with quaternary ammonium compound surface treatments for hospitality and residential segments.
- Composite:Fiber-reinforced materials with embedded antimicrobial agents for laboratory and cleanroom applications.
Plastic captures the highest shipment volumes; metal commands the steepest expansion trajectory in specification-grade channels.
End User:
Application maturity varies dramatically across customer types, with regulatory pressure accelerating healthcare adoption.
- Healthcare:Acute care facilities, outpatient clinics, and long-term care operations mandate antimicrobial surfaces in patient-facing areas. REACH authorization timelines for biocidal actives force European suppliers to maintain dual-formulation inventories.
- Hospitality:Hotel chains rewrite FF&E specifications to include antimicrobial finishes as guest-safety protocols harden into brand standards.
- Residential:Consumer demand concentrates in home office and nursery segments with limited regulatory oversight.
- Educational:K-12 and university procurement lags healthcare adoption due to budget constraints and less stringent infection-control mandates.
Healthcare dominates current specification activity; hospitality is gaining share fastest as brand differentiation priorities shift.
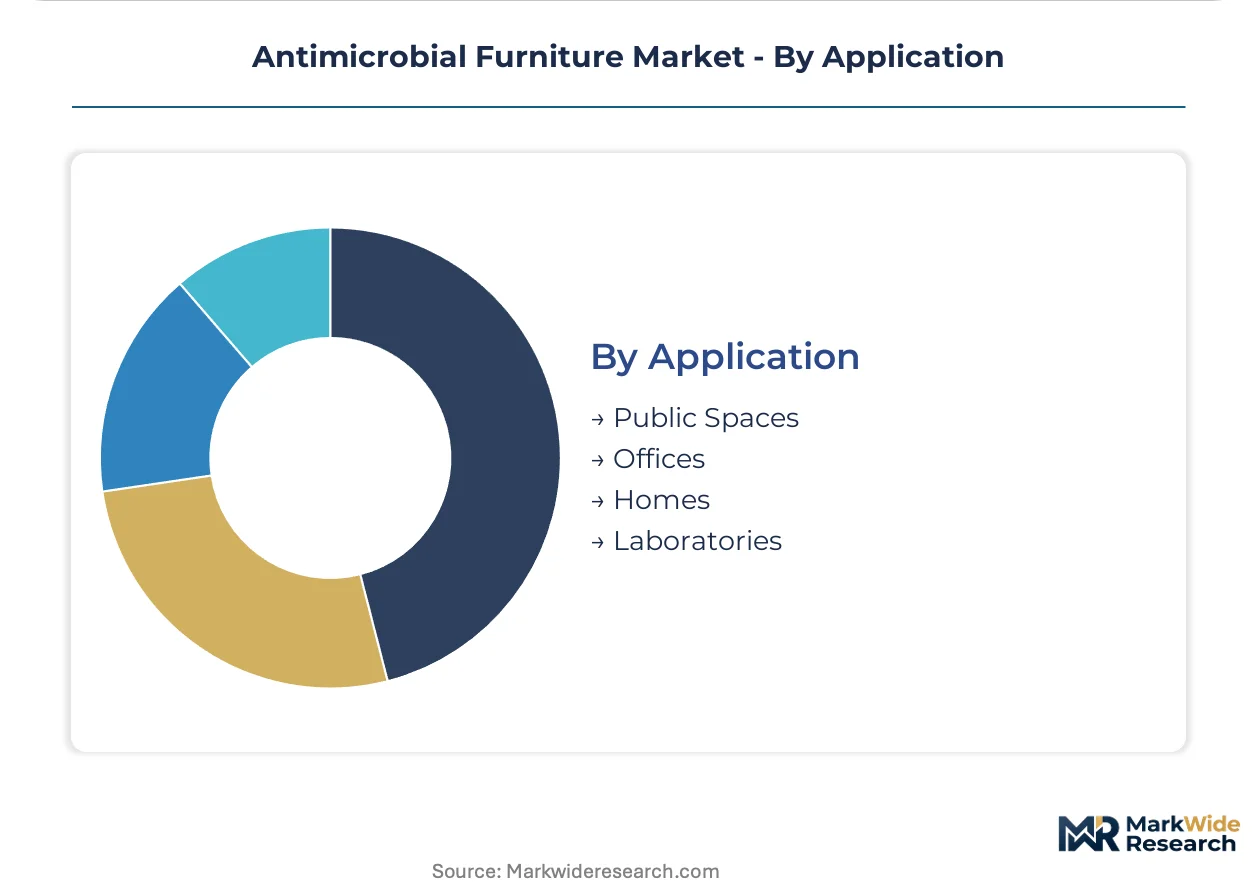
Application:
Volume distribution tracks occupancy density and disinfection frequency requirements across built environments.
- Public Spaces:Airports, transit terminals, and civic buildings specify high-durability antimicrobial seating. Netherlands hospital systems extend these specifications to adjacent public waiting zones.
- Offices:Corporate interiors adopt antimicrobial surfaces as return-to-work protocols emphasize shared-space hygiene.
- Homes:Residential adoption concentrates in kitchen and bathroom furniture with moisture-resistant antimicrobial treatments.
- Laboratories:Research and clinical lab furniture demands EPA-registered surfaces with validated pathogen reduction claims.
Public spaces anchor current procurement volumes; offices are climbing the fastest as hybrid work models stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper mining districts in Chile and Peru supply the antimicrobial metal feedstock that German and US manufacturers convert into specification-grade furniture alloys. Silver extraction from Mexican and Polish deposits feeds masterbatch producers serving injection-molded healthcare seating. These raw material localities anchor three distinct demand centers.
United States
Joint Commission infection-control audits and VA hospital renovation programs drive antimicrobial furniture procurement. EPA registrations for copper-alloy surface claims shape product development timelines. Grand Rapids, Michigan hosts Steelcase and Herman Miller engineering clusters where clinical seating expertise concentrates.
Germany
Federal hospital infrastructure spending and stringent hygiene protocols accelerate specification-grade adoption. REACH authorization timelines for biocidal actives force dual-formulation inventory strategies. North Rhine-Westphalia manufacturing corridors supply copper-infused laminates to Dutch and Belgian hospital systems.
India
Government medical college construction and AIIMS expansion programs generate institutional tender volumes. BIS certification requirements for hospital furniture harden procurement specifications. Maharashtra and Gujarat production hubs dominate cost-optimized antimicrobial laminate and metal frame output.
Japan
Aging care facility construction and METI infection-control guidelines expand antimicrobial seating demand. JIS standards for healthcare furniture surfaces constrain import eligibility. Osaka-Kobe manufacturing clusters specialize in photocatalytic titanium dioxide coating applications for transit and medical waiting areas.
Netherlands
Hospital system consolidation and public-space hygiene mandates extend antimicrobial specifications beyond clinical boundaries. ECHA biocidal product regulation compliance costs filter supplier pools. Randstad urban corridor projects specify high-durability antimicrobial seating for integrated healthcare-transit hubs.
Antimicrobial Furniture Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent hospitality and corporate segments through coating technology licensing. The vendor base stratifies across specification-grade healthcare specialists, mass-market institutional suppliers, and regional fabrication houses serving government tenders. Three archetypes dominate: clinical-engineering incumbents with Joint Commission relationships, cost-optimized laminate producers capturing emerging market share, and coating technology licensors enabling rapid portfolio expansion. Consolidation pressures concentrate purchasing power among health system GPOs while capacity expansion in South Asian fabrication clusters intensifies price competition.
Among US-based contract furniture specialists, Steelcase and Herman Miller occupy positions within the clinical-engineering tier, anchoring premium specification channels through accumulated regulatory expertise and hospital system relationships. Godrej & Boyce Mfg represents the cost-optimized institutional archetype, leveraging South Asian manufacturing scale to capture government tender volumes across India and adjacent emerging markets.
| Leading Market Players |
|---|
| HNI Corporation |
| Inter IKEA Group |
| Ashley Furniture Industries |
| Kohler Co. |
| The Home Depot, Inc |
| Godrej & Boyce Mfg |
| Steelcase |
| Okamura Corporation |
| Herman Miller, Inc |
| Others |
Supply Flow & Price Mechanics
Captive copper-alloy processing in German and US manufacturing clusters anchors specification-grade pricing power by internalizing precious metal conversion costs that otherwise fluctuate with London Metal Exchange volatility. Furniture producers with backward-integrated finishing lines command premium positions in hospital procurement channels where EPA-registered surface claims justify extended payment terms.
Pricing Analysis
Service-bundling separates integrated vendors from transactional suppliers, with multi-year surface monitoring contracts commanding 15-20% premiums over unbundled equipment sales. Pricing stratifies across premium, standard, and economy tiers based on certification grade and antimicrobial durability testing depth. Cost compression in the plastic seating tier intensifies as Indian laminate producers scale government tender volumes. Mass-market institutional buyers exhibit highest price sensitivity, while US health system GPOs prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Domestic-content mandates in Indian government hospital tenders reshape sourcing by requiring BIS-certified local manufacturing for eligibility. Raw material flows concentrate on Chilean and Peruvian copper concentrate, Mexican and Polish silver feedstock, and Saudi petrochemical derivatives for antimicrobial masterbatches. Single-source vulnerability runs through German copper-laminate specialists serving Dutch and Belgian hospital systems. Distribution feeds from fabrication clusters in Maharashtra, Gujarat, and North Rhine-Westphalia through specification-grade dealer networks and health system GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antimicrobial furniture sector is becoming a vertical-integration race, with upstream control over copper-alloy finishing and EPA-registered coating formulation determining margin sustainability.
For Market Incumbents: Deploy captive coating technology to lock in specification-grade eligibility as REACH authorization timelines compress formulation flexibility. Steelcase and Herman Miller should deepen hospital system GPO relationships through integrated service contracts that bundle furniture delivery with surface monitoring. Godrej & Boyce Mfg must defend its Indian tender position by scaling BIS-certified production capacity ahead of federal medical college expansion programs. For New Entrants and Emerging Players: Regional fabrication houses in Southeast Asia represent the most penetrable channel partner type for coating technology licensing arrangements that bypass capital-intensive extrusion investments. White-space targets include hospitality FF&E procurement teams rewriting brand standards around guest-safety protocols, and US corporate interiors specifying antimicrobial surfaces for return-to-work environments. A direct licensing play to mid-tier laminate producers enables rapid portfolio expansion without manufacturing footprint. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to contract furniture conglomerates seeking clinical-engineering capabilities. Long-term viability hinges on regulatory compliance infrastructure that survives REACH substance authorization volatility and EPA registration pathway evolution. The signal to watch is consolidation among health system GPOs concentrating purchasing power and marginalizing regional distributors without national scale.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Registration Pathway Investment | Validates antimicrobial claims for federal procurement eligibility under EPA guidelines. |
| Backward Integration into Copper-Alloy Processing | Captures precious metal margin and insulates against LME price volatility. |
| REACH Dual-Formulation Strategy | Maintains EU market access as ECHA authorization timelines compress. |
| Integrated Service Contract Expansion | Shifts vendor selection criteria from unit price to total cost of ownership. |
| Photocatalytic Coating Licensing | Enables rapid portfolio diversification without capital-intensive manufacturing investment. |
Methodological Framework
Document review covered EPA registration databases, ECHA biocidal product authorization lists, and hospital procurement contract disclosures, complemented by interviews with contract furniture product development executives, health system GPO contracts managers, antimicrobial masterbatch technical directors, and REACH regulatory affairs specialists. Secondary validation drew from FDA medical device surface guidelines, BIS certification records, Joint Commission infection-control audit protocols, and customs trade data for copper-alloy and silver-ion feedstock flows. Bottom-up shipment estimates by product category and material were triangulated against top-down healthcare construction spending allocations.
Market size and growth trajectory outputs reflect demand-side modeling across the projection horizon, with segmentation by product type, material substrate, end-user vertical, and geographic regulatory cluster. CAGRs were derived from installed base replacement cycles, hospital renovation program timelines, and hospitality FF&E specification revision patterns. Industry-specific forecast inputs incorporated REACH substance authorization sunset schedules, EPA registration approval timelines, and federal infrastructure spending commitments for clinical facility modernization.
Caveats apply where REACH authorization delays, silver price volatility spikes, or biocidal efficacy testing bottlenecks could materially shift the outlook for product launch timelines and margin structures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Medical Scrubs Market
Healthcare Products
Automatic Hand Sanitizer Dispenser Market
Healthcare Products
Europe Blood and Blood Components Market
Healthcare Products
Menstrual Sponge Market
Healthcare Products
Global Life Science Products Market
Healthcare Products
Artificial Saliva Market
Healthcare Products
Pressure Ulcer Prevention Market
Healthcare Products
Medical Products Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
Global Healthcare Distribution Market
Healthcare Products
Organ Care Products Market
Healthcare Products
Australia Hair Transplant Market
Healthcare Products
Isolation Gowns Market
Healthcare Products
Birth Tissue Products Market
Healthcare Products
Hospital Privacy Screens Market
Healthcare Products
GCC Healthcare Packaging Market