
 Enzymatic Wound Debridement Market | 2026-2036
Enzymatic Wound Debridement Market Size, Share, and Industry Trends Forecast 2026-2036
Enzymatic Wound Debridement Market Analysis
Software-enabled wound monitoring and subscription-based debridement program management is consolidating the value proposition beyond standalone enzymatic products. Integra LifeSciences leverages its regenerative medicine portfolio to anchor premium positioning in collagenase-based therapies. Smith & Nephew plc competes through advanced wound care ecosystems that integrate enzymatic debridement with negative pressure systems. MediWound Ltd. specializes in proteolytic enzyme platforms derived from botanical and biological sources.
Enzymatic wound debridement employs proteolytic enzymes such as collagenase, papain, and fibrinolysin to selectively break down necrotic tissue while preserving viable wound bed structures, operating optimally at physiological pH ranges between 6.0 and 8.0. Collagenase-based products occupy the dominant revenue position due to their tissue-specific activity profile and established reimbursement codes across major healthcare systems. The home healthcare delivery mode represents the fastest-expanding channel as payors push cost-effective outpatient wound management, while intraoperative applications retain the highest margin pools due to surgical pricing structures.
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape product development timelines and clinical evidence standards for enzymatic debridement agents entering commercial distribution. The Centers for Medicare & Medicaid Services reimbursement determinations directly influence hospital formulary adoption and physician prescribing patterns for chronic wound therapies. Stakeholders must monitor evolving biosimilar enzyme classifications and real-world evidence requirements that will determine competitive moats in the next phase of market development.
Market Dynamics
Hospital formulary committees now prioritize enzymatic debridement agents with bundled digital wound tracking capabilities, compressing procurement decisions around integrated therapeutic ecosystems rather than standalone pharmaceutical products.
Growth Catalysts
- FDA 510(k) Clearance Pathways:Streamlined premarket notification routes for collagenase variants accelerate commercialization timelines for novel formulations targeting diabetic foot ulcers.
- German Outpatient Clinic Integration:Regional reimbursement incentives for chronic wound management drive protocol standardization across ambulatory care networks in Bavaria and North Rhine-Westphalia.
- Collagenase Biosimilar Development:Enzyme engineering advances reduce production costs while maintaining tissue-specific proteolytic activity profiles essential for necrotic tissue removal.
Market Restraints
- Reimbursement Code Fragmentation:CMS billing complexity creates administrative friction for home healthcare providers seeking coverage for enzymatic debridement applications.
- Collagen Supply Concentration:Bovine-derived enzyme feedstock sourcing clusters in specific agricultural processing regions, exposing manufacturers to livestock disease outbreak risks.
- Silver-Based Dressing Substitution:Antimicrobial wound care alternatives with lower per-application costs displace enzymatic protocols in certain venous ulcer treatment pathways.
Strategic Opportunities
- Subscription-Based Wound Management:Recurring revenue models combining enzymatic products with remote monitoring software penetrate Medicare Advantage plans seeking predictable cost structures.
- Pediatric Burn Application Expansion:Off-label protocol development for collagenase use in partial-thickness pediatric burns addresses underserved therapeutic niches.
- EU MDR Harmonization:Centralized conformity assessment procedures reduce regulatory duplication costs for manufacturers seeking pan-European market access.
Industry Challenges
- Wound Care Specialist Training Gaps:Insufficient clinical education programs limit proper enzymatic agent application technique among home health nursing staff.
- Real-World Evidence Collection Infrastructure:Fragmented electronic health record systems impede post-market surveillance data aggregation required for MDR compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enzymatic Wound Debridement Market |
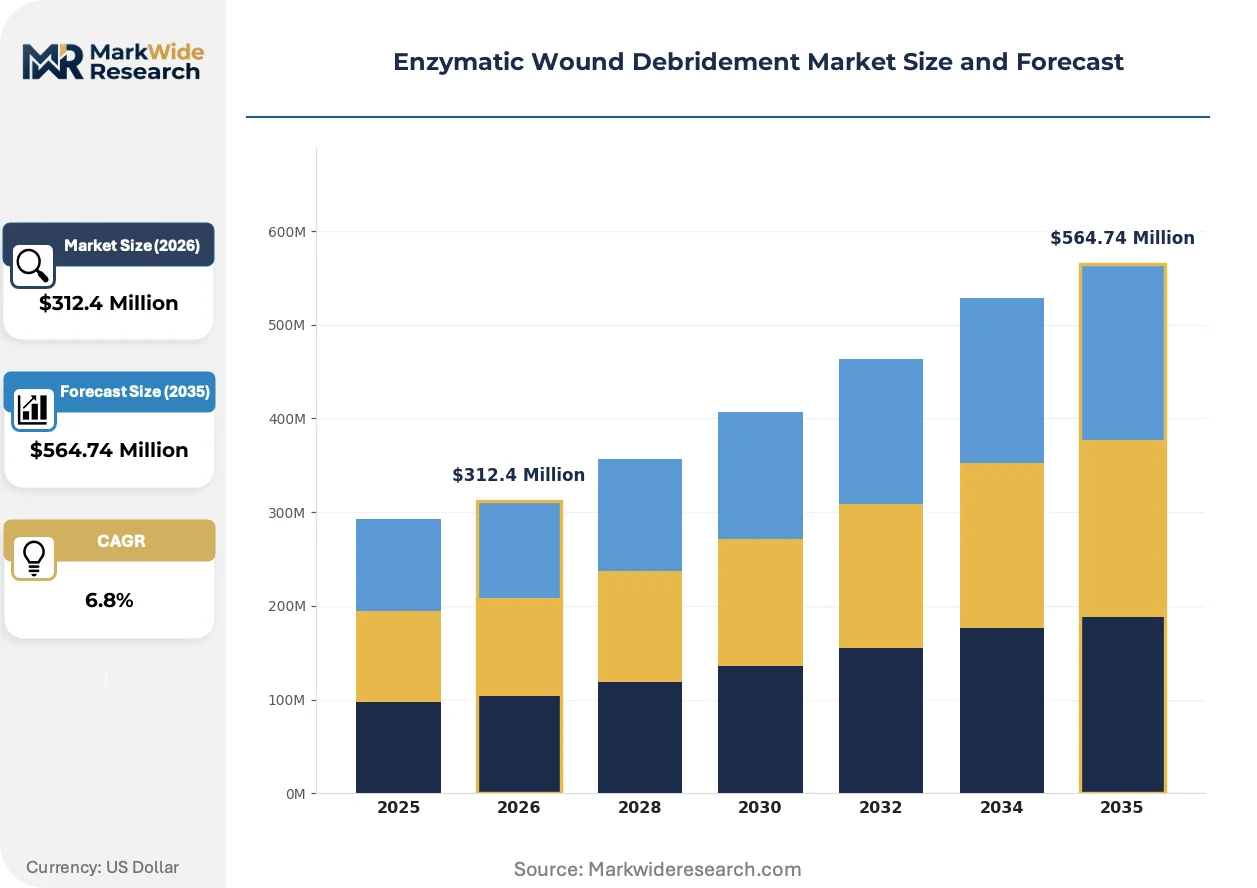
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagenase, Fibrinolysin, Papain, Protease Delivery Mode: Topical, Intraoperative, Intralesional, Combined End User: Hospitals, Outpatient Clinics, Home Healthcare, Long-term Care Facilities Application: Diabetic Ulcers, Pressure Ulcers, Venous Ulcers, Burn Wounds |
| Companies Covered | Integra LifeSciences, Mölnlycke Health Care AB, B. Braun Melsungen AG, SOLASCURE Limited, Medline Industries, Inc., Coloplast Corp, Smith & Nephew plc, MediWound Ltd., ConvaTec Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enzymatic Wound Debridement Market Emerging Trajectories
Enzymatic wound care is converging with digital health infrastructure, creating hybrid therapeutic platforms where pharmaceutical action and data capture operate as unified value propositions rather than separate purchase decisions.
Dual-enzyme formulations combining collagenase with fibrinolysin are modularizing treatment protocols for mixed necrotic wounds. Burn centers and plastic surgery units adopt these combinations at accelerating rates for complex trauma cases. The technology is modularizing what were previously sequential debridement procedures into single-application interventions, compressing operating room time and recovery windows.
EU Medical Device Regulation recast requirements now classify certain high-potency enzymatic agents as Class III devices rather than pharmaceuticals. This reclassification extends clinical evidence timelines and elevates notified body scrutiny for manufacturers. German and French regulators are applying these standards most stringently, forcing portfolio rationalization among mid-tier suppliers.
Hospital purchasing coalitions now negotiate enzymatic debridement contracts through centralized procurement offices rather than individual department requisition. This buyer concentration compresses price points while demanding extended technical support commitments. The shift is most visible in United States integrated delivery networks managing multiple acute care facilities under single administrative structures.
Enzymatic Wound Debridement Market Segmentation
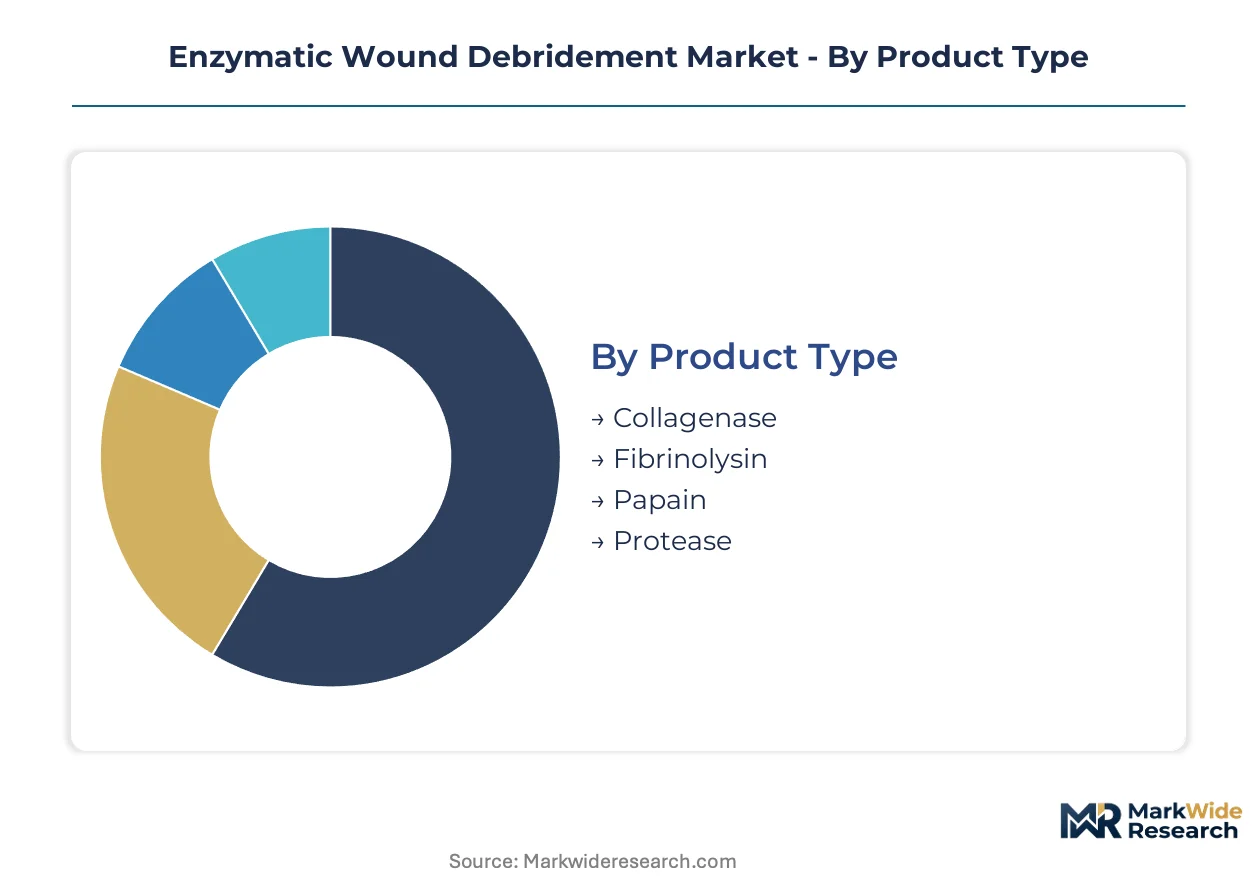
Enzymatic wound debridement markets fragment across enzyme specificity, clinical setting, and wound pathology. Each segmentation axis reveals distinct margin structures and regulatory exposure that shape manufacturer portfolio strategy.
Product Type:
Collagenase commands premium pricing through tissue-selective proteolysis, while papain and fibrinolysin compete on cost efficiency in high-volume protocols.
- Collagenase:Selective degradation of denatured collagen preserves viable wound bed architecture. Hospital formulary committees in the United States prioritize FDA-cleared collagenase variants for diabetic foot ulcer protocols requiring precision tissue removal.
- Fibrinolysin:Dissolution of fibrin-based necrotic tissue complements surgical debridement in burn centers. German outpatient networks integrate fibrinolysin with hydrogel carriers for venous ulcer management under regional reimbursement frameworks.
- Papain:Botanical protease derived from Carica papaya latex offers broad-spectrum necrotic tissue dissolution at lower unit cost.
- Protease:Non-specific enzymatic activity targets proteinaceous slough in mixed wound presentations.
Today's leader: Collagenase. Tomorrow's challenger: Fibrinolysin.
Delivery Mode:
Intraoperative applications sustain the highest per-procedure margins, while topical formulations drive volume expansion through outpatient and home settings.
- Topical:Enzyme-impregnated ointments and gels enable nurse-administered debridement without anesthesia. Home healthcare agencies in Bavaria deploy topical collagenase for chronic wound monitoring under telemedicine protocols.
- Intraoperative:Surgical-grade enzyme preparations applied during operative debridement command institutional pricing tiers. United States burn centers utilize intraoperative fibrinolysin-cocktails to reduce operative time for partial-thickness thermal injuries.
- Intralesional:Direct enzyme injection into wound beds targets deep necrotic pockets inaccessible to surface application.
- Combined:Sequential or simultaneous deployment of multiple delivery modalities addresses complex multi-layer necrosis.
Margin concentration favors intraoperative; volume expansion concentrates in topical delivery.
End User:
Hospital procurement offices centralize enzymatic product selection, compressing vendor diversity while home healthcare channels fragment purchasing across regional agencies.
- Hospitals:Integrated delivery networks negotiate enterprise contracts covering multiple acute care facilities. CMS reimbursement determinations directly influence formulary placement for collagenase products in United States hospital systems.
- Outpatient Clinics:Ambulatory wound care centers in North Rhine-Westphalia standardize enzymatic protocols under German statutory health insurance frameworks. These clinics represent the steepest expansion trajectory as payors shift chronic wound management from inpatient settings.
- Home Healthcare:Nurse-administered topical debridement reduces per-episode costs for Medicare Advantage plans.
- Long-term Care Facilities:Skilled nursing facilities manage pressure ulcer enzymatic protocols for immobile patient populations.
Procurement leverage consolidates around hospitals; growth velocity clusters in outpatient clinics.
Application:
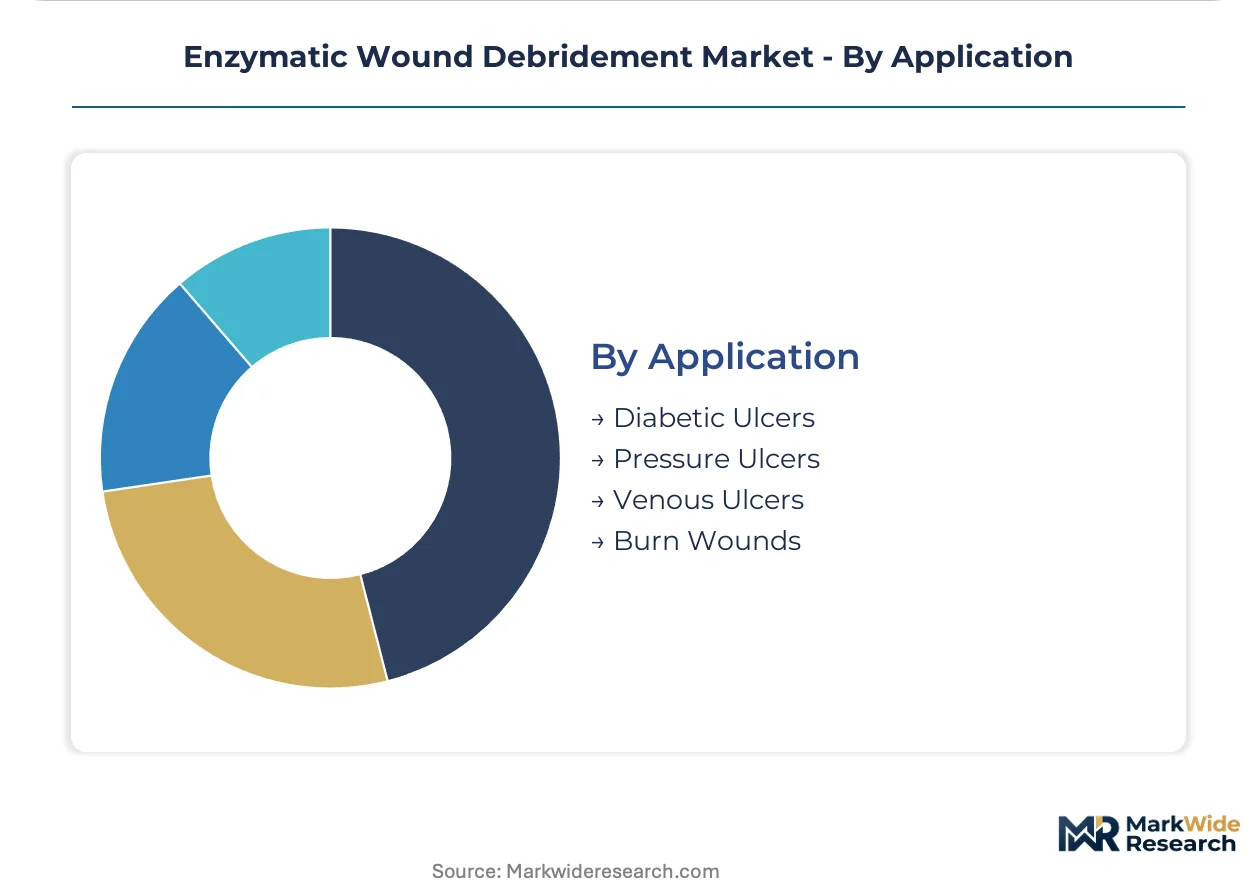
Diabetic ulcers anchor commercial volume due to population prevalence, while burn wounds sustain premium positioning through surgical pricing structures.
- Diabetic Ulcers:Lower extremity wounds in diabetic patients require repeated enzymatic debridement cycles. FDA 510(k) clearance pathways specifically address collagenase efficacy claims for diabetic foot ulcer indications.
- Burn Wounds:Partial-thickness thermal injuries demand rapid necrotic eschar removal to prevent infection. United States burn centers adopt dual-enzyme formulations combining collagenase with fibrinolysin for complex trauma cases.
- Pressure Ulcers:Ischemic tissue necrosis in immobilized patients responds to papain-based debridement in long-term care settings.
- Venous Ulcers:Chronic venous insufficiency wounds in lower extremities utilize enzymatic protocols alongside compression therapy.
Volume foundation: diabetic ulcers. Premium capture: burn wound applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States pursue divergent reimbursement models for chronic wound management, yet both drive enzymatic debridement volume through aging populations and diabetic ulcer prevalence. Hospital formulary centralization in the United States contrasts with German outpatient clinic network expansion. Regulatory pathways in each market reshape commercialization timelines and product positioning strategies.
United States
Medicare Advantage plans accelerate home healthcare adoption of topical enzymatic products to reduce per-episode costs. FDA 510(k) clearance pathways for collagenase variants streamline premarket notification for diabetic foot ulcer indications. Hospital purchasing coalitions in Texas and Florida negotiate enterprise contracts covering multiple acute care facilities under single administrative structures.
Germany
Statutory health insurance frameworks incentivize ambulatory wound care protocols across Bavaria and North Rhine-Westphalia. EU Medical Device Regulation recast requirements classify high-potency enzymatic agents as Class III devices, extending clinical evidence timelines. Outpatient clinic networks in Munich and Düsseldorf standardize collagenase integration into chronic venous ulcer management pathways.
United Kingdom
NHS Integrated Care Systems consolidate procurement decisions for advanced wound care products across regional hospital trusts. NICE technology appraisal processes evaluate enzymatic debridement cost-effectiveness against surgical alternatives. London and Southeast England wound care centers pilot subscription-based debridement program management combining pharmaceutical products with remote monitoring software.
Japan
PMDA regulatory frameworks require local clinical trial data for enzyme-based wound care product approvals, extending market entry timelines. METI healthcare technology assessment programs evaluate enzymatic protocols against traditional debridement methods. Kansai region burn centers adopt dual-enzyme formulations for complex trauma cases requiring rapid necrotic eschar removal.
Australia
TGA conformity assessment procedures for enzymatic medical devices align with EU MDR standards, reducing regulatory duplication for multinational manufacturers. Medicare Benefits Schedule determinations influence physician prescribing patterns for chronic wound therapies. New South Wales and Victoria home healthcare agencies deploy nurse-administered topical debridement under telemedicine monitoring protocols.
Enzymatic Wound Debridement Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital procurement offices concentrating purchasing power around integrated therapeutic ecosystems. The vendor base organizes into three tiers: regenerative medicine portfolio holders, advanced wound care ecosystem integrators, and proteolytic enzyme platform specialists. Consolidation pressures intensify as buyer concentration demands extended technical support commitments alongside product supply. Dominant competitive moves include strategic partnerships with digital health infrastructure providers and geographic expansion through notified body certification stacking.
Among regenerative medicine portfolio holders, Integra LifeSciences anchors premium positioning in collagenase-based therapies. Smith & Nephew plc exemplifies the ecosystem integrator archetype, occupying a position where negative pressure systems and enzymatic protocols converge. MediWound Ltd. represents the proteolytic enzyme specialist tier, with botanical and biological source differentiation. These three companies collectively illustrate the strategic segmentation governing competitive positioning in enzymatic wound debridement.
| Leading Market Players |
|---|
| Integra LifeSciences |
| Mölnlycke Health Care AB |
| B. Braun Melsungen AG |
| SOLASCURE Limited |
| Medline Industries, Inc. |
| Coloplast Corp |
| Smith & Nephew plc |
| MediWound Ltd. |
| ConvaTec Group PLC |
| Others |
Supply Flow & Price Mechanics
EU MDR sustainability and traceability mandates for Class III medical devices gate qualified supply access and premium-tier pricing power, compressing vendor pools to manufacturers with certified bovine collagen sourcing and documented environmental compliance. Hospital purchasing coalitions exploit this qualification bottleneck to extract technical support commitments alongside product supply, while home healthcare channels face pricing pressure from fragmented agency purchasing.
Pricing Analysis
Capacity additions in biosimilar collagenase manufacturing across India and China are reshaping price floors for standard-grade enzymatic products. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared collagenase variants with digital wound tracking integration from basic papain formulations and unbranded alternatives. Price differentiation hinges on certification tier and after-sales clinical training bundling. Cost compression in the economy tier intensifies because silver-based dressing substitution threatens volume retention. Home healthcare agencies exhibit highest price sensitivity; burn centers and integrated delivery networks demonstrate lowest sensitivity due to surgical pricing structures and enterprise contract leverage.
Supply Chain Analysis
Specialized fermentation technician availability constraints in Denmark and the Netherlands limit expansion of pharmaceutical-grade enzyme production facilities. Bovine-derived collagen feedstock concentrates in Argentina, Brazil, and the United States; recombinant enzyme production draws from Chinese contract manufacturing organizations and Indian biotech parks. Raw material dependencies include fetal bovine serum, defined culture media, and sterile hydrogel carriers. Single-source vulnerability in collagen supply chains from livestock disease outbreaks threatens production continuity. Distribution runs through hospital GPOs and specialized wound care distributors in developed markets, with direct-to-clinic models gaining traction in German outpatient networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The enzymatic wound debridement market represents a late-cycle quality story where hospital formulary committees now demand FDA-cleared collagenase with integrated digital wound monitoring, shifting procurement toward premium specifications and compressing commodity-grade margins.
For Market Incumbents: To counter silver-based dressing substitution and biosimilar collagenase entrants, anchor formulary position through backward integration into recombinant enzyme production and exclusive hospital system partnerships with embedded biomedical engineer training programs. Prioritize certification investment for EU MDR Class III device reclassification to extend competitive moats against mid-tier suppliers facing extended clinical evidence timelines. For New Entrants and Emerging Players: FDA 510(k) clearance pathway streamlining for diabetic foot ulcer indications opens a window for botanical protease specialists to penetrate Medicare Advantage home healthcare channels with cost-positioned papain alternatives. Target German outpatient clinic networks in Bavaria and North Rhine-Westphalia where statutory health insurance frameworks incentivize ambulatory wound care standardization. Pursue telemedicine protocol partnerships as primary go-to-market angle to bypass entrenched hospital GPO relationships. For Investors and Strategic Acquirers: Roll-up economics work for proteolytic enzyme platform specialists because hospital purchasing coalition concentration demands extended technical support commitments that scale-efficient mid-caps can deliver more profitably than fragmented single-product vendors. Five-to-ten year viability hinges on digital therapeutic integration capabilities and notified body certification stacking across multiple geographies. Monitor CMS reimbursement determinations for home healthcare enzymatic debridement as primary inflection signal; expanded coverage codes would accelerate channel shift and validate subscription-based wound management platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Streamlined premarket notification accelerates commercialization timelines for novel collagenase formulations targeting diabetic foot ulcers. |
| EU MDR Class III Certification | Centralized conformity assessment procedures extend clinical evidence requirements and elevate notified body scrutiny for high-potency enzymatic agents. |
| Hospital System Partnership | Integrated delivery network enterprise contracts compress vendor diversity while demanding embedded biomedical engineer training and technical support. |
| Software Companion Development | Digital wound tracking integration transforms standalone pharmaceutical products into subscription-based therapeutic ecosystems with recurring revenue. |
| Reimbursement Strategy | CMS coverage determinations and German statutory health insurance framework alignment directly influence formulary placement and prescribing patterns. |
Methodological Framework
Multiple input streams — formulary committee interviews, GPO contract database analysis, and regulatory filing review — were reconciled through bottom-up and top-down triangulation. Primary discussions with hospital procurement managers, wound care clinicians, biomedical engineers, and payer access specialists informed demand-side dynamics. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and German statutory health insurance framework records. Supply-side assessment incorporated fermentation facility capacity reports and bovine collagen sourcing trade data.
Data-stream reconciliation across enzyme specificity, delivery mode, end user, and wound pathology dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and pricing tier evolution. Modeled inputs included diabetic ulcer prevalence projections, burn center admission patterns, and Medicare Advantage plan expansion rates. Regional clusters reflected divergent reimbursement models and regulatory pathway timelines without specific year attribution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under livestock disease outbreak scenarios or abrupt CMS reimbursement code revision. Forecasts reflect documented assumptions regarding FDA clearance pathway stability and EU MDR implementation consistency. Material deviation in bovine collagen supply chain integrity or digital therapeutic integration adoption rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Dental Wound Dressings Market
Wound Care
Vascular Dressings Market
Wound Care
Australia Wound Care Management Devices Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Venous Skin Ulcer Treatment Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Wound Closure Strips Market
Wound Care
Wound Healing Nutrition Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Wound Care Sealants Market
Wound Care
Acute Wound Care Market
Wound Care
Single-Use Negative Pressure Wound Therapy Devices Market
Wound Care
Wound Management Market
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
Patch Based Wound Healing Products Market
Wound Care
South Korea Wound Care Management Market